
 Augmented and Virtual Reality in Education Market | 2026-2036
Augmented and Virtual Reality in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Augmented and Virtual Reality in Education Market Analysis
The capital-intensity divergence between full-stack platform developers and content-only specialists is unwinding competitive dynamics across the sector. Meta Platforms, Inc. leverages its Reality Labs hardware ecosystem to anchor institutional VR deployments in North American higher education. Microsoft Corporation competes through Azure cloud integration that sustains hybrid AR delivery for K-12 districts already embedded in Office 365 environments. zSpace, Inc. specializes in stereoscopic display systems that dominate vocational and technical training centers requiring precision spatial manipulation.
Augmented and Virtual Reality in Education comprises immersive hardware and software systems that render three-dimensional digital content overlaid upon or substituting physical environments, typically operating at 90 frames per second with sub-20 millisecond motion-to-photon latency to prevent user disorientation. These systems enable experiential learning in anatomy, physics, and hazardous procedure simulation where physical replication proves cost-prohibitive or dangerous. Software Solutions currently capture the majority of margin pools as recurring licensing models displace one-time hardware transactions. Within the Application dimension, STEM Education leads absolute spending while Professional Training registers the fastest trajectory as enterprise reskilling programs replace traditional classroom instruction.
The U.S. Department of Education coordinates with FCC E-Rate funding mechanisms that subsidize broadband infrastructure prerequisite to district-level AR/VR adoption, while EU member states implement GDPR compliance frameworks that constrain biometric data collection from student headset users. China's Ministry of Education issues GB standards for classroom electronic equipment that dictate display brightness, blue-light emission thresholds, and electromagnetic compatibility testing protocols. Stakeholders must monitor how divergent data-localization requirements across these jurisdictions reshape content delivery architectures and vendor certification burdens.
Market Dynamics
The divergence between full-stack platform providers and content-only specialists is compressing margin pools across the sector. Hardware commoditization pressures are forcing vendors to anchor recurring revenue through software licensing models that lock institutional buyers into multi-year contracts.
Growth Catalysts
- ESSER-funded infrastructure:The U.S. Department of Education's Elementary and Secondary School Emergency Relief allocations are accelerating district-level hardware procurement cycles for immersive classroom technology.
- Aviation simulation mandates:Federal Aviation Administration training requirements for pilot certification are expanding corporate VR training budgets for procedural rehearsal in risk-free environments.
- Smart classroom directives:Provincial education bureaus in China are mandating stereoscopic display installations in tier-two city secondary schools.
Market Restraints
- GDPR biometric constraints:The European Union's General Data Protection Regulation imposes strict consent frameworks on student headset data collection, limiting deployment scale in K-12 environments.
- Display panel concentration:OLED microdisplay manufacturing concentrates in East Asian foundries, creating supply vulnerability for headset vendors outside the region.
- Motion-to-photon latency thresholds:Sub-20 millisecond response requirements demand specialized GPU architectures that inflate hardware costs beyond mass-market accessibility.
Strategic Opportunities
- Vocational reskilling pipelines:Germany's Federal Institute for Vocational Education is piloting AR-guided apprenticeship programs for precision manufacturing trades.
- 5G edge streaming architectures:Cloud-rendered immersive content delivered over low-latency cellular networks is eliminating tethered PC dependencies for mobile classroom deployments.
- Healthcare procedure libraries:Surgical training centers in India are licensing anatomical simulation content for residency programs previously limited to cadaver-based instruction.
Industry Challenges
- Instructional design talent scarcity:Educational technology departments lack personnel trained in spatial pedagogy and three-dimensional curriculum development.
- Interoperability certification delays:Fragmented headset operating systems require content developers to maintain parallel codebases, extending product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Augmented and Virtual Reality in Education Market |
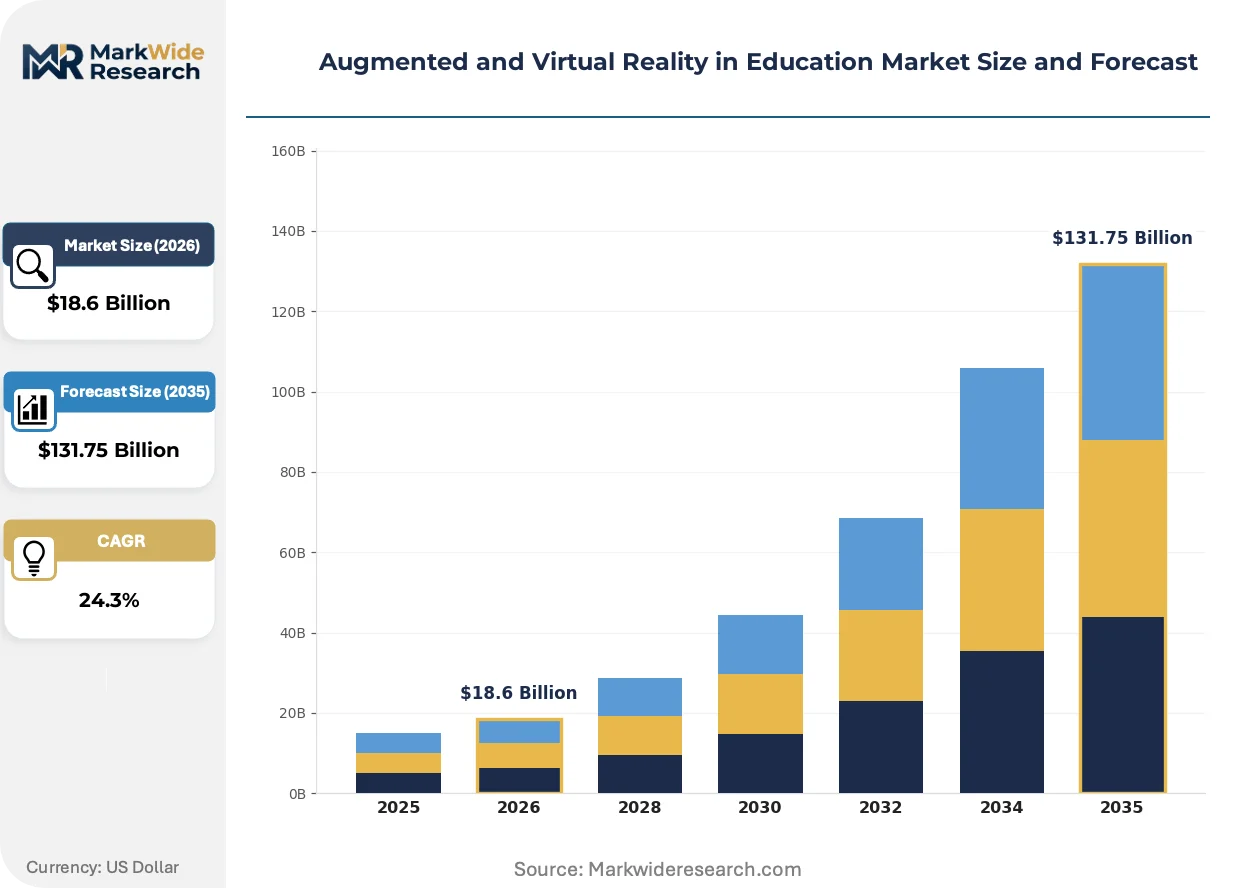
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $131.75 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AR Headsets, VR Headsets, Software Solutions, Simulation Tools End User: Schools, Universities, Training Centers, Corporate Learning Technology: Immersive Learning, Interactive Platforms, Content Creation Tools, AI Integration Application: STEM Education, Professional Training, Language Learning, Skill Development |
| Companies Covered | Meta Platforms, Inc., Microsoft Corporation, Sony Group Corporation, HTC Corporation, Google LLC, EON Reality, Inc., Lenovo Group Ltd., zSpace, Inc., Labster ApS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Augmented and Virtual Reality in Education Market Emerging Trajectories
Immersive learning architectures are pivoting from standalone hardware sales toward integrated platform ecosystems. The sector is witnessing accelerated convergence between cloud rendering infrastructure and cellular edge delivery.
Pass-through mixed reality is supplanting fully occluded virtual reality in K-12 deployments. Stereoscopic cameras embedded in headsets overlay digital content onto physical classroom environments, preserving teacher visibility and spatial awareness. District technology coordinators in the United States are prioritizing these hybrid systems for chemistry and physics laboratories where physical equipment manipulation remains pedagogically essential.
The European Union's Artificial Intelligence Act establishes risk classification frameworks for biometric emotion recognition in educational settings. Vendors deploying attention-tracking algorithms must now demonstrate proportionality and obtain explicit institutional consent. French secondary schools are delaying procurement of analytics-enabled headsets pending national CNIL guidance on pupil data processing.
Subscription-based content licensing is eroding perpetual software ownership in higher education. University procurement offices are negotiating enterprise-wide immersive library access rather than title-by-title acquisition. This shift is most pronounced in Australian technical colleges where TAFE institutions aggregate demand through state-level purchasing consortia.
Augmented and Virtual Reality in Education Market Segmentation
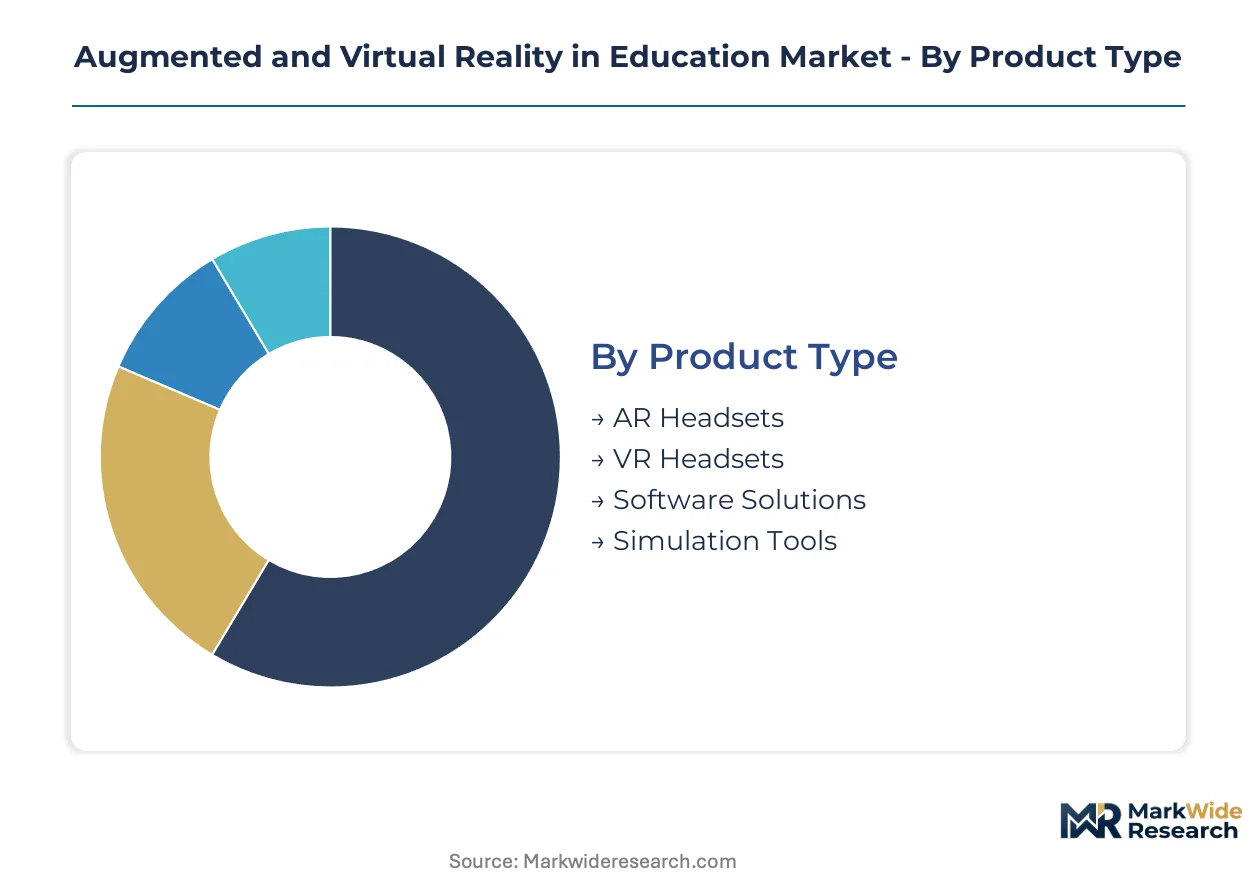
Segmentation in AR/VR education reveals how procurement patterns diverge across institutional budgets, regulatory constraints, and pedagogical requirements. Understanding these divides helps vendors align product roadmaps with buyer capabilities and compliance obligations.
Product Type:
FCC E-Rate subsidies in the United States favor hardware bundles that include managed software services, while EU procurement frameworks under GDPR constrain biometric-enabled headset categories. China's GB standards for classroom electronics create certification barriers that reshape vendor product mixes.
- Software Solutions:Cloud-based licensing platforms enable centralized content distribution and usage analytics for district IT administrators. Recurring revenue models dominate procurement conversations in Australian TAFE consortia and German vocational networks seeking predictable budget cycles.
- VR Headsets:Fully occluded headsets with 90Hz refresh rates and sub-20ms motion-to-photon latency deliver procedural simulation for aviation and healthcare training. FAA certification requirements for pilot training drive enterprise procurement in United States flight schools and Indian aviation academies.
- AR Headsets:Pass-through optical systems overlay digital content onto physical laboratory environments. French secondary schools under CNIL guidance prioritize these for chemistry instruction where teacher visibility remains mandatory.
- Simulation Tools:Physics engines and haptic feedback peripherals enable precision skill rehearsal. German Federal Institute for Vocational Education pilots these for manufacturing apprenticeship programs.
Software Solutions handle the majority of throughput; Professional Training applications within VR Headsets are gaining share fastest.
End User:
Customer scale determines pricing architecture and support intensity. Enterprise buyers negotiate multi-year enterprise agreements while K-12 districts depend on federal relief allocations.
- Corporate Learning:Reskilling programs at aviation maintenance facilities and healthcare systems command premium budgets for risk-free procedural rehearsal. Indian surgical training centers license anatomical libraries previously limited to cadaver-based instruction.
- Training Centers:Vocational institutes in Germany and Australia aggregate demand through state-level purchasing consortia. These institutions prioritize AR-guided precision manufacturing modules over traditional classroom instruction.
- Universities:Higher education procurement offices negotiate enterprise-wide immersive library access rather than title-by-title acquisition. Subscription models displace perpetual ownership in North American research institutions.
- Schools:K-12 districts in the United States leverage ESSER-funded technology upgrades for hardware procurement cycles. Chinese provincial education bureaus mandate smart classroom infrastructure in tier-two city secondary schools.
Corporate Learning captures the highest per-seat pricing; Training Centers are expanding most quickly as enterprise reskilling displaces traditional certification pathways.
Technology:
Technical maturity curves separate experimental deployments from scaled implementations. Cloud rendering capabilities now determine geographic reach for vendors without localized server infrastructure.
- AI Integration:Attention-tracking algorithms and biometric emotion recognition trigger EU AI Act risk classification requirements. French schools delay analytics-enabled headset procurement pending national CNIL proportionality assessments.
- Immersive Learning:Stereoscopic display systems operating at 90 frames per second with specialized GPU architectures dominate vocational precision training. zSpace installations anchor technical education centers requiring spatial manipulation capabilities.
- Interactive Platforms:Multi-user collaborative environments enable remote laboratory instruction. 5G edge streaming architectures eliminate tethered PC dependencies for mobile classroom deployments in Japan and South Korea.
- Content Creation Tools:Authoring suites for three-dimensional curriculum development face talent scarcity in educational technology departments. Instructional design personnel trained in spatial pedagogy remain concentrated in specialized studios.
Immersive Learning carries the installed base; AI Integration faces the steepest regulatory compliance trajectory.
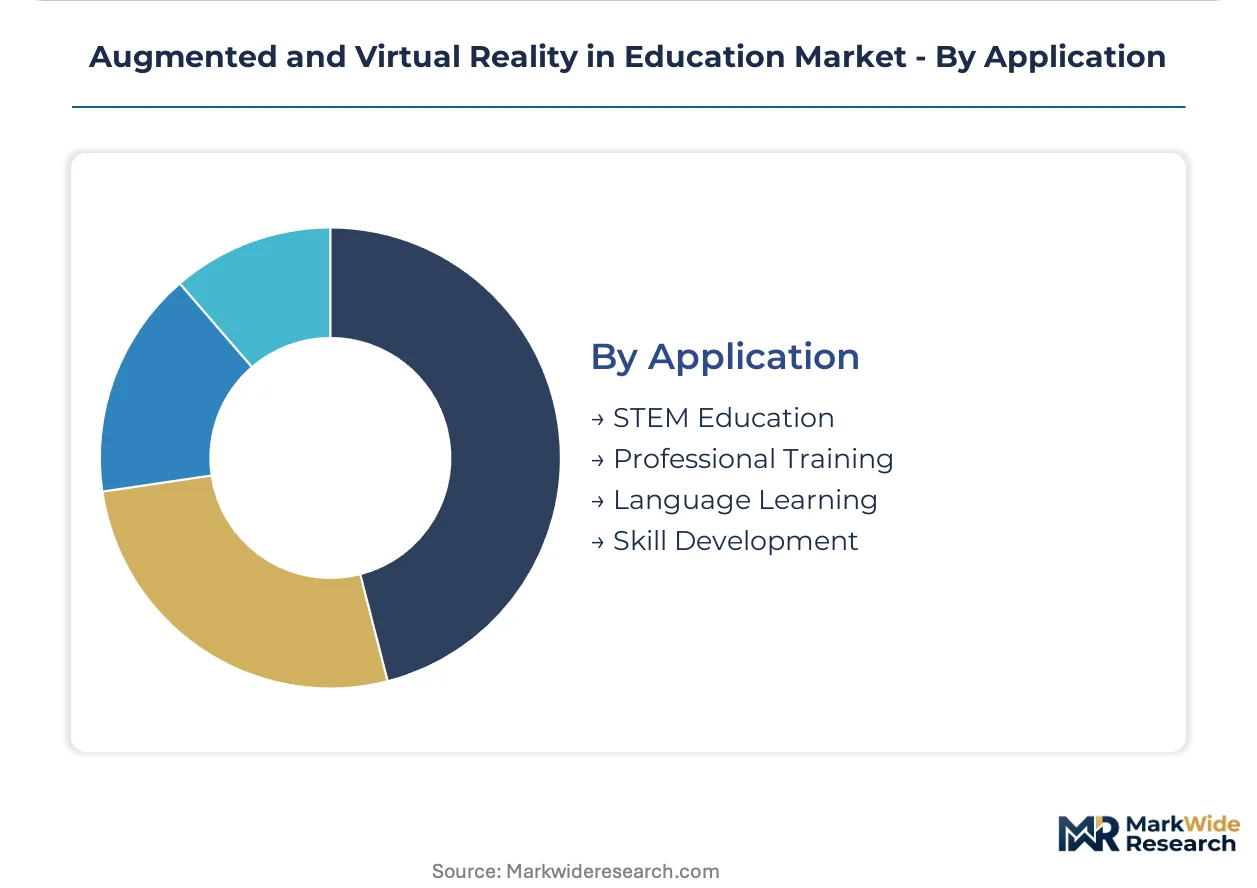
Application:
Pedagogical outcomes drive funding allocation across institutional types. STEM disciplines command dedicated equipment budgets while language instruction favors lower-cost mobile AR solutions.
- STEM Education:Physics, chemistry, and biology simulations where physical replication proves cost-prohibitive or dangerous. United States district technology coordinators prioritize pass-through mixed reality for laboratory environments where equipment manipulation remains essential.
- Professional Training:Aviation, healthcare, and hazardous procedure simulation with measurable competency certification. FAA training mandates expand corporate VR budgets for risk-free procedural rehearsal environments.
- Skill Development:Vocational reskilling for precision manufacturing trades. Germany's Federal Institute for Vocational Education pilots AR-guided apprenticeship programs with measurable throughput gains.
- Language Learning:Immersive conversation environments with AI-generated native speaker scenarios. Lower hardware requirements enable smartphone-based AR deployment in budget-constrained institutions.
STEM Education absorbs the largest absolute spending; Professional Training registers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate learning buyers in the United States tolerate premium hardware costs for FAA-compliant aviation simulation, while Chinese provincial education bureaus enforce aggressive price ceilings for smart classroom rollouts in tier-two cities. German vocational institutes occupy the middle ground, prioritizing measurable training outcomes over acquisition cost.
United States
Flight schools and healthcare systems command enterprise VR budgets for risk-free procedural rehearsal. FCC E-Rate subsidies accelerate district-level hardware procurement cycles for K-12 immersive technology deployments. District technology coordinators in Texas and California prioritize pass-through mixed reality systems for chemistry laboratories.
China
Provincial education bureaus mandate stereoscopic display installations in secondary schools across tier-two cities. GB standards for classroom electronics dictate display brightness thresholds and electromagnetic compatibility testing protocols. Chengdu and Xi'an anchor smart classroom infrastructure deployment clusters.
Germany
The Federal Institute for Vocational Education pilots AR-guided apprenticeship programs for precision manufacturing trades. GDPR compliance frameworks constrain biometric data collection from student headset users. Stuttgart and Munich host technical education centers deploying simulation tools for measurable throughput gains.
India
Surgical training centers license anatomical simulation content for residency programs previously limited to cadaver-based instruction. The country's national education technology regulator monitors data localization requirements for cloud-rendered immersive content. Bangalore and Hyderabad anchor healthcare procedure library development clusters.
France
Secondary schools delay procurement of analytics-enabled headsets pending CNIL guidance on pupil data processing. The EU AI Act risk classification framework triggers proportionality assessments for biometric emotion recognition in educational settings. Lyon and Toulouse host chemistry instruction pilots using pass-through optical systems.
Augmented and Virtual Reality in Education Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the sector. Full-stack platform developers anchor institutional deployments through hardware-software integration, while content-only specialists compete on licensing flexibility and curriculum breadth. Three archetypes dominate: cloud-integrated enterprise platforms, stereoscopic display specialists, and immersive content studios. Strategic moves concentrate on multi-year contract lock-in and cloud rendering infrastructure partnerships.
Within the full-stack tier, Meta Platforms, Inc. and Microsoft Corporation exemplify divergent ecosystem strategies. Meta anchors North American higher education through its Reality Labs hardware ecosystem. Microsoft competes via Azure cloud integration for K-12 districts embedded in Office 365 environments. zSpace, Inc. occupies a specialist position serving vocational and technical training centers requiring precision spatial manipulation capabilities.
| Leading Market Players |
|---|
| Meta Platforms, Inc. |
| Microsoft Corporation |
| Sony Group Corporation |
| HTC Corporation |
| Google LLC |
| EON Reality, Inc. |
| Lenovo Group Ltd. |
| zSpace, Inc. |
| Labster ApS |
| Others |
Supply Flow & Price Mechanics
Ninety-day component lead times for OLED microdisplays have compressed vendor margins and forced a strategic pivot toward software licensing models that lock institutional buyers into recurring revenue streams. This inventory pressure concentrates pricing power among East Asian foundries while North American and European headset vendors absorb cost volatility through tiered service bundling.
Pricing Analysis
Extended warranty and content update contracts generate lifetime value multiples exceeding initial hardware transactions. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified aviation simulation systems from K-12 classroom bundles and mobile AR smartphone applications. Cost compression in mid-tier VR headsets is intensifying because ESSER funding exhaustion forces US districts toward lower-specification procurement. Corporate learning buyers in aviation and healthcare exhibit the lowest price sensitivity, while Chinese provincial education bureaus enforce aggressive ceilings for smart classroom rollouts.
Supply Chain Analysis
Container availability constraints on trans-Pacific lanes have inflated inbound logistics costs for US-based hardware assemblers. OLED microdisplay manufacturing concentrates in South Korea and Taiwan, while rare earth magnet sourcing for haptic feedback motors rests on Chinese processing facilities. Single-source vulnerability in East Asian foundry capacity threatens headset vendors outside the region during demand surges. Distribution runs through direct enterprise sales teams for corporate learning contracts and state-level purchasing consortia for vocational institutes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market faces substitution pressure from AI-generated simulation platforms that replicate procedural training without dedicated headset hardware. Incumbents must navigate this threat by anchoring institutional relationships through integrated platform ecosystems.
For Market Incumbents: Shield installed base relationships by embedding cloud rendering infrastructure that increases switching costs for district IT administrators. Prioritize certification investment in FAA-compliant aviation modules and GDPR-compliant biometric data architectures to create regulatory moats against low-cost Asian competitors. Consolidate content libraries through exclusive licensing agreements with anatomical and physics simulation studios. For New Entrants and Emerging Players: Curriculum localization services represent an underserved layer where incumbents under-serve non-English-speaking markets. White-space targets include AR-guided apprenticeship content for German precision manufacturing and Hindi-language surgical simulation libraries for Indian residency programs. Go-to-market execution should anchor through vocational institute consortia rather than direct K-12 district sales. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because recurring software revenue multiples exceed hardware transaction valuations as institutional procurement shifts toward subscription models. Acquisition targets should display proprietary physics engines or haptic feedback IP with FAA or medical certification pathways. Monitor 5G edge streaming deployment timelines as the inflection signal for untethered classroom scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Rendering Infrastructure Partnership | Azure and AWS integrations enable hybrid AR delivery for Office 365-embedded K-12 districts. |
| FAA Certification Pathway Investment | Aviation simulation mandates in US flight schools create captive demand for compliant procedural libraries. |
| GDPR-Compliant Biometric Architecture | CNIL and EU AI Act proportionality requirements delay analytics-enabled headset procurement without explicit consent frameworks. |
| State-Level Purchasing Consortium Alignment | Australian TAFE and German vocational networks aggregate demand through centralized procurement offices. |
| 5G Edge Streaming Platform Launch | Low-latency cellular networks eliminate tethered PC dependencies for mobile classroom deployments in Japan and South Korea. |
Methodological Framework
Two parallel data streams informed the analysis: structured conversations with district technology coordinators, vocational institute procurement officers, aviation training facility managers, and immersive content studio executives; and secondary validation against FCC E-Rate disbursement records, ESSER funding allocation databases, FAA training mandate documentation, and EU AI Act regulatory filings. Bottom-up triangulation of hardware shipment data and top-down reconciliation against institutional IT budget surveys anchored volume estimates.
Across the projection horizon, the analytical framework modeled segmentation across product type, end user, technology architecture, and application pedagogy, with additional granularity for regional regulatory cluster variations. CAGRs were derived from installed base growth rates and replacement cycle compression observed in procurement pattern analysis. Forecast inputs incorporated 5G infrastructure deployment schedules and cloud rendering capability expansion timelines.
Material uncertainties — ESSER fund exhaustion rates, GDPR enforcement variance across EU member states, and OLED foundry capacity allocation shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about institutional procurement cycle continuity and certification pathway stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
M-Education Market