
 Artificial Intelligence in the Education Sector Market | 2026-2036
Artificial Intelligence in the Education Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Intelligence in the Education Sector Market Analysis
China is fragmenting as a production hub for AI education infrastructure, with domestic cloud providers and hardware assemblers multiplying regional data center capacity. Google LLC leverages its Tensor processing ecosystem to anchor large-scale personalized learning deployments across North American school districts. Microsoft competes through Azure OpenAI integrations that sustain enterprise-grade security compliance for higher education institutions. Squirrel AI dominates adaptive tutoring in East Asian markets through specialized algorithmic architectures optimized for mathematics and language acquisition.
Artificial Intelligence in the Education Sector encompasses machine learning algorithms, natural language processing engines, and predictive analytics models that process student behavioral data to automate instructional adaptation, assessment generation, and administrative forecasting. These systems typically operate through cloud-based inference pipelines requiring sub-200-millisecond response times for real-time feedback loops during live classroom sessions. Machine Learning applications currently occupy the deepest margin pools as institutions prioritize predictive dropout modeling and automated grading workflows over robotics hardware. Natural Language Processing is displacing conventional chatbot architectures as universities demand sophisticated essay evaluation and Socratic dialogue simulation. Cloud-Based deployment controls the majority of institutional procurement budgets, though Hybrid configurations are gaining traction among European universities constrained by GDPR data residency requirements.
The U.S. Department of Education coordinates with the FTC to enforce student data privacy standards under FERPA and COPPA, compelling vendors to implement auditable data minimization protocols. The EU AI Act imposes conformity assessment obligations on high-risk educational AI systems, effectively restricting market access for uncertified predictive analytics platforms. China's SAMR and Ministry of Education jointly mandate algorithmic transparency for K-12 adaptive learning products, creating divergent compliance architectures for multinational suppliers. Stakeholders must monitor whether emerging national AI safety institutes will extend licensing requirements into formative assessment technologies before committing to regional platform investments.
Market Dynamics
Adaptive learning algorithms are compressing procurement cycles across K-12 and higher education institutions, forcing vendors to demonstrate measurable learning outcome improvements within single academic year horizons rather than multi-year pilot programs.
Growth Catalysts
- Federal Infrastructure Stimulus:United States K-12 systems are channeling ESSER funds into AI-powered tutoring platforms, creating immediate procurement windows for adaptive assessment vendors.
- EU AI Act Conformity Pathways:The risk-based classification system for educational algorithms is creating compliance-driven replacement demand as institutions retire non-conforming legacy systems.
- Cloud Inference Latency Thresholds:Sub-200-millisecond response requirements for real-time classroom feedback are accelerating hardware refresh cycles in mathematics and language acquisition applications.
Market Restraints
- GDPR Data Residency Mandates:European universities face structural constraints on cloud-only deployments, forcing expensive hybrid infrastructure investments that compress vendor margins.
- Algorithmic Transparency Requirements:China's SAMR mandates for K-12 adaptive learning products create divergent compliance architectures that fragment product development resources.
- FERPA Audit Protocols:The US Department of Education's data minimization enforcement is extending sales cycles by requiring auditable privacy frameworks as table stakes.
Strategic Opportunities
- Essay Evaluation Automation:Natural Language Processing engines capable of Socratic dialogue simulation represent underpenetrated white space in higher education humanities departments.
- Hybrid Deployment Architectures:GDPR-constrained European institutions are creating demand for edge-computing configurations that process behavioral data within national borders.
- Predictive Dropout Modeling:Machine learning applications for administrative forecasting remain unevenly deployed across community college systems and regional university networks.
Industry Challenges
- Multidisciplinary Product Teams:Vendors struggle to recruit talent combining pedagogical expertise with machine learning engineering and regulatory compliance knowledge.
- Legacy LMS Integration:Custom API development for incumbent learning management systems consumes disproportionate engineering resources relative to core algorithm development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Intelligence in the Education Sector Market |
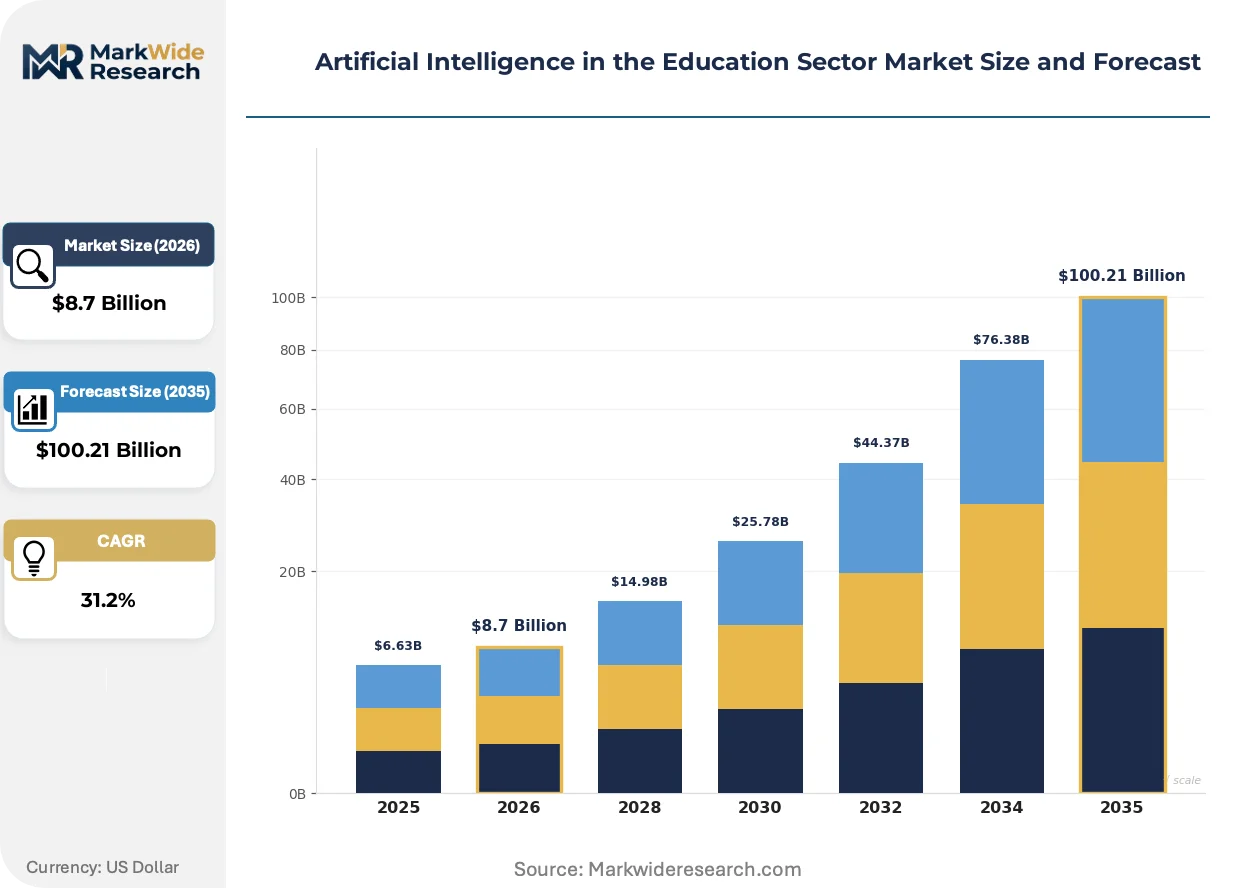
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $100.21 Billion |
| CAGR (2026 – 2036) | 31.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Personalized Learning, Assessment Tools, Virtual Classrooms, Learning Analytics Technology: Natural Language Processing, Machine Learning, Robotics, Predictive Analytics End User: K-12 Schools, Higher Education Institutions, Corporate Training, Educational NGOs Deployment Model: Cloud-Based, On-Premises, Hybrid, Mobile Solutions |
| Companies Covered | Google LLC, IBM Corporation, Microsoft, Amazon Web Services, Inc., Pearson, Carnegie Learning, Inc., DreamBox Learning, Inc., Squirrel AI, Nuance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Intelligence in the Education Sector Market Emerging Trajectories
Generative AI architectures are rewriting competitive boundaries between established adaptive tutoring platforms and enterprise software incumbents, compressing the window for specialized vendors to demonstrate sustainable differentiation.
Transformer-based large language models are rendering obsolete conventional rule-based chatbot architectures in university helpdesk and tutoring applications. Higher education IT departments are accelerating procurement of dialogue systems capable of contextual follow-up and multi-turn reasoning. The technology is rendering obsolete three-year chatbot replacement cycles by enabling continuous model refinement without full platform rebuilds.
The EU AI Act's high-risk system classification for predictive student analytics is forcing conformity assessment investments before market access. Educational technology vendors must now document risk management systems and post-market monitoring protocols for automated grading and dropout prediction tools. North American institutions are beginning to demand similar audit trails as procurement due diligence standardizes across jurisdictions.
Subscription-based platform licensing is displacing perpetual software purchases in K-12 district procurement. Chief technology officers are prioritizing vendors offering outcome-linked renewal terms tied to measurable learning gains. This shift is most visible in United States urban school systems where ESSER fund exhaustion is forcing operating expenditure discipline and vendor consolidation.
Artificial Intelligence in the Education Sector Market Segmentation
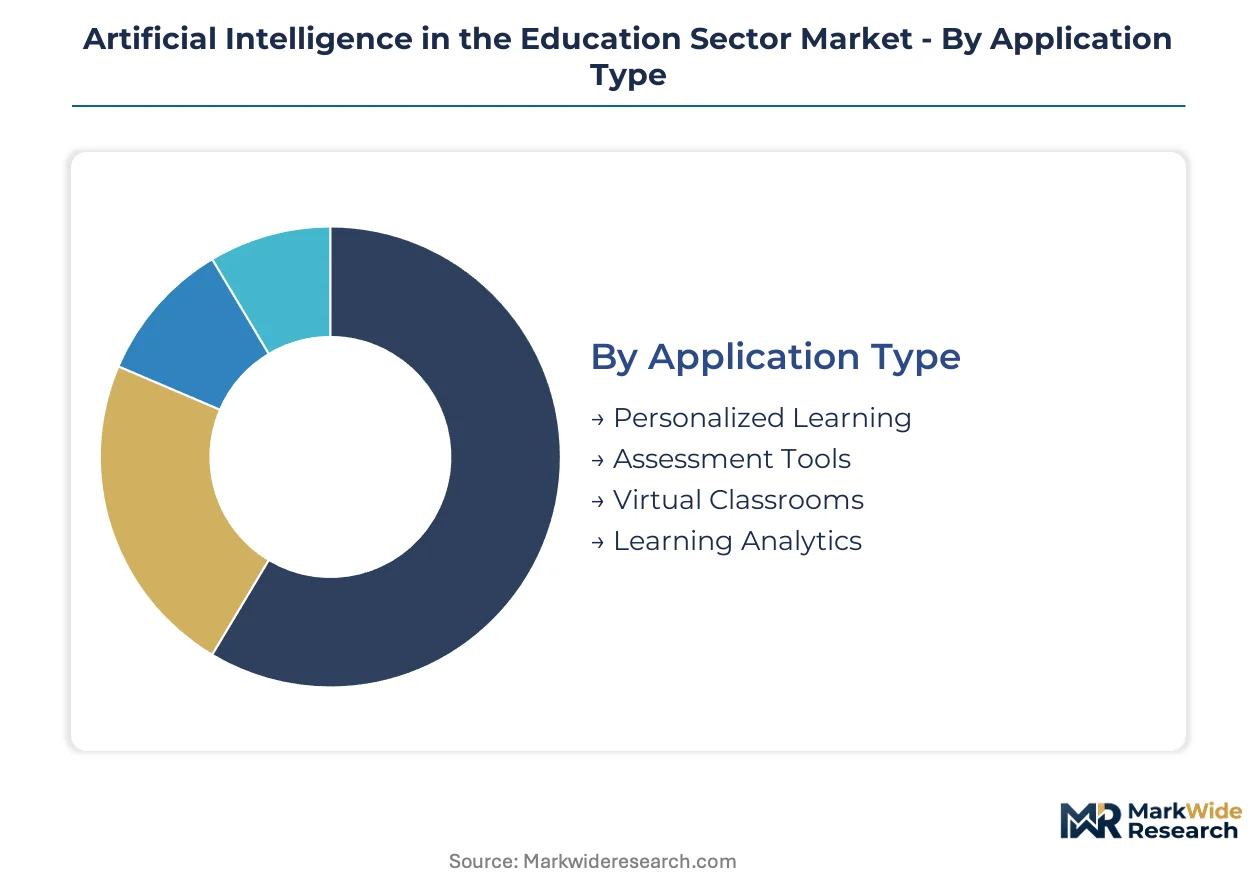
Artificial Intelligence in the Education Sector Market segmentation reveals how procurement priorities diverge across institutional contexts. Vendors must align product architectures with distinct latency requirements, compliance burdens, and pedagogical workflows.
Application Type:
Mature deployments dominate administrative automation, while emerging applications reshape live instruction.
- Personalized Learning:Adaptive algorithms modify content sequencing in real-time based on student performance telemetry. United States K-12 districts channel ESSER stimulus into these platforms, demanding measurable literacy gains within single academic year horizons.
- Assessment Tools:Automated grading engines process essay submissions and standardized test responses using transformer-based evaluation models. Higher education institutions in North America prioritize these systems to reduce instructional labor costs in large-enrollment gateway courses.
- Virtual Classrooms:Immersive environments integrate computer vision for attention tracking and gesture recognition.
- Learning Analytics:Dashboard systems aggregate behavioral signals to flag at-risk students for intervention.
Assessment Tools retain volume leadership; Personalized Learning holds the steepest expansion curve.
Technology:
Cost tiers separate commodity inference from specialized pedagogical architectures.
- Natural Language Processing:Large language models power Socratic dialogue systems and automated essay evaluation. European universities under GDPR constraints demand on-premise or hybrid deployments for sensitive student writing samples.
- Machine Learning:Predictive models forecast dropout risk and optimize resource allocation. Community college systems in the United States deploy these most aggressively to improve retention metrics tied to state funding formulas.
- Robotics:Physical tutoring agents and laboratory automation hardware serve STEM education environments.
- Predictive Analytics:Administrative forecasting tools project enrollment trends and facility utilization.
Machine Learning commands the largest procurement budgets; Natural Language Processing is climbing the fastest.
End User:
Customer type determines pricing tolerance and compliance sophistication.
- K-12 Schools:District-level procurement favors outcome-linked subscription models over perpetual licenses. Federal infrastructure stimulus in the United States accelerates deployment of adaptive tutoring platforms with auditable privacy frameworks.
- Higher Education Institutions:Universities demand enterprise-grade security certifications and API integration with legacy learning management systems. Azure OpenAI and comparable cloud integrations dominate RFP requirements for research-intensive campuses.
- Corporate Training:Enterprise learning departments prioritize skills-gap analytics and certification automation.
- Educational NGOs:Non-governmental organizations seek low-cost deployments for underserved populations.
Higher Education Institutions retain volume leadership; Corporate Training holds the steepest expansion curve.
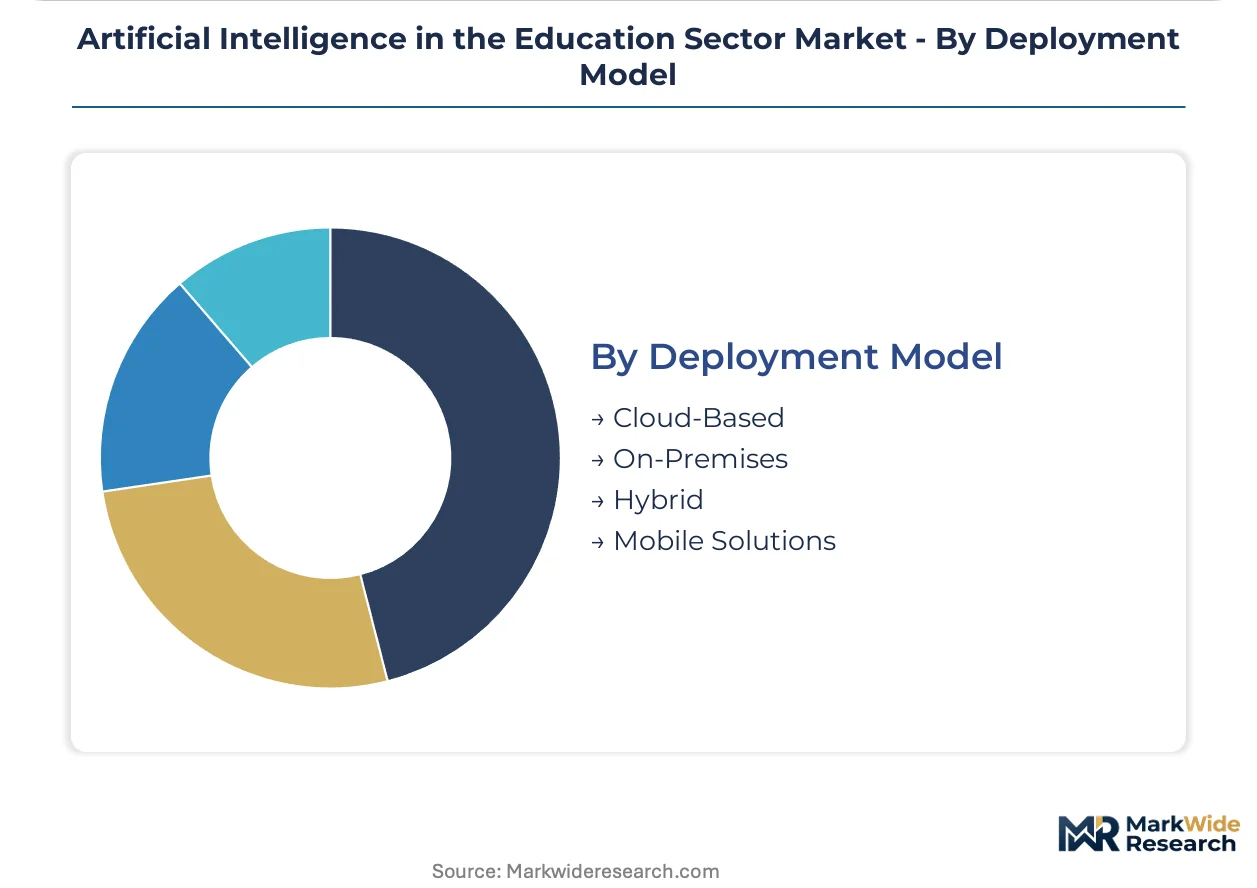
Deployment Model:
Data residency mandates fragment cloud-only strategies across jurisdictions.
- Cloud-Based:Centralized inference pipelines serve institutions without specialized compliance requirements. Sub-200-millisecond latency thresholds for real-time classroom feedback drive edge location investments by major providers.
- Hybrid:Split architectures process sensitive behavioral data on-premise while leveraging cloud resources for model training. European universities constrained by GDPR data residency mandates are expanding this configuration fastest.
- On-Premises:Fully localized deployments satisfy national security requirements in defense-related training programs.
- Mobile Solutions:Smartphone-native applications extend tutoring access to students without dedicated computing devices.
Cloud-Based retains volume leadership; Hybrid holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud hyperscalers concentrate AI education infrastructure investments across three dominant jurisdictions. North American school districts channel federal stimulus into adaptive platforms, while European compliance mandates and East Asian algorithmic specialization create divergent procurement architectures.
United States
K-12 districts deploy ESSER-funded tutoring systems with sub-200-millisecond latency requirements for real-time mathematics feedback. The Department of Education coordinates with FTC under FERPA and COPPA to enforce auditable data minimization protocols. Boston and Austin metropolitan clusters host concentrated vendor engineering operations serving higher education LMS integration demands.
China
Domestic cloud providers multiply regional data center capacity for K-12 adaptive learning products. SAMR and Ministry of Education jointly mandate algorithmic transparency for mathematics and language acquisition platforms. Shanghai and Beijing anchor specialized algorithmic development for Squirrel AI and comparable domestic adaptive tutoring architectures.
Germany
Technical universities under GDPR constraints prioritize hybrid deployment configurations processing sensitive student data on-premise. The EU AI Act conformity assessment obligations reshape procurement criteria for predictive analytics vendors. Munich and Berlin industrial clusters concentrate compliance engineering talent for educational algorithm certification.
United Kingdom
Higher education institutions accelerate procurement of transformer-based dialogue systems for humanities department essay evaluation. GDPR data residency mandates drive edge-computing investments from major cloud providers. London and Oxford-Cambridge corridor anchor NLP research partnerships between universities and enterprise software incumbents.
India
State government digital education missions expand procurement of mobile-native tutoring applications for underserved student populations. BIS standards and central education ministry guidelines shape algorithmic procurement specifications for public school systems. Bangalore and Hyderabad technology clusters host engineering operations serving both domestic adaptive platforms and multinational cloud inference deployments.
Artificial Intelligence in the Education Sector Market Vendor Landscape
Cloud hyperscalers and specialized adaptive tutoring platforms split the market between infrastructure-scale deployments and pedagogical algorithm optimization. The vendor base concentrates around three strategic archetypes: hyperscale cloud providers with education-specific compliance certifications, specialized adaptive learning vendors with subject-matter algorithmic depth, and legacy educational publishers with institutional distribution relationships. Competitive dynamics center on API integration speed with incumbent learning management systems and outcome-linked subscription pricing models that tie renewal terms to measurable learning gains.
Within the hyperscale tier, Google LLC and Microsoft exemplify divergent approaches to institutional procurement security requirements. Google leverages Tensor processing ecosystems for large-scale personalized learning deployments across North American school districts, while Microsoft competes through Azure OpenAI integrations sustaining enterprise-grade compliance for research-intensive universities. Squirrel AI occupies a distinct position as an East Asian specialist in mathematics and language acquisition algorithmic architectures optimized for regional curriculum structures.
| Leading Market Players |
|---|
| Google LLC |
| IBM Corporation |
| Microsoft |
| Amazon Web Services, Inc. |
| Pearson |
| Carnegie Learning, Inc. |
| DreamBox Learning, Inc. |
| Squirrel AI |
| Nuance |
| Others |
Supply Flow & Price Mechanics
United States cloud hyperscaler concentration for GPU inference capacity anchors margin capture downstream, with subscription pricing power flowing to vendors controlling sub-200-millisecond latency infrastructure for real-time classroom feedback loops.
Pricing Analysis
The EU AI Act dictates the pricing tier structure for educational algorithm procurement across European institutions. Three-tier pricing structure across premium, standard, and economy levels separates hyperscale cloud integrations with full conformity assessment documentation from mid-market hybrid deployments and basic on-premise configurations. Cost compression in the economy tier is intensifying because GDPR data residency mandates force expensive edge infrastructure investments that vendors struggle to recover at scale. K-12 school districts in the United States exhibit the highest price sensitivity due to ESSER fund exhaustion, while research-intensive universities demonstrate lowest sensitivity given enterprise-grade security requirements.
Supply Chain Analysis
Export-control restrictions on advanced GPU and tensor processing unit shipments limit hardware availability for training large educational language models. Taiwan, South Korea, and the United States anchor semiconductor fabrication for AI education infrastructure. Supply chains draw from specialized memory components, high-bandwidth interconnects, and precision cooling systems. Single-source vulnerability concentrates in advanced node GPU supply from TSMC-dependent designers. Distribution runs through direct enterprise sales teams serving higher education institutions and channel partners penetrating fragmented K-12 district procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce talent pools combining pedagogical expertise with machine learning engineering and regulatory compliance knowledge constrain execution velocity across all competitive tiers.
For Market Incumbents: Insulate market position by deepening API integration speed with incumbent learning management systems to raise switching costs for higher education customers. Invest in auditable privacy frameworks ahead of anticipated FERPA enforcement expansions. Backward integration into specialized GPU allocation contracts secures inference capacity for real-time adaptive tutoring deployments. For New Entrants and Emerging Players: Community college systems in the United States with uneven predictive dropout modeling penetration represent the most penetrable entry point for machine learning administrative forecasting tools. European hybrid deployment architectures constrained by GDPR data residency mandates offer white-space for edge-computing specialists. Lead with outcome-linked subscription pilots tied to measurable retention metric improvements. For Investors and Strategic Acquirers: Capital is best deployed toward specialized adaptive learning vendors with subject-matter algorithmic depth in mathematics and language acquisition. Long-term viability hinges on demonstrating sustainable differentiation against transformer-based large language model commoditization. Watch for EU AI Act conformity assessment completion rates as inflection indicator for European market access viability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Deployment Architecture Launch | GDPR-constrained European universities require on-premise behavioral data processing with cloud model training. |
| API Integration Partnership | Legacy LMS connectivity consumes disproportionate engineering resources relative to core algorithm development. |
| Conformity Assessment Investment | EU AI Act high-risk system classification forces documentation of risk management systems for automated grading tools. |
| Outcome-Linked Subscription Model | ESSER fund exhaustion drives K-12 procurement toward renewable terms tied to measurable literacy gains. |
| Pedagogical-Engineering Talent Acquisition | Multidisciplinary product teams combining regulatory compliance knowledge remain scarce across competitive tiers. |
Methodological Framework
Operator-level perspectives from chief technology officers at K-12 school districts, university IT procurement directors, adaptive learning platform product managers, and regulatory compliance officers anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of publicly traded education technology vendors, hyperscaler capex disclosures for cloud infrastructure investments, and EU AI Act implementation guidance documents. Bottom-up deployment estimates across application types, technologies, and end-user segments triangulated against top-down market sizing from institutional procurement budget flows.
Scenario-bracketing around regulatory enforcement intensity and federal stimulus continuity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include application type, technology category, end-user institution, and deployment model complexity. CAGRs derived from institution-level procurement cycle analysis and vendor revenue recognition patterns. Forecast inputs incorporated ESSER fund exhaustion timelines and EU AI Act conformity assessment completion rates.
Practitioners should monitor federal infrastructure stimulus renewal debates and emerging national AI safety institute licensing proposals for early signals. Forecasts reflect assumptions about sustained cloud hyperscaler investment in education-specific compliance certifications. Material shifts in FERPA enforcement protocols or GPU export-control expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
Global Smart Learning Market
Educational Technology (EdTech)
Education Security Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Global Smart Classroom Market
Educational Technology (EdTech)
Micro Learning Platform Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Flipped Classroom Market