
 Back to School Market | 2026-2036
Back to School Market Size, Share, and Industry Trends Forecast 2026-2036
Back to School Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) is shifting demand toward products with verifiable sustainable sourcing and recycled content. Amazon.com, Inc. leverages its massive logistics network to offer a wide array of eco-friendly product options. Walmart Inc. controls a significant share of the budget-friendly segment through its extensive global brick-and-mortar presence. Newell Brands Inc. differentiates its market position through its portfolio of established stationery and writing instrument brands.
Back to school products encompass a range of consumer goods, from paper-based stationery manufactured with specific pulp blends and GSM weights to advanced electronic devices. The primary purpose is to equip students and educators with the necessary tools for academic activities, digital learning, and personal organization. Electronics, including laptops and tablets, represent the fastest-growing product type category due to digital curriculum adoption. Online retailers are rapidly gaining share from traditional brick-and-mortar channels, especially for higher-priced technology items.
Product safety and material standards are governed by bodies like the US Consumer Product Safety Commission (CPSC) and EU regulations such as REACH, which restricts hazardous chemicals. In parallel, the US Federal Trade Commission (FTC) and the UK's Competition and Markets Authority (CMA) scrutinize marketing claims related to environmental benefits. Stakeholders must now decide how to balance investments in digital innovation against the rising compliance costs associated with global sustainability mandates.
Market Dynamics
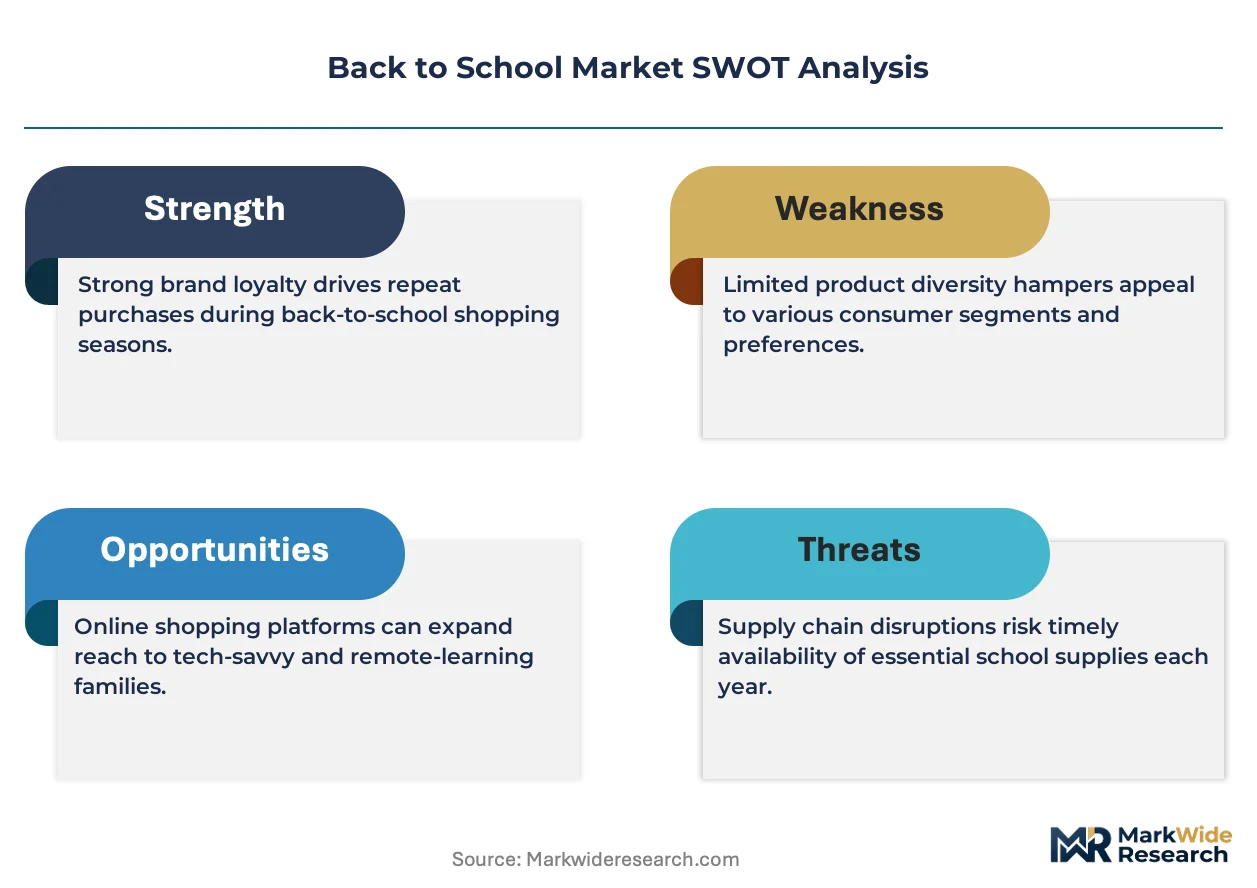
The central dynamic shaping the back to school market is the structural tension between demand for high-specification digital learning tools and the rising compliance costs associated with global sustainability mandates, forcing difficult investment trade-offs for manufacturers and retailers.
Growth Catalysts
- Government Initiatives:Education modernization programs in countries like India are expanding public procurement of essential school supplies, including stationery, uniforms, and basic electronics, creating a large, centralized demand pool for suppliers.
- Digital Curriculum Adoption:The integration of AI-powered educational software and digital textbooks in higher education is driving student demand for laptops and tablets with advanced processing capabilities and longer battery life.
- Sustainable Product Demand:Consumer and institutional buyer preference for products with verifiable eco-credentials, such as those using recycled materials or carrying sustainability certifications, is creating a premium segment and new product development opportunities.
Market Restraints
- Input Cost Volatility:Fluctuations in the prices of key raw materials, including paper pulp for stationery and semiconductors for electronics, create margin pressure and complicate long-term pricing strategies for manufacturers.
- Substitution from Digital Alternatives:The availability of free or low-cost open-source educational software and digital organizational tools presents a significant substitution threat to traditional paid software licenses and physical planners.
- Regulatory Fragmentation:Divergent product safety and chemical regulations, such as the US CPSC standards versus the EU's REACH framework, increase the complexity and cost of compliance for companies operating across multiple regions.
Strategic Opportunities
- Subscription-Based Models:Developing subscription services for curated digital content, software bundles, and even device-as-a-service programs offers a pathway to recurring revenue streams, especially in the higher education market.
- Circular Economy Products:Designing products for repairability, disassembly, and recycling aligns with policy direction like the EU Green Deal, opening access to environmentally conscious consumer segments and public tenders with green criteria.
- Emerging Market Expansion:Targeting underpenetrated markets in Southeast Asia and Africa, where educational enrollment rates are rising and digital infrastructure is improving, provides a significant long-term growth vector beyond mature markets.
Industry Challenges
- Sustainability Reporting Burden:Implementing the systems necessary to track, verify, and report on supply chain sustainability to meet mandates like the CSRD imposes significant administrative and financial costs on vendors.
- Channel Management Complexity:Managing inventory, pricing, and logistics across a hybrid model of brick-and-mortar stores and rapidly growing online retail channels requires sophisticated supply chain capabilities and investment.
- Greenwashing Scrutiny:Companies face increased legal and reputational risk from regulators like the FTC and CMA, who are actively policing unsubstantiated environmental marketing claims on product packaging and advertisements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Back to School Market |
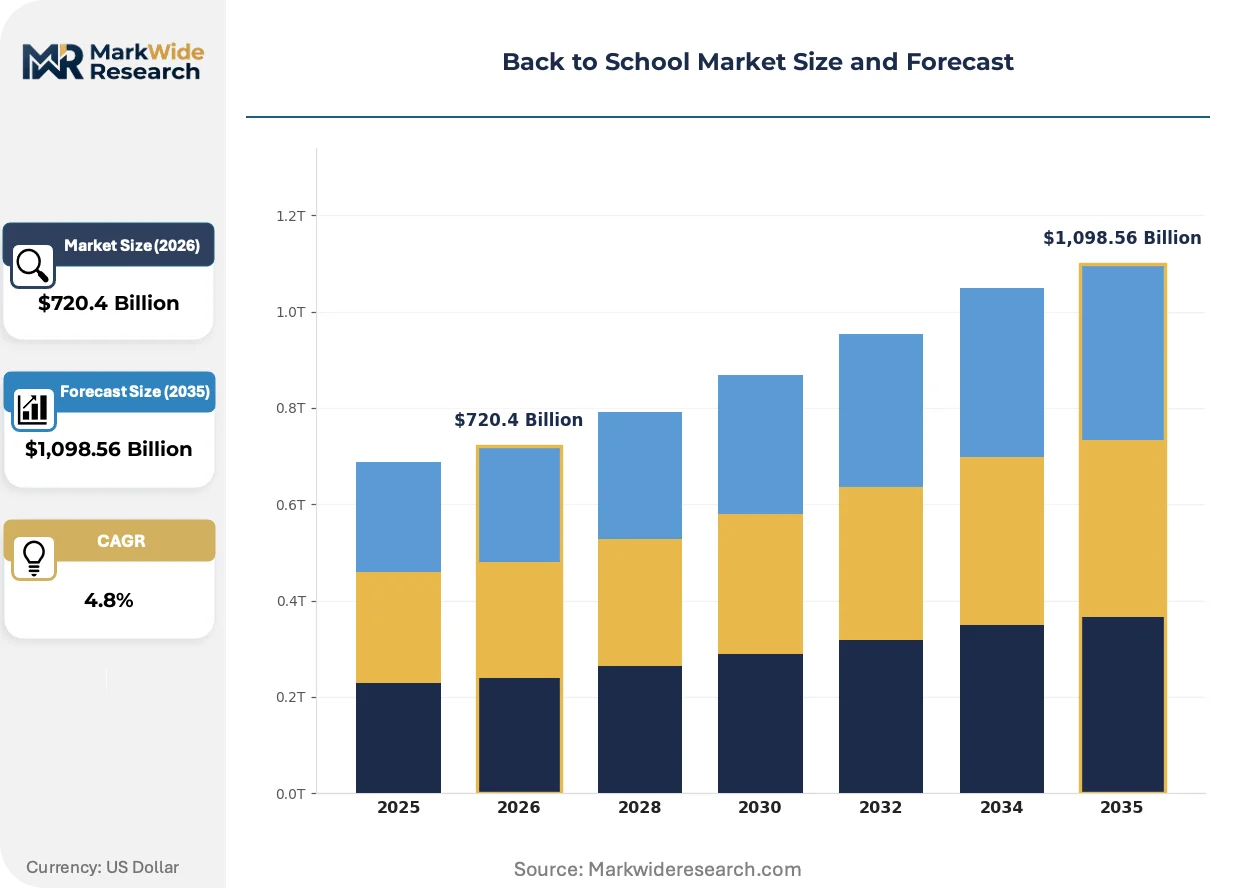
| Market Size in 2026 | $720.4 Billion |
| Market Size in 2035 | $1,098.56 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationery, Backpacks, Electronics, Apparel Customer Type: Parents, Students, Educators, Schools Price Tier: Budget, Mid-range, Premium, Luxury Distribution Channel: Online Retailers, Brick-and-Mortar, Wholesale, Discount Stores |
| Companies Covered | The ODP Corporation, Staples Inc., Amazon.com, Inc., Apple Inc., HP Inc., Acco Brands Corporation, Newell Brands Inc., Faber Castell AG, Walmart Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Back to School Market Strategic Shifts & Innovations
Innovation in the back to school market is coalescing around personalization through technology and sustainability in materials. Product development is increasingly focused on integrating smart features into traditional items and verifying the environmental footprint of the entire supply chain.
AI-powered adaptive learning software personalizes educational content for students based on their real-time performance and learning pace. This technology is being adopted by K-12 school districts and universities to provide tailored instruction and support diverse learning needs. The software-centric model is absorbing the function of static physical workbooks and supplemental materials, shifting value from disposable print goods to dynamic digital services.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) mandates extensive disclosure of environmental and supply chain data. This regulation compels manufacturers of all school products to provide verifiable proof of their sustainability claims, from paper sourcing to electronics manufacturing. Consequently, products with certified recycled content or transparent supply chains are gaining a distinct competitive advantage, particularly within the EU bloc.
A significant behavioral shift is the move from one-time product purchases toward service-based consumption, especially for technology. This trend disrupts the traditional seasonal sales cycle by replacing large, upfront expenditures with recurring subscription fees for software and device leasing programs. This model is most visible in the higher education segment for costly specialized applications and premium electronics.
Back to School Market Segmentation
Understanding the varied components of the back to school market allows stakeholders to target specific consumer needs and optimize product development. This granular breakdown reveals distinct purchasing behaviors and channel preferences across different product types and customer demographics. Effective segmentation is crucial for tailoring marketing strategies and supply chain operations within this dynamic sector.
Product Type:
The capital intensity varies significantly across product types, with advanced electronics requiring substantial investment in R&D and manufacturing infrastructure.
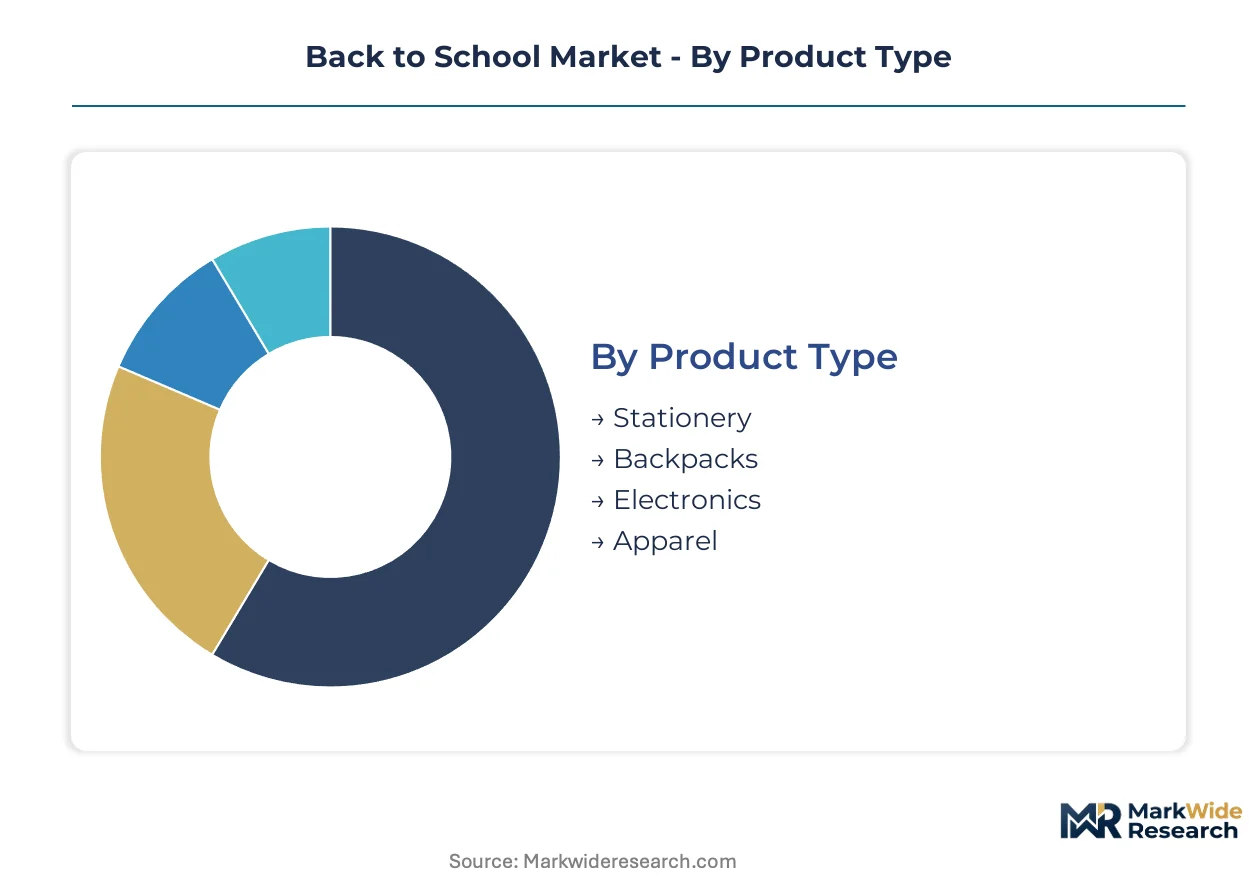
- Electronics:These include laptops, tablets, and specialized calculators designed for academic use, often featuring advanced processors and extended battery life. Demand for these high-specification devices is concentrating in higher education institutions, driven by digital curriculum adoption and AI-powered learning tools.
- Stationery:This category encompasses paper-based products, writing instruments, and organizational supplies, often manufactured with specific pulp blends and GSM weights. Procurement patterns for sustainable stationery are shifting in the European Union due to mandates like the CSRD, influencing material sourcing.
- Backpacks:Functional carriers for school supplies, ranging from basic designs to ergonomic and tech-integrated models.
- Apparel:Includes school uniforms and other student clothing items, often subject to specific institutional guidelines or seasonal trends.
Most installed capacity flows through Stationery. Expansion is steepest in Electronics.
Customer Type:
Customer types exhibit different cost sensitivities, with parents often balancing budget constraints against perceived product quality and durability.
- Students:This segment comprises the primary end-users of back to school products, ranging from K-12 to higher education, influencing demand for both basic supplies and advanced tech. Their purchasing decisions are increasingly influenced by peer trends and digital learning requirements.
- Parents:As primary purchasers for younger students, parents prioritize product safety, durability, and value for money, often responding to promotional offers. Their buying patterns are influenced by household budgets and school supply lists.
- Educators:Professionals requiring specific tools for teaching and classroom management, including specialized software and presentation equipment.
- Schools:Institutional buyers making bulk purchases for classroom supplies, technology infrastructure, and administrative needs, often through public procurement processes.
The Parents segment drives the largest volume of seasonal purchases, while demand from Students for advanced electronics demonstrates rapid growth.
Price Tier:
Supply concentration varies across price tiers, with budget and mid-range products often sourced from high-volume manufacturing hubs in Asia.
- Budget:Products designed for affordability, often mass-produced with cost-effective materials and minimal features to meet basic functional requirements. This tier sees significant volume demand from price-sensitive consumers and large-scale government education initiatives in India.
- Mid-range:These items offer a balance of quality, features, and price, appealing to a broad consumer base seeking reliable performance without premium costs. Consumer preference for durable goods in established markets supports consistent demand in this segment.
- Premium:Characterized by higher quality materials, enhanced features, brand reputation, and often sustainable or ethical sourcing credentials.
- Luxury:Niche products distinguished by exclusive designs, superior craftsmanship, and high-end materials, targeting affluent consumers with unique aesthetic preferences.
Volume sales are dominated by the Budget price tier, while the Premium segment captures increasing value due to sustainability mandates.
Distribution Channel:
The maturity of distribution channels ranges from long-established brick-and-mortar networks to rapidly evolving online retail platforms.
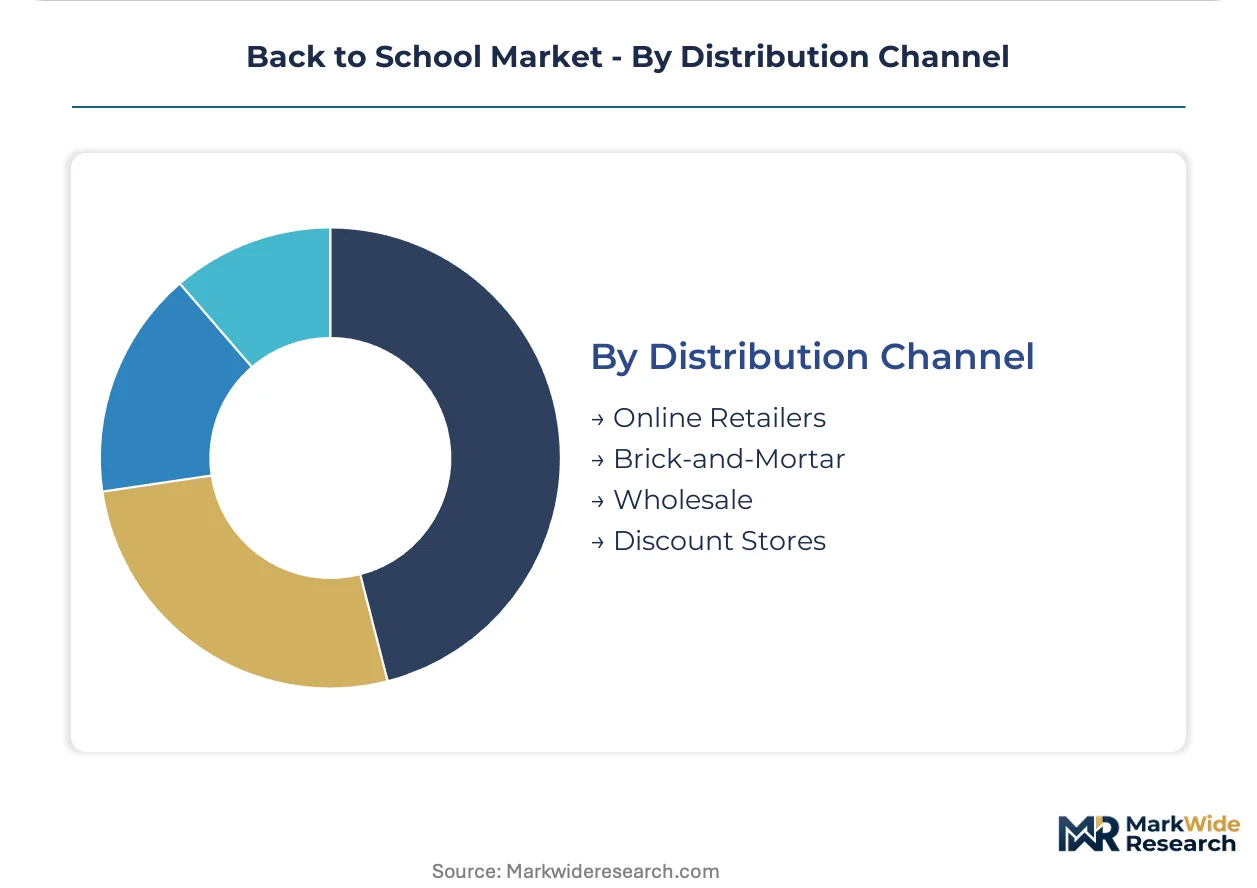
- Online Retailers:E-commerce platforms offering extensive product selections, competitive pricing, and convenience through direct-to-consumer shipping. This channel is gaining significant share for higher-priced technology items and serves students in remote areas.
- Brick-and-Mortar:Traditional physical stores including department stores, big-box retailers, and specialty shops, providing immediate access and tactile product evaluation. Walmart Inc. leverages its global presence in this channel to serve budget-conscious consumers.
- Wholesale:Channels supplying products in bulk to educational institutions, smaller retailers, or corporate clients, often involving large volume transactions.
- Discount Stores:Retailers focusing on low prices and promotional deals, attracting price-sensitive buyers for essential school supplies.
Brick-and-Mortar stores maintain a foundational role in overall sales volume, but Online Retailers are capturing a disproportionate share of growth, particularly for technology products.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The back to school market’s foundational demand originated with the establishment of widespread public education systems, requiring standardized supplies for students. Today, regional dynamics are shaped by varying economic conditions, digital infrastructure development, and diverse regulatory environments governing product safety and sustainability.
United States
Demand for advanced electronics and sustainable products drives market activity across American states. The US Consumer Product Safety Commission (CPSC) sets stringent safety standards for school supplies, influencing manufacturing practices. Silicon Valley and other tech hubs concentrate innovation in educational software, boosting demand for compatible devices.
India
Government education initiatives significantly expand public procurement of essential school supplies in India. The Bureau of Indian Standards (BIS) regulates product quality and safety for a wide range of goods. Major metropolitan areas like Mumbai and Delhi observe increased demand for digital learning tools as educational infrastructure improves.
Germany
Consumer and institutional buyer preference for eco-friendly products is strong in Germany, aligning with EU sustainability goals. The European Union's REACH regulation restricts hazardous chemicals in products, impacting material sourcing for manufacturers. Industrial regions like North Rhine-Westphalia are adapting production to meet stringent environmental certifications.
China
China's vast student population drives immense volume demand for both traditional stationery and digital learning devices. GB standards establish national product safety and quality requirements across all consumer goods. Manufacturing centers in the Yangtze River Delta produce a significant share of global school supplies and electronics.
United Kingdom
Digital curriculum adoption in higher education institutions fuels demand for high-specification laptops and tablets across the United Kingdom. The UK's Competition and Markets Authority (CMA) scrutinizes marketing claims, particularly regarding environmental benefits. London and other major university cities see concentrated demand for premium technology and educational software.
Back to School Market Key Industry Players
Capital-heavy producers of physical goods compete with asset-light designers and distributors of digital learning tools. The market structure exhibits a tiered consolidation, with large retailers and tech giants dominating distribution, while specialized manufacturers focus on niche product categories. Strategic partnerships between hardware providers and educational software developers represent a dominant competitive move.
Within the retail distribution segment, Amazon.com, Inc. leverages its expansive logistics network to offer a broad selection of products. Walmart Inc. controls a significant share of the budget-friendly segment through its extensive global brick-and-mortar presence. Newell Brands Inc. occupies a position as a specialized manufacturer, anchoring its market position through a portfolio of established stationery and writing instrument brands.
| Leading Market Players |
|---|
| The ODP Corporation |
| Staples Inc. |
| Amazon.com, Inc. |
| Apple Inc. |
| HP Inc. |
| Acco Brands Corporation |
| Newell Brands Inc. |
| Faber Castell AG |
| Walmart Inc. |
| Others |
Cost & Logistics Intelligence
European Union's CSRD mandates for verifiable eco-credentials are shifting product requirements, forcing manufacturers to invest in sustainable sourcing and production. These rising compliance costs directly influence pricing strategies across the supply chain.
Pricing Analysis
A three-tier pricing structure differentiates products across budget, mid-range, and premium segments in the back to school market. Price differentiation stems from brand reputation, verifiable sustainability certifications like FSC for paper, and the integration of advanced electronic features. Cost compression in the budget segment intensifies due to high-volume demand from government education initiatives in India. Parents often exhibit high price sensitivity for essential supplies, contrasting with students in higher education who prioritize premium electronics.
Supply Chain Analysis
Domestic content mandates in certain regions are beginning to influence sourcing decisions for school supplies. Supply concentration for electronics manufacturing centers in China and Southeast Asia, while paper pulp production for stationery draws from global sources. The market relies on key inputs like semiconductors for devices and various plastics for accessories. Commodity price volatility, particularly for paper pulp and semiconductors, presents a structural risk. Distribution channels integrate online retailers and extensive brick-and-mortar networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The back to school market presents a geographic-arbitrage opportunity, as manufacturing costs in Southeast Asia remain significantly lower than compliance-heavy production in the European Union. This cost differential creates distinct market entry and supply chain optimization pathways.
For Market Incumbents:Deploy strategic R&D into circular economy product design to counter digital substitution threats from AI-powered software and greenwashing scrutiny. Strengthen logistics networks in emerging markets like India to leverage government procurement programs and increase volume sales. Investing in verifiable sustainability certifications for stationery and electronics can defend premium segment share against new entrants.
For New Entrants and Emerging Players:Direct-to-consumer online platforms offer a viable route to target underpenetrated markets in Southeast Asia and Africa. Develop subscription-based models for digital learning tools and device-as-a-service programs, particularly appealing to higher education students seeking flexible access. Focus on eco-friendly niche products with transparent supply chains to capture value in environmentally conscious segments.
For Investors and Strategic Acquirers:Asymmetric upside sits with specialized manufacturers of sustainable materials and innovative AI-powered education software providers. Long-term viability in this market hinges on companies capable of navigating both digital transformation and stringent sustainability mandates over the next decade. An inflection indicator to watch is the increasing volume of public procurement tenders specifying certified green products in Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Subscription Service Launch | Captures recurring revenue from higher education students for software bundles. |
| Circular Design Integration | Aligns product development with EU Green Deal policies for repairability. |
| Emerging Market Expansion | Taps into rising educational enrollment rates in Southeast Asia. |
| AI-Powered Tool Partnership | Enhances digital learning offerings for K-12 and university students. |
| Sustainable Sourcing Certification | Verifies eco-credentials, meeting CSRD requirements in Europe. |
Research Approach
Direct dialogue with retail procurement managers, education technology developers, stationery manufacturers, and government education officials provided qualitative insights. This primary research was cross-referenced with extensive secondary data from sources including US CPSC reports, EU REACH guidelines, BIS standards, and company annual reports. Both bottom-up and top-down approaches were employed to triangulate market size and segment forecasts.
A bottom-up analytical framework, complemented by top-down validation, formed the basis of market projections across the analysis window. Segmentation dimensions modeled included product type, customer type, price tier, distribution channel, and regional regulatory compliance. Compound annual growth rates were derived from historical data, expert interviews, and macroeconomic indicators. Student enrollment rates and digital curriculum adoption rates were critical forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for AI-powered learning tools would alter the outlook. Forecasts reflect assumptions regarding raw material price stability and consistent regulatory enforcement. Unforeseen shifts in global trade policies or sustainability mandates represent key risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
Qatar Private K12 Education Market