
 Virtual Schools Market | 2026-2036
Virtual Schools Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Schools Market Intelligence
The expansion of cloud infrastructure in emerging economies is repositioning the competitive landscape for virtual school providers. Coursera leverages university partnerships to offer higher education credentials, creating a strong brand in the post-secondary space. Kaplan specializes in test preparation and professional education modules targeted at adult learners and career changers. Meanwhile, IXL Learning focuses on the K-12 segment with its adaptive learning technology and curriculum-aligned content.
Virtual schools are educational institutions that deliver instruction primarily through internet-based platforms. These models utilize Learning Management Systems for course delivery and video conferencing for live interaction, providing flexible access to accredited curricula. The higher education and adult education segments command significant value due to demand for professional development and reskilling. While asynchronous learning offers scalability, synchronous and blended delivery modes are expanding to enhance student engagement and improve learning outcomes.
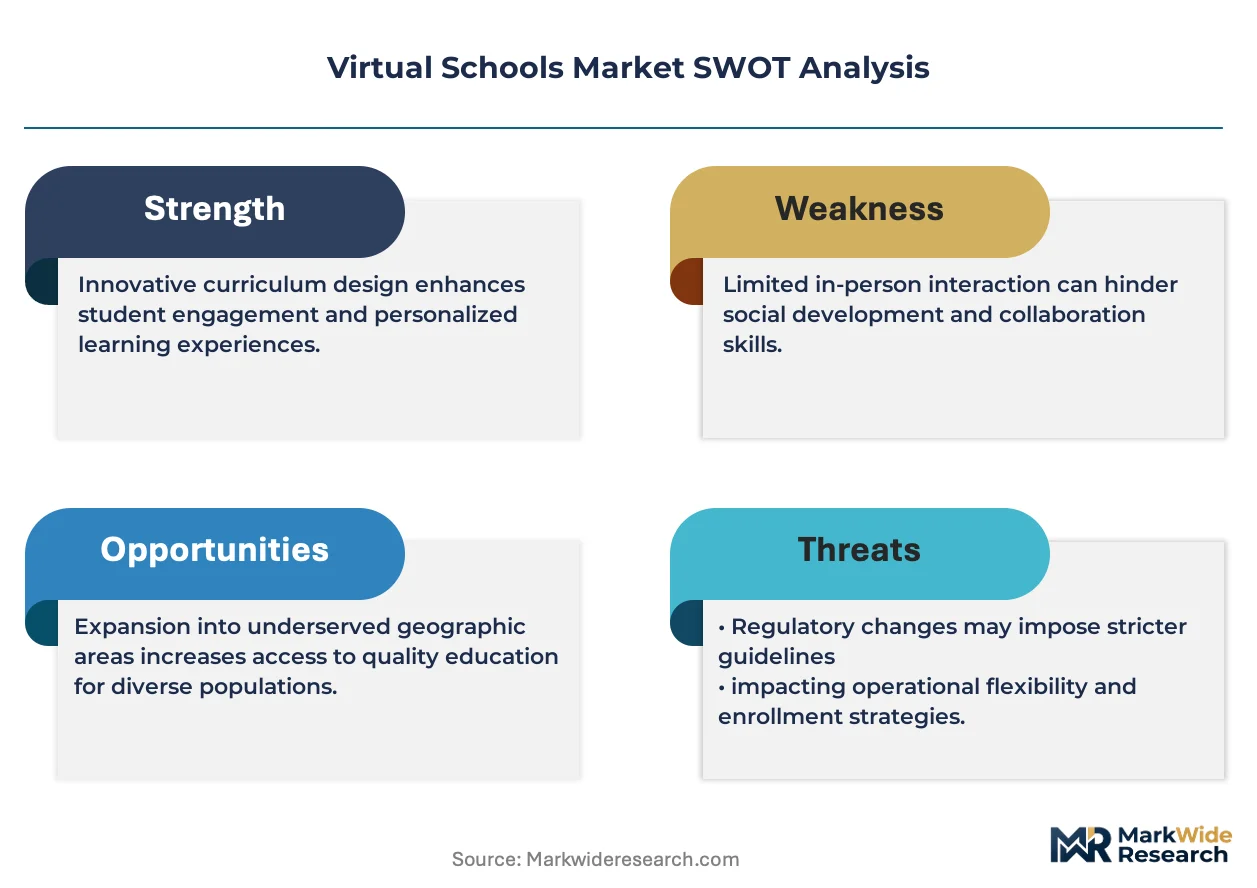
Regulatory oversight is fragmented, with bodies like the US Department of Education influencing accreditation and funding, while the EU's GDPR governs student data privacy. These frameworks directly impact market access and the design of learning platforms, requiring compliance for data handling. Providers must navigate the strategic choice between developing proprietary, high-margin content and leveraging open educational resources to achieve scale.

Market Dynamics
The central dynamic in the virtual schools market is the tension between scalable, standardized content delivery and the growing demand for personalized, engaging learning. This is driven by advancements in adaptive AI technology and evolving pedagogical expectations from educators, parents, and corporate clients.
Growth Catalysts
- Government Initiatives:India's National Education Policy is actively promoting digital learning and building out public digital infrastructure, creating a massive, state-supported addressable market for virtual school platforms and content providers.
- Corporate Demand for Upskilling:A persistent need for continuous professional development fuels corporate adoption of flexible virtual training modules, particularly within the technology and finance sectors that require constant reskilling.
- Advancements in EdTech:The integration of adaptive learning algorithms and gamification elements into Learning Management Systems enhances student engagement, personalizes educational pathways, and improves retention rates.
Market Restraints
- The Digital Divide:Inequitable access to reliable high-speed internet and appropriate computing devices in rural areas and low-income households globally limits market reach and reinforces educational disparities.
- Regulatory Fragmentation:The absence of uniform accreditation and quality assurance standards across different states in the US and member countries of the EU creates significant compliance burdens and market entry barriers.
- Teacher Training Deficits:A substantial portion of the educator workforce lacks the specialized pedagogical training and technical proficiency required to deliver instruction effectively in a fully virtual environment, impacting educational quality.
Strategic Opportunities
- Specialized Niche Verticals:A significant opportunity exists in creating dedicated virtual schools for underserved student populations, including those with special educational needs, gifted learners, or students pursuing specialized vocational training.
- Blended Learning Models:Developing hybrid offerings that combine online instruction with periodic, in-person sessions at local partner facilities can address concerns about socialization and appeal to a broader segment of parents and learners.
- AI-Powered Tutoring:The development and integration of AI-driven personal tutors within virtual school platforms represents a major area for innovation, offering enhanced student support and creating new premium service tiers.
Industry Challenges
- Student Data Privacy Compliance:Adhering to stringent data protection regulations like the EU's GDPR and various US state privacy laws requires continuous investment in secure platform architecture, legal counsel, and transparent data governance.
- Maintaining Student Engagement:Combating student disengagement and screen fatigue in fully remote learning environments remains a persistent operational challenge, demanding innovative instructional design and proactive student support systems.
- Content Licensing Complexity:Navigating the intricate and often costly landscape of digital content rights and licensing agreements with educational publishers creates significant operational overhead and can slow curriculum development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Schools Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $36.13 Billion |
| CAGR (2026 – 2036) | 15.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Education Level: Primary School, Secondary School, Higher Education, Adult Education Technology Platform: Learning Management System, Video Conferencing, Interactive Whiteboards, Gamification Tools Delivery Mode: Asynchronous Learning, Synchronous Learning, Blended Learning, Self-Paced Modules End User: Students, Educators, Administrators, Corporate Trainees |
| Companies Covered | Kaplan, Rootstrap, Coursera, Vention, Brainhub, IXL Learning, Vrinsoft Technology, Aristek Systems, Imagine Edgenuity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Schools Market Strategic Shifts & Innovations
Evolution in the market is defined by a push towards more immersive and data-driven educational experiences. This shift transforms passive content consumption into active, personalized learning journeys, driven by technological integration and new pedagogical models.
Adaptive learning technology utilizes algorithms to adjust curriculum difficulty and content in real-time based on individual student performance. K-12 and corporate training segments are adopting this technology to create personalized learning paths at scale. This AI-driven personalization is converging with immersive technologies like AR and VR to create highly effective simulated labs and training environments, particularly for STEM and technical subjects.
The European Union's AI Act establishes risk-based requirements for artificial intelligence systems, including those deployed in the education sector. This regulation mandates transparency, robust data governance, and human oversight for AI tools used in student assessment and adaptive learning platforms. EdTech providers serving the EU are most affected, now re-engineering their products to demonstrate compliance and ethical AI principles.
A clear behavioral shift is occurring from purchasing standalone courses to subscribing to comprehensive, credential-focused learning pathways. This unbundling of traditional degrees allows learners in higher education and professional development to acquire verifiable micro-credentials and stackable certificates. This trend is most prominent in North America and Europe, where career-focused individuals seek flexible, skill-based qualifications for advancement.
Virtual Schools Market Segmentation

The Virtual Schools Market exhibits diverse operational models and target audiences, necessitating a clear segmentation to understand its varied growth trajectories. This granular analysis illuminates distinct value propositions and competitive dynamics across different educational levels, technological implementations, delivery methods, and end-user groups.
Education Level:
What differentiates buyers in this category is their stage of academic or professional development and corresponding learning objectives.
- Primary School:This segment encompasses virtual learning solutions for students typically aged 5-11, focusing on foundational literacy, numeracy, and early cognitive development. Demand concentrates in regions like India, where government initiatives support digital education infrastructure for young learners.
- Secondary School:Virtual platforms for students aged 12-18 provide accredited curricula, often including advanced placement courses and college preparatory programs. The need for flexible scheduling and diverse course offerings drives adoption in urban areas across North America.
- Higher Education:This segment includes online degree programs, certification courses, and specialized professional development modules offered by universities and colleges. Learners in North America and Europe seek stackable micro-credentials for career advancement and reskilling, driving significant value.
- Adult Education:Virtual schools catering to adult learners focus on vocational training, continuing professional education, and personal enrichment. Corporate demand for upskilling in technology and finance sectors fuels the adoption of flexible training modules globally.
Volume sits with Primary School; growth tilts toward Adult Education.
Technology Platform:
The application and integration capabilities of technology platforms define their utility for virtual school providers.
- Learning Management System:These comprehensive software suites manage course content, student enrollment, assignments, and communication, forming the backbone of most virtual learning environments. Scalability and administrative efficiency are critical for large educational institutions.
- Video Conferencing:Tools enabling real-time, synchronous interaction between educators and students are essential for live classes, virtual office hours, and collaborative projects. Enhanced student engagement and immediate feedback drive its expansion across all education levels.
- Interactive Whiteboards:Digital whiteboards facilitate dynamic content presentation, collaborative problem-solving, and visual learning experiences in virtual classrooms. These tools enhance engagement for K-12 students in blended learning models.
- Gamification Tools:Integrating game-like elements such as points, badges, and leaderboards into educational content aims to boost student motivation and retention. Corporate training programs utilize these tools to improve engagement in professional development.
The adoption of Learning Management System drives market efficiency, while Video Conferencing enhances interactive experiences.
Delivery Mode:
Customer type preferences and learning styles dictate the choice of delivery mode for virtual education.
- Asynchronous Learning:This mode allows students to access course materials and complete assignments at their own pace, without real-time interaction requirements. Its inherent scalability makes it suitable for large-scale corporate training programs and global outreach.
- Synchronous Learning:Live, real-time instruction and interaction via video conferencing or virtual classrooms characterize this delivery mode. It addresses concerns about student isolation and improves learning outcomes through immediate feedback and engagement.
- Blended Learning:Hybrid models combine online instruction with periodic in-person sessions, offering a balance of flexibility and social interaction. Parents seeking a comprehensive educational experience for K-12 students increasingly favor these models.
- Self-Paced Modules:These highly flexible units allow learners to progress through content independently, often without fixed deadlines or direct instructor interaction. Professional development learners value this approach for its adaptability to busy schedules.
Flexibility remains a core driver for Asynchronous Learning, with Blended Learning gaining traction for deeper engagement.
End User:
The margin profiles associated with different end-user segments influence strategic investments and content development.
- Students:This broad category includes K-12, higher education, and vocational students directly consuming virtual educational content and services. The K-12 segment, served by providers like IXL Learning, demands curriculum-aligned content and adaptive learning technologies.
- Educators:Virtual school platforms provide tools and resources for teachers, enabling content creation, student assessment, and classroom management. Professional development for educators in virtual pedagogy is a key supporting service.
- Administrators:School and district administrators utilize virtual school platforms for operational management, student data tracking, and compliance reporting. Efficiency and robust data governance are critical for these stakeholders.
- Corporate Trainees:Employees undertaking professional development, reskilling, or compliance training through virtual platforms constitute this segment. The technology and finance sectors consistently demand flexible, outcome-based virtual training modules.
Revenue generation concentrates around Students, with Corporate Trainees representing the fastest-growing trajectory.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India anchors the global virtual schools market, demonstrating substantial growth potential driven by digital infrastructure expansion. This dynamic landscape reflects varying regulatory environments and educational priorities across key geographies. Each region contributes distinct demand drivers and policy frameworks shaping virtual learning adoption.
India
Government initiatives and a vast student population drive demand for digital education platforms. India's National Education Policy actively promotes online learning and public digital infrastructure. EdTech clusters in Bangalore and Hyderabad are developing localized virtual school solutions to meet this expanding market.
United States
Demand for higher education credentials and flexible professional development fuels virtual school expansion. The US Department of Education influences accreditation standards and funding for online programs. Major university hubs in Boston and California's Silicon Valley lead innovation in EdTech platforms.
Germany
Corporate upskilling and professional development modules generate significant demand for virtual learning. The EU AI Act and GDPR mandate robust data governance for educational platforms operating here. Berlin and Munich serve as growing centers for EdTech startups and corporate training providers.
United Kingdom
Learners seek stackable micro-credentials and flexible skill-based qualifications for career advancement. GDPR compliance remains a critical factor for EdTech providers in this region. London and Manchester host numerous online learning providers and university extension programs.
Canada
The need for flexible scheduling and diverse course offerings drives secondary school adoption of virtual platforms. Provincial education ministries set quality assurance standards for accredited online curricula. Toronto and Vancouver are emerging as innovation hubs for Canadian EdTech companies.
Virtual Schools Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niche verticals and AI-powered tutoring solutions. The virtual schools market exhibits a tiered structure, with providers differentiating through content depth or technological integration. Strategic partnerships with educational institutions and technology licensing agreements are common competitive moves.
Specialists in distinct educational segments include Kaplan, which exemplifies a focus on test preparation and professional education for adult learners. Coursera represents a prominent platform for higher education credentials through extensive university partnerships. IXL Learning sits within the K-12 segment, anchoring its offering around adaptive learning technology and curriculum-aligned content.
| Leading Market Players |
|---|
| Kaplan |
| Rootstrap |
| Coursera |
| Vention |
| Brainhub |
| IXL Learning |
| Vrinsoft Technology |
| Aristek Systems |
| Imagine Edgenuity |
| Others |
Cost & Logistics Intelligence
Venture-backed EdTech startups often drive aggressive pricing strategies to capture market share, influencing the broader supply of innovative learning solutions. This dynamic interplay shapes both content accessibility and market competitiveness across various educational segments.
Pricing Analysis
Service bundling often dictates the perceived value in virtual education, with comprehensive packages including live tutoring and accredited certification commanding higher prices. The dominant pricing model is subscription-based, frequently structured in tiered premium, standard, and basic levels. Price differentiation stems from content accreditation and the level of personalized instructor support offered, while pricing softness reflects the proliferation of free open educational resources. K-12 parents exhibit higher price sensitivity compared to corporate trainees seeking career-critical certifications.
Supply Chain Analysis
Accreditation and qualification gating significantly influence the supply chain for virtual schools, ensuring educational rigor and market acceptance. Content development and platform innovation concentrate in the United States, India, and the United Kingdom, relying heavily on skilled instructional designers, software developers, and licensed educational content. Content licensing complexity represents a structural risk, creating significant operational overhead for providers. Distribution runs through direct-to-consumer channels, corporate HR departments, and government education ministries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The virtual schools market faces a supply-constrained future, primarily due to the scarcity of specialized pedagogical talent capable of effective online instruction. This capacity bottleneck props up pricing for high-quality, engaging virtual learning experiences.
For Market Incumbents: Deepen existing university partnerships to co-develop accredited micro-credentials, countering the threat from unaccredited, low-cost course providers. Invest significantly in AI-powered adaptive learning platforms to enhance student engagement and personalize educational pathways. Consolidate market position through strategic acquisitions of niche EdTech startups specializing in immersive technologies. This vertical integration into content creation and technology development strengthens competitive moats.
For New Entrants and Emerging Players: Begin with specialized niche verticals like vocational training for green energy jobs or platforms for students with specific learning disabilities. The K-12 segment in underserved rural areas of India presents a penetrable geography due to government support and digital infrastructure buildout. Focus on a freemium model for foundational content, converting users to premium tiers for personalized AI tutoring and accredited certifications. This approach builds trust and demonstrates value.
For Investors and Strategic Acquirers: Widespread government mandates for digital literacy programs is the leading indicator that validates the long-term viability of virtual education over the next decade. Target acquisition archetypes include AI-driven assessment platforms and content providers specializing in STEM subjects for K-12 and corporate upskilling. A significant shift in regulatory frameworks towards global accreditation standards would signal accelerated market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI-Powered Adaptive Learning | Enhances student engagement and personalizes educational pathways for K-12 students. |
| Form University Micro-Credential Partnerships | Provides flexible, verifiable qualifications for adult learners seeking career advancement. |
| Expand Blended Learning Models | Addresses socialization concerns and broadens appeal to K-12 parents. |
| Secure Global Content Licensing | Reduces operational overhead and accelerates curriculum development for international markets. |
| Target Specialized Vocational Verticals | Captures underserved student populations requiring specific skill-based training. |
Research Approach
Government education policy documents, university partnership agreements, and EdTech funding reports formed the secondary backbone for this analysis. This was combined with primary interviews involving virtual school administrators, corporate training managers, instructional technology specialists, and EdTech founders. The approach triangulated bottom-up market sizing with top-down validation, ensuring comprehensive data coverage and accuracy.
Historical trendline analysis established the foundational growth trajectory across the analysis window, informing the quantitative model. The framework segmented the market by education level, technology platform, delivery mode, and end-user, alongside regional adoption patterns. Compound Annual Growth Rates were derived from an assessment of demand drivers and market restraints. Forecast inputs included projected internet penetration rates and government digital education spending.
Regulatory shifts, technological breakthroughs in AI, and unforeseen economic downturns are the dominant revision risks to these forecasts. The projections reflect assumptions about sustained EdTech investment and evolving pedagogical models. A model refresh is warranted upon material change in global digital education policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Game-Based Learning Market
Educational Technology (EdTech)
SETM Education Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Global Social Learning Platforms Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Global Smart Learning Market