
 Global IoT in Education Market | 2026-2036
Global IoT in Education Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Education Market Foresight
The EU Green Deal's digital-education sustainability targets are recalibrating procurement criteria across European institutions, forcing vendors to certify energy-efficient device fleets. Cisco Systems Inc. leverages its networking hardware dominance to anchor campus-wide IoT backbone contracts. IBM Corporation competes through Watson IoT analytics platforms that specialize in predictive maintenance for connected classroom equipment. Microsoft Corporation controls the productivity layer, extending Azure IoT integration into learning management systems.
IoT in education denotes networked sensor, actuator, and computing ecosystems deployed across academic institutions to automate environmental control, track asset utilization, and generate real-time behavioral analytics for instructional optimization. These systems typically operate on low-power wireless protocols such as Zigbee, LoRaWAN, or BLE mesh, with edge nodes processing latency-sensitive commands locally before cloud synchronization. Cloud-based deployment leads solution architecture, as elastic compute resources accommodate unpredictable enrollment spikes and seasonal usage patterns. Smart classrooms command the largest solution offering category, though campus security systems carry higher per-unit margins due to regulatory compliance complexity and recurring software licensing.
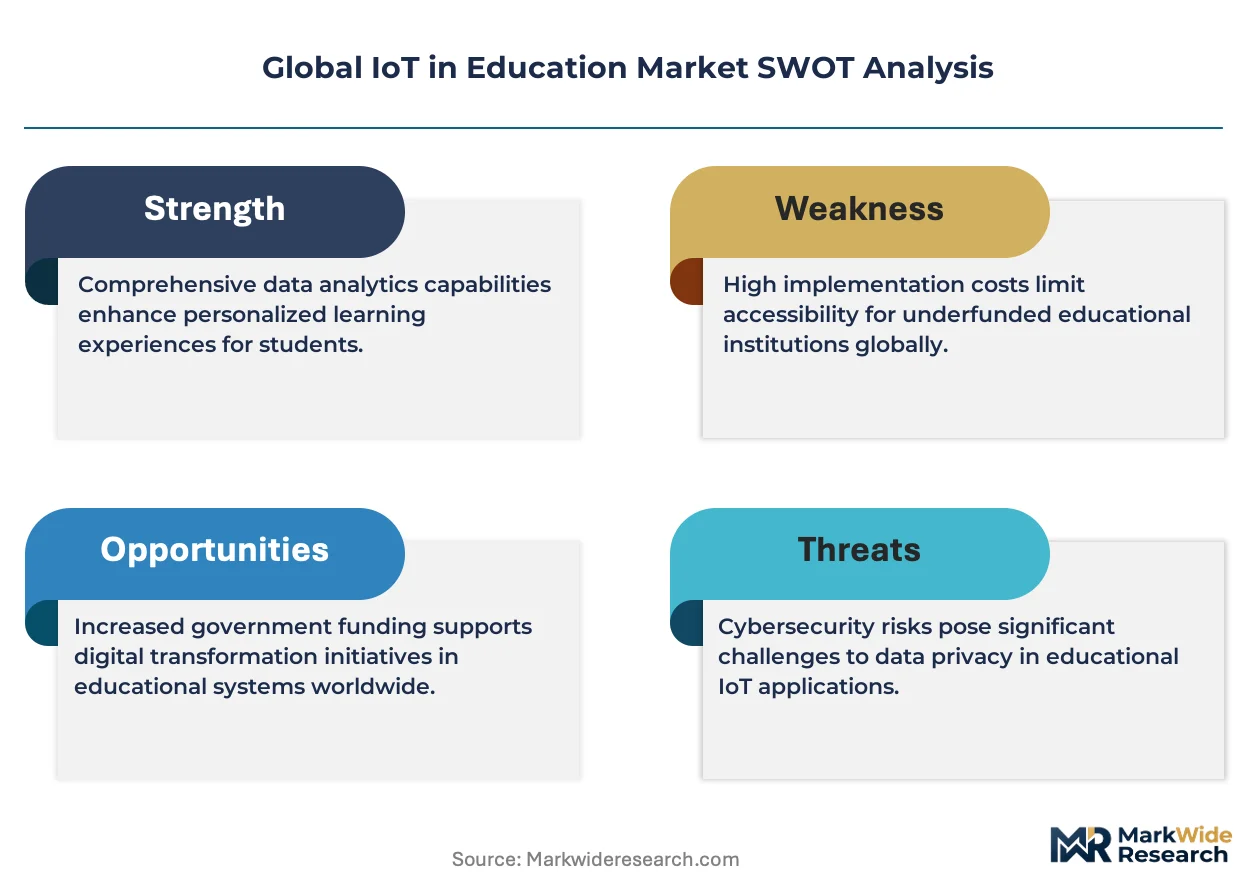
The U.S. Federal Communications Commission's E-Rate program subsidizes broadband and internal connections for schools and libraries, directly expanding addressable hardware volumes. China's Ministry of Education mandates national smart campus standards through GB specifications, while India's BIS certification requirements for electronic equipment filter import competition. Stakeholders must monitor divergent data localization rules across jurisdictions, as student information governance increasingly determines vendor eligibility and contract renewal terms.
Market Dynamics
The EU AI Act's risk-based classification system for educational technologies is forcing vendors to reengineer product architectures and compliance documentation, compressing development timelines while expanding legal review costs across the supply chain.
Growth Catalysts
- E-Rate Program Expansion:The U.S. FCC's connectivity subsidies directly expand hardware procurement volumes for K-12 institutions modernizing infrastructure.
- GB Standard Mandates:China's Ministry of Education enforces national smart campus specifications that standardize interoperability and accelerate replacement cycles.
- BLE Mesh Protocols:Low-power wireless networking enables battery-operated sensor deployments without electrical retrofitting, cutting installation costs for aging buildings.
Market Restraints
- Silicon Supply Concentration:Edge processor fabrication concentrates in Taiwan and South Korea, exposing vendors to geopolitical disruption and allocation delays.
- GDPR Compliance Friction:Student biometric data collection triggers enhanced consent frameworks and data protection impact assessments across European deployments.
- Copper and Lithium Volatility:Battery chemistry and wiring material costs fluctuate with commodity markets, squeezing hardware margins on fixed-price contracts.
Strategic Opportunities
- India BIS Certification Gap:Import filtering through Bureau of Indian Standards requirements creates protected domestic market share for certified local assembly partners.
- AI-Edge Convergence:On-device inference chips combined with cloud training pipelines enable real-time behavioral analytics without latency penalties.
- EU Green Deal Procurement:Digital-education sustainability targets recalibrate RFP scoring to prioritize energy-efficient device fleets and circular design.
Industry Challenges
- Zigbee-LoRaWAN Interoperability:Fragmented wireless standards force vendors to maintain multiple firmware branches and certification tracks.
- Legacy LMS Integration:Decades-old student information systems lack API maturity, requiring expensive middleware development for data synchronization.
- Edge AI Talent Scarcity:Embedded machine learning engineering sits at the intersection of hardware design and data science, with limited trained labor supply.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Education Market |
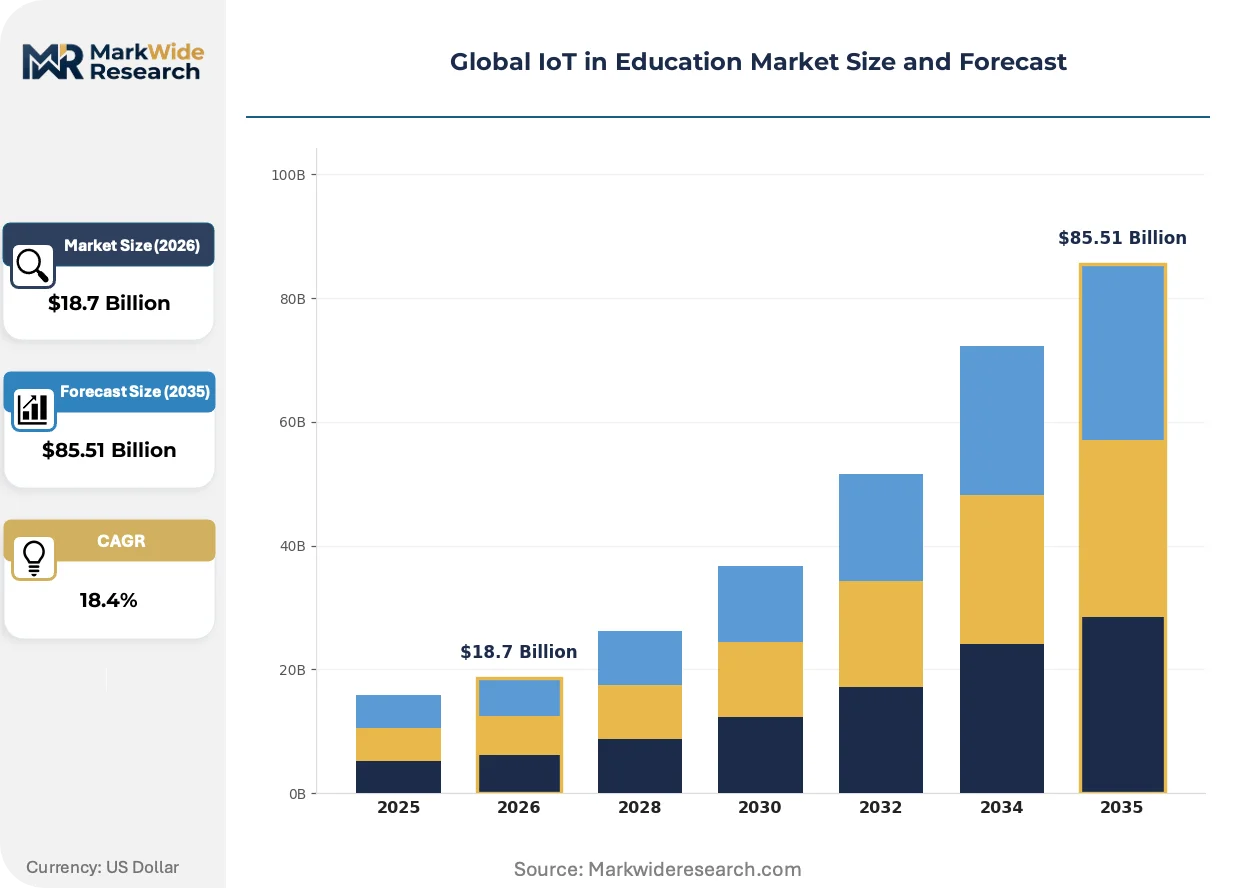
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Edge Computing Solution Offering: Smart Classrooms, Student Monitoring, Campus Security, Resource Management, Attendance Tracking Use Case: Interactive Learning, Virtual Labs, E-Assessment, Remote Tutoring, Skill Development End User: Primary Schools, Higher Education, Vocational Training Centers, Corporate Training Facilities |
| Companies Covered | Cisco Systems Inc., IBM Corporation, Microsoft Corporation, Google LLC, Huawei Technologies Co., Ltd., Intel Corporation, Oracle Corporation, Amazon Web Services, Inc., SAP SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Education Market Shifts & Advancements
Architectural choices in connectivity protocols and data governance frameworks are splitting vendor strategies between centralized cloud analytics and distributed edge intelligence, with compliance requirements increasingly determining technical roadmaps.
LoRaWAN is overtaking proprietary RF solutions for campus-wide environmental monitoring. University facilities managers in Germany and the Netherlands are standardizing on unlicensed spectrum deployments for HVAC and occupancy tracking. This shift is compressing recurring licensing revenue for incumbent building automation vendors.
REACH substance restrictions on persistent organic pollutants are phasing out certain flame-retardant plastics in classroom device housings. Manufacturers serving European institutions must reformulate enclosures or face market exclusion. Component suppliers in Poland and Hungary are accelerating certification for halogen-free alternatives to maintain contract eligibility.
Subscription-based hardware provisioning is displacing capital purchase models in U.S. public school districts facing budget volatility. California and Texas education agencies now structure multi-year service agreements bundling devices, connectivity, and analytics. This compresses upfront revenue recognition while extending customer lifetime value for vendors with financing capabilities.
Global IoT in Education Market Segmentation
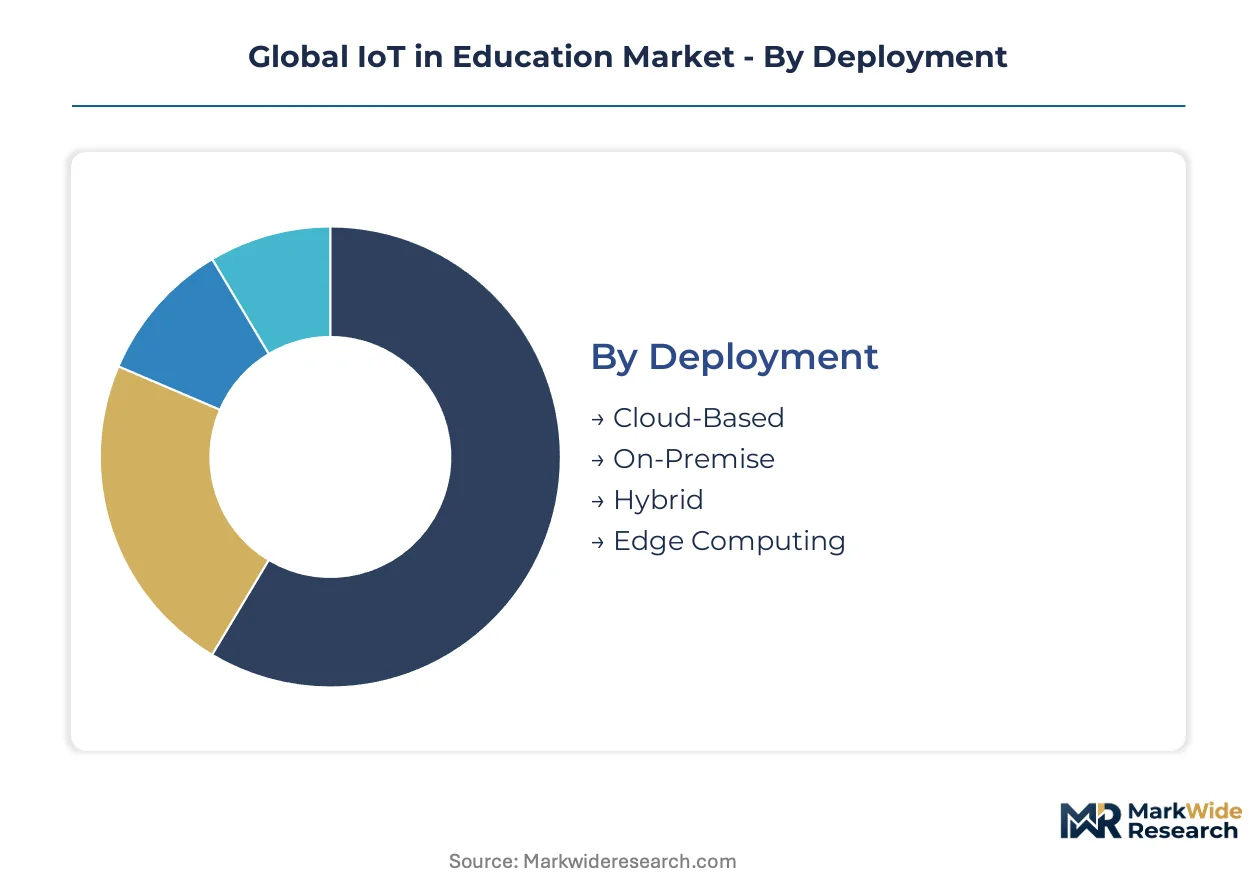
Architectural choices in deployment models determine capital intensity and recurring revenue profiles for vendors across education IoT. Solution offerings diverge sharply on margin structure, with hardware-centric segments carrying lower recurring attach rates than software-heavy alternatives.
Deployment:
Cloud-native architectures dominate procurement specifications as elastic compute accommodates enrollment volatility and seasonal usage swings.
- Cloud-Based:Elastic infrastructure provisions accommodate unpredictable enrollment spikes and summer downtime cycles. United States K-12 districts prioritize this model under E-Rate subsidy frameworks that favor operational expenditure over capital outlays.
- On-Premise:Institutions with stringent data localization mandates maintain physical server control for student biometric archives. Germany's federal states enforce this architecture for facial recognition attendance systems under GDPR Article 9 heightened consent requirements.
- Hybrid:Split workloads process latency-sensitive environmental controls locally while archiving analytics in distributed cloud nodes. This balances real-time HVAC responsiveness with long-term predictive maintenance data lakes.
- Edge Computing:On-device inference chips enable millisecond-response behavioral analytics without round-trip latency to centralized servers. Battery-powered BLE mesh sensors in aging Japanese school buildings deploy this architecture to avoid electrical retrofitting costs.
Cloud-Based leads on scale; Edge Computing leads on momentum.
Solution Offering:
Margin profiles split between commoditized hardware bundles and compliance-heavy security systems with recurring software licensing.
- Smart Classrooms:Integrated projector, sensor, and actuator ecosystems automate lighting, climate, and display management based on occupancy detection. India's BIS certification requirements for electronic equipment filter import competition, protecting domestic assembly partners in this highest-volume category.
- Campus Security:Video analytics, access control, and emergency notification systems carry elevated per-unit margins due to GDPR Article 35 data protection impact assessment requirements across European deployments.
- Student Monitoring:Wearable and environmental sensors track location, posture, and engagement metrics for instructional optimization. China's GB standard mandates accelerate interoperability certification for biometric data collection devices.
- Resource Management:Asset tracking for laboratory equipment, library inventory, and fleet vehicles reduces replacement procurement through utilization analytics. Dutch universities standardize on LoRaWAN protocols for this application to compress licensing costs.
- Attendance Tracking:RFID, facial recognition, and mobile beacon systems automate roll-call processes. California school districts structure multi-year service agreements bundling these devices with connectivity under subscription provisioning models.
Smart Classrooms dominates procurement volumes; Campus Security commands premium pricing.
Use Case:
Instructional modality determines sensor density and bandwidth requirements across deployment scenarios.
- Interactive Learning:Touch-enabled displays, haptic feedback devices, and real-time polling systems demand low-latency edge processing for synchronous classroom engagement.
- Virtual Labs:Simulated science experiments through VR headsets and IoT-connected physical apparatus reduce consumable costs while maintaining tactile learning outcomes.
- E-Assessment:Proctoring sensors, keystroke analytics, and environmental monitors verify examination integrity in remote testing environments.
- Remote Tutoring:Bidirectional video, document cameras, and connectivity quality sensors bridge geographic gaps in instructor availability.
- Skill Development:Industrial training equipment with embedded sensors tracks competency progression in vocational programs, particularly in Germany's dual education system.
Interactive Learning anchors current infrastructure investment; Virtual Labs shows steepest expansion trajectory.
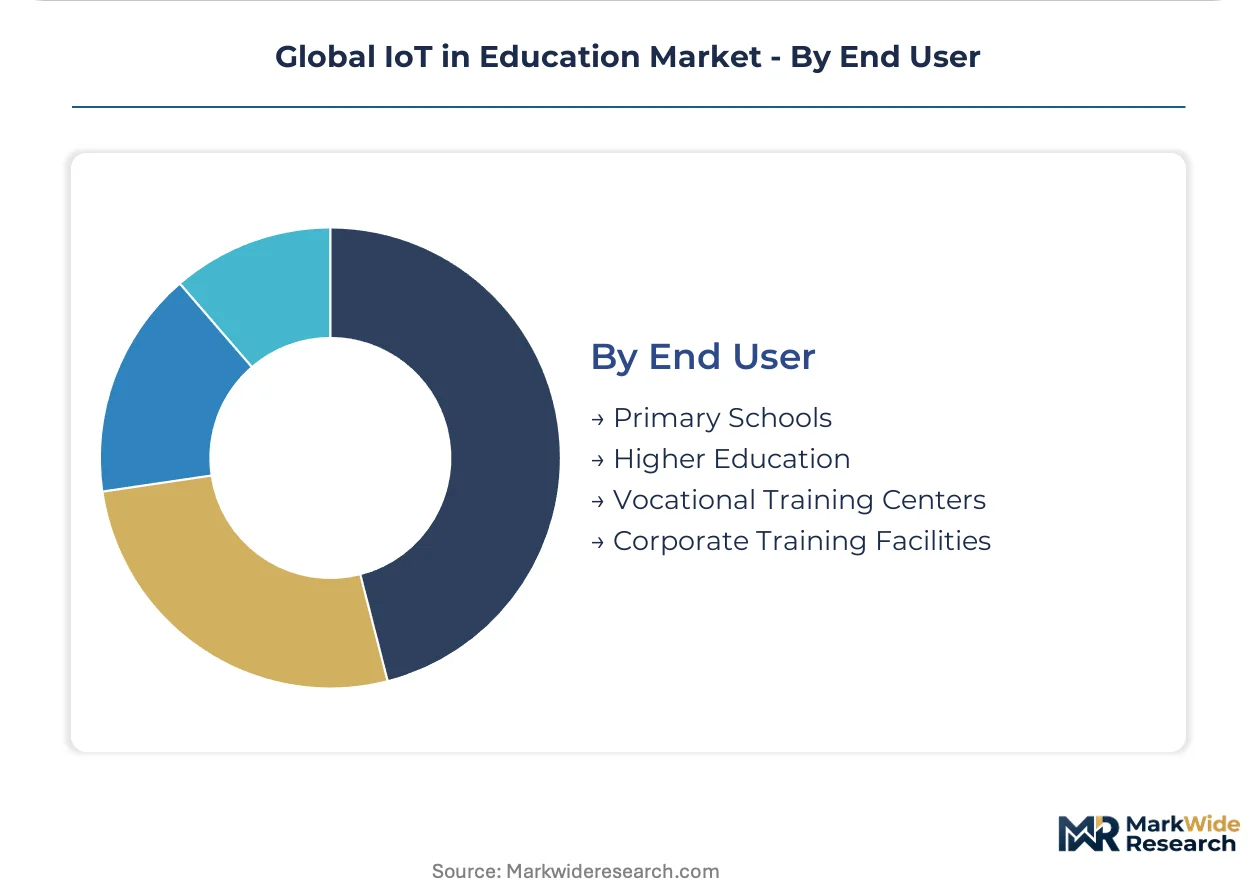
End User:
Budget authority and procurement sophistication vary dramatically across institutional types.
- Primary Schools:Federal connectivity subsidies in the United States expand addressable hardware volumes for infrastructure modernization. E-Rate program eligibility concentrates vendor sales efforts on this price-sensitive segment.
- Higher Education:Research universities deploy dense sensor networks for facilities optimization and behavioral research, with procurement governed by sustainability scoring under EU Green Deal targets.
- Vocational Training Centers:Equipment-integrated IoT tracks hands-on competency development, with China's Ministry of Education mandating national smart campus standards through GB specifications.
- Corporate Training Facilities:Subscription-based hardware provisioning displaces capital purchases as enterprises shift learning infrastructure to operating expenditure models.
Primary Schools generate highest unit volumes; Higher Education drives technology specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded systems engineers in Taiwan and South Korea anchor semiconductor fabrication for edge processors, while cloud architects concentrate in Seattle and Bangalore. Procurement patterns diverge sharply across jurisdictions as data localization mandates reshape vendor eligibility.
United States
FCC E-Rate subsidies expand hardware procurement volumes for K-12 infrastructure modernization. California and Texas education agencies structure multi-year service agreements bundling devices with connectivity under subscription models. Silicon Valley cloud providers anchor Azure IoT and AWS IoT integration into learning management systems nationwide.
Germany
GDPR Article 9 heightened consent requirements enforce on-premise architecture for facial recognition attendance systems. Federal states mandate physical server control for student biometric archives under data protection impact assessments. Bavarian technical universities deploy dense LoRaWAN sensor networks for facilities optimization under EU Green Deal sustainability scoring.
China
MIIT GB standard mandates accelerate interoperability certification for biometric data collection devices. Ministry of Education enforces national smart campus specifications that standardize replacement cycles across provinces. Shenzhen hardware clusters supply BLE mesh sensor assemblies for aging school building retrofits without electrical infrastructure overhaul.
India
BIS certification requirements for electronic equipment filter import competition, protecting domestic assembly partners. Maharashtra and Karnataka state education departments drive smart classroom procurement at scale. Delhi-NCR vocational training centers integrate equipment-embedded IoT for competency tracking under national skill development mandates.
Netherlands
REACH substance restrictions on persistent organic pollutants phase out flame-retardant plastics in classroom device housings. Dutch universities standardize on unlicensed spectrum LoRaWAN deployments for HVAC and occupancy tracking. Eindhoven component suppliers accelerate halogen-free alternative certification to maintain contract eligibility under EU Green Deal procurement criteria.
Global IoT in Education Market Competitive Landscape
Capital-heavy networking hardware producers compete with asset-light cloud platform designers for campus-wide IoT backbone contracts. The vendor base stratifies across three tiers: infrastructure incumbents with captive silicon supply, hyperscale cloud providers with elastic compute platforms, and specialized analytics firms with vertical education expertise. Dominant competitive moves include strategic partnerships bridging hardware-software gaps and geographic expansion through local certification partnerships.
Within the infrastructure incumbent tier, Cisco Systems Inc. and Huawei Technologies Co., Ltd. occupy positions anchoring campus networking hardware dominance across their respective home markets. Microsoft Corporation and Amazon Web Services, Inc. exemplify the hyperscale cloud archetype, extending IoT platform integration into learning management systems through subscription provisioning models. IBM Corporation represents the specialized analytics segment, competing through Watson IoT platforms for predictive maintenance applications.
| Leading Market Players |
|---|
| Cisco Systems Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Google LLC |
| Huawei Technologies Co., Ltd. |
| Intel Corporation |
| Oracle Corporation |
| Amazon Web Services, Inc. |
| SAP SE |
| Others |
Supply & Pricing Matrix
EU Green Deal sustainability targets gate qualified supply and premium-tier pricing access, forcing component suppliers to certify halogen-free alternatives before bidding on institutional contracts. Schools in Germany and the Netherlands now score RFP responses on circular design metrics, compressing margins for uncertified vendors while rewarding compliant manufacturers with preferred pricing tiers.
Pricing Analysis
Bundled subscription services are displacing unbundled capital purchases across U.S. public school districts facing budget volatility. Three-tier pricing structure across premium, standard, and economy levels separates vendors with full-stack IoT platforms from hardware-only suppliers and white-label assemblers. Cost compression in the economy tier is intensifying because copper and lithium commodity volatility squeezes fixed-price contract margins. Primary schools exhibit highest price sensitivity under E-Rate subsidy constraints, while research universities demonstrate lowest sensitivity when sustainability scoring determines vendor selection.
Supply Chain Analysis
Regional distribution centers in Poland and Hungary feed hub-and-spoke patterns across European institutional markets, compressing lead times for REACH-compliant component suppliers. Edge processor fabrication draws from Taiwan and South Korea, with battery chemistry sourcing anchored in Chinese lithium refining operations. Single-source vulnerability in semiconductor wafer production exposes vendors to geopolitical allocation delays. Distribution runs through certified local assembly partners in India under BIS import filtering requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU AI Act's risk-based classification system driving compliance investment demand across vendor portfolios.
For Market Incumbents: Lock in campus-wide backbone contracts by embedding predictive maintenance analytics into existing networking hardware deployments. Cisco Systems and Huawei Technologies anchor their respective home markets through captive silicon supply and localized certification partnerships. Threats from hyperscale cloud providers entering the productivity layer demand accelerated Azure IoT and AWS IoT platform integration investments. For New Entrants and Emerging Players: Begin with BLE mesh sensor deployments in aging Japanese school buildings, where battery-powered architectures avoid electrical retrofitting costs and incumbent building automation vendors maintain proprietary RF licensing revenue. India's BIS certification gap creates protected domestic market share for certified local assembly partners. White-space opportunity concentrates in vocational training equipment-embedded IoT for competency tracking under China's GB standard mandates. For Investors and Strategic Acquirers: Roll-up economics work for specialized analytics firms with vertical education expertise because fragmentation across predictive maintenance, behavioral analytics, and facilities optimization creates platform consolidation potential. Long-term viability hinges on AI-edge convergence capabilities combining on-device inference with cloud training pipelines. Signal to watch: E-Rate program expansion velocity as indicator of U.S. K-12 hardware procurement inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Microsoft Azure IoT extension into learning management systems captures the productivity layer. |
| Geographic Expansion | Local certification partnerships in India bypass BIS import filtering for smart classroom contracts. |
| Acquisition of Specialist Firm | Watson IoT analytics specialization in predictive maintenance addresses campus equipment downtime costs. |
| Product Launch | LoRaWAN environmental monitoring solutions compress recurring licensing revenue for incumbent building automation vendors. |
| Strategic Partnership | Cisco networking hardware anchors campus-wide IoT backbone contracts through E-Rate subsidy eligibility. |
Research Methodology
Bottom-up institutional deployment modeling reconciled against top-down semiconductor supply tracking forms the analytical core of this study. Primary interviews with K-12 technology directors, university facilities managers, IoT platform engineers, and regulatory compliance officers combined with secondary validation from FCC E-Rate disbursement records, EU AI Act implementation guidance, China's GB standard publications, and SEC filings from hyperscale cloud providers. Triangulation across these sources ensures convergence between procurement volume indicators and component supply constraints.
Historical trendline analysis of smart classroom deployment cycles, connectivity subsidy authorization patterns, and wireless protocol adoption curves informed the projection framework. Segmentation dimensions modeled include deployment architecture, solution offering category, instructional use case, and institutional type across the analysis window. CAGR derivation incorporated enrollment volatility elasticity, replacement cycle acceleration under national standard mandates, and edge AI chip cost decay curves.
Several conditions sit outside the modeled scope, including potential E-Rate program funding discontinuation, Taiwan semiconductor fabrication disruption scenarios, and GDPR enforcement intensity variations across European member states. Forecasts reflect documented assumptions regarding subsidy continuity, commodity price stabilization, and certification timeline adherence. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Smart Education System Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Education Apps Market
Educational Technology (EdTech)
VR Education Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
Virtual Schools Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Edtech and Smart Classroom Market
Educational Technology (EdTech)
Asia Big Data Analytics in Education Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
Child Care Software Market
Educational Technology (EdTech)
ASEAN Smart Education and Learning Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Global Smart Learning Market