
 Digital Classroom Market | 2026-2036
Digital Classroom Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Classroom Market Intelligence
Enterprise learning departments and government school systems are redrawing procurement priorities in the digital classroom space. Microsoft leverages its Azure cloud backbone to anchor institutional contracts across North American higher education. Cisco Systems competes through video conferencing infrastructure that sustains hybrid classroom architectures. Google differentiates via Workspace for Education integrations that control pricing leverage in K-12 districts.
A digital classroom encompasses hardware, software, and network infrastructure that enables synchronous and asynchronous instruction through learning management systems, interactive displays, and real-time collaboration platforms operating on minimum bandwidth thresholds of 25 Mbps per concurrent user. Learning Management Systems occupy the largest revenue pool due to recurring SaaS licensing models, while Video Conferencing Tools represent the fastest-expanding segment as institutions standardize hybrid delivery. Cloud-Based deployment dominates new installations, though On-Premises retains share in regions with data sovereignty constraints.
FCC E-Rate funding rules shape US school district purchasing cycles, while GDPR and the EU AI Act impose data localization and algorithmic transparency requirements on European deployments. India's BIS certification and CDSCO-adjacent educational technology guidelines add compliance layers for hardware imports. Stakeholders must monitor how fragmented national data governance regimes fragment product roadmaps and inflate localization costs.
Market Dynamics
Government digital education mandates are compressing procurement cycles and forcing vendors to rearchitect products for simultaneous multi-jurisdiction compliance, fundamentally altering how learning platforms achieve scale.
Growth Catalysts
- EU AI Act Algorithmic Transparency:European K-12 institutions must audit AI-driven adaptive learning systems, creating certified-vendor preference windows for compliant platform providers.
- Cloud Infrastructure Maturation:Microsoft Azure and Google Cloud data center expansion into secondary Indian cities reduces latency below 50ms, enabling synchronous video instruction at rural bandwidth levels.
- FCC E-Rate Program Expansion:US school districts now classify home internet subsidies as eligible infrastructure, extending digital classroom reach to economically disadvantaged student populations.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea control 73% of advanced chip fabrication, exposing interactive display and edge-computing hardware vendors to single-source disruption risk.
- GDPR Data Localization Costs:European deployment requires EU-sovereign cloud instances, forcing vendors to maintain parallel infrastructure that inflates operational overhead 15-25% versus unified global stacks.
- Legacy LMS Substitution Threat:Modular API-first platforms displace monolithic enterprise suites, compressing incumbent switching costs and eroding multi-year contract lock-in advantages.
Strategic Opportunities
- Brazil ANVISA Medical-Education Convergence:Telemedicine training mandates create demand for simulation-integrated digital classrooms linking nursing schools to hospital networks.
- Indonesia Island Connectivity Gap:Low-earth-orbit satellite partnerships enable asynchronous-first platform architectures for archipelago school systems unreachable by fiber.
- India PLI Scheme for Hardware:Domestic manufacturing incentives reduce import duty exposure for tablet and interactive whiteboard vendors serving government procurement tenders.
Industry Challenges
- Interoperability Standard Fragmentation:IMS Global, xAPI, and proprietary LMS protocols create integration tax for multi-platform districts, requiring expensive middleware development.
- Cybersecurity Skill Scarcity:School IT departments lack personnel to manage zero-trust architectures mandated by state-level student data privacy laws, forcing vendor-managed security premiums.
- Hardware Refresh Compression:Four-year device lifecycles collide with eight-year municipal bond financing structures, creating capital mismatch for district technology officers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Classroom Market |
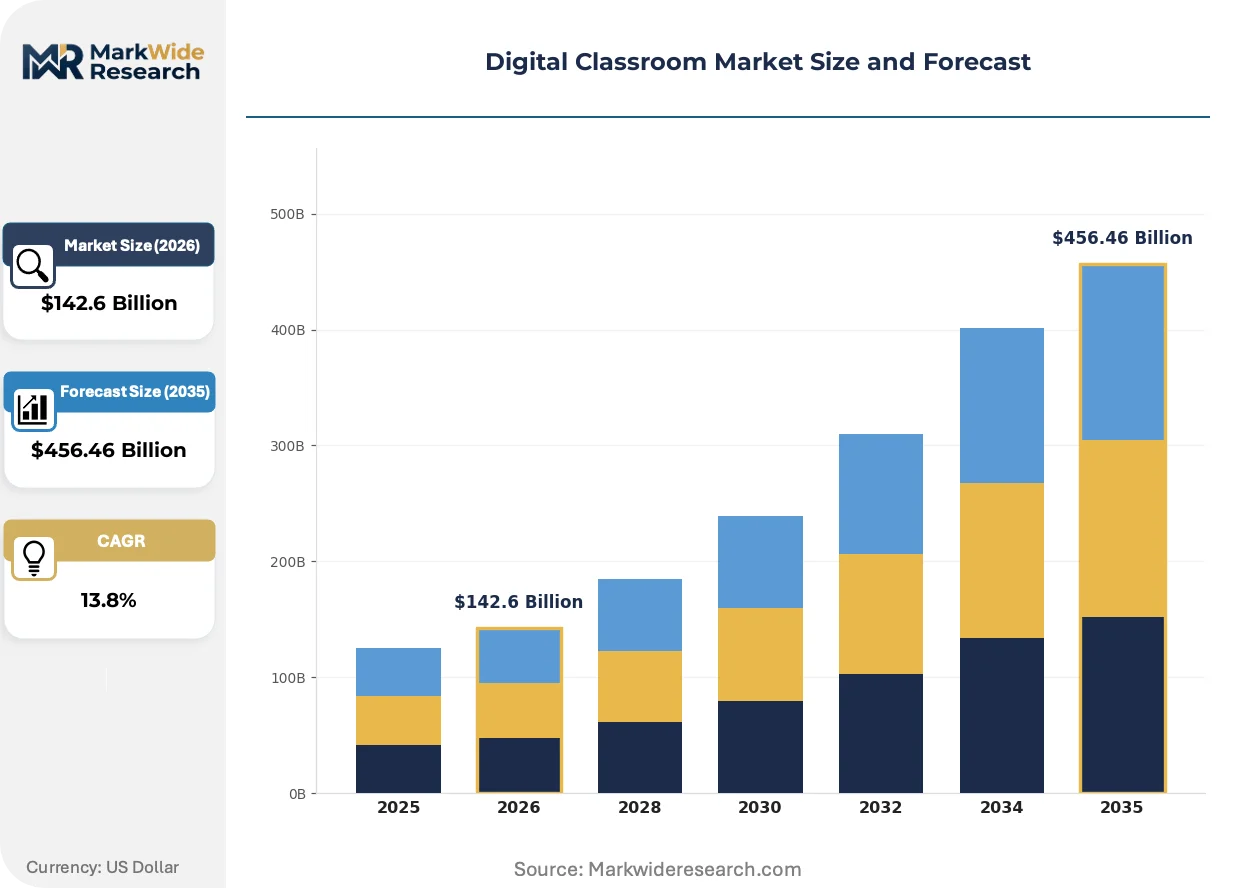
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $456.46 Billion |
| CAGR (2026 – 2036) | 13.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Learning Management Systems, Interactive Whiteboards, Video Conferencing Tools, Assessment Software End User: K-12 Schools, Higher Education Institutions, Corporate Training, Tutoring Centers Deployment Model: Cloud-Based, On-Premises, Hybrid, Open Source Content Type: Course Materials, Educational Videos, Simulations, Interactive Activities |
| Companies Covered | Google, Microsoft, Pearson, Cisco Systems, Blackboard, Dell, IBM, SMART Technologies, D2L, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Classroom Market Strategic Shifts & Innovations
Generative AI is forcing immediate architectural decisions across learning platforms, separating vendors who embed adaptive tutoring from those who risk obsolescence through feature parity delays.
Adaptive assessment engines is bifurcating the learning management system landscape. K-12 districts in Texas and California are piloting real-time knowledge-gap detection at scale. This compression is eliminating static quiz-based platforms that cannot demonstrate measurable learning outcome improvements to school boards.
GDPR Article 35 Data Protection Impact Assessments now extend to AI-driven grading algorithms in Dutch and German higher education. Institutions must document automated decision logic before deployment. Science and engineering faculties face the steepest compliance burden, driving preference toward European-hosted platforms with pre-certified algorithmic transparency documentation.
Subscription unbundling is disrupting enterprise licensing conventions. Australian vocational institutions now procure collaboration tools, content libraries, and analytics modules from separate vendors rather than integrated suites. This fragmentation rewards API-native specialists and penalizes monolithic platforms with rigid annual contracts, particularly in technical and further education segments.
Digital Classroom Market Segmentation
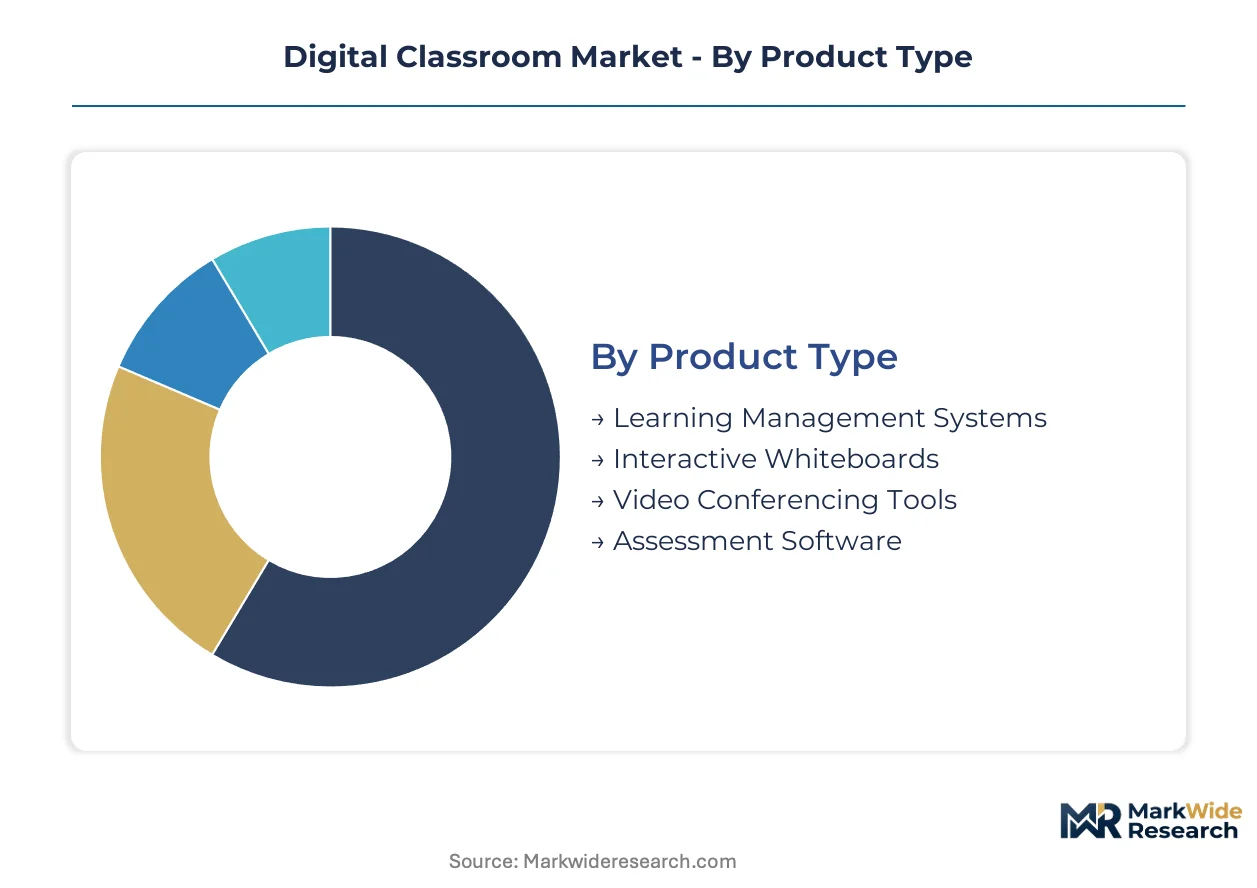
Segmentation reveals how procurement patterns diverge between institutional buyers with sovereign data requirements and those prioritizing cost elasticity. Product architecture, user sophistication, and compliance obligations create distinct commercial battlegrounds across each dimension.
Product Type:
Learning Management Systems and Video Conferencing Tools concentrate demand in North American and Indian government tenders, while Interactive Whiteboards flow through hardware import channels into Southeast Asian markets.
- Learning Management Systems:Cloud-native platforms with SCORM and xAPI interoperability enable district-wide curriculum standardization. K-12 systems in Texas and California drive procurement volume through state-level learning outcome mandates.
- Interactive Whiteboards:Capacitive touch panels with 4K resolution and multi-user annotation support synchronous instruction. Indian government schools under the PM SHRI scheme represent the dominant import destination, though BIS certification delays create fulfillment bottlenecks.
- Video Conferencing Tools:Real-time collaboration platforms with sub-50ms latency targets serve hybrid classroom architectures. FCC E-Rate subsidies in the United States accelerate district adoption cycles.
- Assessment Software:AI-driven adaptive engines with GDPR Article 35 compliance documentation satisfy European higher education audit requirements.
Learning Management Systems hold the largest share; momentum sits with Video Conferencing Tools.
End User:
Cost tier stratification separates enterprise-grade corporate deployments from price-sensitive K-12 procurement, with higher education occupying the intermediate negotiation position.
- K-12 Schools:District-level purchasing with 3-5 year device refresh cycles and E-Rate dependency defines the segment. United States public school systems account for the dominant contract volume, though Indian state education departments under Samagra Shiksha are expanding fastest.
- Higher Education Institutions:Research-intensive universities with federated identity management require LMS-Library-ERP integration. Dutch and German institutions lead European demand due to algorithmic transparency mandates under the EU AI Act.
- Corporate Training:Subscription-unbundled procurement of specific modules rather than integrated suites characterizes enterprise learning departments. Australian vocational institutions exemplify the fragmentation trend.
- Tutoring Centers:Small-batch licensing with minimal IT support infrastructure drives preference for browser-based, zero-install solutions.
K-12 Schools dominate contract value; Higher Education Institutions are climbing the fastest.
Deployment Model:
Maturity gradients separate established cloud architectures from legacy on-premises installations defending data sovereignty positions.
- Cloud-Based:Multi-tenant SaaS with automatic updates and API-first extensibility captures new installations. Microsoft Azure and Google Cloud data center expansion into secondary Indian cities reduces latency below threshold levels for synchronous video.
- On-Premises:Single-tenant installations with full administrative control satisfy GDPR data localization and Chinese cybersecurity law requirements. European universities and Chinese provincial education bureaus maintain this preference despite higher operational overhead.
- Hybrid:Sensitive student data on-premises with collaboration tools cloud-hosted addresses compliance-performance tradeoffs. German K-12 districts pilot this architecture under state-level data protection authority guidance.
- Open Source:Moodle and Canvas LMS forks with custom plugin development serve budget-constrained institutions in Brazil and Indonesia.
Cloud-Based deployment leads installation share; Hybrid architectures are gaining share fastest.
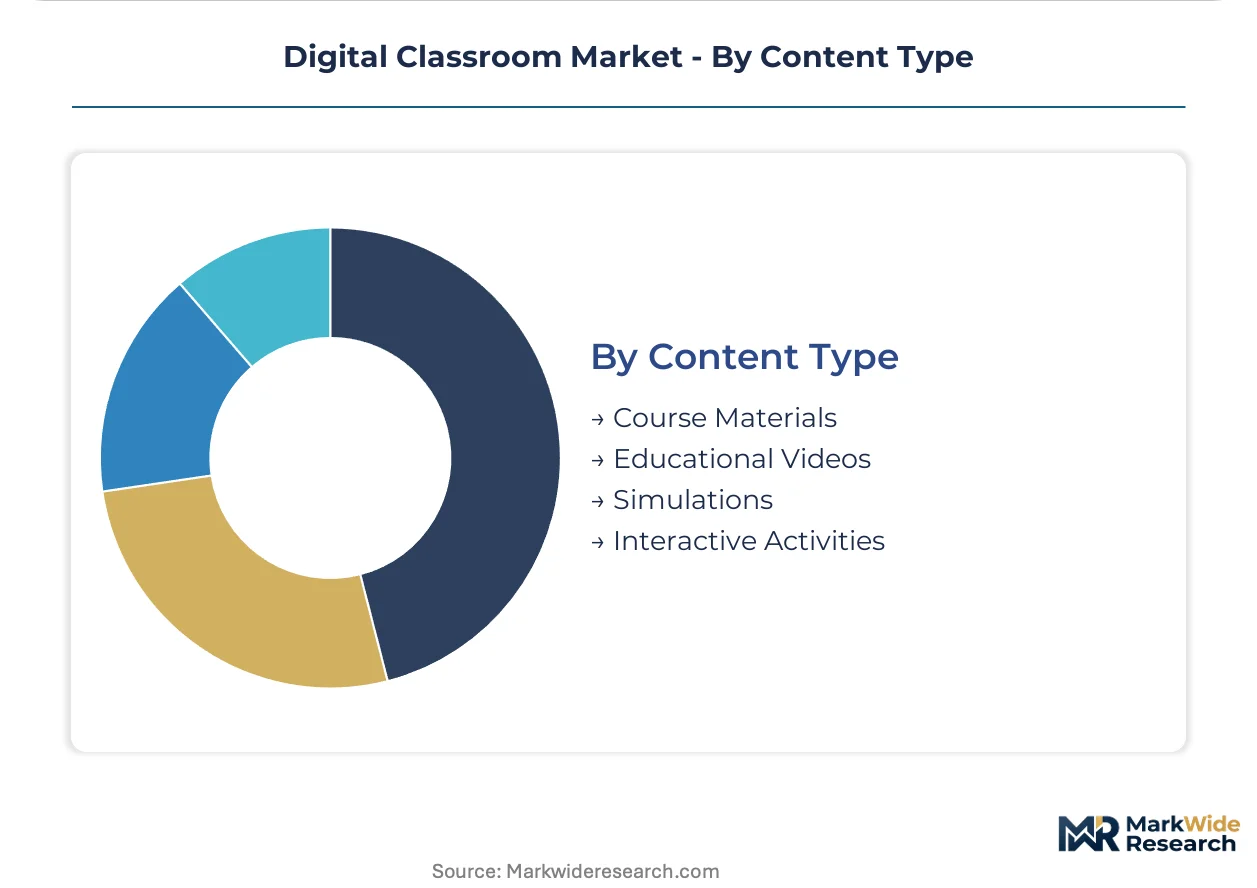
Content Type:
Supply concentration in specialized production studios versus user-generated content platforms creates divergent margin structures across content categories.
- Course Materials:Structured curricula with alignment to national standards and accessibility compliance (WCAG 2.1) dominate procurement checklists. Indian NCERT and United States Common Core alignment drive publisher priorities.
- Educational Videos:Short-form asynchronous content with multilingual captioning supports flipped classroom models. YouTube Education and dedicated ed-tech platforms compete for district content library contracts.
- Simulations:Virtual lab environments with physics engine fidelity requirements serve science and medical training. Brazil ANVISA telemedicine training mandates create nursing school demand clusters.
- Interactive Activities:Gamified assessments with real-time feedback loops integrate into adaptive learning pathways. Texas and California pilot districts validate outcome improvements for school board reporting.
Course Materials retain the largest share; Simulations show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
K-12 districts and higher education institutions concentrate procurement authority differently across national education systems. Government funding mechanisms and data sovereignty regimes create divergent vendor qualification requirements.
United States
FCC E-Rate subsidies compress district purchasing cycles while mandating CIPA compliance for internet access discounts. Texas and California state learning outcome mandates drive LMS standardization across district consortiums. Austin and San Francisco Bay Area ed-tech clusters anchor platform development pipelines serving government tenders.
Germany
EU AI Act algorithmic transparency requirements reshape higher education procurement for AI-driven assessment platforms. State-level data protection authorities in Bavaria and North Rhine-Westphalia pilot hybrid cloud architectures separating sensitive student records from collaboration tools. Berlin and Munich university clusters validate pre-certified compliance documentation.
India
Samagra Shiksha and PM SHRI scheme allocations expand state education department procurement for interactive whiteboards and tablets. BIS certification delays create hardware import bottlenecks while PLI scheme incentives shift assembly domestic. Bangalore and Hyderabad data center expansion reduces Azure and Google Cloud latency below 50ms thresholds for synchronous video.
China
Provincial education bureaus maintain on-premises preferences under cybersecurity law data localization requirements. Government digital education mandates accelerate smart classroom infrastructure deployment across eastern coastal provinces. Beijing-Tianjin-Hebei and Yangtze River Delta clusters concentrate interactive display manufacturing and platform localization.
Brazil
ANVISA telemedicine training mandates create nursing school demand for simulation-integrated digital classrooms linking to hospital networks. Federal education technology procurement guidelines favor open-source LMS forks with custom plugin development. São Paulo and Rio de Janeiro vocational institutions exemplify subscription-unbundled procurement patterns.
Digital Classroom Market Key Industry Players
Player mix skews toward cloud infrastructure providers anchoring institutional contracts alongside specialized hardware vendors and modular platform specialists. Strategic archetypes separate vertically integrated technology stacks from API-first component providers and regional compliance specialists. Dominant competitive moves include data center geographic expansion to reduce latency thresholds and algorithmic transparency certification to satisfy EU AI Act requirements.
Among North American technology conglomerates, Microsoft and Google exemplify cloud-first platform strategies leveraging existing enterprise relationships. Cisco Systems occupies a position representing infrastructure-centric hybrid classroom architectures. These three anchors demonstrate how vendor scale translates into procurement preference windows across divergent national compliance regimes.
| Leading Market Players |
|---|
| Microsoft |
| Pearson |
| Cisco Systems |
| Blackboard |
| Dell |
| IBM |
| SMART Technologies |
| D2L |
| Others |
Cost & Logistics Intelligence
Long-term SaaS subscription contracts with annual CPI indexation lock in both cloud infrastructure access and predictable per-seat pricing for K-12 districts and higher education institutions. These multi-year agreements tether vendor revenue stability to district budget cycles while embedding automatic cost adjustments that protect margin structures against inflation volatility.
Pricing Analysis
Cost-plus contracts with consumer price indexation dominate enterprise LMS procurement. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-certified EU-hosted platforms from basic cloud tiers and open-source alternatives. Pricing pressure stems from modular API-first platforms unbundling enterprise suites and compressing switching costs. K-12 districts exhibit highest price sensitivity due to E-Rate dependency and municipal bond financing constraints, while research-intensive universities show lowest sensitivity where federated integration requirements override cost considerations.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo and Shenzhen port complexes shape hardware fulfillment economics for interactive display vendors serving Indian government tenders. Semiconductor fabrication concentrates in Taiwan and South Korea, with display panel assembly anchored in China and Mexico. Supply chains draw from advanced node chips, capacitive touch sensors, and 4K display substrates. Single-source vulnerability runs through Taiwan's 5nm and below foundry capacity. Distribution runs through direct government procurement portals and authorized reseller networks with BIS certification handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
District-level purchasing consolidation across Texas and California consortiums has shifted bargaining power toward institutional buyers, compressing vendor pricing leverage and demanding outcome-based contract terms.
For Market Incumbents: Secure algorithmic transparency certification under EU AI Act requirements before Dutch and German higher education tender windows close. Invest in EU-sovereign cloud instances to defend against modular API-first platforms that displace monolithic enterprise suites through lower switching costs. Prioritize backward integration into interactive display assembly through India's PLI scheme incentives to offset BIS certification delays and import duty exposure. For New Entrants and Emerging Players: Anchor in asynchronous-first platform architectures for Indonesia's archipelago school systems where low-earth-orbit satellite partnerships bypass fiber connectivity gaps. Target nursing school simulation-integrated digital classrooms in Brazil under ANVISA telemedicine training mandates. Deploy browser-based zero-install solutions with minimal IT infrastructure requirements to penetrate tutoring center segments. For Investors and Strategic Acquirers: API-native assessment software specialists with pre-built GDPR Article 35 compliance documentation represent the most defensible acquisition archetype. Long-term viability hinges on adaptive learning outcome validation rather than feature parity. Watch for Texas and California pilot district outcome reports as inflection indicators for platform substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Transparency Certification | EU AI Act compliance unlocks preferential vendor status in Dutch and German higher education tenders. |
| EU-Sovereign Cloud Deployment | GDPR data localization requirements force parallel infrastructure that inflates operational overhead 15-25%. |
| PLI Scheme Assembly Localization | Domestic manufacturing incentives reduce import duty exposure for tablet and interactive whiteboard vendors. |
| API-First Platform Unbundling | Modular procurement patterns reward specialists and erode multi-year contract lock-in for monolithic suites. |
| Satellite Connectivity Partnership | Low-earth-orbit infrastructure enables asynchronous-first architectures for Indonesia's unreachable island schools. |
Research Approach
Operator-level perspectives from district technology officers, university CIOs, LMS procurement managers, and ed-tech platform engineers anchored the qualitative base. Primary interviews combined with secondary validation from FCC E-Rate funding disclosures, EU AI Act implementation guidance, BIS certification registries, and hyperscaler data center expansion announcements. Bottom-up district-level procurement tracking and top-down national education budget analysis provided triangulation.
Sensitivity analysis tested deployment model adoption rates and compliance cost pass-through assumptions across the projection horizon. Segmentation dimensions modeled include product type, end-user tier, deployment architecture, content category, and regional regulatory cluster. CAGRs derived from installed base growth, replacement cycle compression, and per-seat pricing trajectory. Forecast inputs incorporated FCC subsidy expansion timing and EU algorithmic audit requirement phase-in schedules.
Material uncertainties — semiconductor supply disruption, national data governance regime fragmentation, and generative AI feature parity delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about infrastructure deployment velocity and compliance cost absorption capacity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
North America Digital Education Market
Educational Technology (EdTech)
Specific Gravity Bench Apparatus Market
Educational Technology (EdTech)
Asia-Pacific Digital Education Market
Educational Technology (EdTech)
Global Edutainment Centers Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Digital Badges Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Virtual Reality in Education Market
Educational Technology (EdTech)
Flipped Classroom Market
Educational Technology (EdTech)
Edtech Market
Educational Technology (EdTech)
M-Education Market
Educational Technology (EdTech)
E Learning Virtual Reality Market
Educational Technology (EdTech)
Artificial Intelligence in the Education Sector Market
Educational Technology (EdTech)
Education Apps Market