
 Global Social Learning Platforms Market | 2026-2036
Global Social Learning Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Social Learning Platforms Market Foresight
Platform bundling is consolidating buyer choice as vendors merge learning management, collaboration, and gamification modules into unified suites. Coursera, Inc. leverages its university partnerships to anchor credential-backed enterprise offerings. Udemy, Inc. competes through marketplace breadth that sustains course volume across technical and soft-skills domains. 360Learning differentiates by specializing in collaborative authoring tools that shift content creation from instructional designers to subject-matter experts.
Social learning platforms are cloud-native software systems that enable peer-to-peer knowledge exchange, learner-generated content distribution, and real-time interaction tracking through APIs and embedded analytics engines. Their primary commercial purpose is reducing training costs while improving knowledge retention through interactive, community-driven pedagogy. Learning Management System deployments dominate enterprise budgets, while Gamification features represent the fastest-growing capability layer as organizations seek measurable engagement metrics. Corporate Training end users command the largest margin pools, though Higher Education institutions occupy the most complex procurement cycles with multi-stakeholder governance.
FDA oversight applies where platforms support healthcare credentialing, while GDPR and the EU AI Act constrain how European providers deploy learner analytics and automated content recommendations. The FCC shapes accessibility standards for video-based instruction in US federal contracts. Stakeholders must monitor how interoperability mandates from ISO and regional regulators affect platform switching costs and data portability requirements.
Market Dynamics
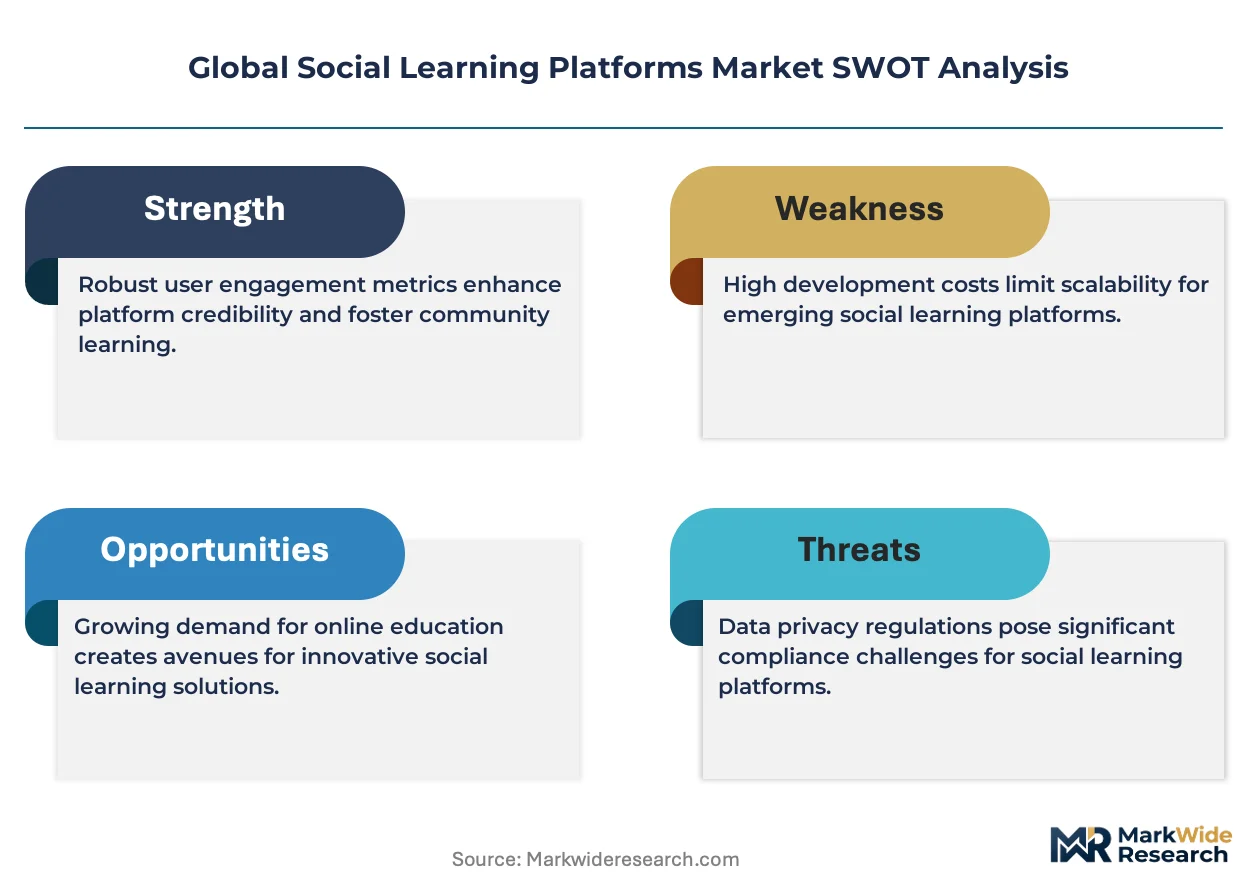
Platform consolidation is compressing vendor margins as unified suites absorb point solutions, while GDPR and the EU AI Act impose compliance costs that favor established providers with dedicated legal infrastructure.
Growth Catalysts
- Enterprise L&D digitization:Siemens and Unilever are expanding platform licenses for workforce upskilling, validating subscription models at scale.
- EU AI Act compliance infrastructure:Automated content recommendation engines require audit trails, creating demand for governance-embedded platforms.
- Gamification capability layering:Measurable engagement metrics are becoming procurement requirements in corporate training RFPs.
Market Restraints
- Cloud infrastructure concentration:AWS, Azure, and Google Cloud dominate hosting, creating single-supplier vulnerability for regional platform operators.
- GDPR data localization mandates:European learner analytics must reside within EU borders, fragmenting technical architecture and raising operational overhead.
- Legacy LMS substitution:Established Learning Management Systems retain procurement inertia through sunk-cost entrenchment and IT security approvals.
Strategic Opportunities
- German Mittelstand penetration:Mid-sized industrial firms remain underpenetrated relative to DAX-listed corporations, representing greenfield deployment potential.
- Healthcare credentialing specialization:FDA oversight requirements for clinical training platforms create defensible moats against generalist competitors.
- API-first interoperability:ISO standardization for learning data portability is lowering switching costs and opening replacement cycles.
Industry Challenges
- Instructional designer talent scarcity:Platform vendors compete for expertise in learning science and UX research to differentiate authoring workflows.
- Multi-stakeholder procurement cycles:Higher education institutions require alignment across faculty senates, IT security, and procurement offices, extending sales timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Social Learning Platforms Market |
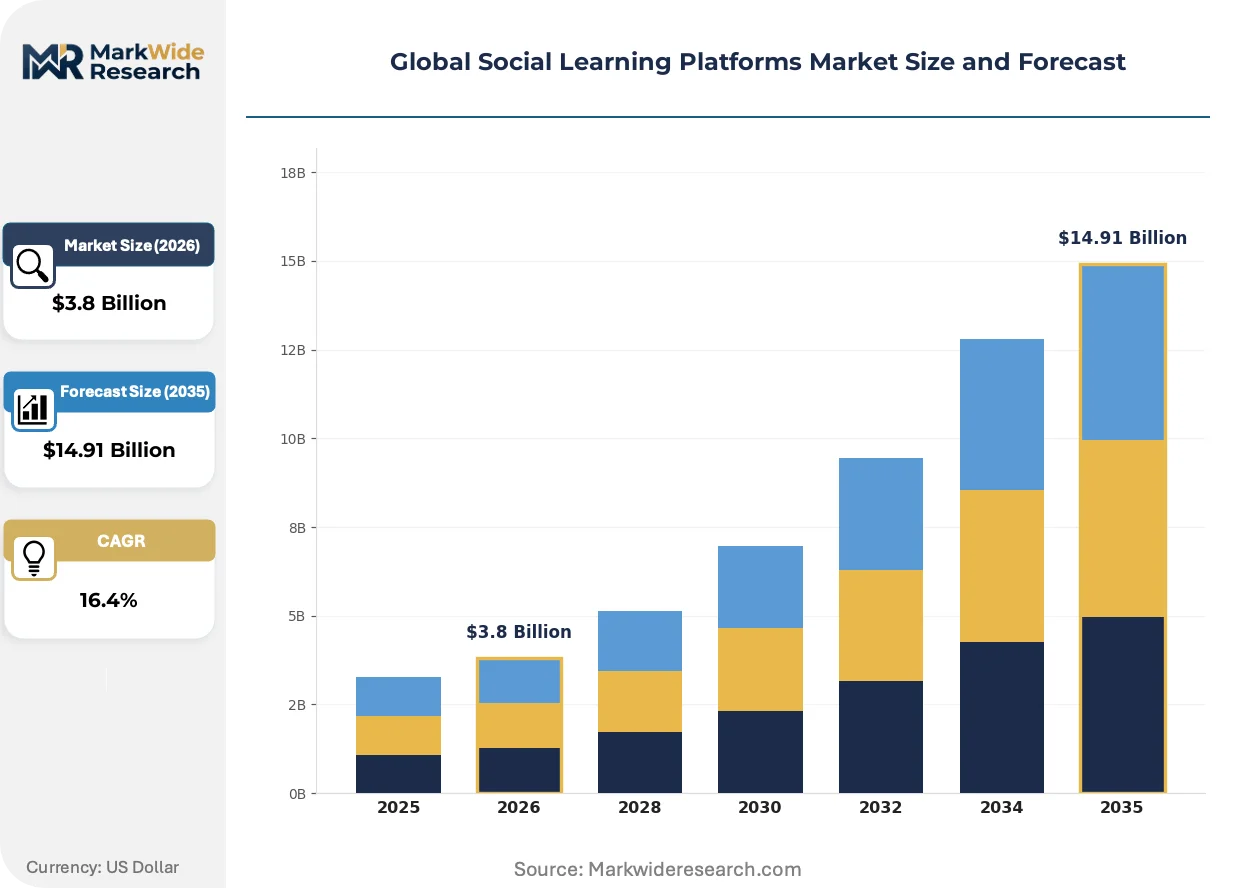
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.91 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Learning Management System, Collaboration Tool, Content Sharing, Gamification, Virtual Classroom, Social Networking Deployment Mode: Cloud-Based, On-Premises, Hybrid, Software-as-a-Service, Mobile Application End User: K-12 Education, Higher Education, Corporate Training, Non-Profit Organizations, Government Agencies Features: Real-Time Communication, Analytics Dashboard, User-Generated Content, Personalized Learning Paths, Certification Support |
| Companies Covered | Coursera, Inc., Udemy, Inc., 360Learning, Docebo, TalentLMS, edX, Inc., LinkedIn Learning, iSpring Learn, Blackboard, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Social Learning Platforms Market Shifts & Advancements
Artificial intelligence is restructuring how content gets created, distributed, and validated across enterprise learning environments. Three developments are compressing traditional value chains.
Generative AI content engines are modularizing course production by fragmenting monolithic curriculum design into componentized microlearning units. Corporate training departments at industrial firms are piloting these tools to compress development timelines from months to days. The technology is modularizing the role of instructional designers into quality assurance specialists rather than primary authors.
The EU AI Act's risk classification framework is mandating human oversight for automated credentialing decisions in European deployments. Platform providers must now maintain algorithmic audit trails and explicability documentation for recommendation engines. German and French enterprise buyers are inserting these compliance requirements into procurement specifications ahead of full enforcement.
Buyer committees are consolidating vendor selection authority into centralized procurement functions, displacing departmental autonomy in learning technology decisions. This concentration is compressing the number of platforms enterprises maintain from dozens to three-to-five strategic relationships. The pattern is most visible in United States healthcare systems undergoing post-merger IT rationalization.
Global Social Learning Platforms Market Segmentation
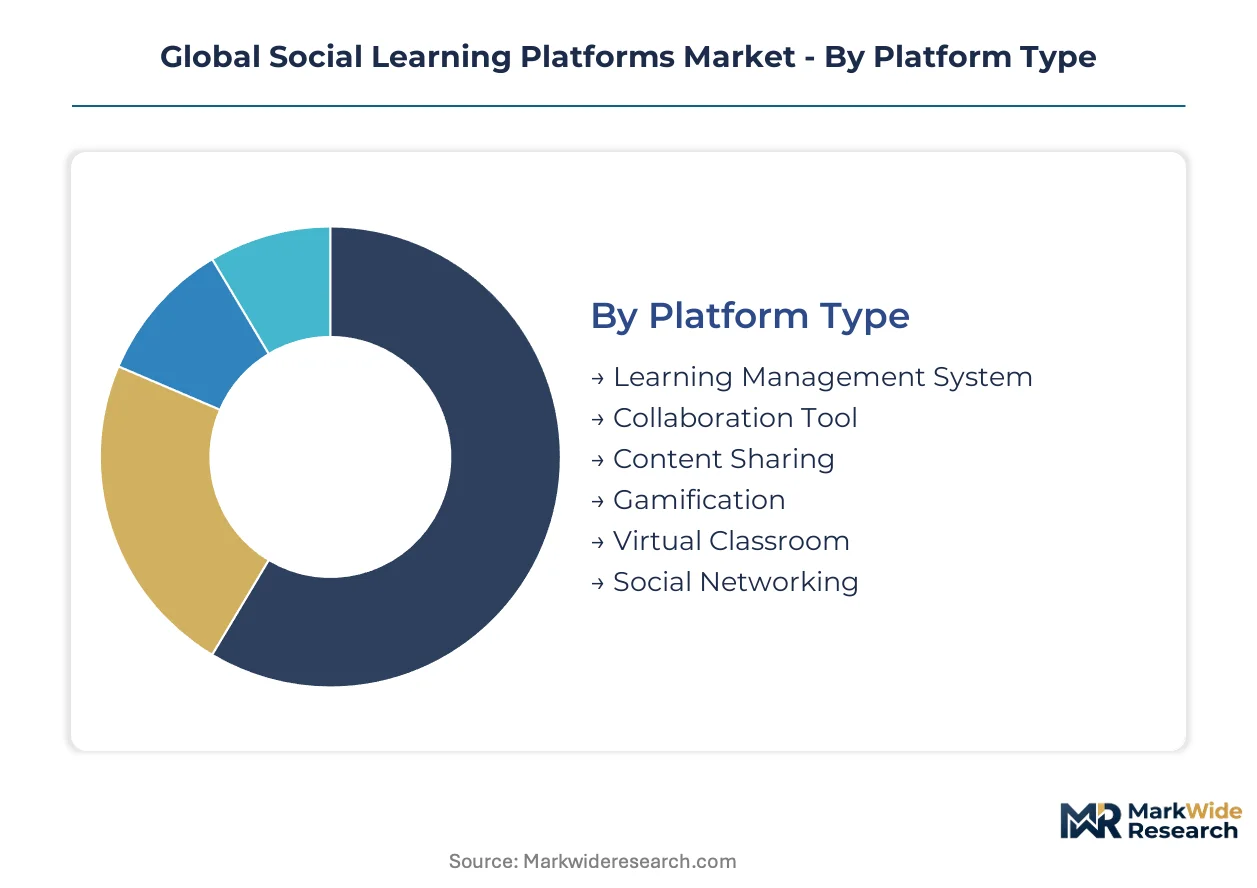
Segmentation in social learning platforms reveals how procurement priorities diverge between cost-conscious K-12 districts and compliance-driven healthcare enterprises. Platform vendors must architect modular pricing that accommodates both standardized SaaS subscriptions and heavily customized on-premises deployments with data residency requirements.
Platform Type:
Learning Management Systems anchor enterprise architecture decisions, while specialized collaboration layers command premium pricing for peer-to-peer knowledge exchange functionality.
- Learning Management System:Core administrative infrastructure for course enrollment, progress tracking, and credential issuance. Siemens and Unilever validate subscription models at scale through workforce upskilling deployments across distributed manufacturing sites.
- Collaboration Tool:Real-time document co-editing, threaded discussions, and expert-finding algorithms that shift content creation from instructional designers to subject-matter experts. 360Learning specializes here, differentiating through collaborative authoring workflows.
- Content Sharing:Learner-generated distribution networks with version control and curation mechanisms.
- Gamification:Badge engines, leaderboards, and progress visualization that transform engagement metrics into procurement requirements. Corporate training RFPs increasingly mandate measurable participation indicators.
- Virtual Classroom:Synchronous video instruction with breakout rooms and polling for remote instructor-led delivery.
- Social Networking:Profile-based connection systems that map organizational expertise and facilitate mentorship matching.
Learning Management Systems lead on scale; Gamification leads on momentum as engagement analytics reshape procurement specifications.
Deployment Mode:
Cloud infrastructure concentration creates vulnerability for regional operators, while data localization mandates fragment technical architecture for European compliance.
- Cloud-Based:Multi-tenant architectures hosted on AWS, Azure, or Google Cloud with automatic scaling and shared security patching. GDPR data localization requirements force EU-specific instance provisioning, raising operational overhead for providers.
- Software-as-a-Service:Subscription pricing with standardized feature tiers and rapid release cycles. German Mittelstand firms represent greenfield deployment potential relative to DAX-listed corporations with established vendor relationships.
- On-Premises:Single-tenant installations behind organizational firewalls for classified or regulated environments. Higher education institutions favor these for multi-stakeholder governance alignment across faculty senates and IT security offices.
- Hybrid:Split architectures with sensitive learner data on-premises and collaboration tools in cloud instances.
- Mobile Application:Native iOS and Android clients with offline content synchronization for field-based workforce training.
Software-as-a-Service dominates new procurement; Cloud-Based deployments face escalating compliance fragmentation under the EU AI Act.
End User:
Corporate training commands the largest margin pools, though extended sales cycles in higher education reward patient vendor investment in procurement relationship management.
- Corporate Training:Workforce upskilling with measurable ROI linkages to productivity metrics and retention rates. FDA oversight applies where platforms support healthcare credentialing, creating defensible moats against generalist competitors.
- Higher Education:Multi-stakeholder procurement involving faculty senates, IT security, and procurement offices with extended sales timelines. Coursera leverages university partnerships to anchor credential-backed enterprise offerings.
- K-12 Education:District-level purchasing with standardized curriculum alignment requirements and parent accessibility mandates.
- Government Agencies:Federal contracts requiring FCC accessibility standards for video-based instruction and Section 508 compliance.
- Non-Profit Organizations:Grant-funded implementations with donor reporting requirements and volunteer training coordination.
Corporate Training leads on scale; Higher Education leads on contract value concentration despite procurement friction.
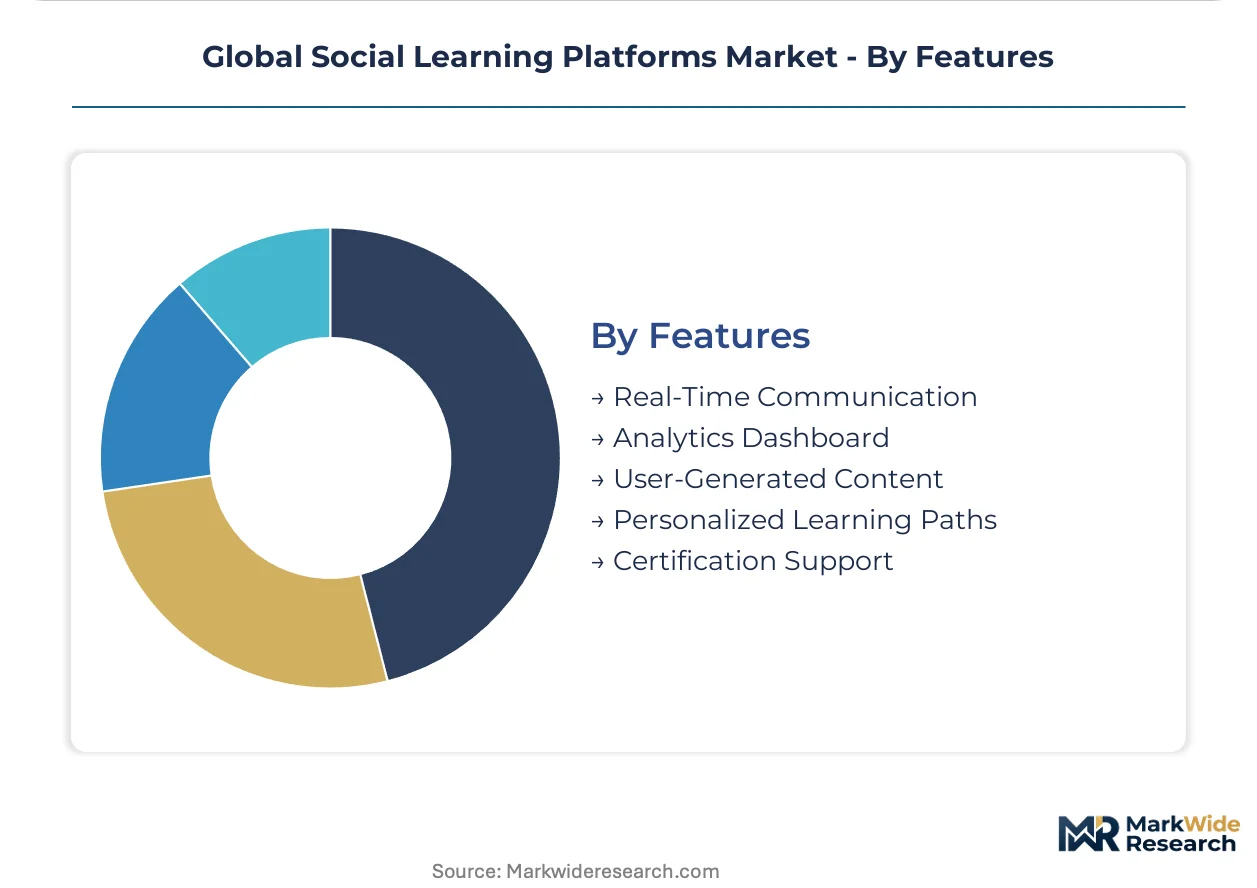
Features:
Analytics capabilities are becoming table stakes as buyers demand audit trails for automated recommendation engines under emerging AI governance frameworks.
- Analytics Dashboard:Learner progress visualization, engagement heatmaps, and predictive dropout risk scoring. The EU AI Act mandates human oversight and explicability documentation for automated credentialing decisions.
- Personalized Learning Paths:Algorithmic content sequencing based on skill gaps, career trajectories, and peer comparison benchmarks.
- Real-Time Communication:Synchronous messaging, video conferencing, and presence indicators for immediate expert consultation.
- User-Generated Content:Subject-matter expert publishing tools with peer review workflows and quality assurance moderation.
- Certification Support:Credential issuance, blockchain verification, and continuing education credit tracking for regulated professions.
Analytics Dashboard leads on procurement priority; Personalized Learning Paths lead on technology differentiation as AI recommendation engines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The social learning platforms industry traces its commercial origins to Silicon Valley's edtech incubation clusters of the late 2000s, where venture capital first validated subscription-based credentialing models at scale before European and Asian markets adapted these architectures to local regulatory environments.
United States
Enterprise digitization of L&D budgets at firms like Siemens and Unilever validates subscription models, though domestic healthcare systems drive FDA oversight requirements for clinical training platforms. The FCC shapes accessibility standards for video-based instruction in federal contracts. Boston's higher education corridor anchors credential-backed enterprise offerings through university partnership networks.
Germany
Mid-sized industrial firms in the Mittelstand segment remain underpenetrated relative to DAX-listed corporations, representing greenfield deployment potential for workforce upskilling platforms. GDPR data localization mandates force EU-specific instance provisioning, fragmenting technical architecture for German operators. Munich and Stuttgart manufacturing clusters pilot collaborative authoring tools for distributed engineering teams.
China
Enterprise digitization proceeds fastest among state-owned enterprises consolidating vendor selection authority into centralized procurement functions. MIIT cloud infrastructure regulations constrain foreign platform hosting arrangements. Shenzhen and Hangzhou technology corridors host domestic alternatives to Western learning management architectures.
United Kingdom
Multi-stakeholder procurement cycles in higher education institutions extend sales timelines across faculty senates, IT security, and procurement offices. GDPR compliance infrastructure requirements favor established providers with dedicated legal resources. London's financial services sector drives demand for measurable engagement metrics in corporate training RFPs.
India
Technical and soft-skills course volume sustains marketplace platform growth as workforce upskilling demand concentrates in IT services and business process outsourcing sectors. BIS standards for educational technology procurement create compliance barriers for unverified foreign vendors. Bangalore and Hyderabad technology corridors anchor regional platform adoption for distributed enterprise workforces.
Global Social Learning Platforms Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance infrastructure and credential-backed partnership depth, with unified suite vendors absorbing point solutions and compressing vendor margins through platform consolidation. The competitive structure segments into three strategic archetypes: university partnership anchors, marketplace breadth specialists, and collaborative authoring tool providers. Dominant competitive moves include M&A activity consolidating learning management with collaboration modules, and strategic partnerships embedding governance-embedded platforms ahead of EU AI Act enforcement.
Within the collaborative authoring tier, 360Learning exemplifies the shift from instructional designer-dependent workflows toward subject-matter expert-driven content creation. Among credential-backed enterprise anchors, Coursera, Inc. occupies a position leveraging university partnerships for defensible moats in corporate upskilling procurement. At the marketplace breadth end, Udemy, Inc. represents sustained course volume across technical and soft-skills domains through decentralized instructor networks.
| Leading Market Players |
|---|
| Coursera, Inc. |
| Udemy, Inc. |
| 360Learning |
| Docebo |
| TalentLMS |
| edX, Inc. |
| LinkedIn Learning |
| iSpring Learn |
| Blackboard, Inc. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA-validated healthcare credentialing platforms and generalist SaaS offerings manifests in both subscription pricing and cloud infrastructure sourcing decisions. Premium tiers command three-to-five-fold multiples over standard deployments by embedding compliance audit trails and EU AI Act governance modules that fragment technical architecture across regional data centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels anchors enterprise procurement, with differentiation driven by GDPR data localization scope and gamification analytics depth. Cost compression in the economy tier intensifies because AWS, Azure, and Google Cloud hosting concentration allows hyperscale buyers to extract volume discounts. Corporate training departments at industrial firms show least price sensitivity where measurable engagement metrics link to retention KPIs, while K-12 districts exhibit highest sensitivity to per-seat licensing.
Supply Chain Analysis
Freight costs for on-premises hardware deployments to German Mittelstand manufacturing sites and Indian IT services corridors elevate total cost of ownership relative to pure cloud delivery. Software development draws from engineering talent pools in the United States, India, and Germany, with cloud infrastructure sourcing anchored in Ireland, Singapore, and Frankfurt for GDPR compliance. Single-source vulnerability concentrates in AWS hosting for mid-tier vendors. Distribution runs through direct enterprise sales teams and systems integrators for complex higher education implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The social learning platforms market operates as a regulatory compounder where EU AI Act enforcement timelines accelerate procurement of governance-embedded platforms ahead of full compliance deadlines.
For Market Incumbents: Anchor defensive positioning through backward integration into proprietary AI content engines that modularize instructional designer workflows against generative AI substitution threats. Pursue certification investment in FDA-validated healthcare credentialing infrastructure to deepen moats against marketplace generalists. Channel control through university partnership exclusivity agreements protects enterprise upskilling revenue pools. For New Entrants and Emerging Players: Enter via German Mittelstand workforce upskilling deployments where DAX-listed vendor relationships remain underpenetrated relative to industrial conglomerates. Target collaborative authoring specialization for distributed engineering teams in Munich and Stuttgart manufacturing clusters. White-space exists in healthcare credentialing automation where FDA oversight requirements deter generalist competition. For Investors and Strategic Acquirers: Consolidation pressure builds where platform bundling compresses point-solution margins and GDPR compliance infrastructure favors established providers with dedicated legal resources. Long-term viability centers on vendors embedding algorithmic audit trails ahead of EU AI Act full enforcement. Acquisition target archetype: collaborative authoring specialists with subject-matter expert workflow differentiation. Signal to watch: procurement specification language mandating human oversight for automated credentialing decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies learning management with gamification modules to meet corporate RFP engagement metrics requirements. |
| Strategic Partnership | Embeds university credentialing networks into enterprise upskilling procurement cycles for defensible positioning. |
| Acquisition of Specialist Firm | Absorbs collaborative authoring capabilities that shift content creation from instructional designers to experts. |
| Geographic Expansion | Captures German Mittelstand greenfield deployment potential through localized GDPR-compliant instance provisioning. |
| Product Launch | Introduces AI governance-embedded platforms with algorithmic audit trails ahead of EU AI Act enforcement. |
Research Methodology
Multiple input streams — interviews with learning technology procurement officers, conversations with instructional design leads, and discussions with regulatory compliance directors — were reconciled against secondary validation from SEC filings of publicly traded platform vendors, hyperscaler capex disclosures, and EU regulatory documentation. Bottom-up triangulation across deployment mode, end-user vertical, and platform type segmentation informed volume estimates. Top-down cross-checks against enterprise L&D budget digitization trends anchored value projections.
Data-stream reconciliation across the modeling period applied analytical frameworks tracking subscription pricing evolution, compliance cost absorption, and vendor consolidation velocity. Segmentation dimensions modeled include platform type, deployment architecture, organization size tier, and regional regulatory cluster. CAGRs derived from trend extrapolation of workforce upskilling penetration rates and gamification capability adoption curves. Industry-specific forecast inputs incorporated GDPR data localization overhead and EU AI Act audit infrastructure deployment timelines.
The model holds under steady regulatory enforcement schedules; deviation in EU AI Act implementation timelines or cloud infrastructure tariff regimes would shift vendor margin compression trajectories. Forecasts reflect assumptions regarding enterprise digitization continuity and compliance infrastructure investment willingness. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Educational Technology (EdTech)
AI in K-12 Education Market
Educational Technology (EdTech)
Global Gamification in Education Market
Educational Technology (EdTech)
Blockchain in Edutech Market
Educational Technology (EdTech)
Education Technology and Smart Classrooms Market
Educational Technology (EdTech)
Edutainment Market
Educational Technology (EdTech)
Digital Education Systems Market
Educational Technology (EdTech)
Digital Classroom Market
Educational Technology (EdTech)
Artificial Intelligence (AI) in Education Market
Educational Technology (EdTech)
Global IoT in Education Market
Educational Technology (EdTech)
Higher Education Learning Systems Market
Educational Technology (EdTech)
Augmented and Virtual Reality in Education Market
Educational Technology (EdTech)
Smart Education and Learning Market
Educational Technology (EdTech)
Global K-12 Software Market
Educational Technology (EdTech)
Global AI in Education Market
Educational Technology (EdTech)
Global Adaptive Learning Market
Educational Technology (EdTech)
Flipped Classroom Market