
 Intrapartum Monitors Market | 2026-2036
Intrapartum Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
Intrapartum Monitors Market Foresight
EU MDR reclassification of active labor monitoring devices is pivoting the cost-of-entry calculus for manufacturers seeking European market access. GE Healthcare leverages its installed base of maternal-fetal monitors to sustain service revenue streams across North American hospital networks. Koninklijke Philips N.V. anchors its competitive position through integrated informatics platforms that connect intrapartum data to enterprise electronic health records. Shenzhen Mindray Bio-Medical Electronics competes aggressively on manufacturing scale, offering combination monitor configurations at price points that challenge premium-tier vendors.
Intrapartum monitors encompass electronic and manual devices that track fetal heart rate, uterine contractions, and maternal vital signs during labor, typically operating via tocodynamometer pressure sensors or Doppler ultrasound transducers with wireless transmission ranges of 30-100 meters to central nursing stations. Their primary purpose is enabling obstetric clinicians to detect fetal distress patterns and coordinate timely intervention decisions during active labor. Wireless monitors represent the fastest-expanding product configuration as birthing centers and hospital labor units eliminate tethered bedside setups to support maternal mobility during prolonged deliveries. Cloud-based systems are capturing disproportionate R&D investment as vendors seek recurring software revenue from remote data archiving and predictive analytics subscriptions. Electronic monitoring technology retains dominant installed volume despite manual monitoring's persistence in resource-constrained clinical settings where capital budgets limit device procurement.
The US FDA maintains stringent 510(k) clearance pathways for fetal monitor hardware and algorithm-based diagnostic outputs, while the EU MDR imposes expanded clinical evidence requirements on active labor monitoring devices that lengthen approval timelines. Japan's PMDA applies distinct electromagnetic compatibility standards that create additional testing burdens for wireless monitor platforms seeking market entry. Stakeholders must weigh regulatory compliance investment against the margin compression risk from health system procurement consolidation and emerging value-based obstetric care contracts.
Market Dynamics
Hospital maternity wards are consolidating around wireless fetal monitoring platforms as labor and delivery units eliminate tethered bedside setups to support maternal mobility during prolonged deliveries.
Growth Catalysts
- Wireless transmission protocols:Birthing centers across the United States are replacing legacy wired configurations with 30-100 meter range systems that enable ambulatory labor management.
- EU MDR clinical evidence pathways:Reclassification of active labor monitoring devices is creating competitive moats for established manufacturers with robust clinical dossiers.
- Cloud-based predictive analytics:Vendors are capturing recurring software revenue from remote data archiving subscriptions that integrate with enterprise electronic health records.
Market Restraints
- 510(k) clearance complexity:The US FDA's evolving premarket submission requirements for algorithm-based diagnostic outputs are elevating compliance costs for new entrants.
- Electromagnetic compatibility testing:Japan's PMDA applies distinct standards that create additional validation burdens for wireless monitor platforms.
- Manual monitoring persistence:Resource-constrained clinical settings with limited capital budgets continue relying on non-electronic alternatives in lower-income regions.
Strategic Opportunities
- Value-based obstetric care contracts:Health system purchasing consortia in the United States are standardizing device configurations across multi-hospital networks.
- Integrated informatics convergence:Platforms connecting intrapartum data to enterprise electronic health records are displacing standalone monitoring hardware.
- Combination monitor configurations:Manufacturing scale advantages enable bundled fetal-maternal vital sign systems at price points challenging premium-tier vendors.
Industry Challenges
- Algorithm validation timelines:FDA scrutiny of machine-learning-based fetal distress pattern recognition is extending clearance cycles beyond traditional hardware pathways.
- Legacy system interoperability:Nursing station infrastructure in established hospital networks requires costly middleware development for wireless monitor integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intrapartum Monitors Market |
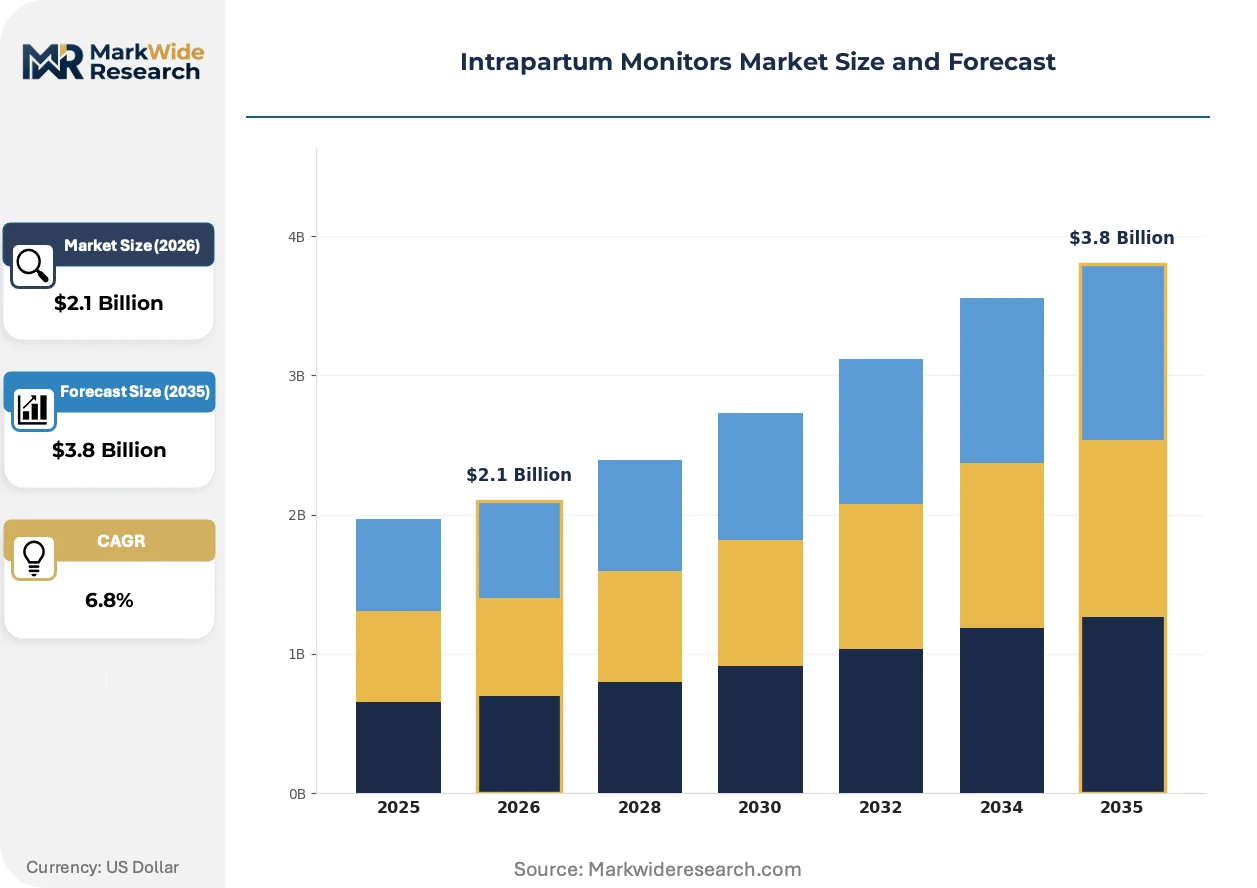
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fetal Monitors, Uterine Monitors, Combination Monitors, Wireless Monitors End User: Hospitals, Clinics, Home Care, Birthing Centers Technology: Electronic Monitoring, Manual Monitoring, Wireless Technology, Cloud-Based Systems Application: Labor Monitoring, Fetal Surveillance, Maternal Assessment, Emergency Response |
| Companies Covered | GE Healthcare, Koninklijke Philips N.V., Medtronic plc, Cardinal Health, The Cooper Companies, Mindchild Medical, Huntleigh Healthcare Limited, Analogic Corporation, Shenzhen Mindray Bio-Medical Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intrapartum Monitors Market Shifts & Advancements
Intrapartum monitoring is pivoting from episodic bedside observation to continuous ambulatory surveillance, with hardware commoditization pressuring vendors toward software-enabled recurring revenue models.
Wireless telemetry systems are expanding into labor and delivery units previously constrained by tethered patient setups. Hospital networks in the United States are deploying these platforms across maternity wards to reduce intervention delays during ambulatory labor phases. The technology is expanding into service revenue streams as vendors bundle hardware with cloud-based data archiving and predictive analytics subscriptions.
EU MDR reclassification mandates expanded clinical evidence requirements for active labor monitoring devices seeking European market access. Manufacturers must now generate robust clinical dossiers that lengthen approval timelines compared to previous directive frameworks. Mid-cap specialists without legacy device portfolios face disproportionate documentation burdens relative to established competitors with extensive installed bases.
Health system procurement consolidation is compressing vendor switching cycles as large purchasing consortia drive standardization across multi-hospital networks. Device selection committees now prioritize enterprise electronic health record integration over standalone monitoring performance specifications. The United States exhibits the most pronounced concentration, where integrated delivery networks negotiate system-wide contracts that marginalize niche hardware suppliers lacking informatics platforms.
Intrapartum Monitors Market Segmentation
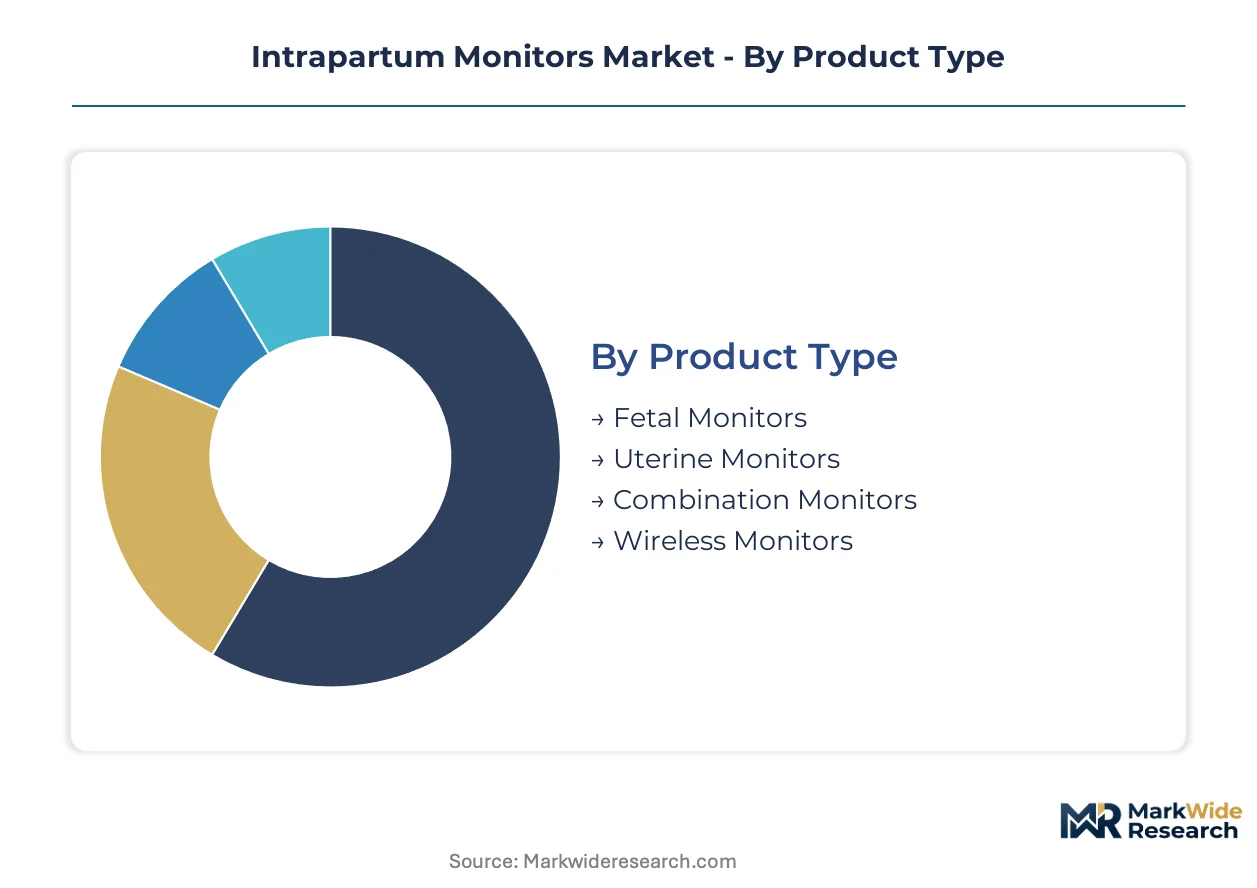
Intrapartum monitor segmentation reveals divergent investment patterns across hardware commoditization and software-enabled service models. Vendors must calibrate portfolio depth against the margin compression from health system procurement consolidation and the premium capture from integrated informatics platforms.
Product Type:
Volume concentrates in established bedside configurations while premium pricing migrates toward mobility-enabled and integrated systems.
- Fetal Monitors:Doppler ultrasound transducers and cardiotocography sensors track fetal heart rate patterns through abdominal or internal electrode placement. Hospital maternity wards in the United States standardize these devices across labor and delivery units, though procurement committees increasingly demand wireless transmission capability as a baseline specification. Today's leader: Fetal Monitors. Tomorrow's challenger: Wireless Monitors.
- Uterine Monitors:Tocodynamometer pressure sensors measure contraction frequency and intensity via strain gauge belts positioned over the fundus. Birthing centers in Germany and France prioritize these systems for ambulatory labor management where maternal mobility reduces intervention rates. Today's leader: Fetal Monitors. Tomorrow's challenger: Wireless Monitors.
- Combination Monitors:Bundled fetal-maternal vital sign systems integrate cardiotocography with maternal blood pressure and pulse oximetry on single platforms.
- Wireless Monitors:Telemetry systems with 30-100 meter transmission ranges to central nursing stations enable untethered labor progression.
Price stratification separates tethered bedside hardware from mobility-premium configurations and integrated software bundles.
End User:
Capital availability and reimbursement frameworks determine device sophistication across institutional and non-institutional settings.
- Hospitals:Large health system purchasing consortia in the United States drive enterprise electronic health record integration requirements and negotiate system-wide standardization contracts. Integrated delivery networks prioritize platforms connecting intrapartum data to central repositories over standalone monitoring performance.
- Clinics:Outpatient obstetric practices with limited capital budgets select refurbished or entry-tier electronic monitors, though EU MDR reclassification is narrowing the availability of legacy devices.
- Home Care:Telemedicine-enabled remote monitoring kits with cellular transmission capability serve high-risk pregnancies in rural catchment areas.
- Birthing Centers:Freestanding midwifery facilities in the Netherlands and United Kingdom favor wireless telemetry for low-intervention birth protocols.
Procurement authority concentrates in hospital networks while clinical autonomy persists in birthing centers and home care segments.
Technology:
Revenue migration follows the shift from capital equipment sales toward recurring software subscriptions and predictive analytics services.
- Electronic Monitoring:Cardiotocography and Doppler ultrasound platforms with algorithm-based pattern recognition dominate installed volume despite margin pressure from hardware commoditization. FDA 510(k) clearance complexity for machine-learning-based fetal distress detection is extending validation timelines beyond traditional hardware pathways.
- Manual Monitoring:Pinard stethoscopes and handheld Doppler devices persist in resource-constrained clinical settings where capital procurement remains restricted.
- Wireless Technology:Bluetooth and proprietary radio-frequency protocols with electromagnetic compatibility testing burdens under Japan's PMDA standards.
- Cloud-Based Systems:Remote data archiving platforms with predictive analytics subscriptions capture disproportionate vendor R&D investment.
Hardware margins compress while software-enabled recurring revenue expands fastest across technology categories.
Application:
Clinical workflow integration determines device selection priority across routine surveillance and acute intervention scenarios.
- Labor Monitoring:Continuous cardiotocography during active labor phases enables obstetric clinicians to detect fetal distress patterns and coordinate timely intervention decisions. Hospital networks deploy wireless configurations to reduce intervention delays during ambulatory labor phases.
- Fetal Surveillance:Extended non-stress testing and biophysical profile assessment for high-risk pregnancies requires prolonged monitoring sessions.
- Maternal Assessment:Integrated vital sign tracking combines uterine activity with maternal hemodynamic parameters.
- Emergency Response:Portable monitor configurations for intrapartum transport and unanticipated complications.
Surveillance intensity stratifies across routine labor management and acute intervention protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Obstetric technology talent clusters in Boston, Basel, and Osaka anchor device development for intrapartum monitoring systems. These biomedical engineering concentrations feed regulatory science capabilities at FDA, Swissmedic, and PMDA respectively.
United States
Large integrated delivery networks in Texas and California drive standardization contracts across multi-hospital maternity systems. FDA 510(k) clearance pathways for algorithm-based fetal monitors impose validation timelines that favor established manufacturers with clinical dossier depth. The Boston-Worcester corridor concentrates venture-backed perinatal technology startups developing wireless telemetry platforms.
Germany
Birthing centers in Bavaria and Baden-Württemberg prioritize ambulatory labor management protocols requiring mobility-enabled monitoring hardware. EU MDR reclassification mandates expanded clinical evidence requirements that lengthen approval timelines for active labor devices. The Munich medical technology cluster hosts engineering teams specializing in cardiotocography algorithm development.
Japan
Metropolitan Tokyo hospitals deploy wireless fetal monitoring systems with proprietary radio-frequency protocols requiring PMDA electromagnetic compatibility validation. Japan's aging obstetric workforce drives automation demand in labor and delivery units across Kansai region facilities. The Nagoya medical device manufacturing base produces precision Doppler ultrasound transducers for domestic and export markets.
China
Provincial hospital networks in Guangdong and Jiangsu expand procurement of combination fetal-maternal monitors as birth centers modernize equipment fleets. NMPA registration requirements for wireless monitoring platforms create compliance barriers for imported devices without domestic clinical trials. The Shenzhen hardware ecosystem enables rapid prototyping of Bluetooth-enabled telemetry systems for cost-sensitive hospital segments.
United Kingdom
NHS England maternity transformation programs fund wireless monitoring adoption in London and Manchester labor units to support home-from-home birth environments. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR device classification standards for active labor monitors. The Oxford-Cambridge arc concentrates digital health ventures developing cloud-based intrapartum data analytics platforms.
Intrapartum Monitors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Three to five multinational health technology groups control premium-tier integrated informatics platforms, while mid-cap specialists concentrate on hardware commoditization strategies. Competitive dynamics center on enterprise electronic health record integration capabilities and manufacturing scale advantages for bundled monitor configurations. M&A activity targets software-enabled predictive analytics firms, and strategic partnerships with cloud infrastructure providers accelerate recurring revenue model transitions.
Within the diversified health technology tier, GE Healthcare and Koninklijke Philips N.V. occupy positions anchored by installed base service revenue streams across North American hospital networks. Shenzhen Mindray Bio-Medical Electronics exemplifies the manufacturing-scale archetype, competing on combination monitor configurations that challenge premium-tier pricing structures. These three entities represent distinct strategic postures: legacy platform leverage, integrated informatics convergence, and cost-engineered hardware bundling respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Koninklijke Philips N.V. |
| Medtronic plc |
| Cardinal Health |
| The Cooper Companies |
| Mindchild Medical |
| Huntleigh Healthcare Limited |
| Analogic Corporation |
| Shenzhen Mindray Bio-Medical Electronics |
| Others |
Supply & Pricing Matrix
Ultrasound transducer component costs and Bluetooth module pricing cascades through intrapartum monitor supply chains into three-tier pricing structures across premium, standard, and economy levels. Tier stratification reflects hardware bundling depth, software subscription attachment rates, and service contract duration commitments negotiated by hospital purchasing consortia.
Pricing Analysis
Bundled hardware-software service splits dominate contract structures as vendors capture recurring revenue from cloud-based data archiving and predictive analytics subscriptions. Price differentiation rests on FDA 510(k) clearance tier and enterprise EHR integration capability, with premium configurations commanding substantial uplifts over standalone monitoring hardware. Cost compression in standard-tier bedside monitors is intensifying because Shenzhen manufacturing scale advantages compress component costs. Clinics and outpatient obstetric practices exhibit highest price sensitivity, while integrated delivery networks prioritize interoperability over unit economics.
Supply Chain Analysis
Ocean freight rate volatility from Asia-Pacific manufacturing hubs elevates landed costs for North American and European hospital procurement committees. Component sourcing concentrates in China, Malaysia, and Mexico, with Doppler ultrasound transducers, pressure sensor assemblies, and radio-frequency telemetry modules feeding final assembly operations. Single-source vulnerability persists for specialized cardiotocography algorithm chipsets. Distribution runs through health system purchasing consortia and group purchasing organizations that aggregate multi-hospital network demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Intrapartum monitor procurement represents a geographic-arbitrage play where EU MDR clinical evidence requirements impose cost barriers that favor established manufacturers with legacy dossiers over emerging entrants lacking European trial infrastructure.
For Market Incumbents: To counter margin erosion from manufacturing-scale competitors, deepen service revenue capture through predictive analytics platform subscriptions and defend installed base positions via EHR integration middleware development. Prioritize FDA 510(k) pathway expertise as algorithm-based diagnostic outputs face extended validation scrutiny.
For New Entrants and Emerging Players: Launch via telemedicine-enabled remote monitoring kits targeting rural home care segments underserved by tethered hospital configurations. White-space opportunity concentrates in cellular-transmission platforms for high-risk pregnancy surveillance, with birthing center wireless telemetry as secondary penetration target.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-based intrapartum data analytics specialists possessing hospital system pilot contracts but pre-scale revenue. Long-term viability over the mid-term projection horizon hinges on recurring software revenue transition completion. Monitor FDA clearance timelines for machine-learning fetal distress pattern recognition as inflection indicator for algorithm-based diagnostic platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Algorithm-based fetal distress detection faces extended validation cycles under evolving premarket requirements. |
| EU MDR Clinical Evidence Pathway | Reclassification mandates robust dossiers that lengthen approval timelines and elevate documentation burdens. |
| Hospital System Partnership | Integrated delivery networks prioritize enterprise EHR connectivity over standalone monitoring performance specifications. |
| Software Companion Development | Cloud-based predictive analytics subscriptions capture recurring revenue from remote data archiving services. |
| Reimbursement Strategy | Value-based obstetric care contracts align device procurement with outcome metrics and intervention reduction targets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with obstetric clinicians, hospital purchasing committee members, biomedical engineers, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR submission databases, hospital procurement records, and CMS Medicare reimbursement data. Bottom-up unit demand estimation and top-down market sizing triangulated volume projections.
Segment-weighting approaches distributed value across product type, end user institutional category, technology platform, and clinical application dimensions throughout the forecast period. CAGRs derived from regression analysis of historical procurement patterns and forward-looking health system capital expenditure intentions, with wireless transmission protocol adoption curves and cloud-based subscription attachment rates as industry-specific demand drivers.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR implementation delays or FDA algorithm validation pathway revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cytology Brush Market
Medical Devices
Esophageal Stethoscopes Market
Medical Devices
Blood Thawing System Market
Medical Devices
Neurovascular Access Catheters Market
Medical Devices
Surgical Robotic Services Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
I.V. Fluid Warmer Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Radiolucent Wrist Fixator Market
Medical Devices
Bone Conduction Hearing Devices Market
Medical Devices
Artificial Vital Organs and Medical Bionics Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
At-Home Vaginal Ph Test Kit Market
Medical Devices
Aortic Cannula Systems Market
Medical Devices
France Respiratory Devices Market