
 Global Small Signal Diode Market | 2026-2036
Global Small Signal Diode Market Size, Share, and Industry Trends Forecast 2026-2036
Global Small Signal Diode Market Foresight
Southeast Asia is reconfiguring its position in discrete semiconductor supply chains as Malaysia and Vietnam add backend packaging capacity for small-signal devices. ROHM leverages captive silicon carbide substrate know-how to differentiate its Schottky small-signal portfolio. STMicroelectronics anchors European sourcing through its front-end fab network in France and Italy. Diodes Incorporated competes aggressively on cost through its Shanghai-based packaging operations.
Small signal diodes are low-power semiconductor devices engineered for current handling below one ampere, typically fabricated on silicon or gallium arsenide wafers using planar epitaxial processes to achieve nanosecond switching speeds and precise forward voltage characteristics. Their primary purpose lies in rectification, signal routing, and circuit protection within high-density electronic assemblies. Switching diodes command the largest volume share across consumer and telecommunications end users, while PIN diodes capture premium positioning in RF circuits for 5G base station deployments. Schottky technology variants are displacing conventional bipolar junction structures in voltage regulation applications where efficiency thresholds have tightened.
FDA oversight of medical device electronics and FCC Part 15 emissions rules in the United States shape product qualification requirements for small signal diodes entering diagnostic and wireless equipment. REACH substance restrictions and RoHS hazardous material limits in Europe constrain lead-frame plating chemistries and mold compound formulations. Stakeholders must monitor how China's GB standards for semiconductor reliability and India's BIS compulsory registration converge with existing IEC frameworks to determine future market access protocols.
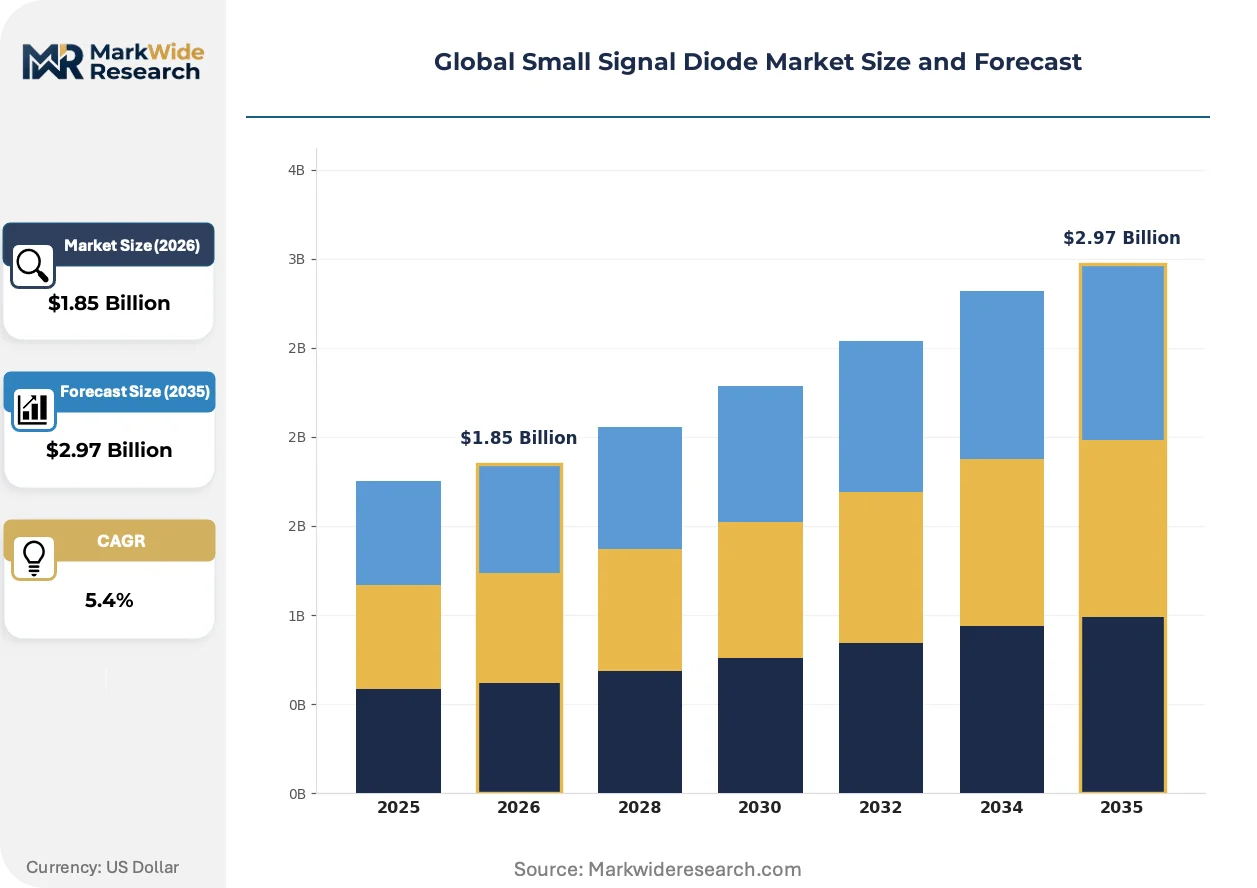
Market Dynamics
Silicon carbide substrate availability is compressing cost structures for high-frequency small-signal diodes, while backend packaging concentration in Southeast Asia creates single-point vulnerability for supply continuity.
Growth Catalysts
- EU RoHS hazardous substance limits:Manufacturers are reformulating lead-frame plating chemistries to eliminate cadmium and hexavalent chromium, accelerating migration to compliant Schottky architectures.
- 5G base station RF modules:PIN diode demand is intensifying for millimeter-wave signal switching in telecommunications infrastructure deployments.
- Seoul metropolitan cluster:Memory and display fab concentration is pulling adjacent small-signal diode procurement into South Korea's component ecosystem.
Market Restraints
- Epitaxial wafer input costs:Silicon carbide substrate pricing volatility constrains margin expansion for high-performance variants.
- Backend packaging concentration:Malaysia and Vietnam now handle critical test-and-tape operations, creating geographic chokepoint risk.
- GB standard convergence timelines:China's semiconductor reliability certification delays market entry for non-domestic suppliers.
Strategic Opportunities
- India BIS compulsory registration:Early compliance with evolving semiconductor standards secures preferential access to electronics manufacturing clusters in Gujarat and Tamil Nadu.
- Medical device electronics:FDA diagnostic equipment rules are tightening signal integrity requirements, opening premium positioning for qualified suppliers.
- Gallium arsenide-silicon convergence:Heterogeneous integration of compound semiconductor substrates with CMOS processes enables new RF performance tiers.
Industry Challenges
- Planar epitaxial process expertise:Shortage of process engineers capable of nanosecond switching optimization limits capacity expansion.
- FCC Part 15 emissions certification:Wireless equipment qualification timelines extend by four to six months, compressing product launch windows.
- REACH substance disclosure:Full supply chain chemical transparency requirements consume significant compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Small Signal Diode Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Switching Diodes, Zener Diodes, PIN Diodes, Tunnel Diodes, Varactor Diodes Technology: Bipolar Junction, Schottky, Gunn, Avalanche, Hot Carrier Application: Signal Processing, RF Circuits, Voltage Regulation, Demodulation, Frequency Multiplication End User: Consumer Electronics, Telecommunications Equipment, Industrial Automation, Aerospace Systems |
| Companies Covered | ROHM, STMicroelectronics, Diodes Incorporated, Toshiba, Texas Instruments, ON Semiconductor, Infineon Technologies, Skyworks Solutions, Vishay Intertechnology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Small Signal Diode Market Shifts & Advancements
Material science breakthroughs and regulatory chemistry constraints are forcing simultaneous evolution in substrate selection and packaging formulations across the small-signal diode value chain.
Gallium arsenide-on-silicon heterostructures are virtualizing traditional discrete PIN diode implementations in 5G millimeter-wave modules. Base station OEMs in South Korea and Japan are adopting these integrated solutions for sub-6 GHz and mmWave arrays. The technology is virtualizing the boundary between discrete and integrated RF components, compressing addressable market definitions.
REACH substance restrictions are prohibiting specific mold compound flame retardants and lead-frame plating chemistries across European-bound shipments. ECHA authorization requirements now cover additional brominated compounds used in high-temperature packaging. Medical and automotive diode suppliers are accelerating halogen-free material qualification to maintain CE marking access.
Consolidated component sourcing is compressing supplier bases as smartphone OEMs reduce qualified vendor lists for power management modules. Tier-one electronics manufacturers now mandate single-source accountability for switching diode families across multiple fab locations. This concentration is most visible in procurement patterns emanating from Shenzhen and Dongguan manufacturing hubs.
Global Small Signal Diode Market Segmentation
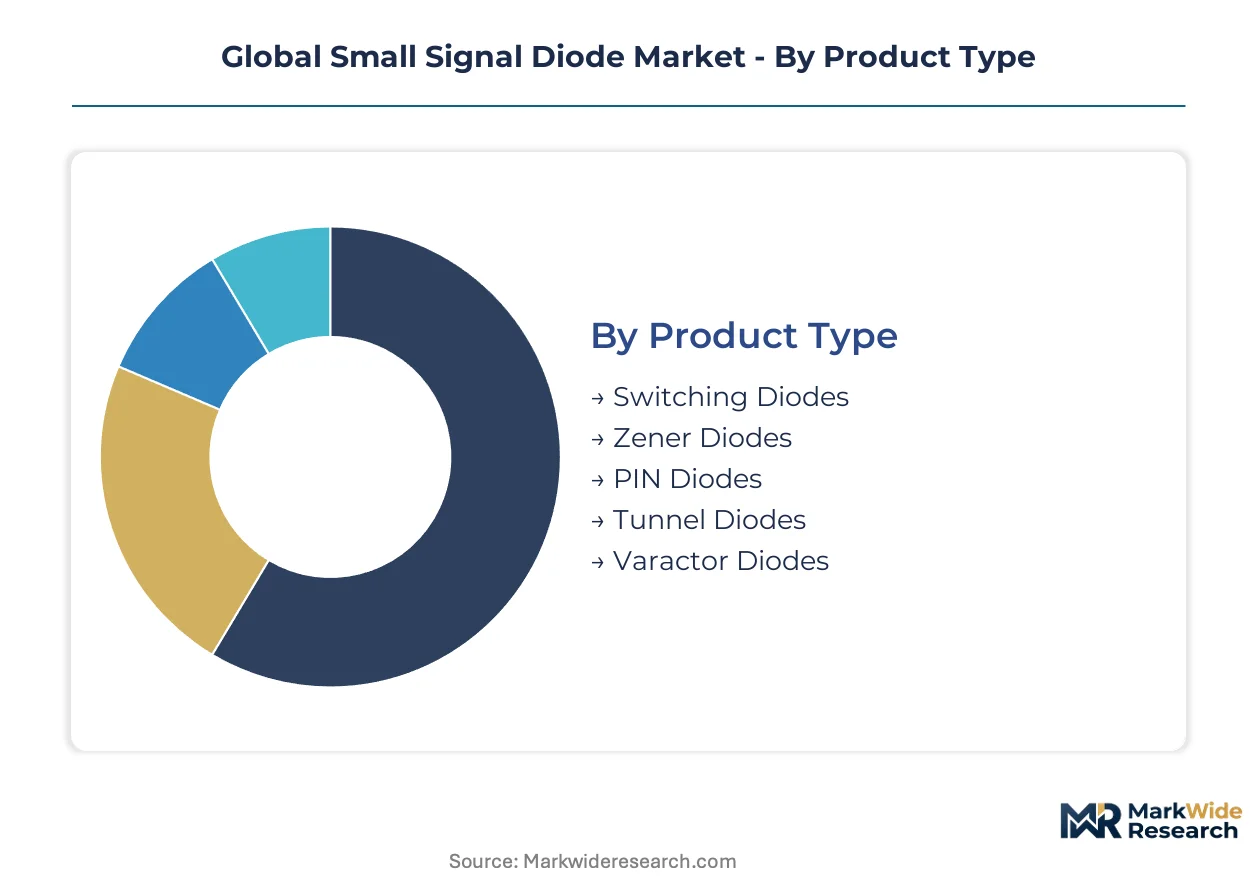
Small signal diode procurement patterns diverge sharply across product architectures and end-use specifications. Voltage regulation demands in automotive electronics favor Zener technologies, while 5G infrastructure deployments pull PIN diode volumes into telecommunications supply chains.
Product Type:
Mature planar epitaxial processes dominate high-volume switching applications, while emerging heterostructure technologies reshape RF performance tiers.
- Switching Diodes:Silicon-based planar devices engineered for nanosecond transition speeds in power management modules. Samsung and Apple procurement teams in Seoul and Cupertino specify these for smartphone battery protection circuits under FCC Part 15 emissions constraints.
- Zener Diodes:Precision voltage reference devices exploiting controlled reverse breakdown characteristics. Automotive ECU manufacturers in Stuttgart and Detroit specify AEC-Q101 qualified variants for load dump protection, with tightening tolerance requirements from 5% to 2% bands.
- PIN Diodes:Intrinsic layer architectures enabling high-frequency RF switching in base station front ends.
- Tunnel Diodes:Quantum tunneling devices for ultra-low-power oscillator circuits.
- Varactor Diodes:Voltage-variable capacitance elements in voltage-controlled oscillators.
Switching diodes handle the majority of throughput; PIN diodes are the fastest mover on share.
Technology:
Cost tier differentiation separates commodity silicon processes from premium compound semiconductor substrates.
- Schottky:Metal-semiconductor junctions delivering sub-0.4V forward drops and negligible reverse recovery. Data center power supply designers in Frankfurt and Singapore specify these for OR-ing diode applications where efficiency losses must stay below 0.5%.
- Bipolar Junction:Conventional P-N structures fabricated on standard silicon epitaxial wafers. Cost-sensitive consumer electronics assemblers in Dongguan and Hanoi default to these for general-purpose rectification where switching speed requirements stay below 100 nanoseconds.
- Hot Carrier:Specialized Schottky variants for microwave detection circuits.
- Avalanche:Breakdown-mode operation for high-voltage protection and noise generation.
- Gunn:Negative differential resistance devices for millimeter-wave oscillation.
Schottky variants command the widest application spread; Gunn technology shows the steepest expansion trajectory in radar modules.
Application:
Volume concentration tracks the geographic clustering of downstream electronics manufacturing.
- RF Circuits:Impedance matching and signal routing in wireless infrastructure. Ericsson and Nokia procurement specifications for 5G massive MIMO arrays in Tampere and Oulu demand PIN diode switches with sub-1 dB insertion loss across 24-40 GHz bands.
- Voltage Regulation:Precision reference and protection functions in power delivery networks. Medical device OEMs in Massachusetts and Minnesota specify these for FDA 21 CFR Part 820 compliant diagnostic equipment where signal integrity affects measurement accuracy.
- Signal Processing:Waveform conditioning in analog front ends.
- Demodulation:Envelope detection in receiver architectures.
- Frequency Multiplication:Harmonic generation in synthesizer circuits.
RF circuits absorb the highest absolute volumes; voltage regulation is climbing the fastest on specification intensity.
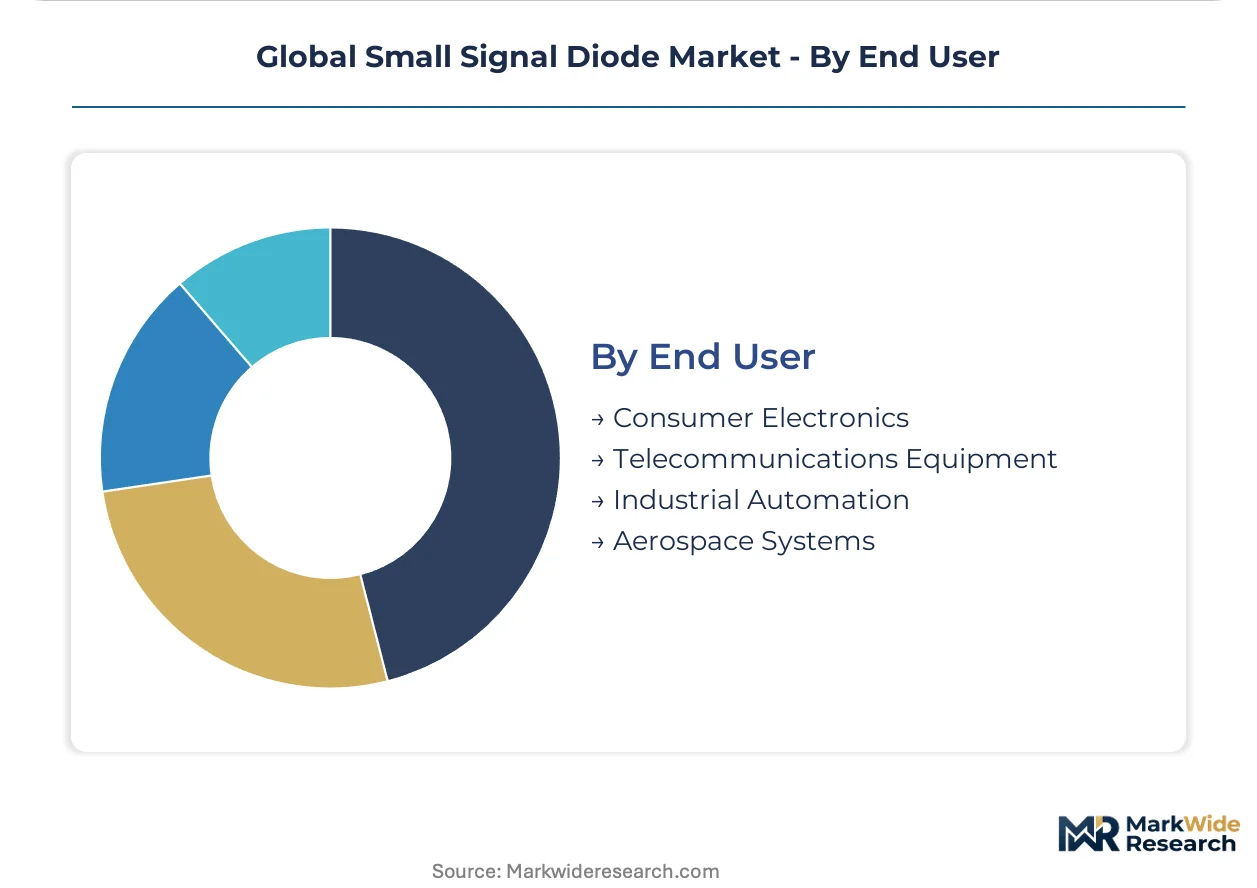
End User:
Customer type determines certification burden and pricing tolerance across the value chain.
- Consumer Electronics:High-volume, cost-optimized procurement for smartphones, wearables, and computing devices. Shenzhen-based ODMs qualify switching diode suppliers against MIL-STD-202G shock and vibration requirements for flagship handset programs.
- Telecommunications Equipment:Infrastructure-grade reliability specifications for base stations and optical networks. Nokia's procurement specifications in Espoo mandate 20-year operational life for outdoor-rated PIN diode modules under ETSI EN 300 019 environmental stress testing.
- Industrial Automation:Harsh-environment operation in motor drives and process control.
- Aerospace Systems:Radiation-hardened and high-reliability specifications for satellite and avionics applications.
Consumer electronics generates the highest unit volumes; telecommunications equipment shows the strongest pricing power on technical differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Discrete packaging operations cluster heavily in Southeast Asian economies, while front-end fabrication concentrates in East Asian and European manufacturing corridors. Malaysia and Vietnam absorb critical test-and-tape functions for small-signal devices, creating geographic dependencies that shape procurement risk assessments.
United States
FCC Part 15 emissions certification requirements govern small-signal diode qualification for wireless equipment entering diagnostic and telecommunications markets. FDA oversight of medical device electronics tightens signal integrity specifications for suppliers targeting diagnostic equipment manufacturers in Massachusetts and Minnesota. Dallas-Fort Worth anchors significant analog semiconductor design activity, with procurement teams specifying AEC-Q101 qualified variants for automotive ECU programs.
Germany
Automotive ECU manufacturers in Stuttgart specify Zener diodes with tightening tolerance bands from 5% to 2% for load dump protection circuits. REACH substance restrictions and ECHA authorization requirements constrain mold compound flame retardants and lead-frame plating chemistries for European-bound shipments. Bavaria hosts precision voltage reference device engineering for industrial automation and medical equipment applications.
China
GB standards for semiconductor reliability certification create entry delays for non-domestic suppliers seeking access to electronics manufacturing clusters. Shenzhen and Dongguan manufacturing hubs concentrate smartphone OEM procurement teams that mandate single-source accountability for switching diode families. MIIT oversight shapes domestic qualification protocols for 5G base station RF module deployments.
South Korea
Memory and display fab concentration around Seoul pulls adjacent small-signal diode procurement into the national component ecosystem. MFDS regulatory frameworks govern medical device electronics incorporating signal routing components. Busan-Ulsan manufacturing corridors host backend packaging operations serving Samsung and Apple supply chains under FCC Part 15 emissions constraints.
Japan
METI industrial policy supports gallium arsenide-on-silicon heterostructure development for 5G millimeter-wave module integration. Kansai region engineering teams collaborate with base station OEMs on sub-6 GHz and mmWave array implementations. JIS standards convergence with IEC frameworks determines qualification pathways for RF circuit components targeting telecommunications infrastructure.
Global Small Signal Diode Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in discrete semiconductor supply chains. The vendor base organizes around three strategic archetypes: integrated device manufacturers with captive substrate capabilities, fabless designers outsourcing fabrication to foundry partners, and specialized packaging houses concentrating backend operations. Competitive positioning depends on M&A activity consolidating qualified vendor lists and capacity expansion in Southeast Asian test-and-tape facilities.
Among Japanese integrated device manufacturers, ROHM and Toshiba exemplify substrate-differentiated positioning through silicon carbide process expertise. STMicroelectronics anchors European sourcing archetypes through front-end fab network concentration in France and Italy. Diodes Incorporated occupies a cost-competitive position through Shanghai-based packaging operations serving high-volume consumer electronics procurement teams.
| Leading Market Players |
|---|
| ROHM |
| STMicroelectronics |
| Diodes Incorporated |
| Toshiba |
| Texas Instruments |
| ON Semiconductor |
| Infineon Technologies |
| Skyworks Solutions |
| Vishay Intertechnology |
| Others |
Supply & Pricing Matrix
Overcapacity in Southeast Asian test-and-tape facilities is compressing contract packaging rates while concentrating bargaining power among Samsung and Apple procurement teams in Seoul and Cupertino. This utilization dynamic forces suppliers to absorb silicon carbide substrate volatility through margin compression rather than price pass-through.
Pricing Analysis
EU RoHS hazardous substance limits dictate the pricing tier structure by imposing compliance cost differentials across lead-frame plating chemistries. Three-tier pricing structure across premium, standard, and economy levels separates AEC-Q101 automotive-qualified variants from general-purpose consumer grades and unbranded commodity offerings. Cost compression in standard-tier switching diodes is intensifying because Diodes Incorporated's Shanghai packaging operations compete aggressively on unit economics. Consumer electronics ODMs in Dongguan exhibit the highest price sensitivity, while medical device OEMs in Massachusetts and Minnesota tolerate premium positioning for FDA 21 CFR Part 820 compliant signal integrity specifications.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for front-end fab equipment and epitaxial wafer inputs. Taiwan, South Korea, and Japan anchor high-purity silicon substrate production, while Malaysia and Vietnam handle critical backend test-and-tape operations. Raw material dependencies center on silicon carbide boules, gallium arsenide wafers, and halogen-free mold compounds. Single-source vulnerability concentrates in Malaysian packaging corridors serving Samsung and Apple supply chains. Distribution runs through consolidated electronics manufacturing service providers in Shenzhen and Dongguan that mandate single-source accountability across multiple fab locations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as gallium arsenide-on-silicon heterostructures virtualize traditional discrete PIN diode implementations, creating niche openings for specialized substrate suppliers and heterogeneous integration specialists.
For Market Incumbents: Entrench position through captive silicon carbide substrate capabilities and AEC-Q101 certification depth that commodity competitors cannot replicate. Add backend capacity in Vietnam to dilute Malaysian geographic concentration risk. Prioritize halogen-free material qualification ahead of REACH substance disclosure deadlines to defend CE marking access against emerging packaging houses. For New Entrants and Emerging Players: Medical device electronics in Massachusetts and Minnesota represent the most penetrable entry point for qualified suppliers capable of FDA 21 CFR Part 820 compliance. India's BIS compulsory registration pathway offers preferential access to Gujarat and Tamil Nadu manufacturing clusters before standard convergence tightens. Lead with heterogeneous integration capabilities for 5G millimeter-wave modules rather than competing on planar epitaxial process maturity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automotive Zener diode suppliers with AEC-Q101 qualification depth and multi-year platform supply agreements. Long-term viability over the projection horizon favors specialists with backward integration into silicon carbide substrate production. The signal to monitor is consolidation in Southeast Asian test-and-tape capacity as Malaysian and Vietnamese facilities attract strategic buyer interest.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Backward Integration | ROHM's captive wafer production insulates margin structures from input volatility. |
| REACH-Compliant Material Qualification | Halogen-free mold compound certification secures CE marking access for European-bound shipments. |
| India BIS Registration Early Compliance | Preferential positioning in Gujarat and Tamil Nadu electronics manufacturing clusters ahead of competitors. |
| Gallium Arsenide-on-Silicon Heterostructure Development | METI-supported Japanese engineering enables sub-6 GHz and mmWave array integration for 5G infrastructure. |
| Southeast Asian Packaging Capacity Expansion | Vietnamese test-and-tape facilities dilute Malaysian geographic chokepoint risk for supply continuity. |
Research Methodology
Desk research of SEC semiconductor filings, IEC reliability standards documentation, and customs trade data preceded structured interviews with fab operations directors, procurement leads at smartphone OEMs, packaging house engineers, and automotive Tier 1 supplier quality managers. Primary fieldwork captured planar epitaxial process expertise constraints and REACH compliance burden assessments. Secondary validation drew from ECHA substance restriction databases, MIIT domestic qualification protocols, and FDA 21 CFR Part 820 guidance documents. Bottom-up unit demand modeling and top-down value chain triangulation converged on segment-level outputs.
Assumptions held fixed include current EU RoHS substance limits, FCC Part 15 emissions certification timelines, and GB standard convergence trajectories; variables tested include silicon carbide substrate pricing volatility and gallium arsenide-on-silicon adoption rates. The analytical framework modeled product type, technology architecture, application specification, and end-user certification tier across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated 5G base station deployment schedules and automotive ECU content per vehicle trends.
Macroeconomic conditions sit as an overlay; deviation in semiconductor capital expenditure cycles or electronics manufacturing relocation patterns would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substrate technology transition timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Metal-Semiconductor-Metal Photodetector Market
Semiconductor Devices
Chip Crusher Market
Semiconductor Devices
Global Transistor Market
Semiconductor Devices
Ram BOP Market
Semiconductor Devices
Rad-Hard Mosfets Market
Semiconductor Devices
Varactor Diode Market
Semiconductor Devices
Coated Silicon Wafer Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
Gaming GPU Market
Semiconductor Devices
Semiconductor Wafer Frame Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Silicon Wafer Market