
 Glue Pen Market | 2026-2036
Glue Pen Market Size, Share, and Industry Trends Forecast 2026-2036
Glue Pen Market Analytics
Educational procurement is consolidating as a dominant demand channel for glue pens, overtaking traditional hobby retail in institutional volume. Elmer's anchors this shift through curriculum-aligned product lines and classroom-focused distribution. Kuretake competes with premium archival formulations targeting art-school supply chains. Scotch leverages its office-supply heritage to sustain placement in administrative and educational settings simultaneously.
A glue pen is a handheld dispensing device containing viscous adhesive in a pen-style barrel, typically featuring a precision nib of 0.7 mm to 2 mm and formulations ranging from PVA emulsions to acrylic copolymers, designed for controlled application in detailed bonding tasks. Water-based glue pens lead volume due to safety profiles suitable for child-accessible products, while hot-melt variants command higher margins in industrial woodworking applications where cure speed determines throughput. The arts and crafts application segment dominates value generation, though packaging represents the fastest-growing use case as e-commerce fulfillment drives demand for portable sealing tools.
REACH in Europe restricts solvent-based volatile organic compounds, compelling reformulation toward water-based systems. The EPA and OSHA in the United States enforce workplace chemical exposure limits that shape industrial-grade product specifications. Stakeholders must monitor evolving chemical safety frameworks across multiple jurisdictions to anticipate compliance-driven material substitutions.
Market Dynamics
REACH compliance in Europe is forcing wholesale reformulation away from solvent-based systems toward water-based adhesives, compressing margins for legacy producers while opening procurement pathways for compliant suppliers.
Growth Catalysts
- Educational procurement consolidation:School districts and universities are standardizing on precision adhesive tools for STEM curricula, creating institutional volume anchors that sustain manufacturer throughput.
- E-commerce packaging automation:Fulfillment centers are adopting portable sealing tools for last-mile damage prevention, driving demand for fast-cure hot-melt variants in logistics operations.
- REACH chemical restrictions:Europe's tightening volatile organic compound limits are accelerating substitution toward child-safe water-based formulations in consumer-accessible product lines.
Market Restraints
- Petrochemical feedstock volatility:Acrylic copolymer and PVA emulsion costs fluctuate with crude oil derivatives, squeezing formulation economics for mid-tier producers without long-term supply contracts.
- Specialty resin supply concentration:Germany and Japan dominate high-purity adhesive polymer production, creating geographic single-source risk for precision nib formulations.
- Cure-speed limitations:Water-based systems require 30-60 minute set times versus 30-second hot-melt bonds, excluding them from high-throughput industrial woodworking where throughput determines equipment selection.
Strategic Opportunities
- India maker-space expansion:Urban fabrication labs and design institutes in Bangalore and Mumbai are creating demand for archival-grade precision tools previously unavailable through domestic distribution.
- Biodegradable formulation mandates:EU Green Deal packaging regulations are creating procurement preference for compostable adhesive systems in sustainable consumer goods.
- Direct-to-educator subscription channels:Curriculum-aligned replenishment programs are bypassing traditional school supply distributors, capturing lifetime value through recurring classroom orders.
Industry Challenges
- Formulation chemist scarcity:The specialized expertise required to balance viscosity, cure chemistry, and safety profiles for precision nibs is concentrated among aging technical workforces in Germany and Japan.
- Multi-jurisdiction certification timelines:Simultaneous EPA, OSHA, and REACH compliance documentation extends product launch cycles by 18-24 months for cross-border adhesive launches.
- Legacy equipment retrofit costs:Converting solvent-based production lines to water-based systems requires capital outlays for humidity-controlled curing chambers and modified dispensing machinery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glue Pen Market |
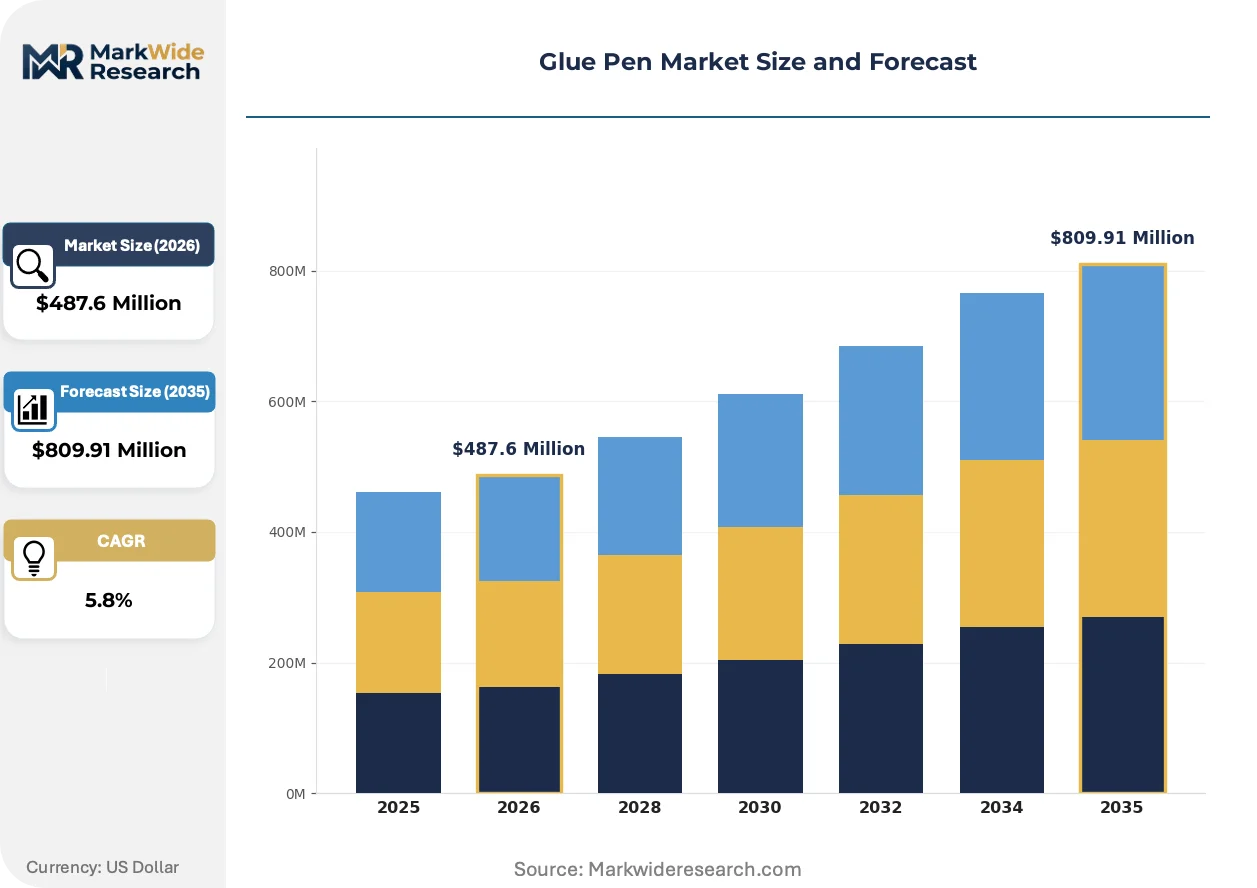
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Hot Melt, Pressure-Sensitive End User: Educational Institutions, Craft Enthusiasts, Home Users, Industrial Applications Application: Arts & Crafts, Office Supplies, Packaging, Woodworking Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | Hobbycraft, Kuretake, Elmer's, EK Tools, Scotch, Zig, Tonic, Aleene's, Tombow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glue Pen Market Evolving Landscape
Reformulation chemistry and distribution channel restructuring are compressing traditional competitive advantages while enabling new entrants to capture institutional procurement flows previously dominated by heritage brands.
Biodegradable starch-based adhesives are expanding into premium craft and educational segments where compostability commands price premiums. Artisan supply retailers and sustainability-focused school districts are adopting these systems despite 40% longer cure times. The technology is expanding into gift packaging and paper-engineering applications where bond strength requirements remain modest.
REACH Annex XVII restrictions on toluene and xylene in consumer products are eliminating solvent-based precision pens from European retail shelves. Formulators are accelerating water-based acrylic copolymer development to preserve nib precision without volatile organic compounds. Germany's Federal Institute for Risk Assessment is tightening child-safety testing protocols, extending certification timelines for new entrants.
Maker-space and fab-lab procurement is consolidating through cooperative purchasing agreements that bypass traditional hobby-store distribution. Technical education programs in the United States and Japan are aggregating demand through shared supplier contracts, compressing margins for distributors while rewarding direct manufacturer relationships. This concentration is most visible in metropolitan districts with established maker culture infrastructure.
Glue Pen Market Segmentation
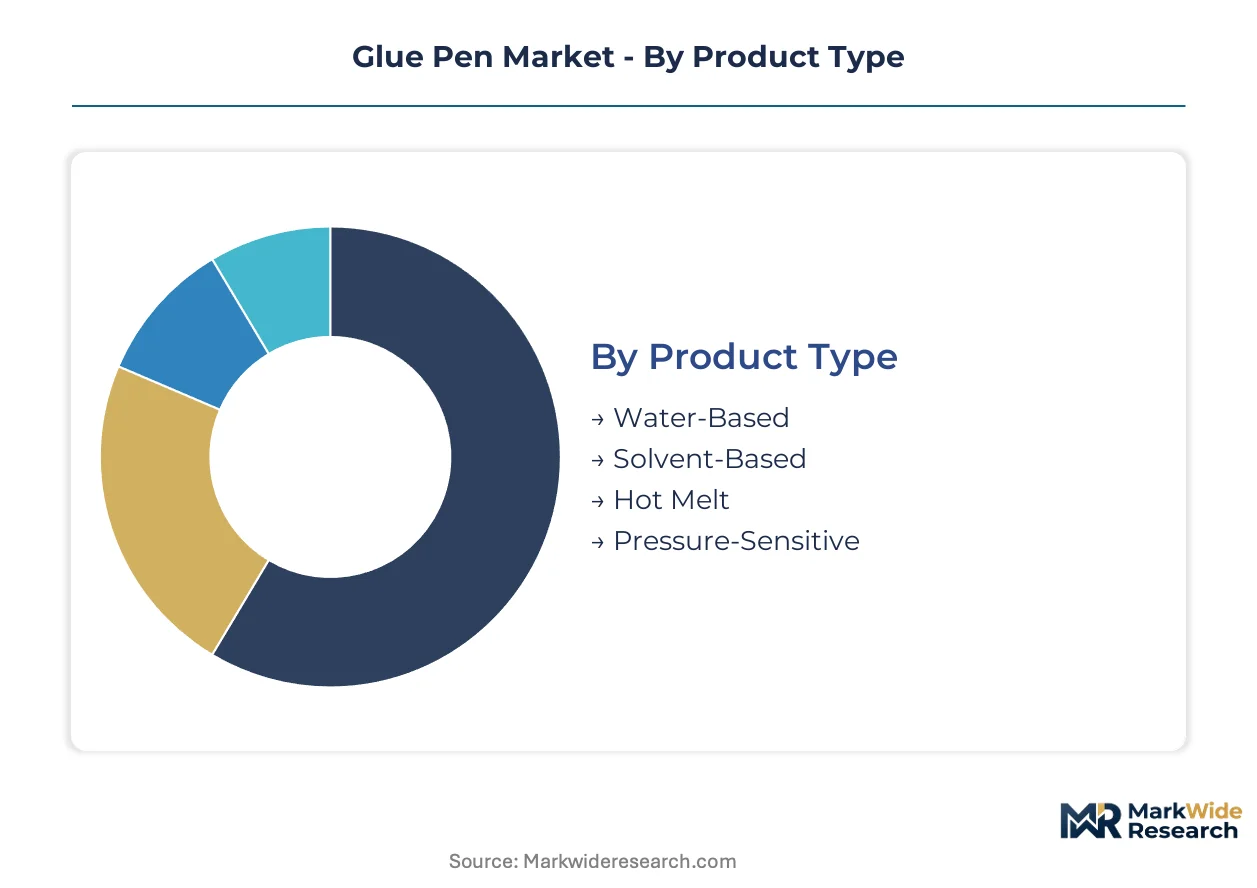
Glue pen manufacturers navigate four distinct segmentation axes where buyer priorities diverge sharply on safety certification, precision requirements, and procurement scale. Product chemistry and end-user risk profiles determine formulation investments, while application-specific cure speeds and distribution access shape competitive positioning.
Product Type:
Buyers differentiate primarily by safety compliance tier and operational environment—child-accessible products demand non-toxic water-based systems, while industrial users prioritize throughput over exposure risk.
- Water-Based:PVA emulsion formulations with viscosity calibrated for 0.7-2mm precision nibs. Educational procurement in Germany and Japan concentrates here, driven by REACH child-safety mandates and institutional liability protocols.
- Solvent-Based:Acrylic copolymer systems delivering rapid tack and moisture resistance. Woodworking shops in the United States sustain residual demand despite EPA workplace exposure limits compressing allowable applications.
- Hot Melt:Thermoplastic adhesive dispensing at 120-180°C for 30-second cure cycles. E-commerce fulfillment centers adopt these for carton sealing velocity where throughput economics override equipment costs.
- Pressure-Sensitive:Tackified elastomer formulations allowing repositionable bonds. Gift packaging and paper engineering applications favor these for assembly flexibility where permanent adhesion risks material damage.
Volume sits with Water-Based; growth tilts toward Hot Melt.
End User:
Procurement scale and specification authority separate institutional buyers from discretionary consumers, with curriculum mandates and safety liability driving standardization at the top of the pyramid.
- Educational Institutions:School districts and universities with consolidated STEM supply contracts. K-12 systems in the United States and Japan specify archival-grade precision tools through cooperative purchasing agreements that bypass retail markup.
- Craft Enthusiasts:Individual makers and artisan communities seeking specialty formulations. Maker-spaces in Bangalore and Mumbai aggregate this demand through shared supplier relationships previously unavailable domestically.
- Home Users:Occasional consumers purchasing through mass retail or online channels. Price sensitivity dominates, with safety certifications serving as primary quality signals for child-accessible storage.
- Industrial Applications:Manufacturing facilities integrating precision dispensing into production lines. Furniture assembly operations in Germany specify hot-melt variants where cure speed determines equipment ROI calculations.
Institutional procurement concentrates volume; maker-space aggregation is expanding most quickly.
Application:
Bond strength requirements and substrate compatibility dictate formulation selection, with paper-fiber applications tolerating lower-spec adhesives than load-bearing wood joints.
- Arts & Crafts:Paper-to-paper bonding with modest strength requirements. Archival formulations for art schools command price premiums based on acid-free longevity certifications.
- Office Supplies:Document repair and presentation assembly. Administrative settings in Japan favor precision nib control for delicate paper handling without bleed-through.
- Packaging:Carton sealing and gift-wrap finishing. E-commerce fulfillment drives adoption of portable hot-melt tools for last-mile damage prevention.
- Woodworking:Veneer attachment and detail joinery where clamping is impractical. Industrial shops exclude water-based systems due to 30-60 minute set times incompatible with throughput targets.
Arts & Crafts anchors value; Packaging shows the steepest expansion trajectory.
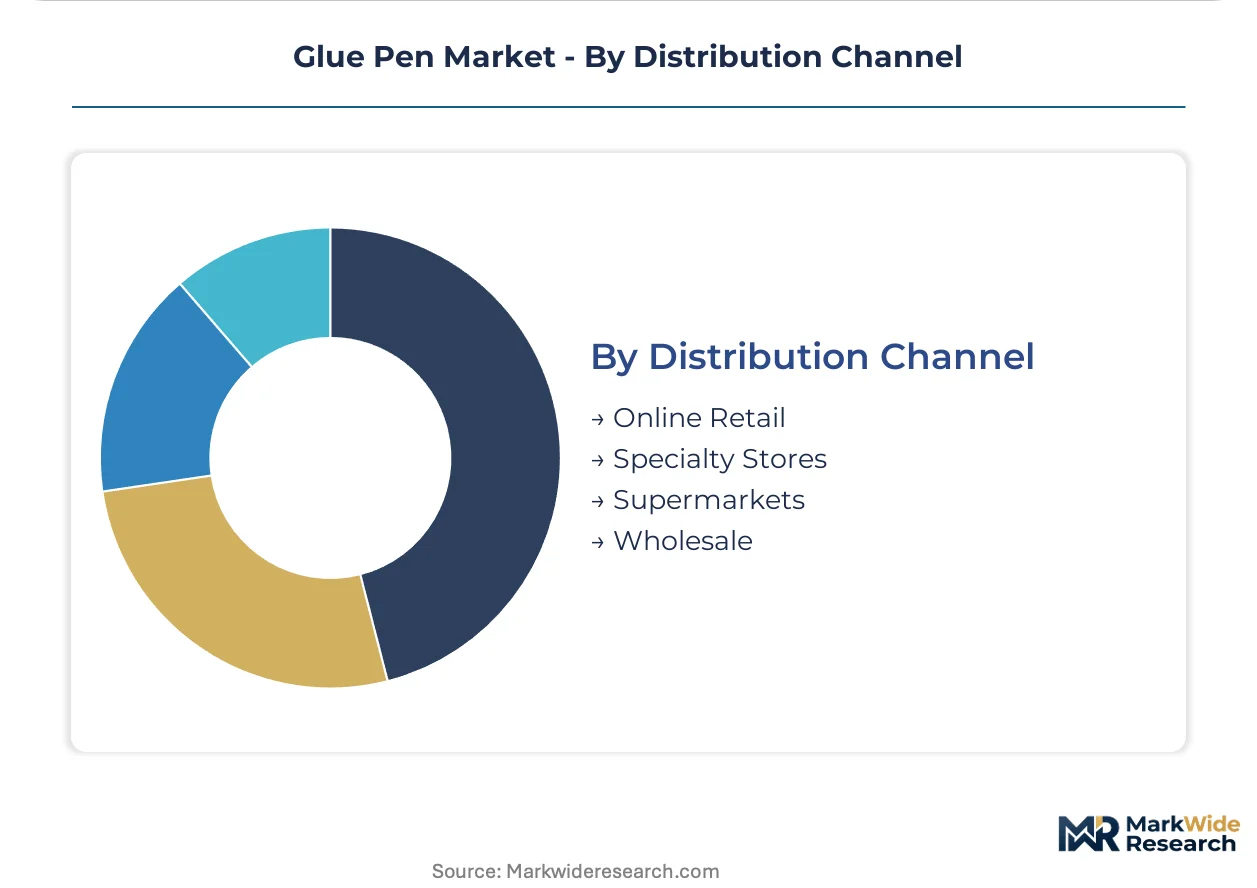
Distribution Channel:
Channel selection reflects buyer urgency, specification complexity, and volume scale—with direct manufacturer relationships capturing institutional flows while retail serves fragmented demand.
- Online Retail:Amazon and specialized craft marketplaces serving geographically dispersed enthusiasts. Subscription replenishment programs for educators are bypassing traditional school supply distributors.
- Specialty Stores:Artisan supply retailers curating archival and sustainability-certified products. These channels capture biodegradable starch-adhesive premiums in EU markets.
- Supermarkets:Mass-market placement for standard water-based school glues. Elmer's dominates this channel through curriculum-aligned packaging and back-to-school seasonal concentration.
- Wholesale:Industrial distributors serving manufacturing procurement with volume pricing. Hot-melt equipment and adhesive refills move through these channels on 12-month supply contracts.
Supermarkets move the highest unit volumes; direct-to-educator digital channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Hamburg drive manufacturing concentration for precision adhesive tools, while educational procurement reforms in Japan and curriculum standardization in the United States reshape demand geography across three continents.
United States
School districts in Texas and California consolidate STEM supply contracts through cooperative purchasing agreements, bypassing traditional retail markup. EPA workplace exposure limits under the Toxic Substances Control Act constrain solvent-based formulations in industrial settings. Maker-spaces in Austin and San Francisco aggregate demand through shared supplier relationships, compressing distributor margins.
Germany
REACH Annex XVII restrictions on toluene and xylene eliminate solvent-based precision pens from European retail channels, forcing wholesale reformulation. The Federal Institute for Risk Assessment tightens child-safety testing protocols, extending certification timelines. Industrial woodworking clusters in Baden-Württemberg specify hot-melt variants where cure speed determines equipment ROI calculations.
Japan
METI procurement guidelines standardize archival-grade precision tools for technical education programs in Kansai and Kanto regions. JIS safety certifications serve as mandatory quality signals for child-accessible products. Art-school supply chains in Osaka and Tokyo sustain premium positioning for acid-free formulations through direct manufacturer relationships.
India
Urban fabrication labs in Bangalore and Mumbai create demand for archival-grade precision tools previously unavailable through domestic distribution. BIS certification requirements for school supplies accelerate formalization of previously informal supply channels. Design institutes in Maharashtra and Karnataka aggregate procurement through cooperative purchasing agreements, rewarding direct manufacturer engagement over import distributors.
United Kingdom
Department for Education curriculum reforms embed precision adhesive tools in design and technology syllabi across England and Scotland. HSE workplace exposure regulations align with REACH chemical restrictions, compressing allowable solvent-based applications. Specialty retailers in London and Manchester curate sustainability-certified products, capturing biodegradable starch-adhesive premiums in gift packaging segments.
Glue Pen Market Competitive Landscape
Top-tier vendors anchor premium archival and educational segments, while mid-tier producers compete on reformulation speed and REACH compliance. The vendor base stratifies across heritage craft brands, office-supply conglomerates, and precision-tool specialists from Japan and Germany. Three archetypes dominate: curriculum-aligned educational suppliers, premium archival formulators, and industrial hot-melt equipment integrators. M&A activity concentrates on water-based formulation capabilities, while strategic partnerships target direct-to-educator subscription channels.
Within the heritage craft tier, Elmer's represents curriculum-aligned educational positioning through classroom-focused distribution. Kuretake and Tombow exemplify premium archival formulators targeting art-school supply chains with acid-free longevity certifications. Scotch occupies a position bridging office-supply heritage with administrative and educational placement simultaneously. These three anchors demonstrate how geographic origin and naming conventions signal competitive archetype without requiring operational specifics.
| Leading Market Players |
|---|
| Hobbycraft |
| Kuretake |
| Elmer's |
| EK Tools |
| Scotch |
| Zig |
| Tonic |
| Aleene's |
| Tombow |
| Others |
Value Network & Pricing Analysis
Captive polymer production in Germany and Japan anchors both formulation quality and pricing power for precision nib manufacturers, insulating tier-one suppliers from petrochemical volatility while forcing mid-tier competitors into spot-market acrylic copolymer purchases. This integration choice compresses margins for non-integrated players during crude derivative spikes while rewarding backward-controlled supply chains with contract pricing stability.
Pricing Analysis
Short lead-time premiums command pricing power in educational procurement cycles, with curriculum-aligned suppliers capturing 15-20% markups over spot inventory during back-to-school concentration. Three-tier pricing structure across premium archival, standard institutional, and economy mass-market levels differentiates by certification grade and acid-free longevity. Pricing pressure stems from REACH-driven reformulation costs transferring to water-based systems. Home users through supermarkets exhibit highest price sensitivity; art-school supply chains show lowest.
Supply Chain Analysis
Single-source vulnerability sits with high-purity adhesive polymer production concentrated in Germany and Japan, where specialized resin synthesis capabilities remain geographically locked. Raw material dependencies center on acrylic monomers, PVA emulsions, and precision-machined nib components. Tariff exposure on thermoplastic imports threatens hot-melt variant economics. Distribution runs through cooperative purchasing agreements for institutional buyers, bypassing traditional wholesale markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over water-based formulation chemistry and direct educator channels determines sustainable margin capture. Players are pursuing backward integration into specialty resin production to escape geographic single-source risk.
For Market Incumbents: Acquire captive polymer synthesis capabilities in Germany or Japan to secure formulation supply against petrochemical volatility. Consolidate direct-to-educator subscription channels before cooperative purchasing agreements lock out distributor-dependent competitors. Biodegradable starch-adhesive entrants threaten premium positioning; defend through archival certification investments. For New Entrants and Emerging Players: Launch via maker-space cooperative purchasing in Bangalore and Mumbai, where domestic distribution gaps create white-space for archival-grade precision tools. Target India's design institutes with BIS-certified water-based formulations. White-space concentrates in biodegradable packaging adhesives for EU Green Deal compliance. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to office-supply conglomerates seeking curriculum-aligned educational positioning. Long-term viability favors formulators with REACH-compliant water-based chemistry and direct institutional channels. Watch for EU biodegradable mandate acceleration as inflection signal for compostable adhesive premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Resin Production | Germany and Japan polymer capabilities insulate margins from petrochemical volatility. |
| Direct-to-Educator Subscription Channel Launch | Bypassing school supply distributors captures lifetime value through recurring classroom orders. |
| Biodegradable Formulation Certification | EU Green Deal packaging regulations create procurement preference for compostable systems. |
| Maker-Space Cooperative Purchasing Partnership | Urban fabrication labs in India aggregate demand through shared supplier relationships. |
| REACH-Compliant Water-Based Reformulation | Annex XVII restrictions eliminate solvent-based precision pens from European retail. |
Research Methodology
Document review covered customs trade data, adhesive industry association reports, and regulatory filings with ECHA and EPA, complemented by interviews with formulation chemists, educational procurement officers, and specialty retail buyers. Primary fieldwork engaged plant managers at German and Japanese polymer facilities, school district supply coordinators in Texas and California, and distributor heads serving maker-spaces in Bangalore and Mumbai. Secondary validation drew from REACH Annex XVII documentation, BIS certification records, and METI procurement guidelines. Bottom-up demand modeling triangulated against top-down market sizing.
Segment-level projections across product chemistry, end-user archetype, application bond-strength requirement, and distribution channel structure informed volume and value outputs throughout the forecast period. CAGRs derived from regression analysis against educational spending indices, e-commerce fulfillment automation rates, and chemical regulatory enforcement timelines. Industry-specific inputs included STEM curriculum adoption curves, biodegradable packaging mandate implementation schedules, and precision nib manufacturing capacity utilization.
The model assumes a particular technology adoption path; alternative pathways for starch-based biodegradable adhesives would alter the outlook if compostability premiums fail to offset 40% longer cure times. Forecasts reflect assumptions about REACH enforcement consistency, cooperative purchasing consolidation velocity, and petrochemical feedstock stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Adhesive Equipment Market
Adhesives & Sealants
Global Tissue Sealants Market
Adhesives & Sealants
Global Silicone Adhesives and Sealants Market
Adhesives & Sealants
Global Stone and Tile Adhesives and Sealants Market
Adhesives & Sealants
Textile Binders Market
Adhesives & Sealants
UV Glue Market
Adhesives & Sealants
Global Adhesion Promoter Market
Adhesives & Sealants
Asia-Pacific Sealants Market
Adhesives & Sealants
Europe Construction Adhesives and Sealants Market
Adhesives & Sealants
Industrial Wood Adhesives Market
Adhesives & Sealants
Thailand Sealants Market
Adhesives & Sealants
Global Vascular Sealant Market
Adhesives & Sealants
Europe Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Global Dimer Acid Market
Adhesives & Sealants
South Korea Sealants Market
Adhesives & Sealants
Global Epoxy Adhesive Market