
 Asia-Pacific Agricultural Microbial Market | 2026-2036
Asia-Pacific Agricultural Microbial Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Agricultural Microbial Market Outlook
CFU-grade bioformulation standards above 10^9 colony-forming units per gram is reorganizing supplier hierarchies across the Asia-Pacific Agricultural Microbial Market. Bayer Cropscience AG leverages its proprietary fermentation infrastructure to dominate high-count bacterial inoculant supply in Australia. Koppert B.V. specializes in mycorrhizal fungi formulations tailored to tropical soil profiles. Sumitomo Chemical Co., Ltd. anchors its position through integrated research stations in Japan and field validation networks across Southeast Asia.
Agricultural microbials comprise live or dormant microorganisms—bacteria, fungi, protozoa, and viruses—formulated at specified viable cell densities for agricultural application, typically delivered in liquid suspensions or granular carriers to colonize plant rhizospheres and enhance nutrient cycling. Bacterial biofertilizers occupy the largest value share due to established nitrogen-fixation protocols in rice and legume systems, while mycorrhizal fungi formulations command premium positioning in high-value horticulture across China's Shandong and Yunnan provinces. Liquid formulations lead volume throughput because of compatibility with existing drip irrigation infrastructure, though granular formats are gaining traction in rain-fed cropping zones where shelf stability determines adoption rates.
India's FSSAI and BIS frameworks govern microbial product safety thresholds and labeling standards, while China's MEE enforces environmental release protocols for novel biocontrol strains. Australia's APVMA registration requirements create extended market-access timelines that favor incumbents with established toxicology dossiers. Stakeholders must track evolving strain patent landscapes and cooperative procurement consolidation to anticipate where formulation premiums will compress or expand.
Market Dynamics
CFU-grade standardization above 10^9 colony-forming units per gram is compressing supplier margins while elevating technical barriers to market entry across Asia-Pacific microbial formulation networks.
Growth Catalysts
- India's PLI scheme for agrochemical manufacturing:Domestic biofertilizer production capacity is accelerating through subsidized fermentation infrastructure and tax incentives targeting nitrogen-fixing bacterial strains.
- Rice cultivation expansion across Southeast Asia:Microbial inoculant adoption is displacing synthetic nitrogen application in Vietnam, Thailand, and Indonesia as water quality regulations tighten around fertilizer runoff.
- Cooperative farming structures in Maharashtra and Gujarat:Bulk procurement mechanisms enable smallholder aggregation, reducing per-unit microbial amendment costs and driving volume throughput for liquid formulations.
Market Restraints
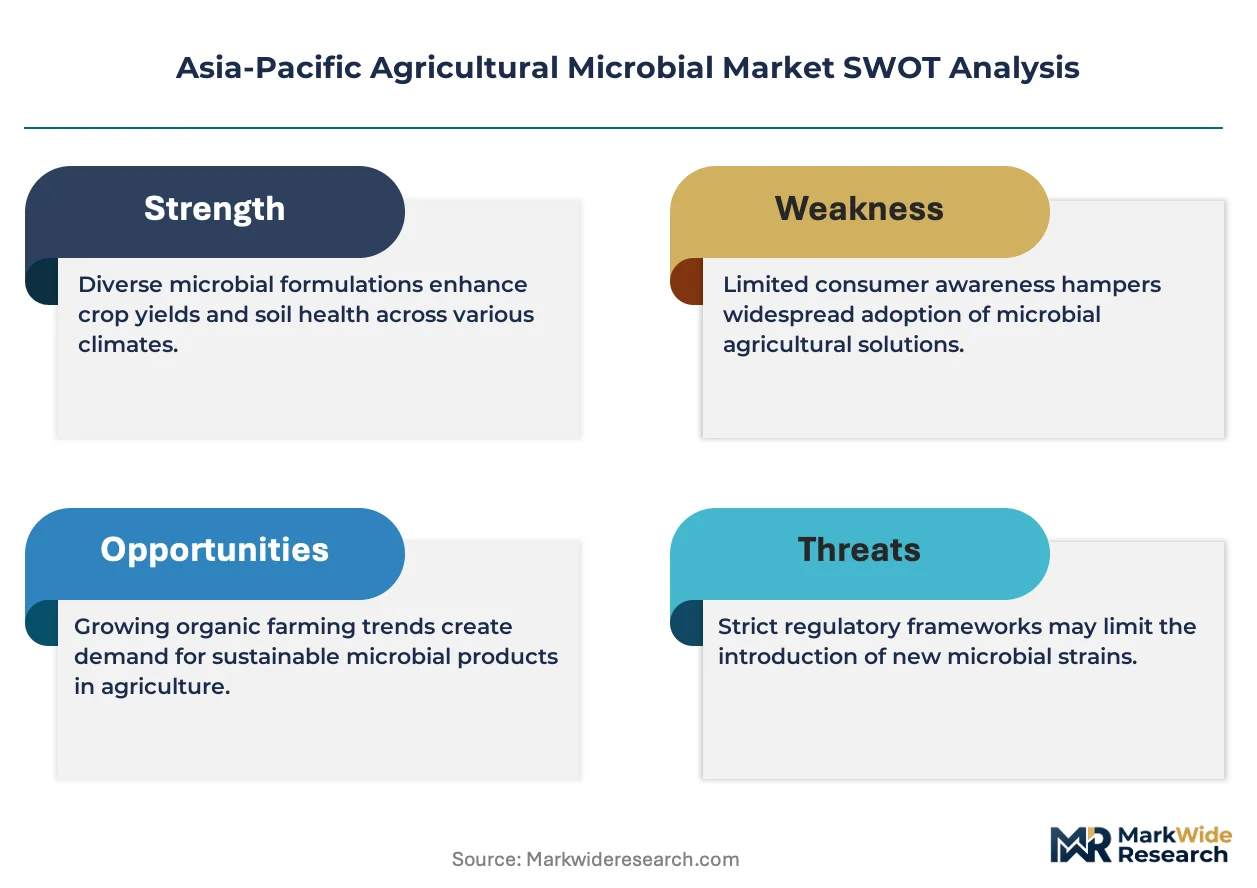
- Extended APVMA registration timelines in Australia:Toxicology dossier requirements create 18-24 month market access delays that favor established incumbents with existing strain libraries.
- Shelf stability limitations in granular carriers:Viability decay rates above 30% during monsoon storage constrain adoption in rain-fed cropping zones across eastern India and Bangladesh.
- Substitution pressure from coated urea:Neem-coated and sulfur-coated synthetic fertilizers retain price advantages in price-sensitive wheat and maize systems across Punjab and Haryana.
Strategic Opportunities
- Underpenetrated horticulture corridors in China's Shandong province:Mycorrhizal fungi applications in protected vegetable cultivation command 3-4x pricing premiums over field crop formulations.
- Dual carbon goals implementation through China's MEE:Carbon credit mechanisms for soil carbon sequestration are creating direct revenue streams for verified microbial carbon banking protocols.
- Drone-based microbial delivery systems:Aerial application compatibility is opening precision agriculture channels in Australia's broadacre wheatbelt and Japan's fragmented rice paddy landscapes.
Industry Challenges
- Strain patent thickets around nitrogen-fixation genetics:Licensing complexity for proprietary Rhizobium and Azotobacter variants is fragmenting R&D pipelines and inflating royalty burdens for domestic Indian manufacturers.
- Integration friction with legacy drip irrigation infrastructure:Biofilm formation in existing emitter networks requires capital-intensive filtration retrofits that delay adoption in Gujarat's progressive farming cooperatives.
- CFU enumeration standardization gaps:Inconsistent viability testing protocols between India's FSSAI and China's GB standards create cross-border shipment rejections and inventory write-downs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Agricultural Microbial Market |
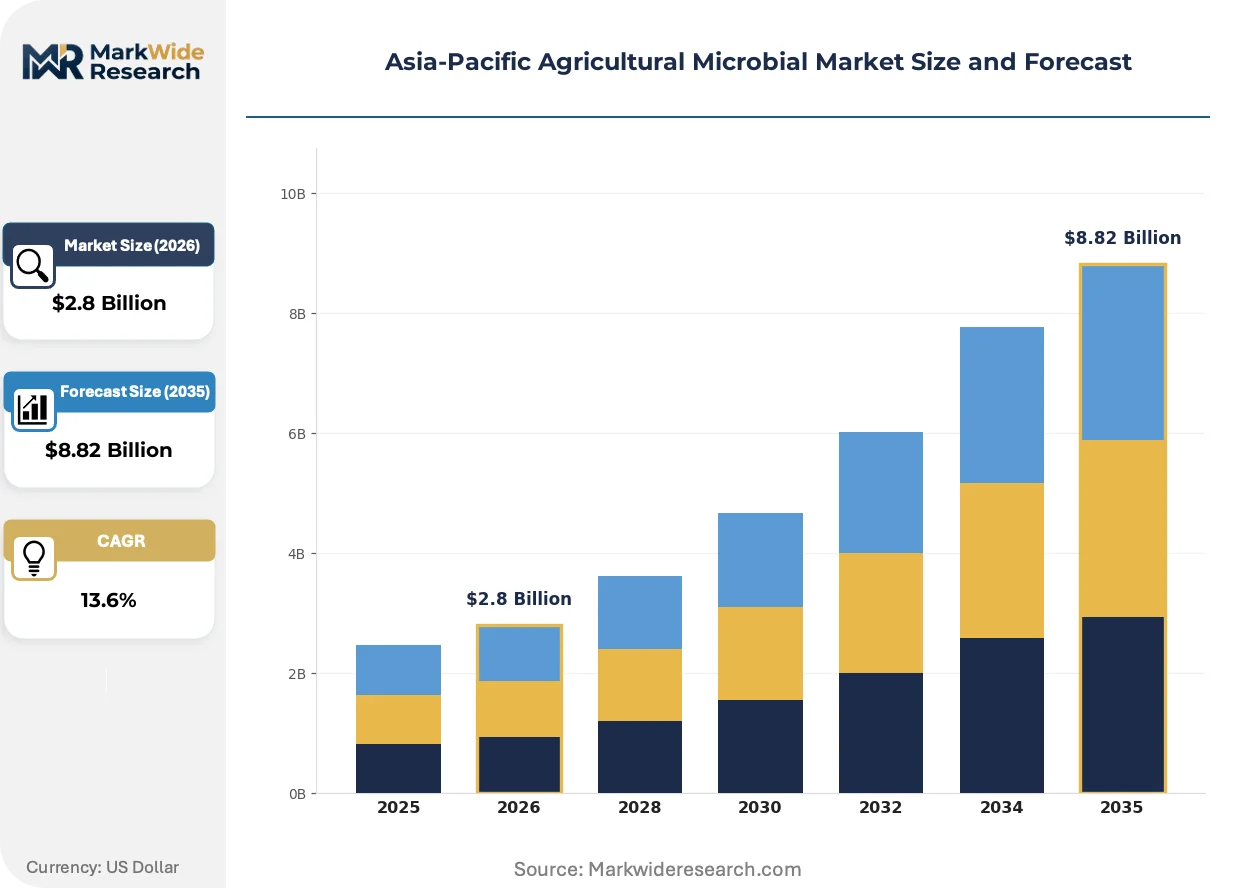
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.82 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Fungi, Protozoa, Viruses Application: Crop Protection, Soil Improvement, Seed Treatment, Biofertilizers Formulation: Liquid, Granular, Powder, Tablet End User: Farmers, Agricultural Cooperatives, Agricultural Research Institutes, Organic Operators |
| Companies Covered | BASF SE, Bayer Cropscience AG, Corteva Agriscience, UPL, Koppert B.V., Syngenta Group, Nufarm Limited, Sumitomo Chemical Co., Ltd., FMC Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Agricultural Microbial Market Strategic Shifts
Encapsulation technologies and precision delivery mechanisms are restructuring how viable microbial loads reach plant rhizospheres, shifting competitive advantage toward formulation chemistry capabilities.
Microencapsulation of bacterial endospores in alginate-chitosan matrices is miniaturizing protective carrier volumes while extending shelf stability from 6 to 18 months. Australian broadacre operators are adopting these concentrated suspensions for aerial seeding compatibility. The technology is miniaturizing logistics costs per viable cell, compressing price points for premium inoculant tiers.
China's MEE environmental release protocols for novel biocontrol strains now mandate field trial documentation across three agro-climatic zones before commercial registration. This regulatory expansion extends development timelines but creates defensible moats for compliant strain libraries. Japanese vegetable cooperatives are accelerating adoption of MEE-registered Trichoderma formulations to preempt supply disruption risks.
Subscription-based microbial replenishment programs are displacing single-season bulk purchases in Vietnam's Mekong Delta rice systems. Input retailers are bundling seasonal soil testing with customized inoculant prescriptions, capturing recurring revenue streams. This behavioral pivot is most visible in commercial farming zones where credit access enables annual payment structures over upfront cash requirements.
Asia-Pacific Agricultural Microbial Market Segmentation
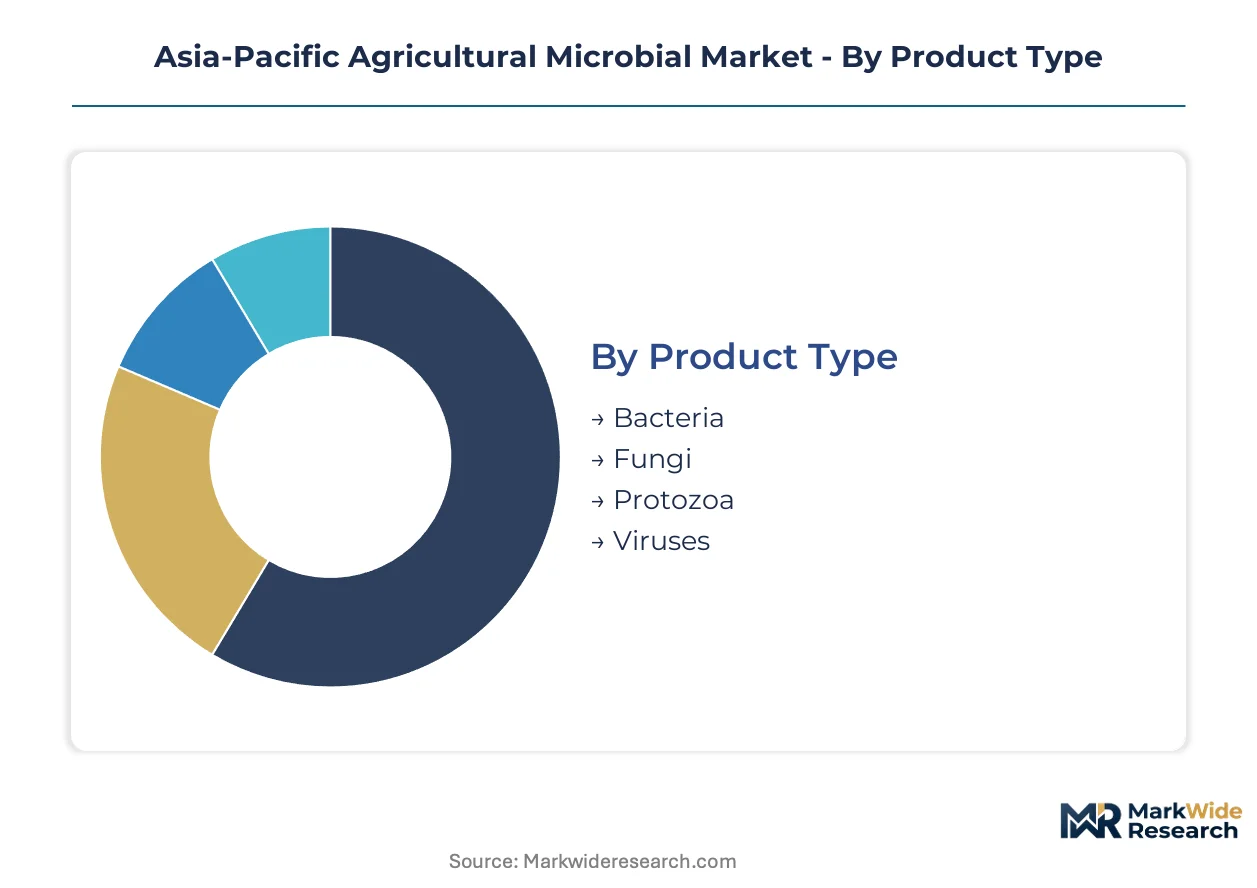
Segmentation in the Asia-Pacific Agricultural Microbial Market reveals how formulation chemistry, microbial taxonomy, and procurement channels intersect to create distinct competitive arenas. Suppliers must align R&D pipelines with the technical requirements of each segment while navigating regulatory fragmentation across national boundaries.
Product Type:
Domestic fermentation capacity in India and China dominates bacterial strain supply, while mycorrhizal fungi formulations remain import-dependent across Southeast Asian markets.
- Bacteria:Nitrogen-fixing Rhizobium and Azotobacter strains constitute the technical core of biofertilizer formulations. Demand clusters in India's Maharashtra and Gujarat cooperative networks, where bulk procurement of high-CFU inoculants displaces synthetic urea in cotton and legume rotations.
- Fungi:Arbuscular mycorrhizal and Trichoderma biocontrol variants command premium positioning in protected horticulture. China's Shandong province drives uptake through vegetable cooperatives seeking soil-borne disease suppression in greenhouse tomato and pepper systems.
- Protozoa:Predatory flagellate formulations for nematode suppression occupy niche positioning in Australia's broadacre wheatbelt, where APVMA-registered biocontrol alternatives face limited domestic manufacturing.
- Viruses:Baculovirus and nucleopolyhedrovirus preparations target lepidopteran pests in high-value fruit orchards across Japan's Kyushu region and Vietnam's Mekong Delta export banana plantations.
Bacterial biofertilizers command the established base. The steepest expansion runs through mycorrhizal fungi applications in China's protected cultivation corridors.
Application:
Cost tier stratification separates commodity field-crop applications from premium horticulture systems, with pricing spreads widening in high-value export agriculture.
- Crop Protection:Biocontrol microbials targeting fungal pathogens and insect vectors compete directly with synthetic pesticide residues in EU-bound export supply chains. Vietnam's dragon fruit and mango export zones drive adoption of Trichoderma and Beauveria formulations to meet maximum residue limits.
- Soil Improvement:Microbial consortia for degraded soil restoration target saline-alkaline patches in Australia's Murray-Darling basin and compacted rice paddy soils in Thailand's central plains. Carbon sequestration verification protocols under China's MEE dual carbon goals create direct revenue linkages for verified soil carbon banking.
- Seed Treatment:On-seed bacterial inoculants for soybean and groundnut face substitution pressure from polymer-coated synthetic nutrition in Punjab's mechanized farming belts, where planting speed priorities favor single-pass application.
- Biofertilizers:Nitrogen-fixation and phosphate-solubilizing formulations anchor volume throughput in India's PLI-subsidized domestic manufacturing expansion, with liquid concentrates dominating drip-irrigation compatible delivery.
Soil improvement applications gain share fastest in carbon-credit-linked verification systems. Biofertilizers retain the volume base across price-sensitive cereal and legume systems.
Formulation:
Volume throughput concentrates in liquid formats compatible with existing fertigation infrastructure, while shelf-stability requirements in rain-fed zones sustain granular demand.
- Liquid:Aqueous suspensions and concentrated broths integrate directly with drip and pivot irrigation networks. Australia's broadacre operators favor liquid delivery for aerial application compatibility in wheat and canola seeding operations.
- Granular:Clay and peat-based carriers extend viability in high-humidity monsoon storage conditions. Eastern India's rain-fed rice zones and Bangladesh delta regions require moisture-resistant formulations with sub-30% decay rates over six-month distribution cycles.
- Powder:Lyophilized and spray-dried preparations serve research institute procurement and small-scale organic operator blending operations, particularly in Japan's fragmented vegetable cooperative structures.
- Tablet:Compressed carrier formats target precision placement in transplant hole applications for high-value horticulture in China's Yunnan province flower and vegetable export clusters.
Liquid formulations command the established base. The steepest expansion runs through microencapsulated concentrates with extended shelf stability for aerial delivery systems.
End User:
Procurement consolidation through cooperative structures compresses per-unit costs for smallholder aggregation, while research institutes drive strain validation and registration pipelines.
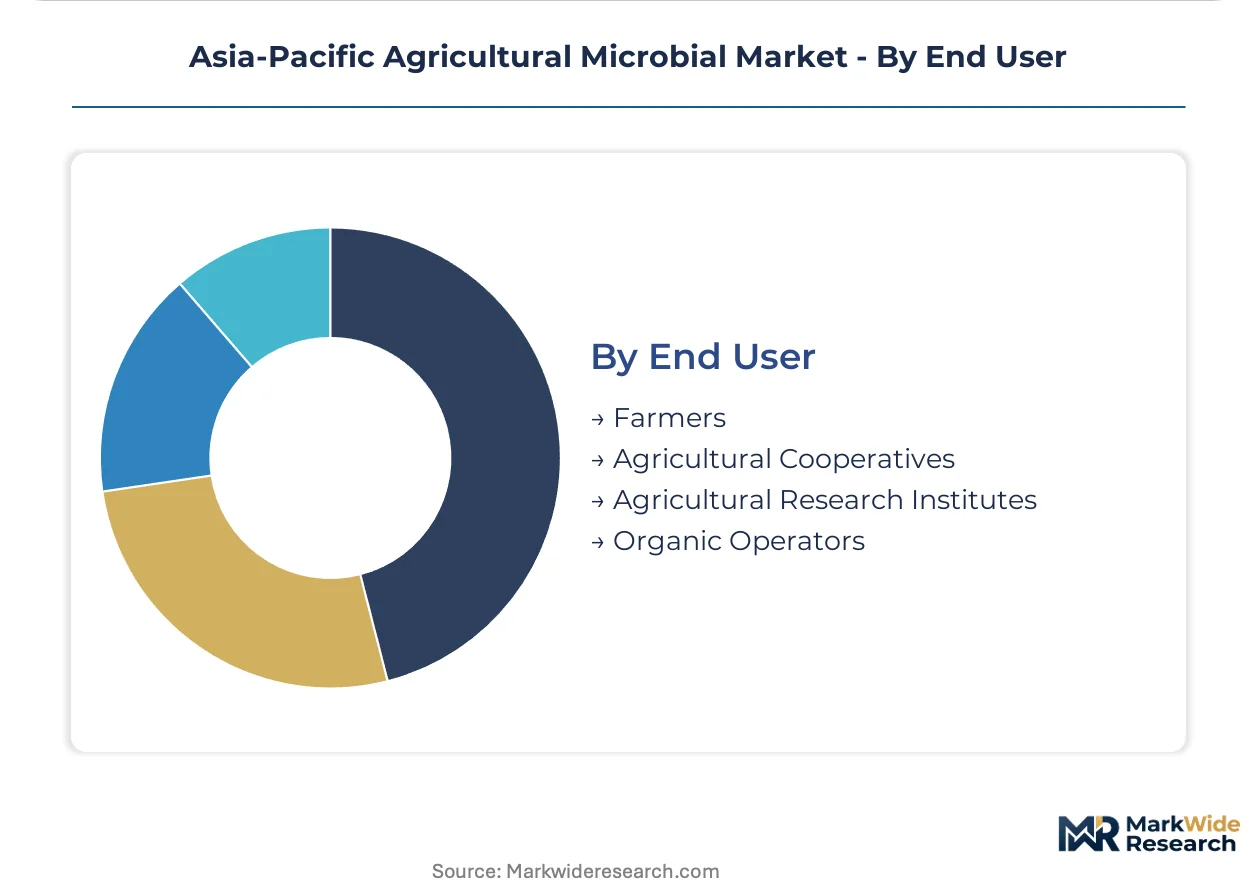
- Farmers:Individual smallholders in India's Bihar and Uttar Pradesh states access microbial inputs through retailer credit schemes and government subsidy programs, with adoption constrained by cash-flow timing mismatches with planting calendars.
- Agricultural Cooperatives:Bulk procurement entities in Maharashtra and Gujarat negotiate volume discounts and technical support packages, enabling CFU-grade standardization across member holdings. Cooperative structures reduce per-hectare amendment costs by aggregating demand across 500-2,000 member farms.
- Agricultural Research Institutes:India's ICAR network and China's CAAS stations conduct multi-locational strain validation trials required for regulatory registration, maintaining germplasm libraries and field trial documentation for MEE and FSSAI submission dossiers.
- Organic Operators:Certified organic farms in Australia's Queensland and Western Australia face mandatory microbial input requirements under organic certification standards, with procurement premiums of 15-25% over conventional equivalents.
Cooperative procurement commands the established base. The steepest expansion runs through subscription-based replenishment programs targeting commercial farming zones with credit-access infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation infrastructure clusters in India and China dominate bacterial strain supply, while mycorrhizal fungi formulations flow through import channels into Southeast Asian horticulture zones. Regulatory divergence between India's FSSAI and China's MEE creates cross-border shipment friction that favors domestic manufacturing investments.
India
Maharashtra and Gujarat cooperative farming structures aggregate smallholder demand into bulk procurement contracts for nitrogen-fixing bacterial inoculants. The PLI scheme subsidizes domestic fermentation capacity expansion for Rhizobium and Azotobacter strains. BIS labeling standards and FSSAI safety thresholds govern product registration timelines in these western state clusters.
China
Shandong and Yunnan provinces drive mycorrhizal fungi uptake in protected vegetable cultivation for export supply chains. MEE environmental release protocols mandate three-zone field trials before novel biocontrol strain registration. The dual carbon goals framework creates revenue linkages for verified soil carbon sequestration through microbial carbon banking protocols.
Australia
Broadacre wheatbelt operators adopt liquid formulations compatible with aerial seeding infrastructure in New South Wales and Victoria. APVMA registration requirements impose 18-24 month toxicology dossier timelines that favor incumbents with established strain libraries. Queensland organic operators face mandatory microbial input requirements under certification standards with 15-25% procurement premiums.
Japan
Kyushu region fruit orchards deploy baculovirus preparations against lepidopteran pests for export-bound produce. METI research stations anchor integrated validation networks for Trichoderma biocontrol formulations. Vegetable cooperatives accelerate MEE-registered product adoption to preempt supply disruption risks in fragmented paddy landscapes.
Vietnam
Mekong Delta rice systems shift toward subscription-based microbial replenishment programs displacing single-season bulk purchases. Water quality regulations tighten around fertilizer runoff, accelerating microbial inoculant displacement of synthetic nitrogen. Dragon fruit and mango export zones drive Trichoderma and Beauveria uptake to meet EU maximum residue limits.
Asia-Pacific Agricultural Microbial Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with proprietary fermentation infrastructure separating high-CFU bacterial suppliers from formulation-assemblers. The market structures around three tiers: integrated agrochemical conglomerates with captive strain libraries, specialized microbial houses with tropical soil expertise, and domestic manufacturers leveraging PLI-subsidized capacity. Consolidation pressure runs through M&A activity targeting regional distribution networks, while R&D pipelines focus on encapsulation chemistry for shelf-stability extension.
Among integrated agrochemical conglomerates, Bayer Cropscience AG anchors high-count bacterial inoculant supply through proprietary fermentation infrastructure in Australia. Koppert B.V. occupies a position within the specialized microbial tier, with mycorrhizal fungi formulations representing tropical soil profile adaptation. Sumitomo Chemical Co., Ltd. exemplifies the integrated research station model, anchoring field validation networks across Southeast Asia through Japan-based development facilities.
| Leading Market Players |
|---|
| BASF SE |
| Bayer Cropscience AG |
| Corteva Agriscience |
| UPL |
| Koppert B.V. |
| Syngenta Group |
| Nufarm Limited |
| Sumitomo Chemical Co., Ltd. |
| FMC Corporation |
| Others |
Value Chain & Pricing Dynamics
Fermentation capacity utilization above 80% in India's PLI-subsidized facilities is compressing unit economics for bacterial inoculants while elevating price floors for mycorrhizal fungi imports into Southeast Asian markets. This scale asymmetry between domestic bacterial production and import-dependent fungal formulations is restructuring procurement hierarchies across cooperative farming networks.
Pricing Analysis
India's BIS labeling standards and FSSAI safety thresholds dictate the pricing tier structure across the Asia-Pacific Agricultural Microbial Market. Three-tier pricing structure across premium, standard, and economy levels separates MEE-registered biocontrol strains from generic bacterial formulations and unbranded commodity inoculants. Price differentiation hinges on CFU-grade certification and cooperative volume aggregation, with Maharashtra's farming cooperatives commanding 20-30% discounts over individual smallholder purchases. Cost compression in standard-tier liquid formulations is intensifying because of PLI-subsidized domestic capacity expansion. Individual farmers in Bihar and Uttar Pradesh exhibit highest price sensitivity due to cash-flow timing mismatches, while Queensland organic operators accept procurement premiums of 15-25% for certification-compliant inputs.
Supply Chain Analysis
Port congestion on Shanghai-Singapore trade lanes is extending lead times for mycorrhizal fungi imports into Vietnam and Indonesia. Geographic supply concentration centers on India and China for bacterial strain fermentation, while the Netherlands and Israel anchor arbuscular mycorrhizal spore supply. Raw material dependencies include molasses feedstock for bacterial culture media, peat and vermiculite for granular carriers, and alginate-chitosan matrices for microencapsulation. Single-source vulnerability runs through proprietary Rhizobium strain libraries controlled by integrated agrochemical conglomerates. Distribution runs through cooperative procurement aggregators in western India, retailer credit schemes in eastern rice belts, and subscription-based replenishment programs in Vietnam's Mekong Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of high-CFU fermentation infrastructure capable of meeting India's BIS standards is concentrating margin capture among players with captive manufacturing assets. This capability gap favors incumbents with validated strain libraries while constraining new entrant scale-up timelines.
For Market Incumbents: Shield proprietary strain portfolios through patent thickets around nitrogen-fixation genetics while expanding backward integration into molasses feedstock supply. Licensing complexity for Azotobacter variants is fragmenting R&D pipelines and inflating royalty burdens for domestic Indian manufacturers. Prioritize certification investment for MEE three-zone field trial documentation to preempt supply disruption risks in Japanese vegetable cooperatives. For New Entrants and Emerging Players: Anchor in underpenetrated horticulture corridors in China's Shandong province, where mycorrhizal fungi applications command 3-4x pricing premiums over field crop formulations. Drone-based microbial delivery systems represent the most penetrable channel, opening precision agriculture access in Australia's broadacre wheatbelt without requiring drip irrigation retrofit investments. Pursue go-to-market partnerships with input retailers bundling seasonal soil testing with customized inoculant prescriptions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized microbial houses with tropical soil expertise over integrated agrochemical conglomerates facing margin compression from PLI-subsidized domestic competition. Long-term viability hinges on encapsulation chemistry capabilities that extend shelf stability from 6 to 18 months, creating defensible moats against commodity bacterial inoculant producers. Target acquisition archetypes include Australian broadacre-focused liquid formulation specialists and Japanese Trichoderma biocontrol developers with MEE-registered strain libraries. Watch for inflection signals around carbon credit mechanism formalization under China's dual carbon goals, which would directly revenue-link soil carbon sequestration verification protocols.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Chemistry Investment | Alginate-chitosan matrix development extends shelf stability for aerial delivery compatibility in Australian wheatbelt operations. |
| Cooperative Procurement Partnership | Bulk aggregation mechanisms in Maharashtra reduce per-hectare amendment costs across 500-2,000 member farm networks. |
| MEE Three-Zone Field Trial Completion | Regulatory registration across Chinese agro-climatic zones creates supply security moats for Japanese vegetable cooperatives. |
| Drone Delivery System Integration | Aerial application compatibility opens precision agriculture channels in fragmented Japanese rice paddy landscapes. |
| Carbon Banking Protocol Verification | Soil carbon sequestration certification under China's dual carbon goals creates direct revenue streams for microbial input providers. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, cooperative procurement officers at Maharashtra farming collectives, APVMA regulatory affairs specialists, and drip irrigation infrastructure engineers. Secondary validation drew from FSSAI registration databases, MEE environmental release filing records, BIS labeling standard documentation, and India's PLI scheme beneficiary disclosures. Bottom-up strain-level production estimates were triangulated against top-down regional demand aggregation across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value trajectories by microbial taxonomy, formulation chemistry, application segment, and procurement channel structure. CAGRs were derived from segmented growth rate reconciliation against macro-level agricultural input expenditure trends. Industry-specific forecast inputs included PLI subsidy disbursement schedules, MEE registration pipeline backlogs, and cooperative membership expansion rates in Gujarat and Maharashtra.
Decision-makers should treat outputs as directional under assumptions of sustained PLI scheme funding and stable MEE regulatory timelines; material deviation would warrant model refresh. Strain patent litigation outcomes, monsoon volatility affecting granular carrier viability, and substitution acceleration from coated urea variants represent specific risk factors that could revise forecasts. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Animal Feed Additives Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Edible Fungus Market
Agricultural Biologicals
Global Agricultural Enzymes Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
North America Agricultural Microbials Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Chitosan for Agriculture Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Insect Feed Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
South America Agricultural Microbials Market
Agricultural Biologicals
Asia Pacific Silage Inoculant Market
Agricultural Biologicals
Microbial Agricultural Inoculants Market