
 India Feed Enzymes Market | 2026-2036
India Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
India Feed Enzymes Market Outlook
Phytase is shifting from niche additive to baseline formulation across Indian compound feed, displacing inorganic phosphate supplements in cost-sensitive rations. BASF SE leverages its global phytase technology portfolio to anchor premium positioning among large integrators. Advanced Enzyme Technologies competes through domestic manufacturing scale and customized blends for regional raw material matrices. Kerry Group Plc extends its nutritional solutions footprint by embedding enzymes within broader premix offerings for southern India's contract poultry farms.
Feed enzymes are protein-based biocatalysts, typically active at temperatures between 40-60°C and pH ranges of 2.5-6.5, that hydrolyze anti-nutritional factors in cereal-based diets to liberate bound phosphorus, amino acids, and energy. Their primary commercial purpose is to improve feed conversion ratios while reducing environmental phosphorus and nitrogen excretion in intensive livestock operations. Proteases and phytase combinations command the largest current volume position, reflecting their proven efficacy in corn-soy diets dominant across Indian feed mills. Amylase demand is accelerating fastest as wheat and broken rice substitutions in poultry rations rise with volatile soybean prices. The aquaculture functionality segment, particularly for shrimp and finfish, represents an emerging margin pool where enzyme stability in pelleted feeds under tropical storage conditions creates technical differentiation.
BIS feed-grade standards and FSSAI's draft regulations on maximum residue limits are tightening product registration requirements, forcing reformulation documentation and stability claims. CDSCO's overlapping jurisdiction on certain probiotic-enzyme combinations adds compliance complexity for manufacturers seeking dual-category positioning. The PLI scheme for animal husbandry inputs is channeling capital toward domestic fermentation capacity, altering import dependence for concentrated enzyme preparations. Stakeholders must monitor how state-level feed control orders in Maharashtra and Gujarat integrate with central frameworks, as enforcement variance will determine market access patterns for imported versus locally blended enzyme products.
Market Dynamics
The PLI scheme for animal husbandry inputs is redirecting capital toward domestic fermentation infrastructure, compressing import dependence for concentrated enzyme preparations while reshaping competitive positioning between multinational and local formulators.
Growth Catalysts
- Phytase penetration in broiler rations:Large integrators in Telangana and Andhra Pradesh are embedding phytase-carbohydrase blends as baseline formulation, reducing inorganic phosphate costs while meeting FSSAI's evolving feed safety protocols.
- Soybean price volatility:Feed mills are accelerating amylase adoption to unlock energy from wheat and broken rice substitutions, particularly in Maharashtra and Gujarat where poultry density concentrates.
- PLI scheme incentives:Capital subsidies for domestic manufacturing of animal husbandry inputs are attracting fermentation capacity investments that previously flowed to imported concentrated preparations.
Market Restraints
- CDSCO-FSSAI jurisdictional overlap:Probiotic-enzyme combination products face dual registration requirements that extend compliance timelines and increase documentation burdens for manufacturers.
- Tropical storage stability:Enzyme activity degradation in pelleted feeds under high-humidity conditions limits shelf-life claims and complicates distribution to coastal aquaculture operations.
- Raw material matrix variability:Regional differences in cereal quality across Indian states force customized blend development, fragmenting production runs and elevating formulation costs.
Strategic Opportunities
- Aquaculture functionality segment:Shrimp and finfish feed applications represent underdeveloped margin pools where enzyme stability in extruded pellets creates technical differentiation against standard poultry offerings.
- State feed control order harmonization:Maharashtra and Gujarat are piloting integrated enforcement frameworks that could streamline market access for compliant domestic manufacturers versus imported products.
- BIS feed-grade standard alignment:Early certification against tightening BIS standards positions suppliers for preferred vendor status as large integrators consolidate procurement.
Industry Challenges
- Fermentation scale-up expertise:Domestic capacity expansion requires specialized biochemical engineering talent that concentrates in Hyderabad and Bengaluru, creating recruitment bottlenecks for greenfield facilities.
- Stability validation protocols:FSSAI's draft regulations on maximum residue limits demand accelerated documentation of enzyme activity retention under tropical storage, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Feed Enzymes Market |
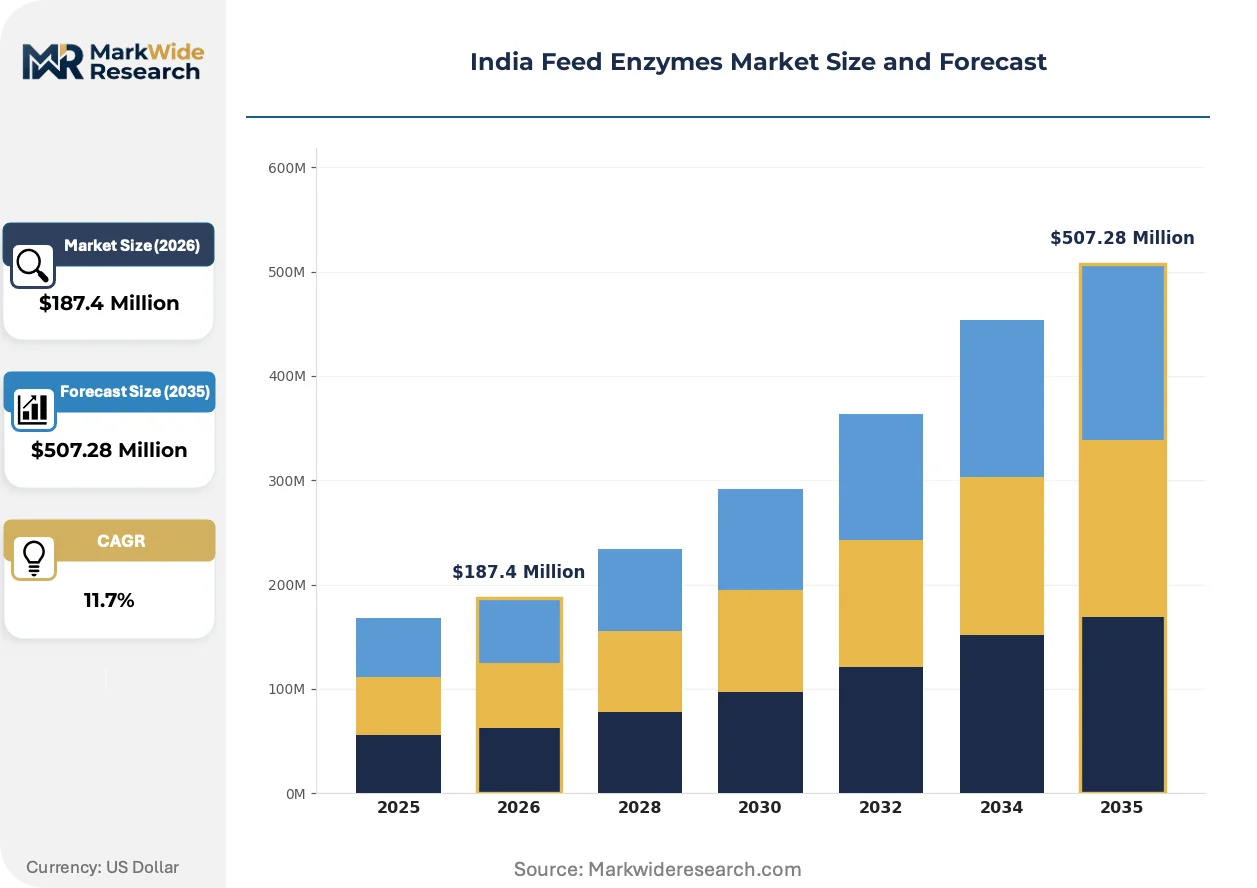
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Cellulases, Lipases Livestock Category: Poultry, Swine, Ruminants, Aquaculture Functionality: Digestive Health, Nutrient Absorption, Feed Efficiency, Growth Promotion Distribution Channel: Online, Direct Sales, Distributors, Retailers |
| Companies Covered | Adisseo, Novonesis A/S (DSM-Firmenich), Archer Daniels Midland Co., BASF SE, Brenntag SE, Kerry Group Plc, Advanced Enzyme Technologies, Cargill Inc., Alltech Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Feed Enzymes Market Strategic Shifts
Enzyme engineering and regulatory alignment are compressing product development timelines while procurement centralization among large integrators is forcing technical service model evolution.
Next-generation phytase variants with enhanced thermostability are converging with pelleting temperature requirements above 85°C, enabling post-pelleting liquid application systems that large integrators in southern India are adopting faster than northern counterparts. This convergence is collapsing the historical trade-off between enzyme survival and processing efficiency, allowing simultaneous feed hygiene and nutrient release optimization.
FSSAI's draft maximum residue limit regulations are tightening documentation requirements for reformulation claims and stability assertions, forcing manufacturers to invest in accelerated degradation studies under simulated tropical storage. Poultry premix suppliers face the most immediate compliance burden as integrators demand transferable regulatory files that satisfy state-level feed control orders in Maharashtra and Gujarat.
Contract poultry farms are consolidating procurement decisions through integrator-managed input programs, displacing independent feed mill relationships that previously dominated enzyme purchasing in southern states. This channel compression elevates technical service expectations, with farms now demanding on-farm mixing validation and real-time reformulation support rather than standard product specifications.
India Feed Enzymes Market Segmentation
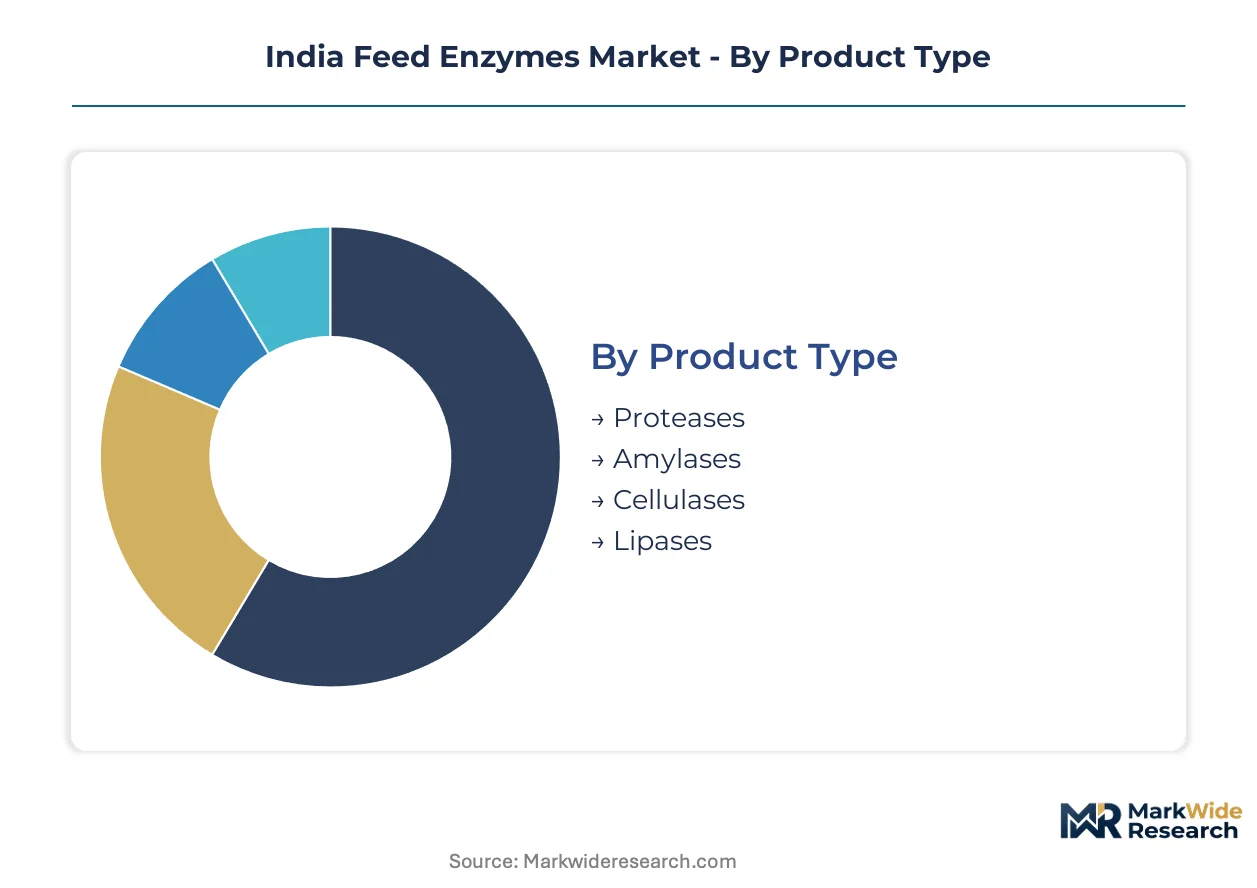
Feed enzyme segmentation in India tracks how formulation complexity varies across livestock systems and procurement channels. Understanding these divides clarifies where technical service investments yield margin protection versus where price competition dominates.
Product Type:
Proteases and amylases dominate standalone additive formulations, while cellulases and lipases increasingly embed within broader premix systems for integrated operations.
- Proteases:These protein-digesting enzymes hydrolyze complex proteins into absorbable amino acids, particularly critical in corn-soy diets prevalent across Telangana and Andhra Pradesh broiler operations. Demand concentrates among large integrators seeking to reduce soybean meal inclusion rates as prices fluctuate.
- Amylases:Starch-targeting biocatalysts unlock energy from wheat and broken rice substitutions that Maharashtra and Gujarat feed mills are accelerating amid volatile oilseed markets. Poultry integrators in western India are embedding these as baseline formulation to maintain feed conversion ratios during raw material switches.
- Cellulases:Fiber-degrading enzymes break down non-starch polysaccharides in cereal byproducts, finding uptake in ruminant feed formulations across Punjab and Haryana dairy belts.
- Lipases:Fat-digesting catalysts improve energy utilization from oilseed meals and animal fats, penetrating aquaculture pellet formulations where lipid stability under tropical storage creates technical differentiation.
Volume placements concentrate in proteases; the faster expansion belongs to amylases.
Livestock Category:
Cost tier stratification separates intensive poultry and aquaculture systems willing to pay for enzyme performance guarantees from ruminant operations where price per ton dominates procurement decisions.
- Poultry:Broiler and layer operations across southern and western states anchor enzyme demand, with integrators in Telangana and Andhra Pradesh mandating phytase-carbohydrase blends to displace inorganic phosphate and meet FSSAI feed safety protocols.
- Swine:Pig farming clusters in northeastern states and Kerala utilize protease-amylase combinations to improve digestibility of locally sourced feed ingredients with variable quality matrices.
- Ruminants:Dairy cooperatives in Gujarat and Maharashtra represent emerging volume as cellulase and fibrolytic enzyme adoption spreads from trial to standard inclusion in total mixed rations.
- Aquaculture:Shrimp feed mills in Andhra Pradesh and finfish operations in Tamil Nadu are driving thermostable enzyme demand where pellet processing above 85°C requires post-pelleting liquid application systems.
Procurement scale favors poultry; margin expansion is steepest in aquaculture.
Functionality:
Application focus determines whether enzymes sell as discrete performance ingredients or embed within nutritional service bundles that integrators demand.
- Digestive Health:Multi-enzyme complexes targeting gut microbiome optimization command premium positioning in antibiotic-free poultry programs across contract farming networks.
- Nutrient Absorption:Phytase-led formulations liberating bound phosphorus dominate volume as FSSAI regulations tighten on environmental discharge from intensive operations.
- Feed Efficiency:Energy-release enzymes enabling cereal substitutions generate fastest uptake in cost-sensitive periods, particularly when soybean meal prices spike.
- Growth Promotion:Enzyme-probiotic combinations face CDSCO-FSSAI jurisdictional complexity that extends registration timelines but attracts integrators seeking growth optimization claims.
Regulatory pressure elevates nutrient absorption; feed efficiency is gaining share fastest during price volatility cycles.
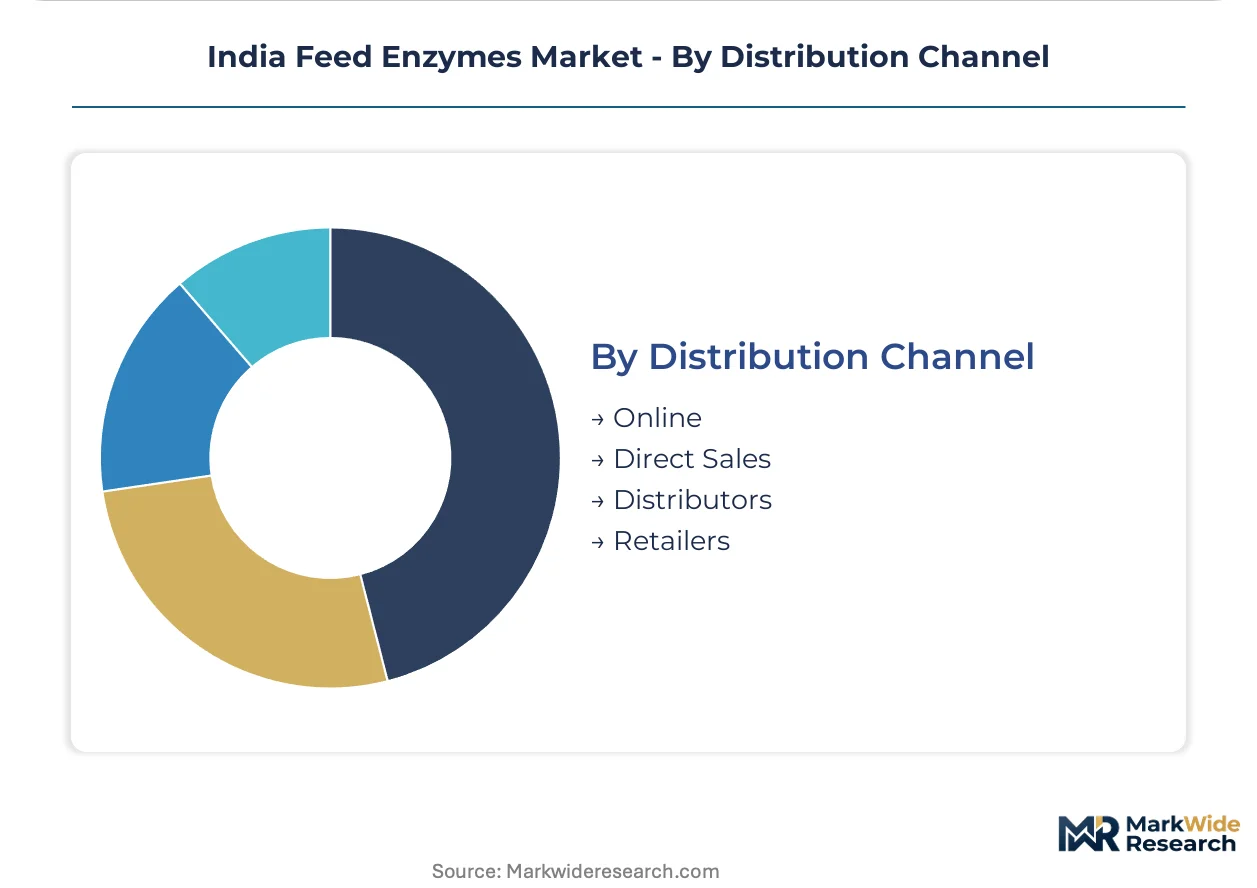
Distribution Channel:
Customer type fragmentation separates integrator-managed procurement from independent feed mill purchasing patterns.
- Direct Sales:Technical service-intensive relationships with large poultry integrators in southern states, involving on-farm mixing validation and real-time reformulation support.
- Distributors:Regional chemical and feed additive distributors serving mid-tier feed mills in Maharashtra, Gujarat, and Punjab with standardized enzyme blends.
- Retailers:Local agricultural supply stores reaching smallholder dairy and backyard poultry operations with basic single-enzyme products.
- Online:Emerging digital procurement channels targeting aquaculture feed formulators and specialty livestock operations seeking technical documentation transparency.
Relationship density concentrates in direct sales; channel development investment is flowing toward online platforms for documentation-heavy aquaculture segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Feed enzyme consumption concentrates in India's southern and western states where large poultry integrators drive formulation standardization. State-level regulatory variance and raw material sourcing patterns create distinct operational environments across major production belts.
Telangana
Broiler integrators in Telangana mandate phytase-carbohydrase blends as baseline formulation to displace inorganic phosphate supplements. The state's feed control orders align with FSSAI's evolving safety protocols, creating compliance clarity for domestic manufacturers. Hyderabad anchors fermentation capacity expansion under the PLI scheme for animal husbandry inputs.
Andhra Pradesh
Shrimp feed mills in Andhra Pradesh accelerate thermostable enzyme demand for extruded pellet applications above 85°C. CDSCO-FSSAI jurisdictional overlap complicates probiotic-enzyme combination registrations for suppliers targeting coastal aquaculture operations. Visakhapatnam clusters attract technical service investments for post-pelleting liquid application systems.
Maharashtra
Poultry density in Maharashtra drives amylase adoption to unlock energy from wheat and broken rice substitutions during soybean price spikes. State feed control orders pilot integrated enforcement frameworks that streamline market access for compliant domestic manufacturers. Pune and Nashik feed mills consolidate procurement through integrator-managed input programs.
Gujarat
Dairy cooperatives in Gujarat represent emerging cellulase volume as fibrolytic enzyme adoption spreads from trial to standard inclusion in total mixed rations. BIS feed-grade certification requirements tighten documentation burdens for suppliers seeking preferred vendor status. Anand and Vadodara clusters anchor western India's ruminant feed enzyme trials.
Karnataka
Specialized biochemical engineering talent concentrates in Bengaluru, creating recruitment bottlenecks for greenfield fermentation facilities seeking PLI scheme incentives. State-level feed safety enforcement lags southern counterparts, delaying standardization of enzyme stability validation protocols. Contract poultry farms around Bengaluru demand real-time reformulation support from enzyme suppliers.
India Feed Enzymes Market Competitive Environment
Capacity expansion dominates the current landscape as PLI scheme incentives redirect capital toward domestic fermentation infrastructure. The vendor base stratifies between multinational technology licensors and local formulators with manufacturing scale. Three archetypes define positioning: global enzyme specialists leveraging thermostability IP, domestic blenders optimizing for regional raw material matrices, and diversified nutrition companies embedding enzymes within premix bundles. Competitive intensity centers on tropical stability validation and technical service density near integrator clusters.
Among global specialists, BASF SE anchors premium positioning through phytase technology portfolios, while Kerry Group Plc exemplifies the nutrition-integrated archetype by embedding enzymes within broader premix offerings. Advanced Enzyme Technologies occupies a position within the domestic manufacturing tier, competing through customized blends and proximity to southern Indian poultry belts. These three represent the competitive vectors—technology licensing, nutritional integration, and manufacturing scale—that define market structure.
| Leading Market Players |
|---|
| Adisseo |
| Novonesis A/S (DSM-Firmenich) |
| Archer Daniels Midland Co. |
| BASF SE |
| Brenntag SE |
| Kerry Group Plc |
| Advanced Enzyme Technologies |
| Cargill Inc. |
| Alltech Inc. |
| Others |
Value Chain & Pricing Dynamics
FSSAI's evolving feed safety protocols gate qualified supply and premium-tier pricing access, compressing margins for uncertified formulators while rewarding domestic manufacturers with BIS feed-grade documentation. Integrators in Telangana and Andhra Pradesh now mandate transferable regulatory files, bifurcating the vendor base into compliant premium suppliers and price-pressured standard-tier competitors.
Pricing Analysis
Volume placements concentrate in standard-tier phytase formulations where price competition dominates, while premium margins accrue to thermostable variants with validated tropical stability claims. Price differentiation hinges on FSSAI compliance documentation and post-pelleting liquid application capability, with certified domestic manufacturers capturing integrator preference. Cost compression in the standard tier is intensifying due to PLI scheme capacity additions attracting new fermentation entrants. Smallholder dairy operations and independent feed mills in Punjab and Haryana exhibit highest price sensitivity, whereas aquaculture feed mills in Andhra Pradesh accept premium positioning for enzyme stability under extrusion temperatures above 85°C.
Supply Chain Analysis
Regional distribution centers in Hyderabad, Visakhapatnam, and Pune anchor hub-and-spoke patterns serving southern and western poultry belts with enzyme concentrates and customized blends. Manufacturing concentrates in India, China, and select European fermentation hubs, with domestic capacity expansion accelerating under PLI scheme incentives. Raw material dependencies span corn and soybean meal quality matrices, specialized fermentation substrates, and thermostability-enhancing enzyme variants. Single-source vulnerability concentrates in concentrated enzyme preparation imports, particularly for next-generation phytase IP held by multinational technology licensors. Distribution runs through integrator-managed input programs displacing independent feed mill relationships in southern states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation scale-up expertise scarcity props pricing for qualified suppliers, as greenfield facilities face recruitment bottlenecks for biochemical engineering talent concentrating in Hyderabad and Bengaluru. This supply-constrained dynamic rewards early movers with validated tropical stability protocols.
For Market Incumbents: Extend technical service density near integrator clusters in Telangana and Andhra Pradesh to lock in contract poultry farm relationships before procurement centralization completes. Invest in backward integration into fermentation capacity under PLI scheme incentives to reduce import dependence for concentrated preparations. BASF SE and Kerry Group Plc exemplify defensive positioning through thermostability IP and premix bundling respectively, while Advanced Enzyme Technologies leverages domestic manufacturing proximity. For New Entrants and Emerging Players: Launch via online platforms targeting aquaculture feed formulators in Tamil Nadu and Andhra Pradesh, where documentation transparency demands outstrip incumbent technical service capacity. Focus white-space capture on thermostable enzyme stability validation for shrimp feed extrusion applications, the fastest-expanding margin pool. Partner with regional distributors in Maharashtra and Gujarat to bypass direct sales relationship barriers with large integrators. For Investors and Strategic Acquirers: FSSAI's draft maximum residue limit finalization is the leading indicator that regulatory compliance will consolidate vendor access within three to five years. Target acquisition of domestic blenders with BIS feed-grade certification and established integrator relationships in southern states, as these assets command scarcity premia under tightening enforcement. Monitor state-level feed control order harmonization progress in Maharashtra and Gujarat as the signal for accelerated procurement centralization.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Expansion | PLI scheme subsidies reduce import dependence for concentrated enzyme preparations from European and Chinese suppliers. |
| Tropical Stability Validation Investment | Accelerated degradation studies under simulated high-humidity storage satisfy FSSAI draft regulations and differentiate premium offerings. |
| Post-Pelleting Liquid Application Systems | Technical integration with extrusion equipment above 85°C captures aquaculture feed mill demand in Andhra Pradesh and Tamil Nadu. |
| Integrator Technical Service Partnerships | On-farm mixing validation and real-time reformulation support lock in procurement decisions across Telangana contract poultry networks. |
| BIS Feed-Grade Certification Pathway | Early compliance positions suppliers for preferred vendor status as large integrators consolidate enzyme procurement in western states. |
Study Parameters
Multi-period observation of phytase penetration rates, PLI scheme capacity additions, and FSSAI regulatory filing volumes anchored the trend analysis, supplemented by interviews with feed mill procurement managers, poultry integrator nutritionists, fermentation plant engineers, and aquaculture feed formulators. Secondary validation drew from BIS feed-grade certification databases, CDSCO probiotic-enzyme registration filings, state-level feed control order gazettes, and customs data on concentrated enzyme preparation imports. Bottom-up enzyme volume estimates by livestock category and state triangulated against top-down compound feed production projections across the analysis window.
Segment-weighting applied differential growth assumptions to poultry, aquaculture, and ruminant enzyme demand based on livestock density trajectories and raw material substitution patterns. The analytical framework modeled product type splits between phytase, carbohydrase, protease, and amylase formulations; livestock category penetration rates; and distribution channel evolution from independent feed mills toward integrator-managed programs. CAGRs derived from logistic adoption curves fitted to enzyme penetration data across southern and western state clusters, incorporating soybean price volatility cycles and PLI incentive uptake rates as exogenous inputs.
Regulatory enforcement variance across Maharashtra, Gujarat, and Karnataka state feed control orders, fermentation substrate price volatility, and integrator consolidation timing are the dominant revision risks to volume and value projections. Forecasts reflect documented assumptions regarding FSSAI protocol finalization and PLI scheme disbursement continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Biologicals
Global Agricultural Inoculant Market
Agricultural Biologicals
Forage Inoculants Market
Agricultural Biologicals
Global Agri Natural Enemy Pest Control Market
Agricultural Biologicals
Silybum Marianum Market
Agricultural Biologicals
Africa Feed Enzymes Market
Agricultural Biologicals
Humic-Based Biostimulants Market
Agricultural Biologicals
Europe Agricultural Microbials Market
Agricultural Biologicals
Agricultural Microbials Market
Agricultural Biologicals
South America Beta-Glucan Market
Agricultural Biologicals
North America Silage Inoculant Market
Agricultural Biologicals
Global Silage Inoculants Market
Agricultural Biologicals
South America Feed Mycotoxin Detoxifiers Market
Agricultural Biologicals
North America Amino Acids Market
Agricultural Biologicals
Baobab Market
Agricultural Biologicals
Acetoin Natural Market
Agricultural Biologicals
South America Biostimulants Market