
 Personal Care and Cosmetic Preservatives Market | 2026-2036
Personal Care and Cosmetic Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care and Cosmetic Preservatives Market Analytics
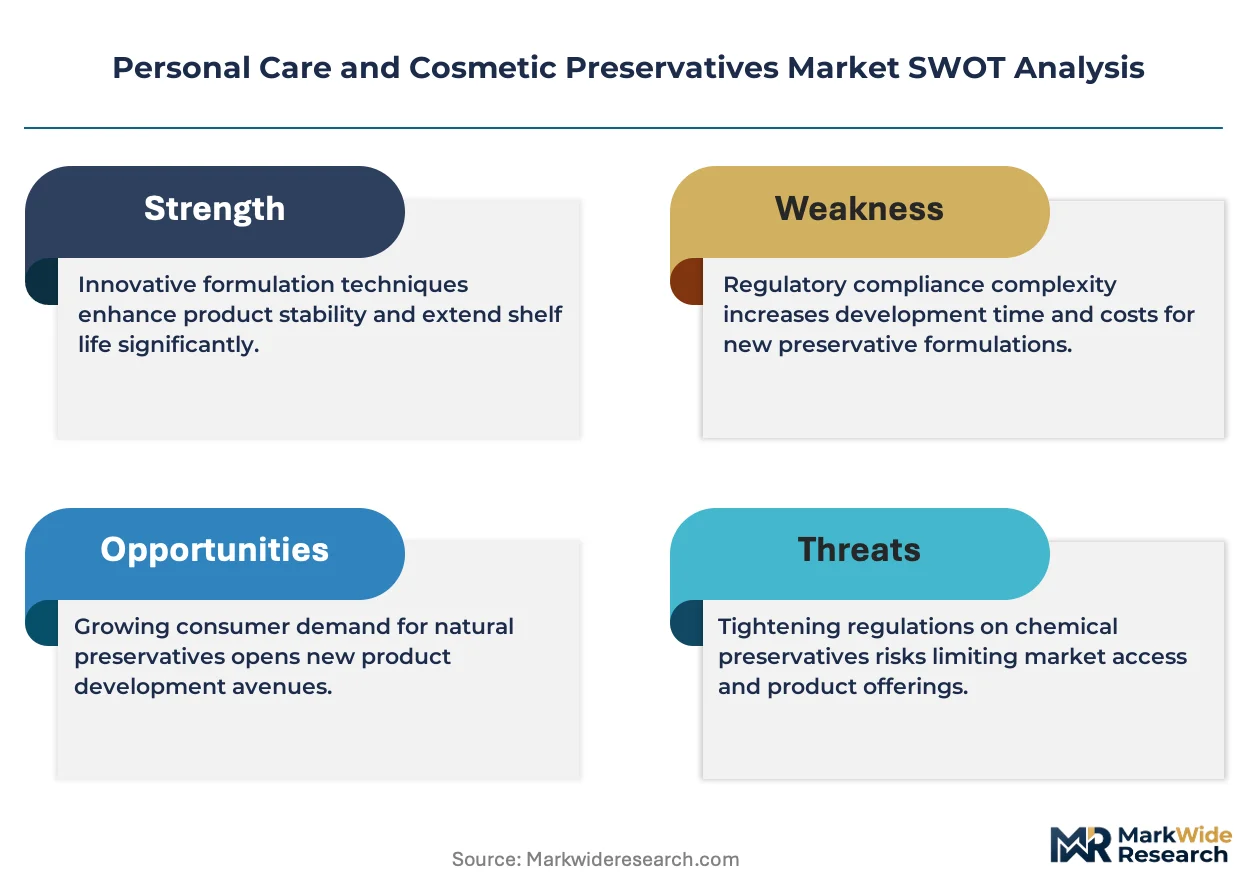
REACH is broadening the cost-of-entry calculus for preservative suppliers entering the European personal care sector. BASF SE leverages its integrated phenoxyethanol production chain to sustain compliance margins under evolving ECHA restrictions. Lonza Group anchors its position through specialized microbiological testing services that parallel its preservative portfolio. Symrise AG differentiates via botanical-derived preservation systems that navigate clean-label certification requirements.
Personal care and cosmetic preservatives are antimicrobial or antioxidant compounds, typically dosed at 0.01% to 1.0% by formulation weight, that inhibit microbial proliferation in water-containing cosmetic matrices. Their primary commercial purpose is to ensure product safety, extend shelf stability, and meet regulatory microbiological challenge-test standards across rinse-off and leave-on applications. Parabens occupy the mature core of the product-type landscape, while phenoxyethanol gains volume in skincare and haircare as brands seek alternatives under regulatory pressure. Sorbic acid competes in powder-format applications where water activity remains constrained, and the emulsions formulation segment leads value capture due to complex preservation needs in multi-phase systems.
The EU Green Deal and ECHA REACH frameworks constrain which synthetic preservatives achieve market access in Europe, while the FDA and state-level regulations in the US govern allowable concentrations and labeling disclosures. The EU AI Act introduces emerging compliance dimensions for automated safety-assessment tools used in preservative efficacy testing. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation mandates and qualification timelines.
Market Dynamics
REACH restrictions on formaldehyde releasers are compressing the acceptable preservative palette across European formulations, forcing suppliers to rebuild compliance margins around alternative chemistries.
Growth Catalysts
- Indonesia Halal Mandate:The country's halal certification requirements for cosmetics are triggering reformulation waves across phenoxyethanol and paraben alternatives, pulling Southeast Asian demand upward.
- ECHA Alternative Assessment Pathways:Streamlined evaluation procedures for novel preservation systems are accelerating market entry timelines for compliant biocidal actives in rinse-off applications.
- Water Activity Control Technologies:Advanced powder-format formulations incorporating sorbic acid are expanding shelf-stable product categories without conventional liquid preservatives.
Market Restraints
- Feedstock Concentration:Phenol supply for phenoxyethanol production clusters in Gulf Coast petrochemical corridors, exposing margins to hurricane-season disruption and force majeure events.
- Biocide Authorization Friction:The EU Biocidal Products Regulation's renewal timelines for existing actives are extending qualification periods to 36-48 months, freezing formulation pipelines.
- Natural Extract Substitution:Botanical preservation systems derived from rosemary and tea tree extracts are capturing clean-label preference in premium skincare, eroding synthetic volumes.
Strategic Opportunities
- Halal-Certified Synthetics:Malaysia and Indonesia's combined cosmetics consumption is creating demand for alcohol-free preservation systems that bypass traditional ethanol-based biocides.
- Microbiome-Friendly Positioning:Preservative systems with selective antimicrobial activity are opening positioning space in probiotic skincare formulations targeting dysbiosis-conscious consumers.
- Automated Challenge Testing:AI-driven preservative efficacy screening under the EU AI Act compliance framework is compressing development cycles for new active combinations.
Industry Challenges
- Reformulation Talent Scarcity:Cosmetic chemists with dual expertise in regulatory compliance and microbiological stability are commanding premium compensation, constraining mid-tier brand execution capacity.
- Legacy System Integration:Established manufacturing lines configured for paraben-based preservation require capital-intensive retooling to handle heat-sensitive alternative actives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care and Cosmetic Preservatives Market |
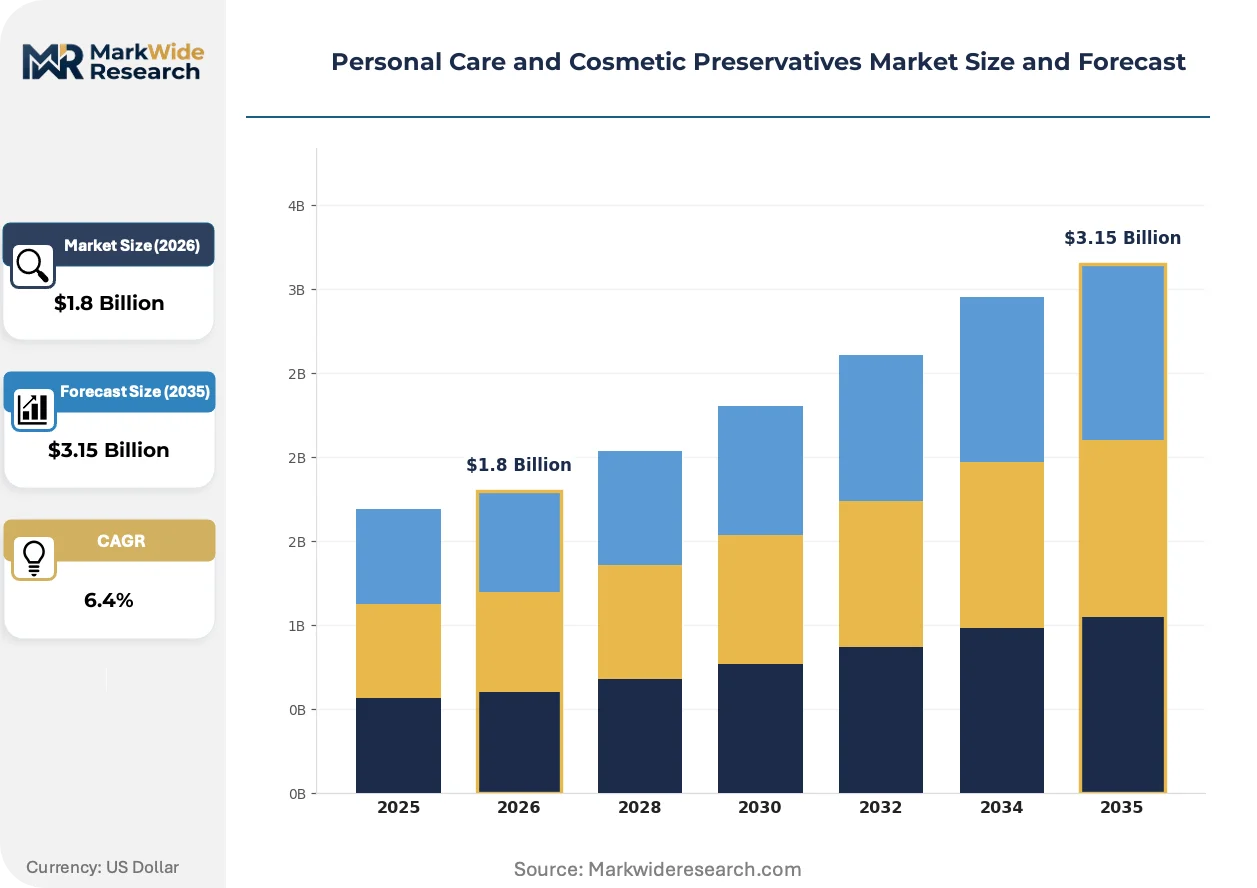
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
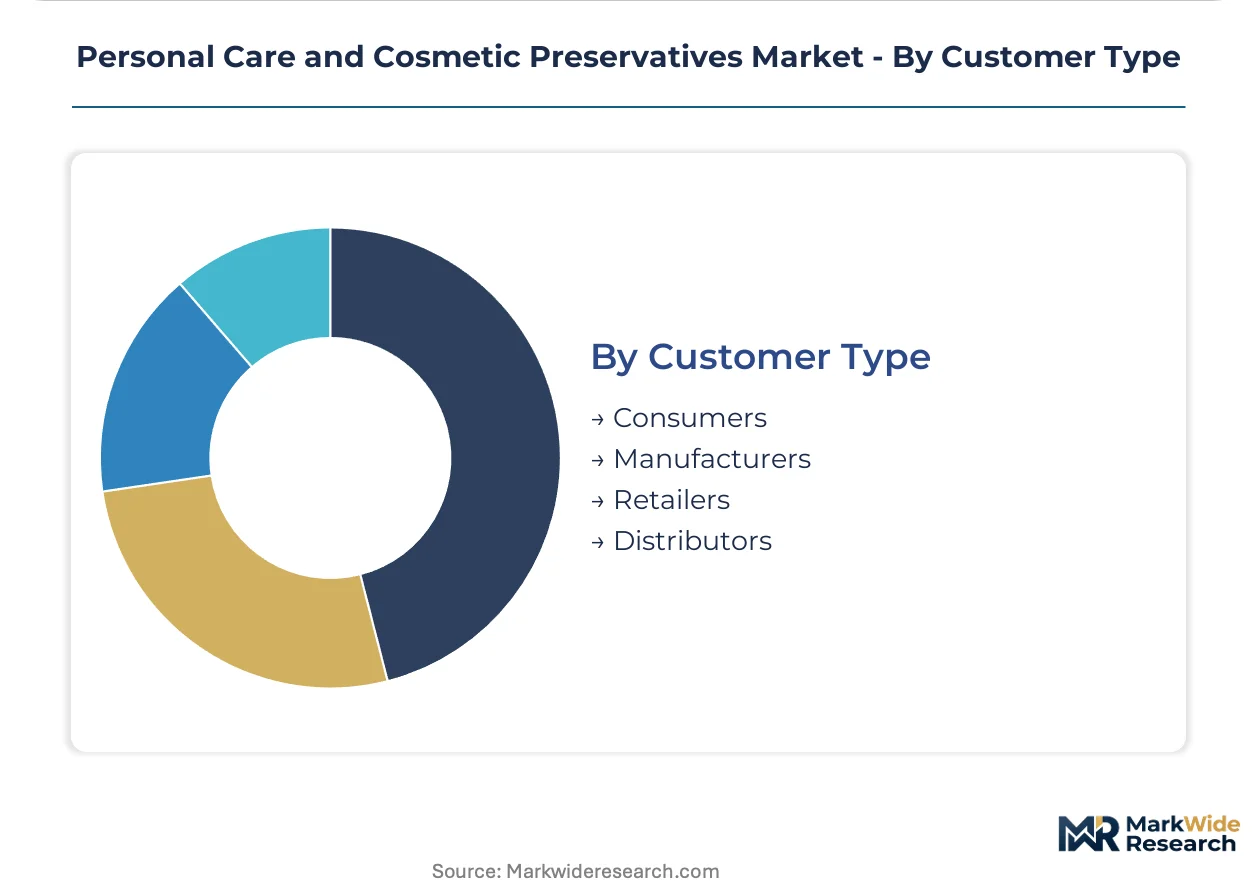
| Segmentation | Product Type: Parabens, Phenoxyethanol, Benzyl Alcohol, Sorbic Acid Formulation Type: Emulsions, Gels, Powders, Liquids Application Area: Skincare, Haircare, Makeup, Fragrance Customer Type: Consumers, Manufacturers, Retailers, Distributors |
| Companies Covered | BASF SE, Ashland Global Holdings, Lonza Group, Clariant AG, Evonik Industries, Symrise AG, International Flavors & Fragrances Inc., Dow Inc., Croda International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care and Cosmetic Preservatives Market Evolving Landscape
Preservation technology is bifurcating between high-performance synthetics for mass-market safety assurance and botanical-derived systems for premium clean-label positioning, with regulatory compliance as the binding constraint across both paths.
Encapsulation technology using lipid-based delivery systems is absorbing volatility in phenoxyethanol release profiles, enabling controlled antimicrobial activity across extended shelf lives. Skincare brands in Germany and France are piloting these systems in leave-on facial products where traditional dosing creates irritation risk. The technology is absorbing market share from conventional free-preservative formulations that fail challenge testing under tightened ECHA standards.
REACH Annex XVII restrictions on formaldehyde-releasing preservatives are eliminating quaternium-15 and DMDM hydantoin from European rinse-off and leave-on categories. Formulators are redirecting toward phenoxyethanol-boosted systems and organic acid combinations, with haircare applications experiencing the most acute substitution pressure. The regulation is compressing supplier margins as qualification costs for replacement actives accumulate across multiple portfolio lines.
Direct-to-consumer subscription channels are fragmenting bulk procurement patterns that historically favored single-preservative systems across large production runs. Indie beauty brands in South Korea and the United States are specifying custom preservation packages for limited-batch releases, forcing suppliers to modularize active combinations. This pattern is most visible in serum and ampoule categories where micro-batch manufacturing dominates.
Personal Care and Cosmetic Preservatives Market Segmentation
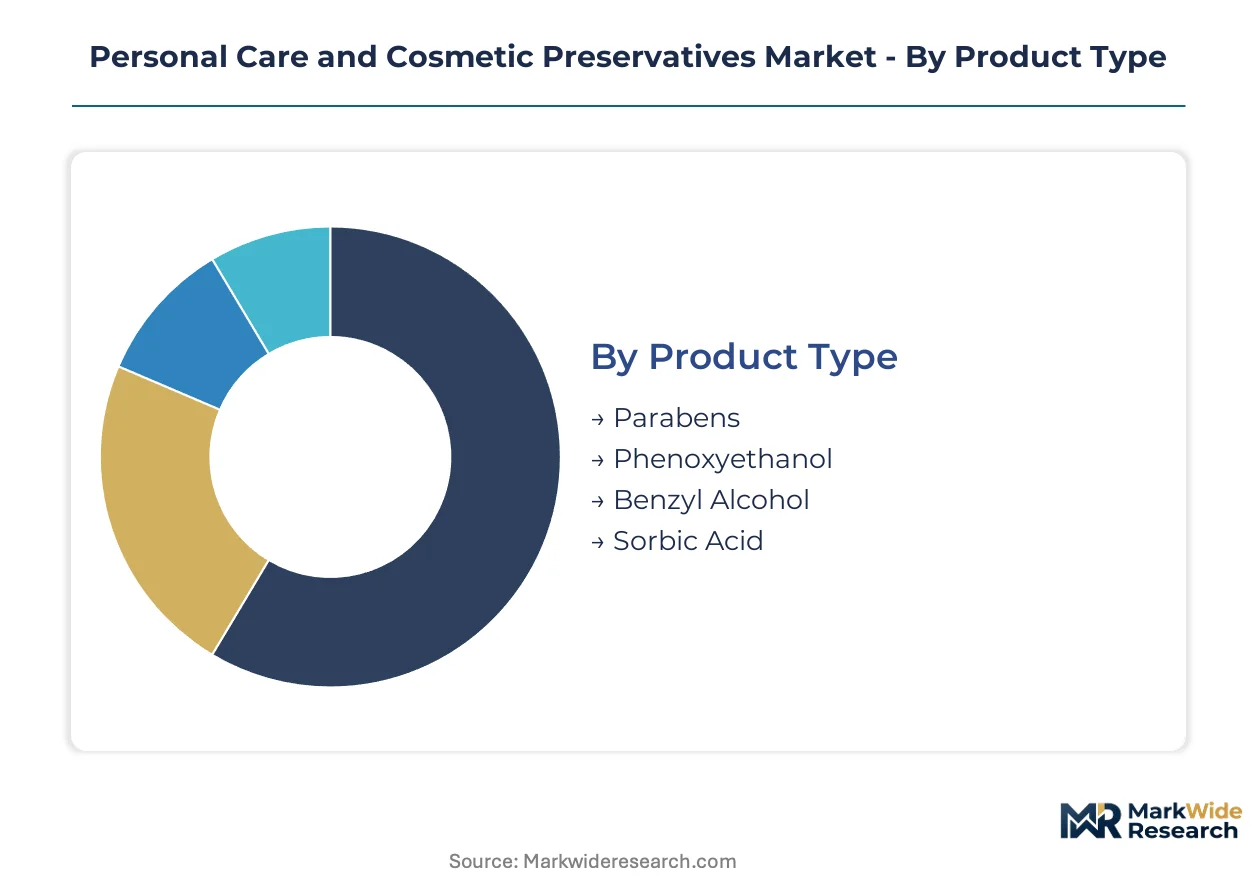
Preservative selection varies sharply across formulation chemistry, end-use application, and regulatory exposure. Segmentation reveals where compliance costs concentrate and which substitution patterns reshape supplier portfolios.
Product Type:
Buyers differentiate primarily by regulatory tolerance thresholds and clean-label positioning requirements.
- Parabens:Ester-based antimicrobials with broad-spectrum efficacy against gram-positive bacteria and molds. Demand concentrates in Southeast Asian mass-market skincare where ECHA restrictions carry limited direct force. Methyl- and propylparaben blends face substitution pressure in European leave-on products.
- Phenoxyethanol:Glycol ether with bacteriostatic properties effective at 0.5-1.0% concentration. German and French formulators are expanding volume in facial serums as REACH eliminates formaldehyde-releasing alternatives. Encapsulation technologies are stabilizing release profiles for sensitive skin applications.
- Benzyl Alcohol:Aromatic alcohol with mild antimicrobial and fragrance-masking properties. Indonesia's halal-certified cosmetics sector absorbs rising volumes for alcohol-free positioning.
- Sorbic Acid:Unsaturated fatty acid effective in low-water-activity systems. Powder-format haircare and dry shampoo applications in South Korea leverage its pH-dependent efficacy.
Volume sits with parabens in developing markets; growth tilts toward phenoxyethanol in reformulation-driven European skincare.
Formulation Type:
Preservation complexity escalates with phase boundary count and water content.
- Emulsions:Oil-in-water or water-in-oil matrices demanding multi-phase microbial control. Premium facial moisturizers in France and Germany require sophisticated active combinations to pass ECHA challenge testing. Microbiome-friendly positioning is driving selective antimicrobial development.
- Gels:Hydrocolloid-thickened aqueous systems with high water activity and transparent aesthetic requirements. K-beauty essence and ampoule formats in South Korea specify low-irritation preservation for damaged-skin positioning.
- Powders:Low-water-activity formats where sorbic acid and benzoic acid derivatives dominate. Dry shampoo and loose powder makeup in Japan leverage inherent microbial resistance.
- Liquids:Single-phase aqueous or hydroalcoholic solutions including toners and facial mists. Indonesian halal mandates are excluding ethanol-based preservation from this category.
Revenue concentrates in emulsions due to technical complexity; powder formats are climbing fastest on waterless formulation trends.
Application Area:
Regulatory scrutiny and consumer sensitivity vary dramatically by product-skin contact duration.
- Skincare:Leave-on facial and body products with prolonged dermal exposure. Clean-label certification requirements in Germany and France are fragmenting preservative specifications across premium and mass tiers.
- Haircare:Rinse-off shampoos and conditioners with reduced contact time. REACH formaldehyde-releasing restrictions are forcing acute reformulation in European salon and retail channels.
- Makeup:Pigmented products requiring preservation across diverse base chemistries. Powder foundations and liquid concealers in South Korea demand format-specific active selection.
- Fragrance:High-alcohol-content products with inherent preservation from ethanol concentration. Indonesian halal certification is excluding conventional alcohol-based formats from this segment.
Skincare commands premium pricing; haircare is expanding most quickly on substitution-driven reformulation cycles.
Customer Type:
Procurement scale and technical capability determine access to customized preservation systems.
- Consumers:End-users whose clean-label preferences transmit upward through retail and brand channels. Dysbiosis-conscious segments in France and Germany are rewarding microbiome-friendly positioning.
- Manufacturers:Contract producers and brand-owning formulators with direct regulatory compliance obligations. Mid-tier European manufacturers face talent scarcity in dual regulatory-microbiology expertise.
- Retailers:Private-label program operators specifying preservative standards across supplier bases. German drugstore chains are tightening microbiological challenge-test requirements.
- Distributors:Bulk chemical intermediaries managing inventory and qualification documentation. Southeast Asian distributors are consolidating around halal-certified synthetic portfolios.
Manufacturers absorb the highest compliance burden; retailer private-label programs are gaining share fastest on specification consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Batam Island's free trade zone concentrates Indonesian halal-certified cosmetic manufacturing, drawing preservative suppliers into Southeast Asian special economic corridors.
Indonesia
Halal certification mandates for cosmetics are accelerating reformulation demand across phenoxyethanol and paraben alternatives. The national halal product assurance agency enforces strict alcohol-free standards that exclude conventional ethanol-based biocides. Manufacturing clusters in Batam and Jakarta absorb rising volumes of benzyl alcohol and synthetic alternatives.
Germany
Clean-label skincare brands in Berlin and Hamburg are expanding phenoxyethanol-boosted systems as REACH eliminates formaldehyde-releasing preservatives. ECHA restrictions on quaternium-15 and DMDM hydantoin are compressing supplier margins through accumulated qualification costs. The Rhine-Ruhr chemical corridor hosts encapsulated preservation technology pilots for sensitive skin applications.
France
Premium facial moisturizer manufacturers in Paris and Lyon require sophisticated multi-phase antimicrobial combinations to pass tightened microbiological challenge testing. ANSM oversight of cosmetic safety assessments is extending documentation requirements for novel preservation systems. The Île-de-France region anchors microbiome-friendly positioning development for probiotic skincare lines.
South Korea
K-beauty essence and ampoule formats specify low-irritation preservation for damaged-skin positioning in Seoul and Incheon production zones. MFDS cosmetic safety regulations govern allowable preservative concentrations in transparent gel systems. The Gyeonggi-do cluster specializes in micro-batch manufacturing for direct-to-consumer subscription channels.
United States
Indie beauty brands in Los Angeles and New York are fragmenting bulk procurement patterns through custom preservation packages for limited-batch releases. FDA concentration limits and state-level labeling disclosures create compliance complexity across rinse-off and leave-on categories. California's Proposition 65 warnings for certain synthetic actives are driving reformulation toward alternative chemistries.
Personal Care and Cosmetic Preservatives Market Competitive Landscape
German producers anchor one tier; Swiss specialists hold differentiated positions in botanical-derived systems. The supplier base concentrates around integrated petrochemical houses and dedicated cosmetic ingredient divisions. Three archetypes dominate: integrated phenol-chain operators, microbiological testing service providers, and botanical preservation system developers. Competitive moves center on ECHA compliance margin rebuilding and Southeast Asian halal certification qualification.
Within the integrated chemical tier, BASF SE exemplifies backward control over phenoxyethanol production chains that sustain compliance economics under evolving restrictions. Lonza Group occupies a position bridging specialized microbiological testing services with preservative portfolio anchoring. Symrise AG represents the botanical-derived archetype, navigating clean-label certification requirements through plant-based preservation systems.
| Leading Market Players |
|---|
| BASF SE |
| Ashland Global Holdings |
| Lonza Group |
| Clariant AG |
| Evonik Industries |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| Dow Inc. |
| Croda International |
| Others |
Value Network & Pricing Analysis
Phenol feedstock costs cascade from Gulf Coast petrochemical corridors through phenoxyethanol production tiers, concentrating pricing power among integrated operators while fragmenting margin structures for non-integrated formulators dependent on spot market exposure.
Pricing Analysis
Lead-time premiums compress as inventory cycles tighten, with spot purchasers in Southeast Asian halal-certified segments absorbing volatility while European contract buyers lock multi-year offtake at stabilized rates. Three-tier pricing structure across premium encapsulated actives, standard phenoxyethanol grades, and economy paraben blends reflects certification grade and volume scale differentiation. Pricing pressure stems from ECHA qualification cost accumulation as formaldehyde-releasing alternatives exit. Mass-market manufacturers in Indonesia exhibit highest price sensitivity; premium skincare brands in Germany and France prioritize performance over unit cost.
Supply Chain Analysis
Freight cost spikes from Rotterdam to Jakarta have reconfigured regional sourcing patterns, with distributors consolidating around Singapore hub stocking to mitigate Red Sea route uncertainty. Phenol production clusters in the United States, Germany, and Saudi Arabia feed global phenoxyethanol synthesis, while sorbic acid sourcing centers on China and Eastern European fermentation facilities. Raw material dependencies on benzene derivatives, ethylene oxide, and crotonaldehyde expose margins to commodity volatility. Single-source vulnerability concentrates in Gulf Coast hurricane corridors. Distribution runs through specialized chemical distributors with halal certification documentation capabilities serving Southeast Asian manufacturing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines function as a cost-of-compliance moat, with ECHA biocide renewal cycles extending to 36-48 months and freezing formulation pipelines for undercapitalized entrants.
For Market Incumbents: Deploy microbiological testing service bundling to anchor client relationships as formaldehyde-releasing alternatives face elimination. BASF SE exemplifies backward integration into phenol chains that sustains margin structures under regulatory compression. Incumbents should consolidate halal certification qualification assets across Malaysian and Indonesian distribution networks before mid-tier competitors accumulate compliance expertise. For New Entrants and Emerging Players: Begin with microbiome-friendly positioning in South Korean probiotic skincare segments where selective antimicrobial systems command premium positioning and regulatory pathways remain less congested than European biocide authorization. Direct-to-consumer subscription channels in Seoul and Los Angeles offer penetrable white-space for custom preservation packages. A go-to-market angle anchored in AI-driven challenge testing compliance can compress development cycle differentiation against established microbiological service providers. For Investors and Strategic Acquirers: ECHA's publication of consolidated formaldehyde-restricted substance lists is the leading indicator that qualification cost accumulation will accelerate supplier consolidation. The 5-10 year viability window favors acquisition targets with captive halal certification infrastructure and Southeast Asian distributor relationships. Signal to watch: Indonesian national halal product assurance agency expansion into mandatory pre-market approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Supply | Gulf Coast captive production insulates BASF SE from hurricane-season force majeure disruptions. |
| Halal Certification Qualification | Indonesian agency mandates create defensible positioning in Southeast Asia's fastest-expanding cosmetics consumption zone. |
| Microbiome-Friendly R&D Investment | Selective antimicrobial development opens premium pricing in South Korean probiotic skincare formulations. |
| AI-Driven Challenge Testing Deployment | EU AI Act compliance frameworks compress development cycles for novel active combination validation. |
| Encapsulation Technology Licensing | Lipid-based delivery systems stabilize phenoxyethanol release profiles for German sensitive-skin facial applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cosmetic chemists, regulatory affairs directors at preservative suppliers, brand formulators, and Southeast Asian distribution channel managers. Secondary validation drew from ECHA biocidal product registrations, FDA cosmetic ingredient statements, Indonesian halal product assurance agency publications, and European customs trade flows. Bottom-up volume modeling triangulated against top-down market sizing across product type, formulation chemistry, and regional consumption clusters.
Granularity-level modeling preserved segment-specific dynamics, with preservative class volumes assessed by formulation type complexity and regional regulatory exposure. End-use application segmentation captured skincare, haircare, makeup, and fragrance category differentiation. CAGRs derived from regression analysis against macroeconomic indicators and regulatory event timelines. Industry-specific inputs included ECHA authorization renewal schedules, Indonesian halal mandate implementation phases, and K-beauty export volume trajectories.
Underlying measurement precision varies by segment; emulsion and gel formulation data carry tighter precision than powder format estimates due to transparent production reporting in water-containing systems. Forecasts reflect assumptions on regulatory timeline adherence and substitution elasticity that ECHA restriction acceleration or Indonesian mandate delay could revise. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Facial Makeup Setting Spray Market
Beauty & Personal Care
Spray Tanning Market
Beauty & Personal Care
Foaming Hand Soaps Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Body Balm Market
Beauty & Personal Care
Europe Cosmeceuticals Market
Beauty & Personal Care
Italy Beauty and Personal Care Products Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Beauty and Wellness Products Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Color Cosmetics Market
Beauty & Personal Care
US Color Cosmetics Market