
 Leave-In Conditioner Market | 2026-2036
Leave-In Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Leave-In Conditioner Market Analytics
The formulation-versus-branding capability gap is rotating competitive investment toward in-house labs and captive ingredient sourcing. L'Oréal S.A. leverages its dedicated hair-science research campuses to control emulsion stability and silicone-alternative pipelines. Procter & Gamble Co. anchors North American retail presence through mass-channel shelf-space agreements and replenishment algorithms. Kao Corporation differentiates in Asian markets with fermented-biopolymer conditioning agents developed through internal biotechnology platforms.
Leave-in conditioner denotes a no-rinse hair treatment product containing cationic surfactants, fatty alcohols, and humectants at pH 4.0–5.5, designed to reduce combing friction and seal cuticle scales between washes. Cream formats dominate mass-market volume due to higher per-unit viscosity and perceived conditioning intensity, while spray variants capture travel and gym-bag occasions where portability outweighs dosage precision. Salon distribution channels command premium positioning through professional-exclusive SKUs with elevated active-ingredient concentrations, whereas online channels concentrate subscription-driven replenishment for textured-hair communities.
Regulators including the FDA, EPA, and ECHA govern cosmetic ingredient safety through pre-market notification thresholds and restricted substance lists, compelling brands to document preservative system biodegradability and exclude formaldehyde-releasing compounds. REACH compliance costs particularly burden mid-size exporters seeking European market access, while California's Proposition 65 warning requirements create state-level formulation divergence within the United States. Stakeholders must monitor emerging state-level chemical disclosure mandates and biopolymer certification standards to anticipate reformulation timelines and geographic portfolio prioritization.
Market Dynamics
Biodegradable surfactant substitution is compressing legacy silicone supply chains while elevating captive fermentation capacity as the decisive competitive moat. Brands lacking in-house biopolymer pipelines face margin compression from REACH compliance costs and reformulation timelines.
Growth Catalysts
- EU Green Deal chemical footprint rules:Mandatory biodegradability disclosure is accelerating reformulation investment toward plant-derived cationic surfactants in European formulations.
- Salon professional protocols:Post-treatment standardization is elevating professional-exclusive SKUs with concentrated active loads as a recurring revenue anchor.
- Textured-hair specialization:Direct-to-consumer subscription models targeting curl-pattern diversity are capturing higher lifetime value through replenishment algorithms.
Market Restraints
- Silicone price volatility:Cyclohexane-derived dimethicone supply concentrates in Chinese petrochemical corridors, exposing formulators to feedstock swings.
- REACH compliance burden:Mid-size exporters face documentation costs exceeding six-figure euro thresholds for European market access.
- Preservative system limitations:Formaldehyde-releasing compound bans eliminate cost-effective broad-spectrum options, forcing phenoxyethanol-caprylyl glycol blends at higher unit cost.
Strategic Opportunities
- India personal care expansion:BIS cosmetic safety standards harmonization is lowering import friction for brands establishing local fermentation partnerships.
- Fermented-biopolymer conditioning agents:Convergence of biotechnology platforms with cosmetic formulation science enables novel emulsion stability without quaternary ammonium compounds.
- Professional channel digitization:Salon-exclusive e-commerce portals with licensed-stylist verification are capturing margin previously lost to diversion.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation scientists capable of bridging emulsion stability and biodegradability certification remain concentrated in Western European and Japanese labor markets.
- Multi-jurisdiction labeling divergence:California Proposition 65 warning requirements force SKU fragmentation distinct from FDA-compliant national packaging.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Leave-In Conditioner Market |
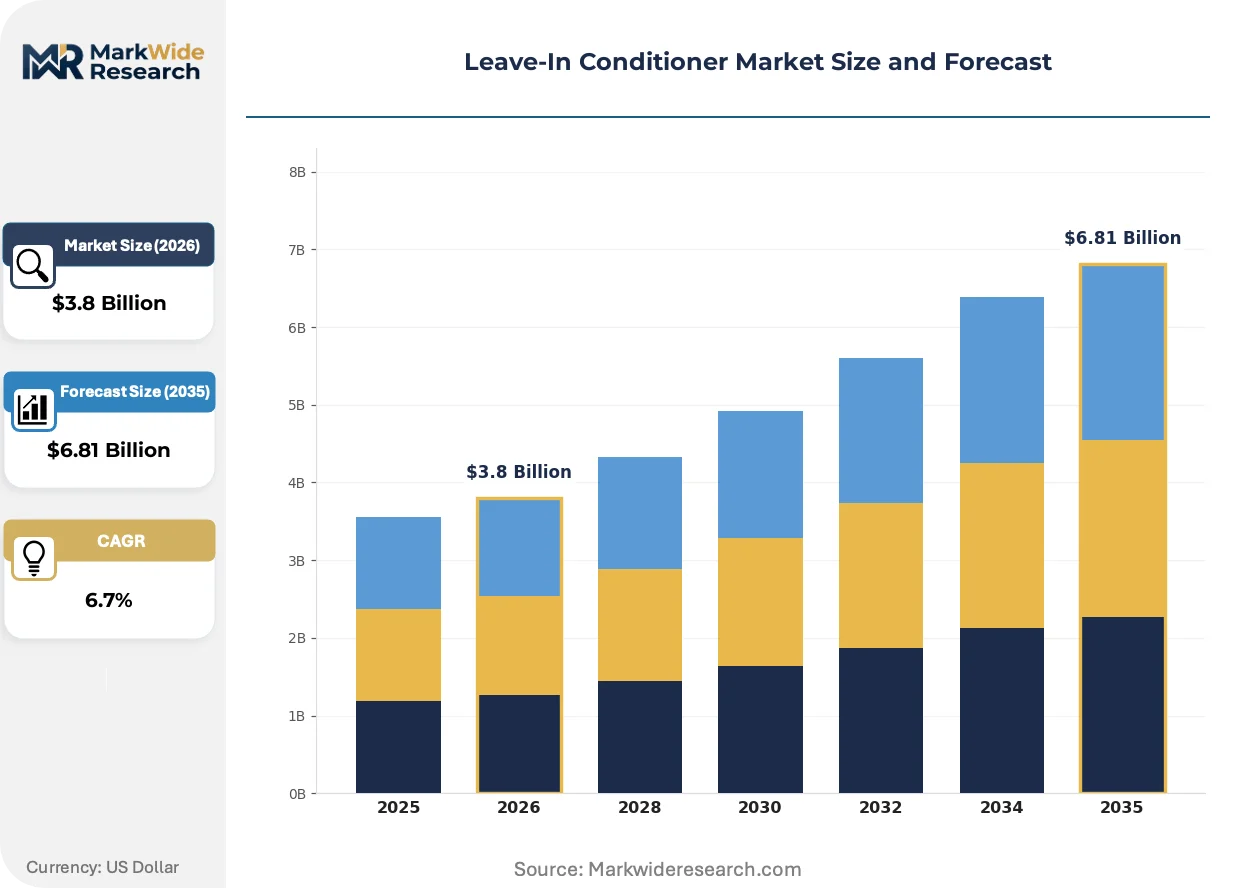
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cream, Spray, Gel, Balm Ingredients: Coconut Oil, Argan Oil, Shea Butter, Aloe Vera End User: Adults, Children, Salon Professionals, Home Users Distribution Channel: Online, Specialty Stores, Supermarkets, Salons |
| Companies Covered | Henkel AG & Co. KGaA, Johnson & Johnson Consumer Inc., L'Oréal S.A., Sol de Janeiro USA Inc., Moroccanoil Israel Ltd, Unilever PLC, Estée Lauder Companies Inc., Kao Corporation, Procter & Gamble Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Leave-In Conditioner Market Evolving Landscape
Silicone-alternative chemistry is fragmenting competitive advantage away from petrochemical supply relationships toward biotechnology capabilities. Three concurrent developments are compressing legacy formulation paradigms.
Fermented polysaccharide conditioning agents are bifurcating the emulsion-stability landscape. Kao Corporation's internal biotechnology platforms demonstrate commercial viability at scale. Salon professionals and textured-hair consumers are migrating toward these biopolymers despite higher per-unit cost, compressing conventional dimethicone demand in premium tiers.
REACH Annex XVII restrictions on persistent organic pollutants are forcing preservative system redesigns across European-exporting formulators. The industrial consequence is accelerated phenoxyethanol dependency and supply concentration among three approved manufacturers. Mid-market brands are responding through backward integration into captive preservative blending facilities to secure volume commitments.
Subscription-based replenishment is displacing retail shelf-space dependency for textured-hair communities. Direct-to-consumer platforms with algorithmic curl-pattern matching are capturing recurring revenue previously routed through mass-channel distributors. This pattern concentrates in United States metropolitan markets with established natural-hair salon infrastructure.
Leave-In Conditioner Market Segmentation
Leave-in conditioner segmentation reveals how formulation chemistry, professional protocols, and channel economics create distinct competitive battlegrounds. Each dimension carries regulatory and margin implications that reshape investment priorities across the value chain.
Product Type:
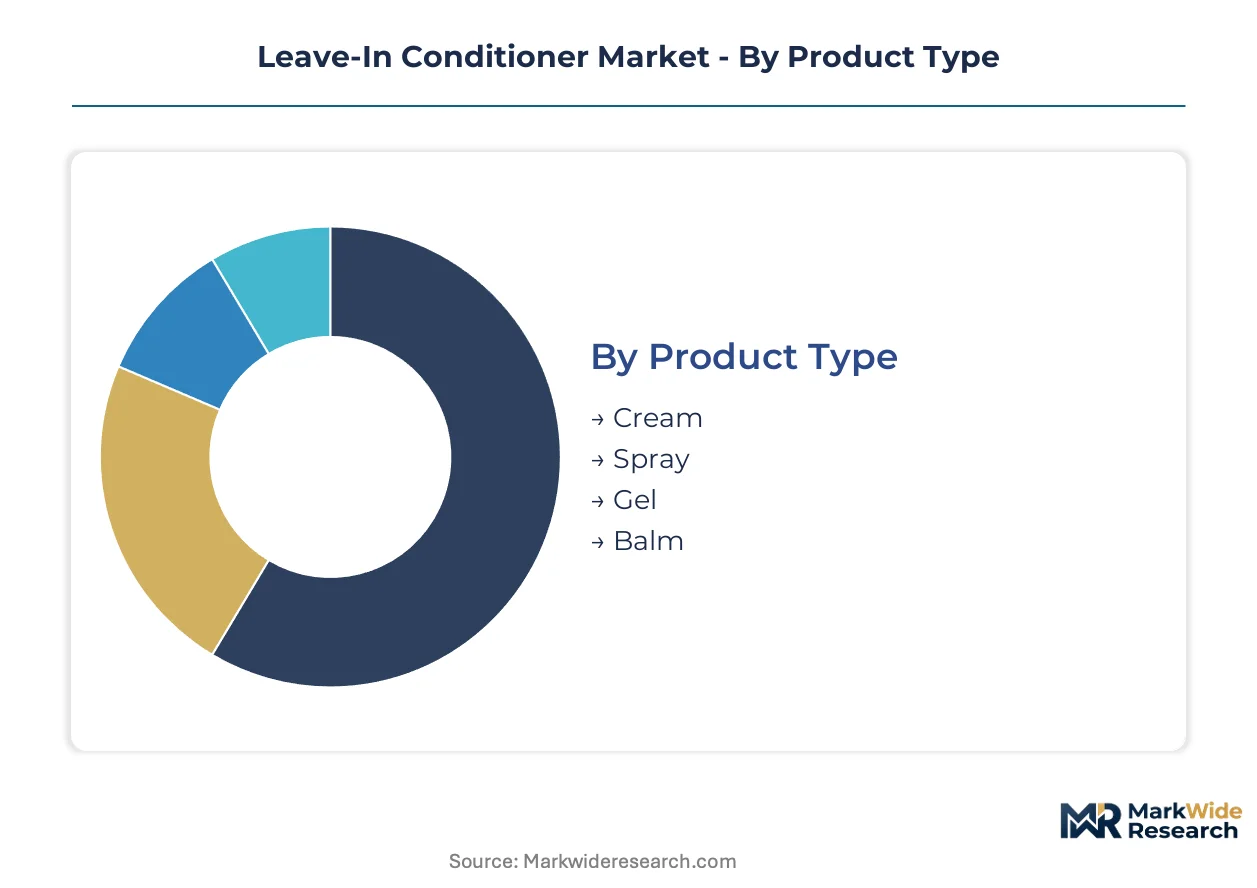
ECHA REACH Annex XVII restrictions on persistent organic pollutants force divergent formulation strategies across cream, spray, gel, and balm formats, with biodegradability certification becoming the gating factor for European market access.
- Cream:High-viscosity emulsions containing cationic surfactants and fatty alcohols at pH 4.0–5.5 deliver maximum cuticle sealing. United States mass-market volume concentrates here due to perceived conditioning intensity and shelf-space economics at Walmart and Target.
- Spray:Low-viscosity aqueous dispersions with atomized delivery systems prioritize portability over dosage precision. Gym-bag and travel occasions in metropolitan United States markets drive fastest share expansion through direct-to-consumer subscription platforms.
- Gel:Hydroxyethylcellulose-thickened formulations with humectant-heavy compositions target curl definition without weight. Salon professionals in textured-hair communities specify gel formats for wash-and-go protocols.
- Balm:Solid-to-emulsion anhydrous bases with high melting-point waxes and butters serve protective styling needs. African-American consumer clusters in Atlanta and Houston anchor balm demand through specialty retail.
Cream handles the majority of throughput; Spray is expanding most quickly on share through algorithmic replenishment models.
Ingredients:
Raw material sourcing geography determines compliance burden and margin structure, with plant-derived alternatives commanding premium positioning against petrochemical legacy inputs.
- Coconut Oil:Lauric acid-rich triglyceride with proven cuticle penetration and film-forming properties. Kerala and Tamil Nadu supply chains in India face BIS cosmetic safety standards harmonization delays that complicate import logistics for mid-size brands.
- Argan Oil:Moroccan-sourced linoleic acid concentrate with antioxidant tocopherol content. European formulators pay REACH documentation premiums for argan-derived formulations, compressing mass-market applicability.
- Shea Butter:West African karite nut extract with stearic and oleic acid profile. Ghana and Burkina Faso cooperative sourcing faces climate volatility and export infrastructure constraints.
- Aloe Vera:Polysaccharide-rich mucilage with humectant and anti-inflammatory properties. Mexican and Texan cultivation zones supply North American natural-positioned brands with shorter carbon footprint credentials.
Coconut Oil anchors volume through cost-competitive Indian supply; Argan Oil climbs the fastest on share through professional-channel premiumization.
End User:
Application expertise and purchase frequency create divergent lifetime value profiles that reshape channel investment and SKU architecture.
- Adults:Primary decision-makers with established hair-care routines and brand loyalty patterns. United States direct-to-consumer platforms capture recurring revenue through curl-pattern matching algorithms.
- Children:Gentle-formulation requirements with tear-free and hypoallergenic positioning. Pediatric dermatologist recommendations drive pharmacy and specialty store distribution.
- Salon Professionals:Licensed practitioners with post-treatment protocol standardization authority. Professional-exclusive SKUs with elevated active concentrations generate recurring B2B revenue through distributor relationships.
- Home Users:Non-professional consumers seeking salon-equivalent results without service costs. Mass-market retail and online subscription channels concentrate here.
Adults generate the majority of revenue volume; Salon Professionals deliver the steepest expansion trajectory through protocol standardization.
Distribution Channel:
Channel selection determines margin capture, regulatory exposure, and consumer data ownership in divergent ways across the value chain.
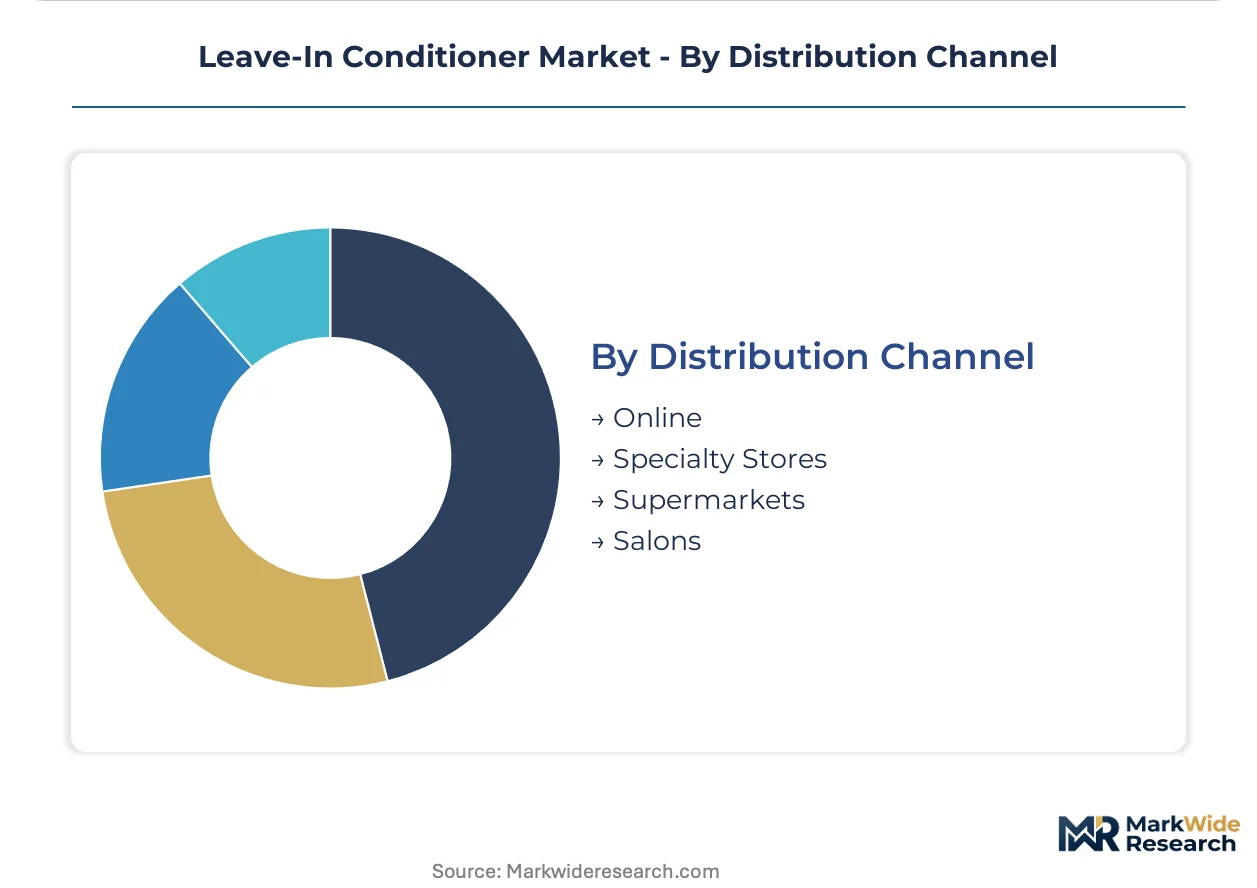
- Online:Direct-to-consumer platforms with algorithmic replenishment and curl-pattern personalization. United States textured-hair communities concentrate here, bypassing traditional retail markup structures.
- Specialty Stores:Curated assortments with educated staff and sampling infrastructure. Sephora and Ulta Beauty in the United States anchor premium and masstige positioning.
- Supermarkets:High-velocity mass-market placement with price-promotion dependency. Walmart shelf-space agreements and replenishment algorithms dominate volume.
- Salons:Licensed-stylist verification with professional-exclusive SKU distribution. Diversion control and margin retention priorities drive brand investment here.
Supermarkets handle the majority of unit throughput; Online channels gain share fastest through subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while European compliance costs compress margins. German formulators absorb REACH documentation premiums that American competitors avoid. Asian biotechnology platforms in Japan and India are capturing value through fermented-biopolymer differentiation.
United States
Textured-hair specialization and direct-to-consumer subscription models concentrate demand in Atlanta, Houston, and New York metropolitan clusters. FDA cosmetic ingredient regulations govern preservative system approvals, while California Proposition 65 mandates state-specific warning labels. Sephora and Ulta Beauty anchor premium distribution in Los Angeles and Chicago, with algorithmic replenishment platforms capturing recurring revenue from curl-pattern communities.
Germany
Professional salon protocols and ECHA REACH Annex XVII compliance drive reformulation toward biodegradable surfactants. EU Green Deal chemical footprint disclosure rules elevate documentation costs for exporters targeting European market access. Cologne and Düsseldorf industrial clusters host contract manufacturing facilities serving premium private-label brands.
Japan
Fermented-biopolymer conditioning agents developed through internal biotechnology platforms differentiate domestic formulators. METI industrial standards govern cosmetic safety certifications, while PMDA oversight ensures preservative system approvals. Tokyo and Osaka metropolitan areas concentrate R&D campuses controlling emulsion stability pipelines.
India
BIS cosmetic safety standards harmonization is lowering import friction for brands establishing local fermentation partnerships. Kerala and Tamil Nadu coconut oil supply chains face documentation delays that complicate logistics for mid-size exporters. Mumbai and Bangalore urban clusters drive direct-to-consumer platform expansion for textured-hair communities.
Brazil
ANVISA pharmaceutical and cosmetic regulations govern ingredient safety approvals for Latin American market access. Shea butter sourcing from West African cooperatives transits through São Paulo distribution hubs. Rio de Janeiro and Minas Gerais metropolitan areas concentrate specialty retail infrastructure for protective styling products.
Leave-In Conditioner Market Competitive Landscape
Concentration sits with multinational personal care conglomerates controlling captive ingredient sourcing and salon distribution relationships. Three to five global players anchor mass-market shelf-space agreements through replenishment algorithms with Walmart and Target. Strategic archetypes include biotechnology-integrated formulators, professional-channel specialists, and mass-market retail anchors. Competitive moves center on backward integration into fermentation capacity and diversion-control investments in licensed-stylist verification systems.
Within the biotechnology-integrated tier, Kao Corporation exemplifies internal platform development for fermented-biopolymer agents. L'Oréal S.A. and Procter & Gamble Co. occupy positions spanning professional-exclusive SKUs and mass-channel algorithmic replenishment. These three entities represent divergent strategic vectors: captive fermentation science, dedicated hair-science research campuses, and North American retail presence through shelf-space dominance.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| Johnson & Johnson Consumer Inc. |
| L'Oréal S.A. |
| Sol de Janeiro USA Inc. |
| Moroccanoil Israel Ltd |
| Unilever PLC |
| Estée Lauder Companies Inc. |
| Kao Corporation |
| Procter & Gamble Co. |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for dimethicone and fermented-biopolymer conditioning agents lock in supply access and price visibility for formulators navigating REACH compliance timelines and silicone price volatility. These contracts anchor margin stability while exposing mid-size brands to working capital constraints when reformulation cycles accelerate.
Pricing Analysis
The customization-premium spread separates professional-exclusive SKUs with elevated active concentrations from mass-market standard formulations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel exclusivity, with salon distribution commanding the widest spreads. Pricing pressure stems from phenoxyethanol-caprylyl glycol blend costs following formaldehyde-releasing compound bans. Home users exhibit highest price sensitivity, while salon professionals prioritize performance over unit economics.
Supply Chain Analysis
Inbound logistics costs from Kerala and Tamil Nadu coconut oil corridors through Mumbai port congestion compress margins for Indian-sourced lauric acid derivatives. Manufacturing concentrates in China for cyclohexane-derived dimethicone, Germany for REACH-compliant surfactant synthesis, and Japan for fermented-biopolymer platforms. Raw material dependencies include Moroccan argan oil, Ghanaian shea butter, and Indian coconut oil. Single-source vulnerability in Chinese petrochemical corridors exposes formulators to feedstock swings. Distribution runs through Walmart and Target replenishment algorithms for mass volume, with direct-to-consumer platforms capturing textured-hair subscription demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Walmart and Target shelf-space consolidation and algorithmic replenishment platforms, fragmenting negotiating leverage among mid-size formulators.
For Market Incumbents: Compound captive fermentation capacity advantages before biotechnology talent scarcity intensifies. Backward integration into phenoxyethanol blending facilities secures volume commitments amid supply concentration among three approved manufacturers. Defend professional-channel margins through licensed-stylist verification systems that prevent diversion. For New Entrants and Emerging Players: Algorithmic curl-pattern matching services represent a service-layer gap where incumbents under-serve textured-hair communities with generic recommendations. Target direct-to-consumer subscription platforms in Atlanta and Houston metropolitan clusters where natural-hair salon infrastructure supports community validation. Pursue BIS cosmetic safety standards harmonization partnerships in India to bypass Kerala supply chain documentation delays. For Investors and Strategic Acquirers: Capital is best deployed toward biotechnology-integrated formulators with internal fermentation pipelines and professional-channel exclusivity agreements. Long-term viability rests on defensible emulsion stability IP and diversion-control infrastructure rather than brand equity alone. Monitor EU Green Deal chemical footprint disclosure enforcement as the inflection signal for reformulation investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fermentation Capacity Buildout | Internal biopolymer pipelines bypass REACH compliance cost premiums and secure emulsion stability IP. |
| Professional Channel Digitization | Licensed-stylist verification portals capture margin previously lost to diversion in salon distribution. |
| Direct-to-Consumer Subscription Launch | Algorithmic replenishment platforms bypass retail markup structures in textured-hair communities. |
| Backward Integration into Preservative Blending | Captive phenoxyethanol facilities secure volume commitments amid three-manufacturer supply concentration. |
| India Local Fermentation Partnership | BIS standards harmonization lowers import friction and anchors Kerala supply chain access. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with cosmetic formulation scientists, salon distribution managers, retail category buyers, and contract manufacturing executives. Secondary validation drew from FDA cosmetic ingredient filings, ECHA REACH Annex XVII substance restrictions, customs trade data for coconut oil and argan oil corridors, and SEC 10-K disclosures from personal care conglomerates. Bottom-up volume modeling and top-down value reconciliation triangulated outputs across the analysis window.
Across the projection horizon, the analytical framework segmented by product format, ingredient sourcing geography, end-user archetype, and distribution channel. CAGRs were derived from regression against historical volume trajectories and regulatory timeline assumptions. Fermented-biopolymer adoption curves and REACH compliance cost pass-through rates served as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA cosmetic safety standards and ECHA REACH enforcement; material policy shifts would require re-modeling. Silicone price volatility, biopolymer certification delays, and state-level chemical disclosure mandates represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Personal Care Products Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Australia Skin Care Products Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Deodorant Wipes Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market