
 United States Bath Soap Market | 2026-2036
United States Bath Soap Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bath Soap Market Intelligence
Leaping Bunny cruelty-free certification is reorganizing competitive access in the United States bath soap landscape, forcing reformulation investments that favor established operators with dedicated compliance infrastructure. Procter & Gamble leverages its massive R&D footprint to maintain shelf dominance across mass retail channels. Dr. Bronner's anchors the organic segment through vertically controlled supply chains spanning fair-trade ingredient sourcing. Unilever competes across multiple price tiers through distinct brand architectures that separate premium positioning from value offerings.
United States bath soap comprises surfactant-based cleansing formulations, typically incorporating sodium tallowate or sodium cocoate as base saponified oils, designed for epidermal hygiene and skin conditioning during bathing or showering. Bar soap retains volume leadership in dollar stores and rural markets, yet liquid soap and shower gel command margin premiums through concentrated formulations and premium packaging that supports higher per-unit pricing. Natural and organic ingredient types capture the fastest expansion as consumers scrutinize INCI lists, while antibacterial claims face regulatory contraction under FDA scrutiny. Online retail channels disrupt traditional supermarket and drugstore distribution by enabling direct-to-consumer subscription models that bypass slotting fee barriers.
FDA oversight under MoCRA tightens facility registration and adverse event reporting obligations, elevating compliance costs that disproportionately burden smaller craft producers. EPA guidelines on antimicrobial active ingredients, particularly triclosan and benzalkonium chloride, continue restricting formulation options for antibacterial-positioned products. California's Proposition 65 warning requirements and the state's Safer Consumer Products regulations add a secondary compliance layer that shapes ingredient selection for brands distributing nationally. Stakeholders must monitor pending federal preemption debates that could either harmonize standards or fragment them further across state lines.
Market Dynamics
MoCRA facility registration mandates and adverse event reporting obligations are forcing capital reallocations across the United States bath soap supply base, advantaging operators with captive compliance infrastructure over craft producers dependent on third-party manufacturers.
Growth Catalysts
- Clean Beauty Corridor Concentration:California's Proposition 65 enforcement and Safer Consumer Products regulations are accelerating reformulation toward plant-derived surfactants. Brands distributing nationally must design for this standard, elevating ingredient transparency as a competitive filter.
- Leaping Bunny Certification:Cruelty-free verification is reorganizing retail access, with mass-market chains requiring documentation for shelf placement. This pulls formulation decisions upstream into supplier qualification protocols.
- Subscription Commerce Infrastructure:Direct-to-consumer replenishment models bypass slotting fee barriers that historically constrained indie brand expansion. Shopify and specialized logistics providers enable margin capture previously lost to retail intermediaries.
Market Restraints
- Palm Oil Price Volatility:Sodium palmate and derivative surfactants face input cost pressure from Malaysian and Indonesian supply concentration. Formulators lack short-term substitution options without performance trade-offs.
- Antibacterial Active Restrictions:EPA guidelines on benzalkonium chloride and FDA scrutiny of triclosan have eliminated a once-differentiated product category. Brands must reposition without the clinical positioning that previously commanded premium pricing.
- Glass and Aluminum Packaging Cost Structure:Premium positioning requires material upgrades that inflate unit economics. Recyclable rigid formats carry 40-60% cost premiums over plastic alternatives that mass-market consumers accept.
Strategic Opportunities
- Waterless Solid Formats:Concentrated cleansing bars eliminate shipping weight and preservative load. Early movers in solid shampoo and conditioner adjacencies demonstrate consumer acceptance of format migration.
- Upcycled Ingredient Sourcing:Food waste streams—coffee grounds, fruit peels, spent grain—offer certified supply inputs that satisfy clean beauty narrative requirements while reducing raw material cost exposure.
- Clinical Positioning Through Dermatologist Partnership:Prescription-adjacent distribution via telehealth platforms and medical spa channels creates access to consumers with diagnosed skin conditions seeking non-pharmaceutical maintenance solutions.
Industry Challenges
- INCI Literacy Gap in Marketing Functions:Technical translation of ingredient provenance into compliant claims requires specialized regulatory writing talent. Smaller brands struggle to staff this function internally.
- Reformulation Timeline Compression:State-level regulatory changes in California propagate faster than traditional 18-24 month product development cycles. Brands must maintain parallel formulation tracks to avoid distribution interruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bath Soap Market |
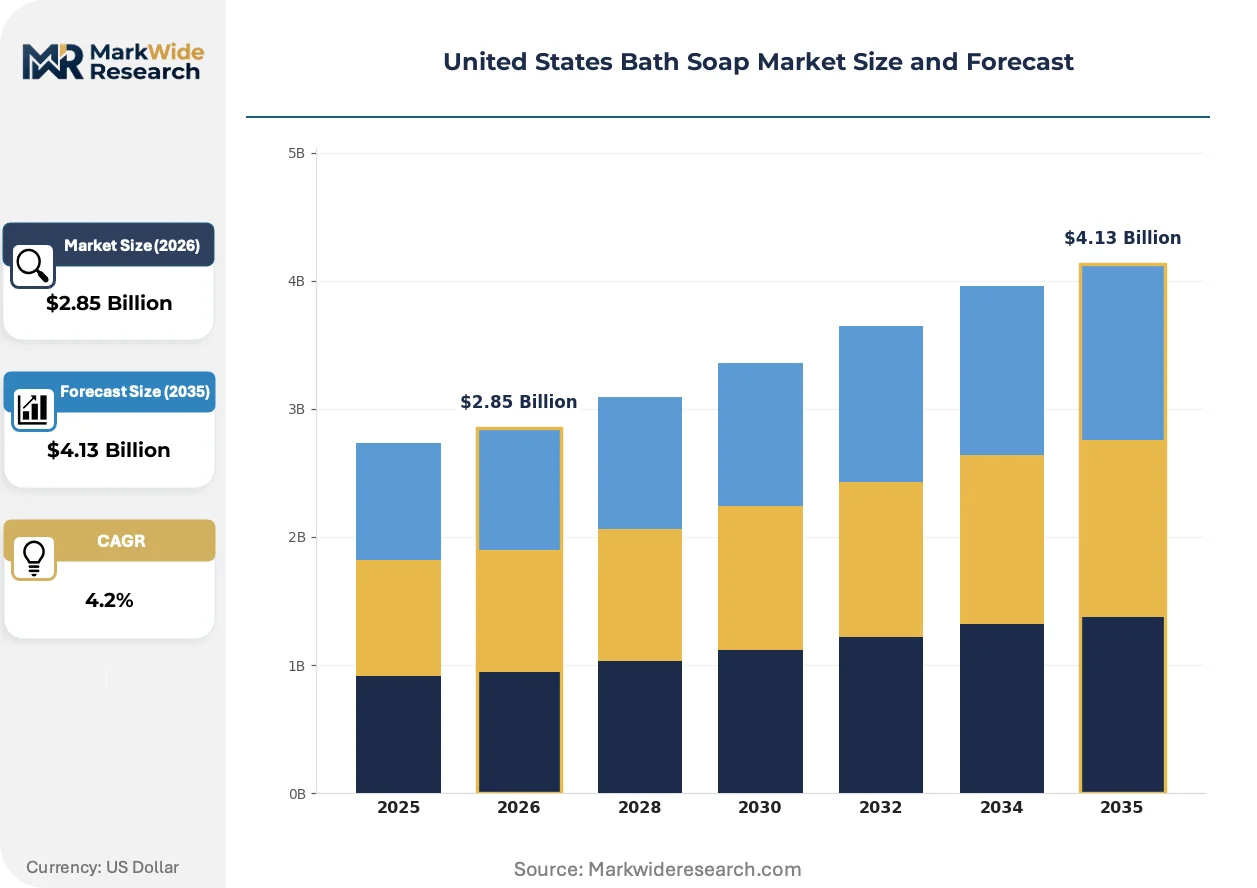
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foam Soap, Shower Gel Ingredient Type: Natural, Synthetic, Organic, Antibacterial End User: Adults, Children, Seniors, Infants Distribution Channel: Online Retail, Supermarkets, Drugstores, Convenience Stores |
| Companies Covered | Colgate-Palmolive, Dr. Squatch, Procter & Gamble, Chagrin Valley Soap & Salve, Buff City Soap, Unilever, Dr. Bronner's, Commonwealth Soap & Toiletries, Johnson & Johnson, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bath Soap Market Strategic Shifts & Innovations
Ingredient disclosure depth and format innovation are compressing traditional category boundaries between bar, liquid, and solid formats while regulatory transparency mandates reshape how brands communicate with consumers.
Syndet-based cleansing bars—synthetic detergent formulations that bypass traditional saponification—are fragmenting the historical bar-versus-liquid dichotomy. Millennials and Gen Z households in coastal metro areas are adopting these formats at rates that mass-market brands now track for portfolio expansion. The technology is fragmenting manufacturing infrastructure, as syndet production requires equipment distinct from conventional soap lines, forcing contract manufacturers to duplicate capital investment or specialize.
MoCRA's Modernization of Cosmetics Regulation Act facility registration and adverse event reporting requirements are tightening enforcement bandwidth at FDA. Small-batch producers face disproportionate compliance cost absorption relative to revenue, accelerating consolidation toward integrated manufacturers with dedicated regulatory affairs staff. The Northeast's urban corridor, with its density of indie brands and contract manufacturing partners, is experiencing the most visible operational restructuring as registration deadlines approach.
Ingredient scrutiny has migrated from niche clean beauty consumers to mainstream purchase behavior, with buyers cross-referencing INCI lists against EWG Skin Deep and similar databases prior to purchase. Mass-market retailers are responding with simplified formulation badges that communicate compliance without requiring consumer education. This pattern concentrates in California and Pacific Northwest markets before propagating through Target and Walmart's national shelf-reset cycles.
United States Bath Soap Market Segmentation
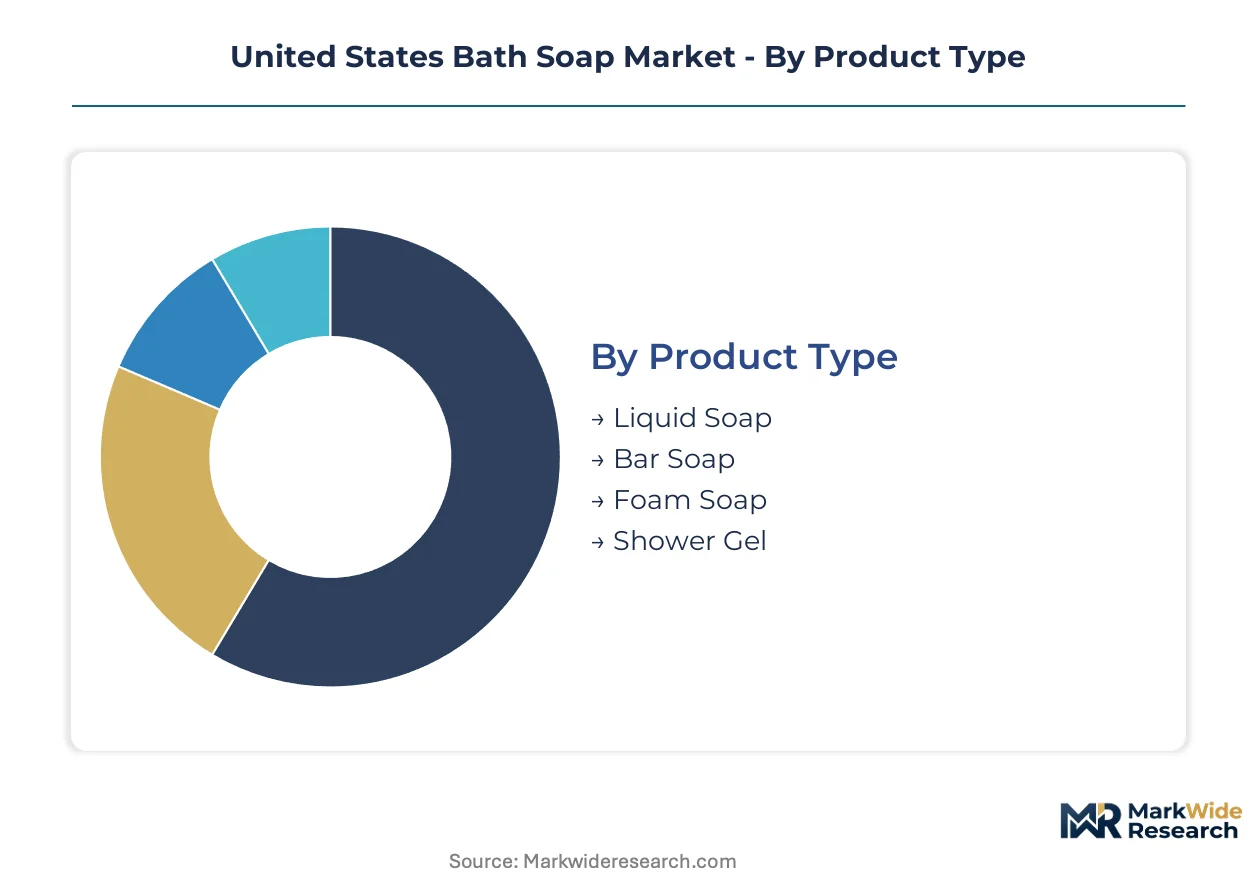
Segmentation in the United States bath soap market reveals how formulation choices, retail access, and demographic targeting fragment margin capture across distinct consumer tribes. Understanding these divides exposes where premium pricing commands shelf space versus where volume throughput dominates.
Product Type:
Margin pools concentrate in concentrated formats that reduce shipping weight and support subscription replenishment economics.
- Liquid Soap:Pump-dispensed surfactant formulations leverage concentrated chemistry to reduce per-use cost while commanding 30-40% price premiums over bar equivalents. Demand clusters in suburban households with children, driven by hygiene theater and ease-of-use preferences that justify recurring purchase.
- Bar Soap:Traditional saponified oil blocks retain cost leadership through minimal packaging and established manufacturing infrastructure. Volume concentrates in dollar store channels and rural markets where price sensitivity overrides format preference, though premium artisan bars are gaining traction in coastal metros.
- Foam Soap:Pre-aerated formulations reduce surfactant loading per dispense while delivering sensorial satisfaction through texture.
- Shower Gel:Thickened liquid formulations with added conditioning agents target skin-conscious consumers seeking post-wash moisture retention.
The dominant share belongs to Bar Soap, while Liquid Soap is closing the gap fastest.
Ingredient Type:
Cost tier stratification runs deepest here, with certification premiums separating accessible mass-market from prestige positioning.
- Natural:Plant-derived surfactants and saponified oils—coconut, olive, shea—command price premiums through supply chain traceability claims. Demand concentrates in California's clean beauty corridor and Pacific Northwest urban clusters where EWG Skin Deep cross-referencing is standard pre-purchase behavior.
- Organic:USDA-certified formulations with restricted synthetic inputs target the highest willingness-to-pay segment. Supply constraints from certified agricultural sourcing limit scale, preserving margin density for operators with vertically controlled ingredient relationships.
- Synthetic:Petrochemical-derived surfactants—sodium lauryl sulfate, cocamidopropyl betaine—deliver consistent performance at lowest unit cost.
- Antibacterial:Triclosan and benzalkonium chloride formulations face EPA and FDA contraction, eliminating a once-differentiated positioning.
Synthetic ingredients still move the most volume, though Organic is expanding most quickly as certification infrastructure matures.
End User:
Application-specific formulation requirements create distinct R&D investment tracks with varying amortization potential.
- Adults:The broadest addressable market spanning mass functional to prestige sensorial positioning. Fragrance complexity and skin condition targeting—acne, aging, sensitivity—drive portfolio proliferation with high SKU density requirements.
- Infants:Hypoallergenic formulations with minimal ingredient counts command extreme price premiums per ounce through safety signaling. Pediatrician recommendation channels and gift registry placement sustain margin structures that would collapse in standard retail.
- Children:Character-licensed packaging and mild-no-tear chemistry balance parent approval with child engagement.
- Seniors:Moisture-retention focus and easy-grip packaging address dermatological and ergonomic needs of aging skin.
Adult segments dominate current revenue, while Infant formulations show the steepest margin expansion trajectory.
Distribution Channel:
Customer acquisition economics diverge sharply between physical slotting fee barriers and digital direct relationships.
- Online Retail:Direct-to-consumer subscription models bypass slotting fees that consume 15-25% of wholesale revenue in physical retail. Shopify infrastructure and specialized bath-and-body logistics providers enable indie brand economics previously impossible at sub-$10M scale.
- Supermarkets:Mass-market volume throughput depends on trade promotion calendars and end-cap placement negotiations with Kroger, Albertsons, and regional chains.
- Drugstores:CVS and Walgreens shelf sets emphasize clinical positioning and travel-size convenience formats.
- Convenience Stores:Single-use and emergency purchase occasions prioritize portability and impulse price points over formulation sophistication.
Supermarkets retain the largest volume position, though Online Retail is gaining share fastest as replenishment automation matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial and Gen Z households in coastal metros drive the strongest per-capita spending on premium formulations. These buyer archetypes cluster in states with stringent ingredient transparency mandates, reshaping where manufacturers prioritize distribution infrastructure.
California
Clean beauty adoption concentrates in Los Angeles and San Francisco metro corridors. Proposition 65 enforcement and Safer Consumer Products regulations force national brands to design for California's disclosure standards first. The state's vertically integrated organic ingredient suppliers are expanding contract manufacturing capacity to serve brands distributing nationwide.
New York
Urban density in New York City supports the highest indie brand penetration outside California. The state's environmental conservation law amendments on packaging waste are accelerating shifts toward refillable and aluminum formats. Brooklyn-based direct-to-consumer startups leverage proximity to East Coast logistics hubs for subscription fulfillment.
Texas
Population growth in Dallas-Fort Worth and Houston sustains mass-market volume leadership. The state's business-friendly regulatory posture attracts manufacturing investment from brands seeking to bypass California compliance costs. Austin's emerging craft soap cluster benefits from local food waste upcycling partnerships with beverage and agriculture sectors.
Illinois
Chicago's retail headquarters density shapes national shelf-reset decisions for mass-market chains. The Midwest's distribution infrastructure advantages position the state as a fulfillment node for direct-to-consumer brands serving secondary markets. Local contract manufacturers are adding syndet bar production lines to capture format migration demand.
Florida
Retirement community concentrations in South Florida sustain senior-targeted moisturizing formulations. The state's tourism economy supports travel-size and hospitality amenity demand that differs from residential purchase patterns. Miami's position as Latin American trade gateway influences ingredient sourcing relationships with Brazilian and Colombian suppliers.
United States Bath Soap Market Key Industry Players
Player mix skews toward diversified consumer goods conglomerates with dedicated personal care divisions. Mass retail shelf dominance requires trade promotion budgets that constrain indie brand expansion. Three archetypes define competitive positioning: vertically integrated organic specialists, multi-brand portfolio operators with distinct premium and value tiers, and direct-to-consumer challengers bypassing slotting fees through subscription infrastructure. Consolidation pressure intensifies as MoCRA compliance costs disproportionately burden craft producers lacking captive regulatory affairs staff.
Among diversified consumer goods operators, Procter & Gamble and Unilever occupy positions spanning mass-market through prestige price tiers. Dr. Bronner's anchors the certified organic segment through vertically controlled fair-trade supply chains. These three exemplify how scale, certification infrastructure, and distribution architecture separate sustainable competitive position from commodity pressure.
| Leading Market Players |
|---|
| Colgate-Palmolive |
| Dr. Squatch |
| Procter & Gamble |
| Chagrin Valley Soap & Salve |
| Buff City Soap |
| Unilever |
| Dr. Bronner's |
| Commonwealth Soap & Toiletries |
| Johnson & Johnson |
| Others |
Cost & Logistics Intelligence
Contract manufacturing scale in Malaysian and Indonesian oleochemical facilities determines minimum efficient scale for sodium palmate derivatives, compressing margin structures for mid-tier brands while concentrating pricing power among integrated operators with captive surfactant production. This concentration feeds downstream into three-tier pricing structures across premium, standard, and economy levels that stratify by certification grade and channel access.
Pricing Analysis
Cost-plus contracts with palm kernel oil indexation dominate raw material procurement, passing through Malaysian Bursa Malaysia Derivatives Exchange volatility into finished goods pricing. Price differentiation hinges on Leaping Bunny certification tier and organic supply chain traceability, with premium tiers capturing margin from EWG-verified positioning. Cost compression in mass-market bar formats is intensifying because dollar store channel consolidation demands volume rebates. Price sensitivity concentrates in rural and suburban households purchasing through Walmart and dollar store channels, while coastal metro consumers show inelastic demand for certified clean beauty formulations.
Supply Chain Analysis
Inbound logistics costs from Port of Long Beach congestion and trans-Pacific container availability constraints have elevated working capital requirements for brands dependent on Asian oleochemical feedstocks. Supply concentrates in Malaysia, Indonesia, and the Philippines for palm-derived sodium palmate and coconut-based sodium cocoate, with secondary sourcing from Sri Lanka for virgin coconut oil grades. Raw material dependencies rest on surfactant intermediates, fragrance compounds from Grasse-region suppliers, and specialty packaging substrates. Single-source vulnerability runs through Malaysian oleochemical giants controlling fractionated fatty acid supply. Distribution runs through Target and Kroger's centralized replenishment systems for mass-market tiers, with Shopify-enabled direct fulfillment capturing premium segment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States bath soap market sits in early-cycle expansion as MoCRA-driven compliance costs accelerate consolidation toward scaled operators with captive regulatory infrastructure. Clean beauty adoption among millennial and Gen Z households sustains penetration growth in premium tiers previously inaccessible to mass-market brands.
For Market Incumbents: Fortify shelf position through exclusive end-cap placement negotiations with Kroger and Albertsons that lock out indie competitors unable to match trade promotion spend. Deepen backward integration into certified organic supply chains to secure margin against commodity surfactant volatility. MoCRA facility registration deadlines threaten craft producer shelf access, creating acquisition opportunities for operators with compliance bandwidth. For New Entrants and Emerging Players: Subscription fulfillment infrastructure gaps in the Northeast corridor offer white-space entry where incumbent DTC capabilities remain underdeveloped. Target Austin and Brooklyn craft manufacturing clusters for partnership-based scale without capital-intensive facility investment. Telehealth-adjacent distribution through dermatologist recommendation channels represents the most penetrable premium positioning for clinical credibility without prescription drug regulatory burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated organic specialists with USDA certification infrastructure and fair-trade supply chain relationships. Long-term viability hinges on format innovation capability—syndet bar production equipment and waterless solid formulation R&D. The signal to monitor is FDA enforcement bandwidth allocation toward small-batch facility inspections, which would accelerate distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Leaping Bunny Certification Investment | Mass retail chains now require cruelty-free documentation for shelf placement, filtering supplier access. |
| Direct-to-Consumer Subscription Launch | Shopify infrastructure enables margin capture previously lost to supermarket slotting fees and trade promotion. |
| Syndet Bar Production Capacity Addition | Synthetic detergent formats fragment manufacturing infrastructure and require distinct capital equipment from conventional lines. |
| Upcycled Ingredient Supply Agreement | Food waste stream partnerships with beverage and agriculture sectors reduce raw material cost exposure. |
| California-First Formulation Design | Proposition 65 and Safer Consumer Products regulations force national brands to design for strictest state standards. |
Research Approach
Operator-level perspectives from brand managers at diversified consumer goods conglomerates, category buyers at Target and Kroger, contract manufacturing plant managers, and supply chain directors at oleochemical suppliers anchored the qualitative base. Secondary validation drew from FDA MoCRA facility registration databases, EPA antimicrobial ingredient guidance documents, California OEHHA Proposition 65 enforcement records, and Nielsen retail audit data. Bottom-up demand modeling triangulated against top-down macroeconomic consumption indicators.
Sensitivity analysis tested forecast robustness across regulatory enforcement intensity scenarios and palm oil price volatility bands throughout the projection horizon. Segmentation dimensions modeled include product format, ingredient certification tier, end-user demographic, and distribution channel architecture. CAGRs derived from historical volume trajectories adjusted for MoCRA compliance cost absorption and subscription commerce penetration curves. Forecast inputs incorporated Leaping Bunny certification adoption rates and syndet bar production capacity expansion timelines.
Forecasts assume regulatory continuity in FDA MoCRA implementation and California Safer Consumer Products program enforcement; material policy shifts would require re-modeling. Palm oil supply disruptions from Indonesian export restrictions or Malaysian sustainability certification changes represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Natural Hair Care Product Market
Beauty & Personal Care
Cosmetics Face Serum Market
Beauty & Personal Care
North America Hair Conditioner Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Intimate Hygiene Products Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Beard Oil Market