
 Laundry Dryer Sheets and Bars Market | 2026-2036
Laundry Dryer Sheets and Bars Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Dryer Sheets and Bars Market Analytics
The split between premium fragrance-infused sheets and commodity-grade unscented bars is hardening as retailers allocate separate shelf economics to each tier. Procter and Gamble leverages its North American distribution density to dominate club-channel sheet volumes, while Henkel AG and Co KGaA anchors European market presence through concentrated bar formulations. Seventh Generation Inc specializes in biodegradable material positioning that commands placement in natural-grocery sets.
Laundry dryer sheets and bars comprise fabric-conditioning substrates—typically nonwoven polyester or cotton carriers, or molded surfactant bars—engineered to deposit softening agents and fragrances during mechanical drying cycles. Manufacturing involves impregnation of quaternary ammonium compounds or fatty acid esters onto carrier sheets, or extrusion of solid bar matrices containing cationic surfactants that activate at tumble temperatures between 50°C and 70°C. The product type dimension shows sheets maintaining mature volume dominance in mass retail, while bars capture faster growth in commercial and subscription-channel deployments where storage efficiency matters. Material segmentation reveals biodegradable substrates gaining shelf space as REACH-compliant formulations displace conventional polyester in European markets, though synthetic carriers still occupy the economy tier in price-sensitive regions.
FDA oversight of fragrance allergen labeling intersects with EPA Safer Choice criteria and EU REACH substance restrictions to elevate compliance costs for multi-region suppliers. California's Cleaning Product Right to Know Act compounds disclosure obligations, forcing reformulation of proprietary fragrance blends across North American production lines. Stakeholders must monitor pending amendments to EU CLP regulation for endocrine-disruptor classifications that could recategorize common quaternary ammonium chemistries.
Market Dynamics
EU REACH substance restrictions and parallel state-level chemical disclosure mandates in the US are fragmenting formulation standards, forcing manufacturers to maintain parallel production lines for regional compliance while biodegradable substrate R&D accelerates.
Growth Catalysts
- Commercial laundry automation:Hospitality and healthcare sectors in Germany are deploying concentrated bar formats to reduce storage footprint and handling labor in high-throughput facilities.
- REACH-compliant biodegradable substrates:ECHA substance evaluations are accelerating displacement of conventional polyester carriers with cellulose-derived alternatives in European retail channels.
- Private-label sustainability mandates:German retailers are requiring third-party environmental certifications as a condition for shelf placement, compressing conventional brand shelf space.
Market Restraints
- Quaternary ammonium compound cost volatility:Fatty acid feedstock prices fluctuate with palm oil and tallow commodity markets, squeezing margin on cationic surfactant formulations.
- Fragrance allergen disclosure friction:California's Cleaning Product Right to Know Act forces reformulation of proprietary scent blends, extending product development cycles for North American production.
- Sheet format infrastructure lock-in:Mass retail slotting fees and existing manufacturing assets create switching costs that slow bar format penetration in price-sensitive channels.
Strategic Opportunities
- Subscription-channel concentrated bars:Direct-to-consumer replenishment models are capturing storage-efficiency-conscious households in urban Germany.
- EU CLP endocrine-disruptor reclassification:Pending amendments could recategorize common chemistries, creating first-mover advantage for suppliers with pre-qualified alternative formulations.
- Healthcare linen service consolidation:Hospital and long-term care facility outsourcing is concentrating procurement volumes with contract laundry operators seeking format standardization.
Industry Challenges
- Cross-regulatory formulation complexity:Simultaneous compliance with EPA Safer Choice, FDA fragrance labeling, and REACH substance restrictions requires dedicated regulatory affairs capacity.
- Biodegradable substrate performance gaps:Cellulose carriers exhibit lower tensile strength in high-heat drying cycles, requiring equipment calibration adjustments at commercial laundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Dryer Sheets and Bars Market |
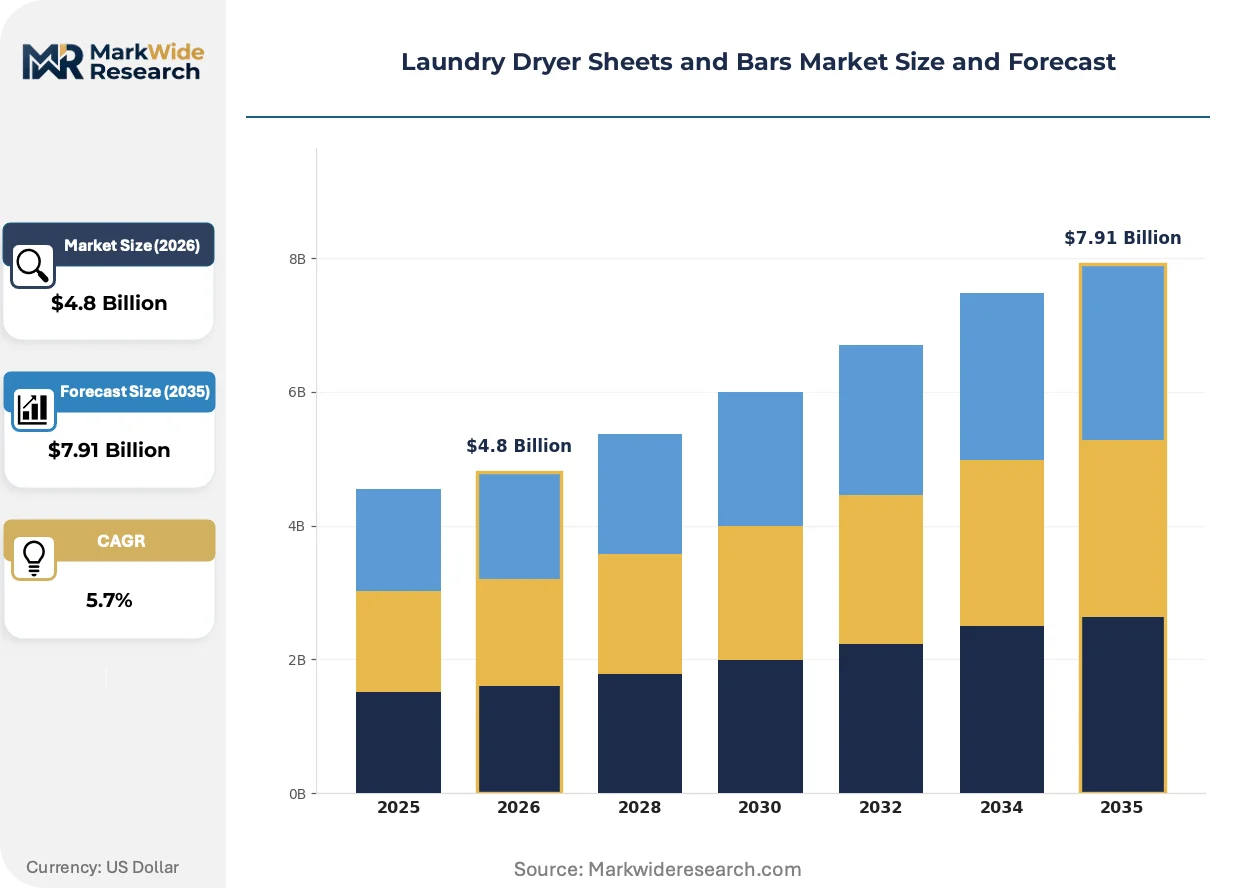
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Bars, Liquid Softener, Pods Material: Cotton, Polyester, Biodegradable, Synthetic Fragrance Type: Lavender, Citrus, Fresh Linen, Free & Clear Packaging Type: Box, Refill Bag, Pouch, Bulk |
| Companies Covered | Procter and Gamble, Unilever PLC, Henkel AG and Co KGaA, SC Johnson and Son, The Clorox Company, Church and Dwight Co Inc, Kao Corporation, Seventh Generation Inc, Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Dryer Sheets and Bars Market Evolving Landscape
Active ingredient delivery systems and carrier material science are converging with digital traceability requirements, reshaping how manufacturers demonstrate compliance and differentiate performance claims.
Solid bar extrusion technology is decentralizing production economics by enabling regional compounding facilities to serve local markets without sheet-impregnation infrastructure. Commercial laundries in Germany and the Netherlands are adopting these formats fastest, drawn by reduced shipping volumes and warehouse space requirements. This shift is compressing the historical advantage of centralized sheet manufacturing in Asia-Pacific export hubs.
EU REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing reformulation of stain-release additives commonly co-deployed with softening agents. Manufacturers serving European markets must now validate alternative chemistries through ECHA notification procedures. The natural-grocery retail channel is absorbing compliance costs fastest by absorbing price premiums for certified-clean-label products.
Subscription-based replenishment models are fragmenting traditional mass-retail procurement patterns among urban households. German consumers are shifting from supermarket stock-up purchases to scheduled bar deliveries, bypassing slotting-fee-driven shelf economics. This behavioral pivot concentrates lifetime customer value with direct-channel operators while eroding impulse-purchase volumes in hypermarket formats.
Laundry Dryer Sheets and Bars Market Segmentation
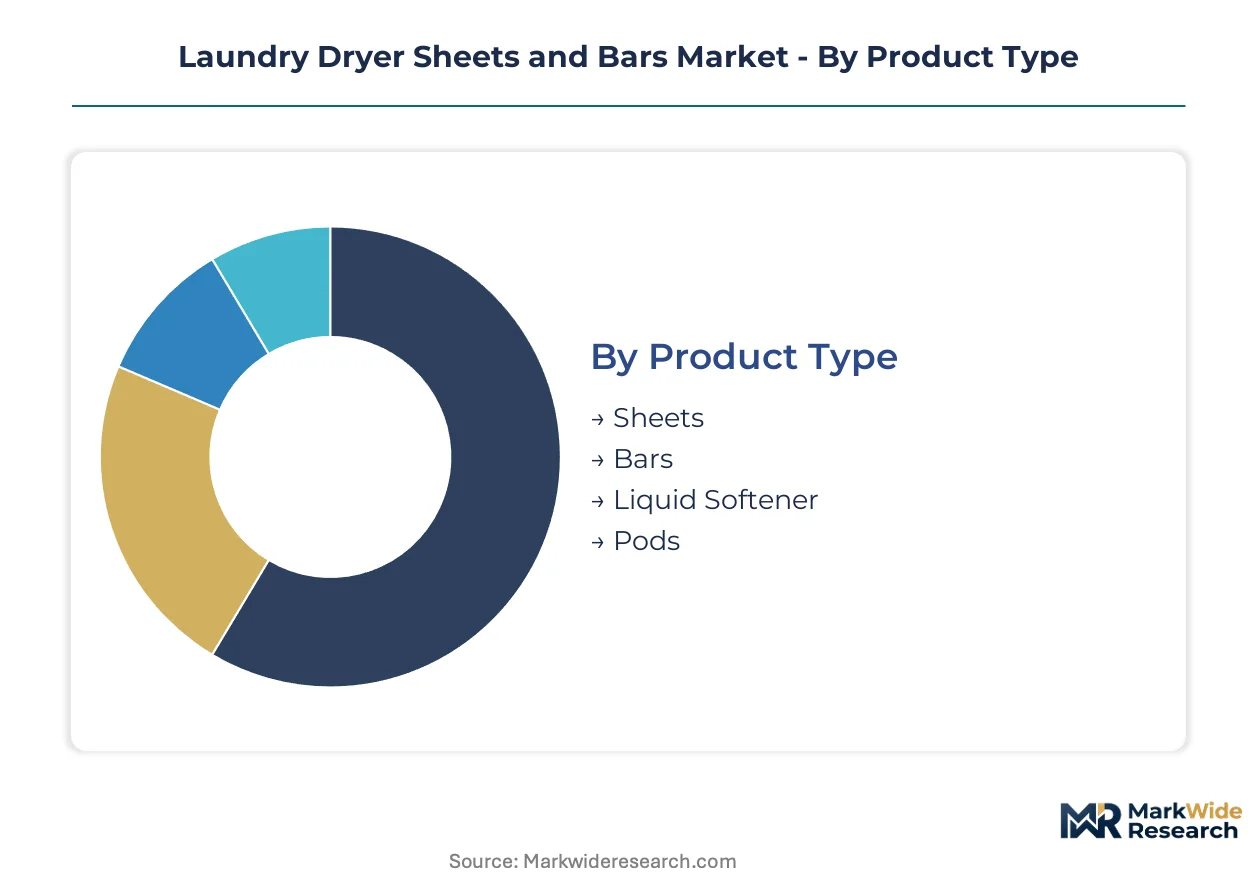
Segmentation in laundry dryer sheets and bars reveals how format preferences diverge between mass retail infrastructure and emerging direct-channel models. Material chemistry and fragrance positioning further stratify the competitive landscape across regulatory jurisdictions.
Product Type:
Standalone fabric-conditioning formats operate independently of washing machine integration, while embedded-system formats require coordinated detergent-softener deployment.
- Sheets:Nonwoven polyester or cotton carriers impregnated with quaternary ammonium compounds deposit softening agents during tumble cycles between 50°C and 70°C. Demand concentrates in US club-channel and hypermarket formats where slotting fees and existing manufacturing assets create infrastructure lock-in.
- Bars:Molded surfactant matrices containing cationic softening agents activate at drying temperatures without carrier substrates. German commercial laundries and urban subscription households are adopting concentrated bar formats fastest, drawn by warehouse space compression and handling labor reduction.
- Liquid Softener:Pourable cationic surfactant emulsions requiring washing machine dispenser integration.
- Pods:Single-dose encapsulated softening agents designed for coordinated release with detergent pods.
Volume placements concentrate in Sheets; the faster expansion belongs to Bars.
Material:
Cost tier stratification separates premium biodegradable substrates from economy synthetic carriers, with regulatory pressure compressing mid-tier positioning.
- Polyester:Petroleum-derived nonwoven carriers dominate mass retail economics through tensile strength and heat resistance in commercial drying cycles. German retailers are compressing conventional polyester shelf space through private-label sustainability mandates requiring third-party environmental certifications.
- Biodegradable:Cellulose-derived substrates from wood pulp or agricultural waste displace synthetic carriers under EU REACH substance evaluations. ECHA notification procedures for alternative chemistries are accelerating placement in European natural-grocery channels despite performance gaps in high-heat drying cycles.
- Cotton:Natural fiber carriers with higher absorbency for fragrance retention.
- Synthetic:Blended petroleum-based substrates occupying price-sensitive economy tiers.
Polyester still commands the largest installed base; Biodegradable substrates are climbing the fastest.
Fragrance Type:
Application context drives fragrance selection, with healthcare and sensitive-skin segments demanding allergen-free positioning.
- Fresh Linen:Clean cotton-inspired scent profiles dominate mass-market household penetration through association with laundry freshness.
- Free & Clear:Unscented formulations without added fragrance molecules target healthcare linen services and sensitive-skin consumers. California's Cleaning Product Right to Know Act forces reformulation of proprietary scent blends, extending development cycles for fragranced variants.
- Lavender:Herbal aromatherapy positioning in premium natural-grocery sets.
- Citrus:Energizing scent profiles targeting younger demographic segments.
Fresh Linen maintains the broadest household penetration; Free & Clear is gaining share fastest in institutional procurement.
Packaging Type:
Customer type segmentation separates stock-up retail purchasers from replenishment-focused subscription households.
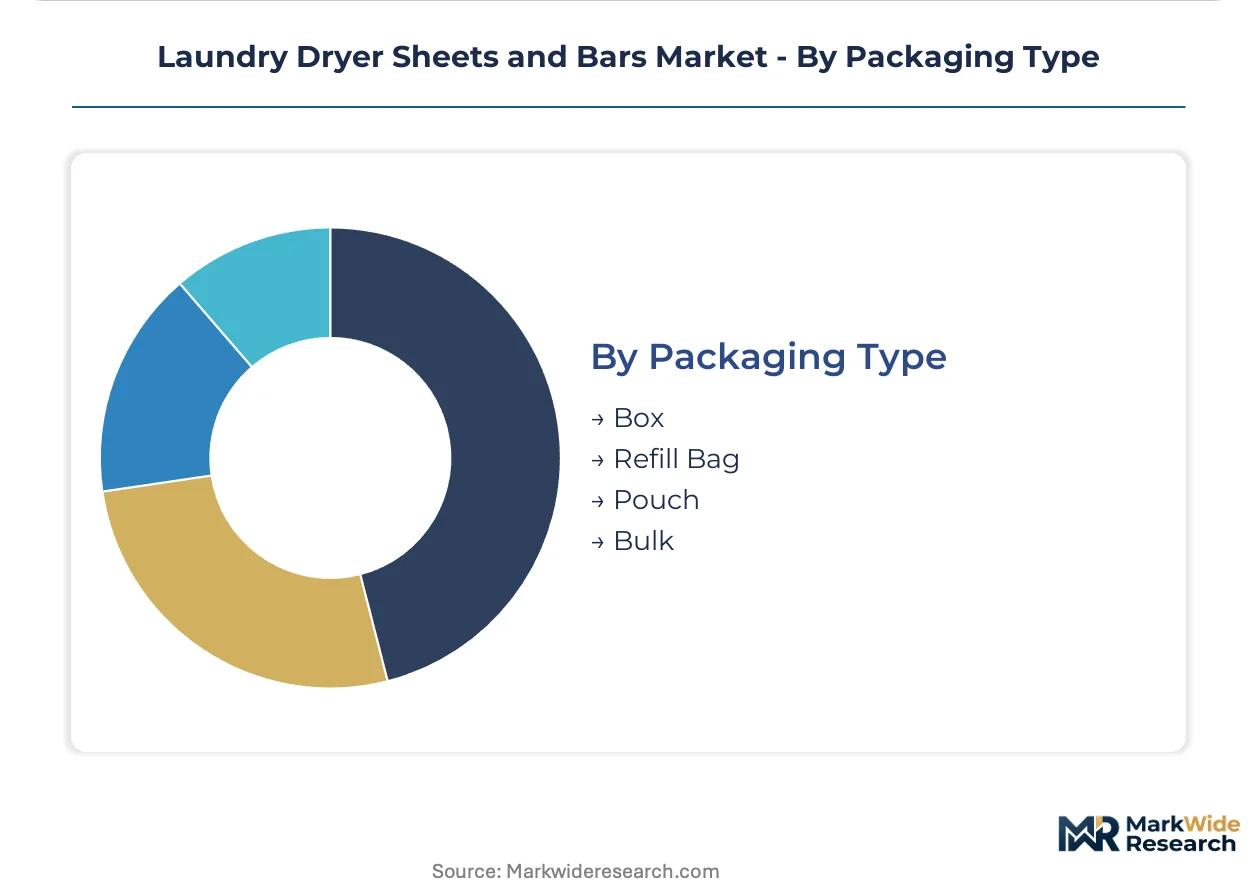
- Box:Rigid paperboard containers with resealable lids dominate traditional retail shelf placement. German consumers are shifting from supermarket stock-up purchases to scheduled deliveries, eroding impulse-purchase volumes in hypermarket formats.
- Refill Bag:Flexible pouches designed for decanting into permanent containers reduce shipping weight and packaging waste. Urban subscription households in the Netherlands and Germany favor refill formats for storage efficiency in smaller living spaces.
- Pouch:Single-use or small-count flexible packaging for trial and travel segments.
- Bulk:Industrial-scale containers for commercial laundry operators and contract linen services.
Box formats retain the highest retail visibility; Refill Bag configurations are expanding most quickly in direct-channel deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European formulation development for concentrated bar technologies, while Cincinnati and Rotterdam drive sheet-format manufacturing scale for club-channel and commercial laundry distribution respectively.
United States
Club-channel procurement concentrates sheet volumes in the Midwest and Southeast corridors. California's Cleaning Product Right to Know Act forces fragrance reformulation across North American production lines. Cincinnati-based manufacturing clusters serve mass retail slotting-fee economics while West Coast facilities adapt to chemical disclosure mandates.
Germany
Commercial laundries in Bavaria and North Rhine-Westphalia deploy concentrated bars to compress warehouse footprints. ECHA substance evaluations under REACH accelerate displacement of polyester carriers with cellulose alternatives. Berlin-Brandenburg retail corridors enforce private-label sustainability certifications as shelf-placement conditions.
Netherlands
Rotterdam port logistics enable bar-format import distribution across Northwestern Europe. EU Green Deal procurement criteria shape institutional purchasing at healthcare linen services. Randstad urban households shift from hypermarket stock-up to subscription-based replenishment models.
China
Yangtze River Delta manufacturing bases supply synthetic carrier substrates for price-sensitive export markets. SAMR chemical registration requirements complicate fragrance additive imports. Pearl River Delta clusters specialize in polyester nonwoven production for economy-tier sheet formats.
United Kingdom
London-Southeast retail corridors fragment between premium natural-grocery positioning and commodity supermarket tiers. UK REACH alignment post-Brexit maintains substance restriction continuity with EU frameworks. Midlands distribution hubs handle bar-format logistics for healthcare sector procurement consolidation.
Laundry Dryer Sheets and Bars Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fragrance positioning and substrate certification tiers. The market structure consolidates around multinational consumer goods conglomerates with dedicated home care divisions alongside specialty natural-channel operators. Three archetypes dominate: mass-market volume leaders leveraging distribution density, European formulation specialists driving bar-format innovation, and clean-label independents capturing natural-grocery shelf space. Competitive moves concentrate on M&A for regional brand portfolios and capacity expansion in biodegradable substrate manufacturing.
Among Cincinnati-based conglomerates, Procter and Gamble exemplifies mass-market volume leadership through club-channel infrastructure control. Henkel AG and Co KGaA anchors European bar-format specialization from its Düsseldorf headquarters, representing concentrated surfactant matrix innovation. Seventh Generation Inc occupies the clean-label archetype, commanding placement in certified-sustainability retail sets without synthetic carrier positioning.
| Leading Market Players |
|---|
| Procter and Gamble |
| Unilever PLC |
| Henkel AG and Co KGaA |
| SC Johnson and Son |
| The Clorox Company |
| Church and Dwight Co Inc |
| Kao Corporation |
| Seventh Generation Inc |
| Colgate-Palmolive Company |
| Others |
Value Network & Pricing Analysis
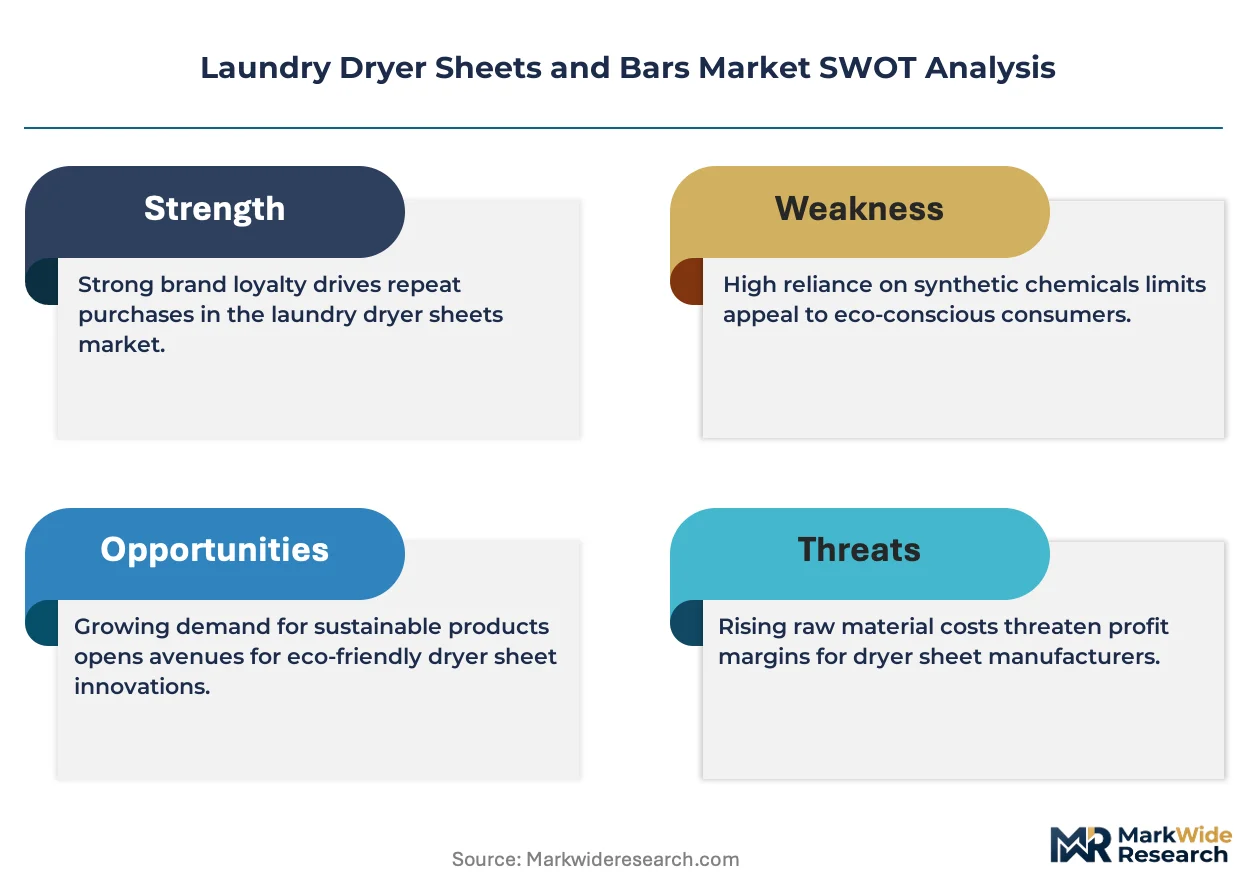
Palm oil futures volatility cascades through cationic surfactant production costs, compressing margins on quaternary ammonium compound formulations while forcing tiered pricing adjustments across biodegradable and synthetic carrier segments.
Pricing Analysis
Load-per-cycle throughput anchors value-based pricing for commercial laundry operators, with bar formats commanding premium positioning against sheet alternatives due to warehouse space savings and handling labor reduction. Three-tier pricing structure across premium fragrance-infused, standard fresh-linen, and economy unscented tiers separates certification-grade biodegradable substrates from conventional polyester carriers. Pricing pressure stems from fatty acid feedstock commodity swings, squeezing margin on cationic surfactant formulations. Healthcare linen services exhibit lowest price sensitivity due to procurement consolidation, while mass retail households show highest elasticity to per-unit cost shifts.
Supply Chain Analysis
Ocean freight rate fluctuations from Rotterdam and Shanghai ports reshape landed cost economics for bar-format imports versus regional sheet manufacturing. Yangtze River Delta clusters supply polyester nonwoven substrates, while German compounding facilities source cellulose-derived alternatives from Nordic pulp processors. Raw material dependencies center on palm oil and tallow for cationic surfactants, petroleum derivatives for synthetic carriers, and wood pulp for biodegradable substrates. Single-source vulnerability concentrates in quaternary ammonium compound precursors. Distribution runs through club-channel warehousing for US mass retail, direct-to-consumer fulfillment for German subscription households, and institutional procurement hubs for healthcare linen services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable substrate manufacturing capacity constraints prop pricing premiums for REACH-compliant formulations, sustaining margin pools for early certification holders.
For Market Incumbents: Hedge against ECHA endocrine-disruptor reclassifications by accelerating alternative quaternary ammonium compound qualification through parallel formulation pipelines. Secure backward integration into cellulose substrate production to defend margin position against Nordic pulp supply bottlenecks. Channel control through club-channel slotting fee retention remains critical as subscription models erode impulse-purchase volumes. For New Entrants and Emerging Players: Enter via direct-to-consumer subscription channels in urban German markets, where storage-efficiency-conscious households bypass hypermarket slotting economics. Target healthcare linen service consolidation as the most penetrable institutional segment, with concentrated bar formats addressing procurement standardization needs. Position through third-party environmental certification as mandatory shelf-placement currency in Berlin-Brandenburg retail corridors. For Investors and Strategic Acquirers: Distressed-cycle entries favor biodegradable substrate specialists with pre-qualified REACH alternative formulations in European manufacturing geographies. Long-term viability hinges on regulatory compliance moats widening over the analysis window as CLP amendments recategorize common chemistries. Watch ECHA notification approval velocity as inflection indicator for first-mover formulation advantages converting to pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Substrate Scale-Up | Cellulose carrier manufacturing expansion secures REACH-compliant supply for German retail mandates. |
| Alternative Surfactant Qualification | ECHA pre-notification of non-quaternary ammonium chemistries builds regulatory optionality ahead of CLP amendments. |
| Direct-to-Consumer Channel Launch | Subscription replenishment models capture lifetime value from urban households shifting from hypermarket stock-up. |
| Healthcare Linen Service Partnership | Contract laundry consolidation concentrates procurement volumes with format-standardized bar suppliers. |
| Third-Party Certification Investment | Environmental label acquisition unlocks shelf placement under German private-label sustainability mandates. |
Research Methodology
Document review covered customs trade records, ECHA substance registration databases, and SEC home care division filings, complemented by interviews with commercial laundry procurement directors, biodegradable substrate plant managers, and natural-grocery category buyers. Primary fieldwork with subscription-channel operators and healthcare linen service executives validated secondary data on format adoption patterns. Bottom-up volume modeling across product type, material chemistry, and fragrance positioning segments triangulated against top-down macroeconomic drivers.
Segment-level demand projections across the analysis window incorporated load-factor assumptions for commercial laundry automation, REACH compliance cost pass-through elasticity, and subscription-channel household penetration curves. CAGRs derived from regression of historical volume trajectories against regulatory announcement timelines and raw material price indices. Modeled inputs included fatty acid feedstock commodity benchmarks and club-channel slotting fee structures.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU CLP endocrine-disruptor reclassification or palm oil supply disruption scenarios. Forecasts reflect assumptions on commercial laundry outsourcing velocity and biodegradable substrate performance gap closure timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Smart Fridge Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Gel Warmers Market
Household Items
Air Freshener Market
Household Items
Infuser Water Bottles Market
Household Items
Handheld Fans Market
Household Items
India Non-Stick Cookware Market
Household Items
Industrial Floor Mats Market
Household Items
Electric Soap Dispenser Market
Household Items
Global Paper Towels Market
Household Items
Turkey Cookware Market
Household Items
Insulated Water Bottles Market
Household Items
Fan Market
Household Items
Robotic Vacuum Cleaner Market
Household Items
Toilet Hygiene Products Market
Household Items
Oman Gas Hobs Market