

Rice Shampoo Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Rice Shampoo Bar Market Insights
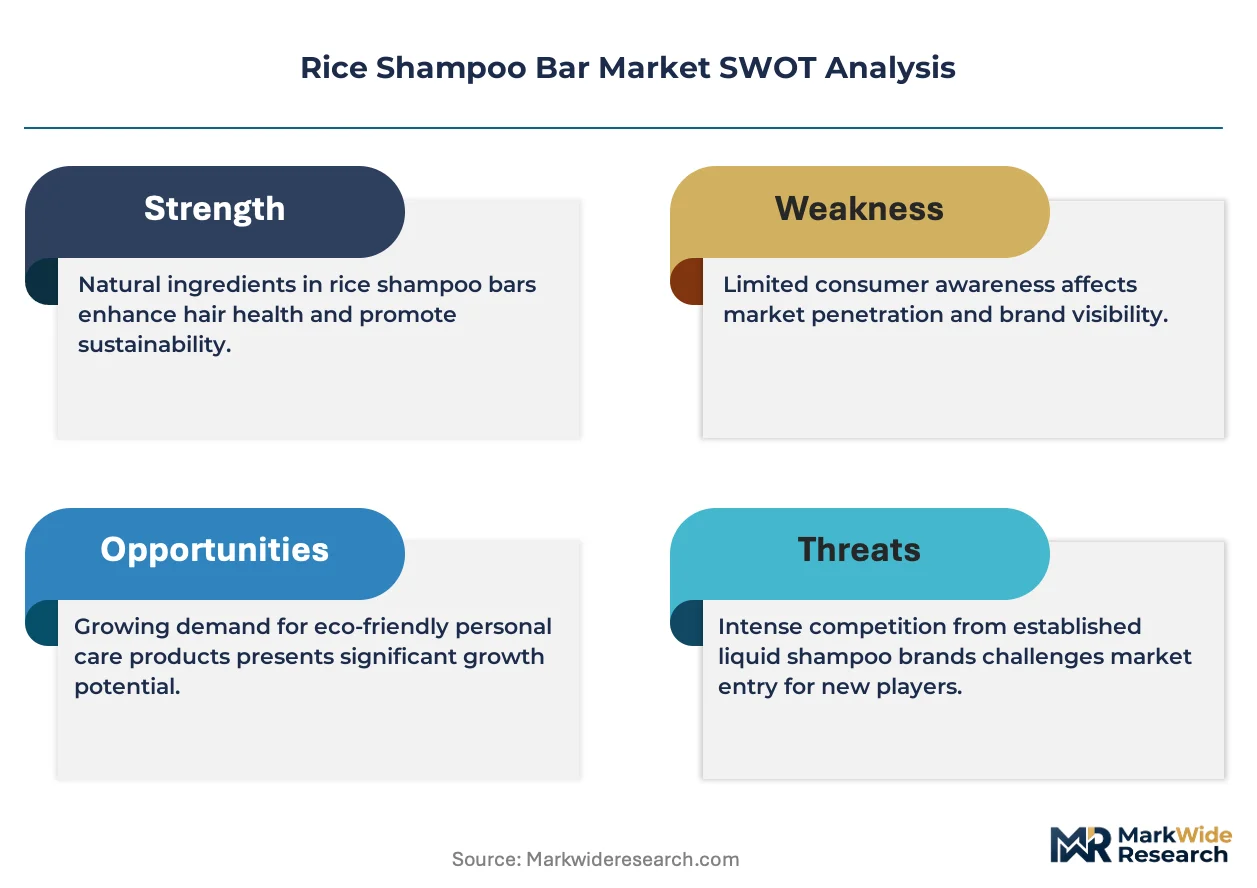
Formulation chemists trained in cold-process saponification without synthetic surfactants is redrawing competitive boundaries in the rice shampoo bar sector. Lush Fresh Handmade Cosmetics leverages its vertically integrated manufacturing to sustain consistent output across multiple continents. Ethique anchors its position through concentrated bar formats that eliminate water content entirely. JR Liggett's competes through heritage positioning and minimal-ingredient recipes that appeal to purist consumers.
A rice shampoo bar is a solid cleansing formulation where rice protein, rice bran oil, or fermented rice water serves as the functional active, typically manufactured through cold-process saponification or melt-and-pour techniques with pH levels between 4.5 and 6.5 to maintain cuticle integrity. The product delivers cleansing and conditioning without plastic packaging, targeting consumers eliminating liquid personal care products. Moisturizing and repair variants occupy the deepest margin pools due to premium ingredient positioning and repeat purchase loyalty. Volumizing formulations lead volume growth among fine-haired consumers seeking silicone alternatives. E-commerce platforms and specialty retailers dominate customer-type distribution, while direct sales channels capture the highest per-unit economics through subscription models.
FDA cosmetic labeling requirements and the EU REACH framework govern ingredient disclosure and safety substantiation, with ISO 16128 natural origin standards increasingly shaping formulation claims and market access conditions. The EU Green Deal's packaging waste directives and emerging state-level plastic reduction mandates in California and New York are accelerating bar-format adoption. Stakeholders must monitor evolving biodegradability certification requirements and surfactant restriction proposals across multiple jurisdictions to anticipate reformulation costs and compliance timelines.
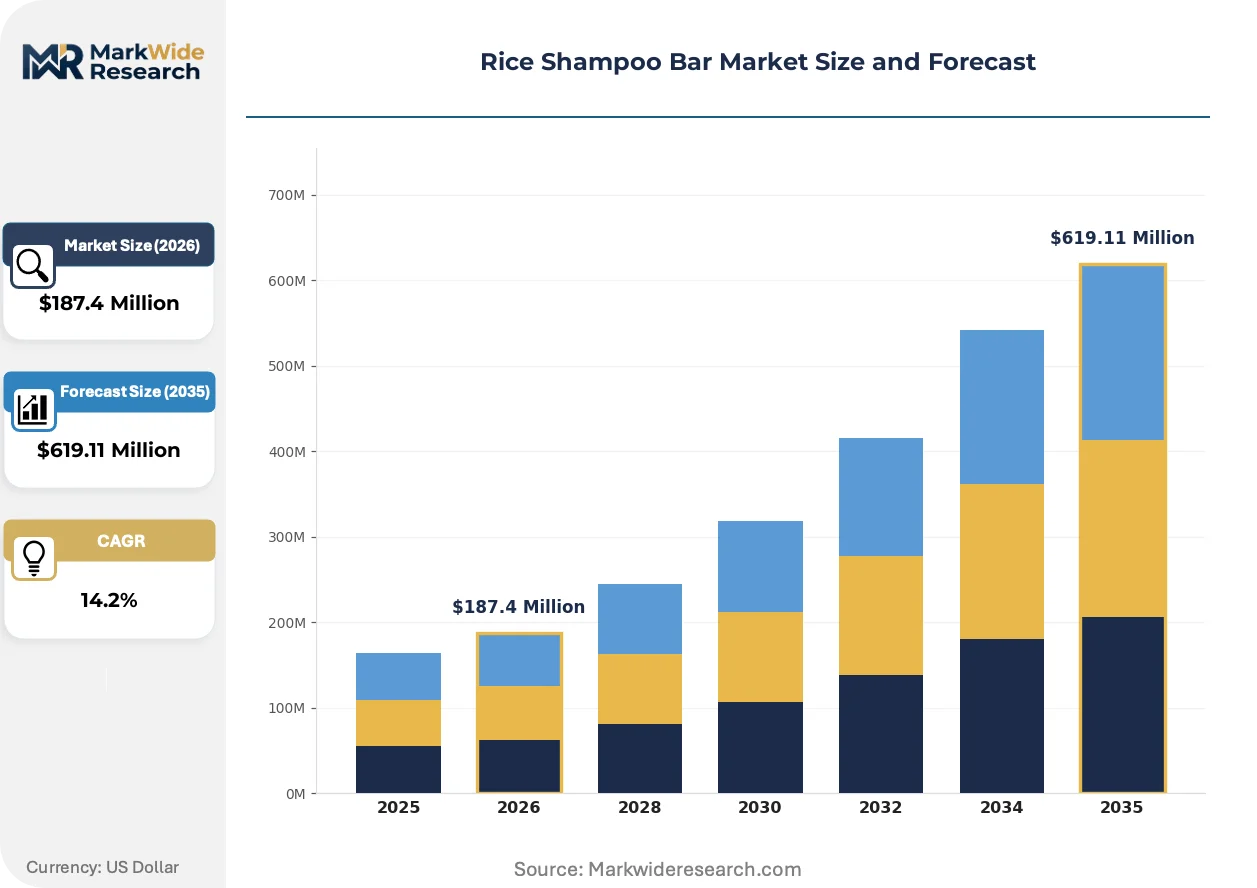
Market Dynamics
Zero-waste personal care mandates across multiple jurisdictions are compressing formulation timelines and forcing manufacturers to secure cold-process saponification expertise ahead of capacity expansion. This regulatory pull is redrawing competitive boundaries between established personal care conglomerates and specialized bar-format producers.
Growth Catalysts
- EU Green Deal packaging directives:Binding reduction targets for single-use plastics in France, Germany, and Italy are mandating bar-format alternatives across mass retail channels by 2025.
- Fermented rice water concentration:Advanced enzymatic processing yields higher amino acid retention than traditional extraction, improving conditioning performance in hard water regions.
- Millennial and Gen Z cohorts:Cohort-specific plastic-free pledges on social platforms are converting trial into subscription-based repeat purchase at rates exceeding legacy liquid shampoo.
Market Restraints
- Cold-process chemist scarcity:United States, Germany, and Japan each face acute shortages of formulation specialists trained in surfactant-free saponification, capping output expansion.
- Rice bran oil price volatility:Weather-driven harvest fluctuations in Thailand and Vietnam transmit directly to input cost instability for moisturizing variant producers.
- ISO 16128 substantiation costs:Third-party natural origin certification requires six-to-twelve-month documentation cycles that delay new product launches.
Strategic Opportunities
- Direct-to-consumer subscription channels:Recurring revenue models bypass specialty retailer margin stacking and capture full per-unit economics.
- Men's grooming vertical:Underpenetrated male consumer segment shows elevated trial rates for simplified, single-bar cleansing routines versus multi-step liquid regimens.
- California and New York state mandates:Emerging plastic reduction legislation creates first-mover advantage for bar-format brands establishing shelf presence ahead of compliance deadlines.
Industry Challenges
- pH stability maintenance:Cold-process saponification without synthetic buffers requires precise lye concentration control to achieve 4.5-6.5 cuticle-safe ranges consistently at scale.
- Biodegradability certification timelines:OECD 301B testing protocols for aquatic toxicity claims extend go-to-market schedules by four to six months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rice Shampoo Bar Market Trends and Innovations
Formulation science is diverging between heritage cold-process methods and precision-controlled enzymatic systems, with each path attracting distinct capital commitments and talent pools. This technological fork is fragmenting R&D investment patterns across the competitive landscape.
Enzymatic rice protein hydrolysis is bifurcating the ingredient supply tier. High-molecular-weight fractions deliver film-forming conditioning for damaged hair segments, while low-weight peptides penetrate for volumizing claims. Specialty chemical suppliers in South Korea and Japan are scaling enzymatic capacity threefold, compressing traditional solvent-extraction margins and forcing legacy processors to defend position through certified organic positioning rather than cost.
REACH authorization requirements for surfactant precursors are tightening disclosure obligations for imported cosmetic ingredients entering the European Economic Area. ECHA's expanded Substance of Very High Concern candidate list now captures several ethoxylated compounds common in liquid shampoo, elevating bar-format alternatives that bypass these chemistries entirely. German and Dutch formulators are accelerating reformulation timelines to maintain market access.
Subscription-based replenishment is displacing intermittent specialty retail purchase among core demographic cohorts. Direct channels capture purchase data that enables personalized variant matching, while retailers respond with exclusive bar-format SKUs and refill station pilots. This channel tension is most visible in United States coastal metros and London, where zero-waste shop density supports experimentation before mass-market scaling.
Rice Shampoo Bar Market Segmentation
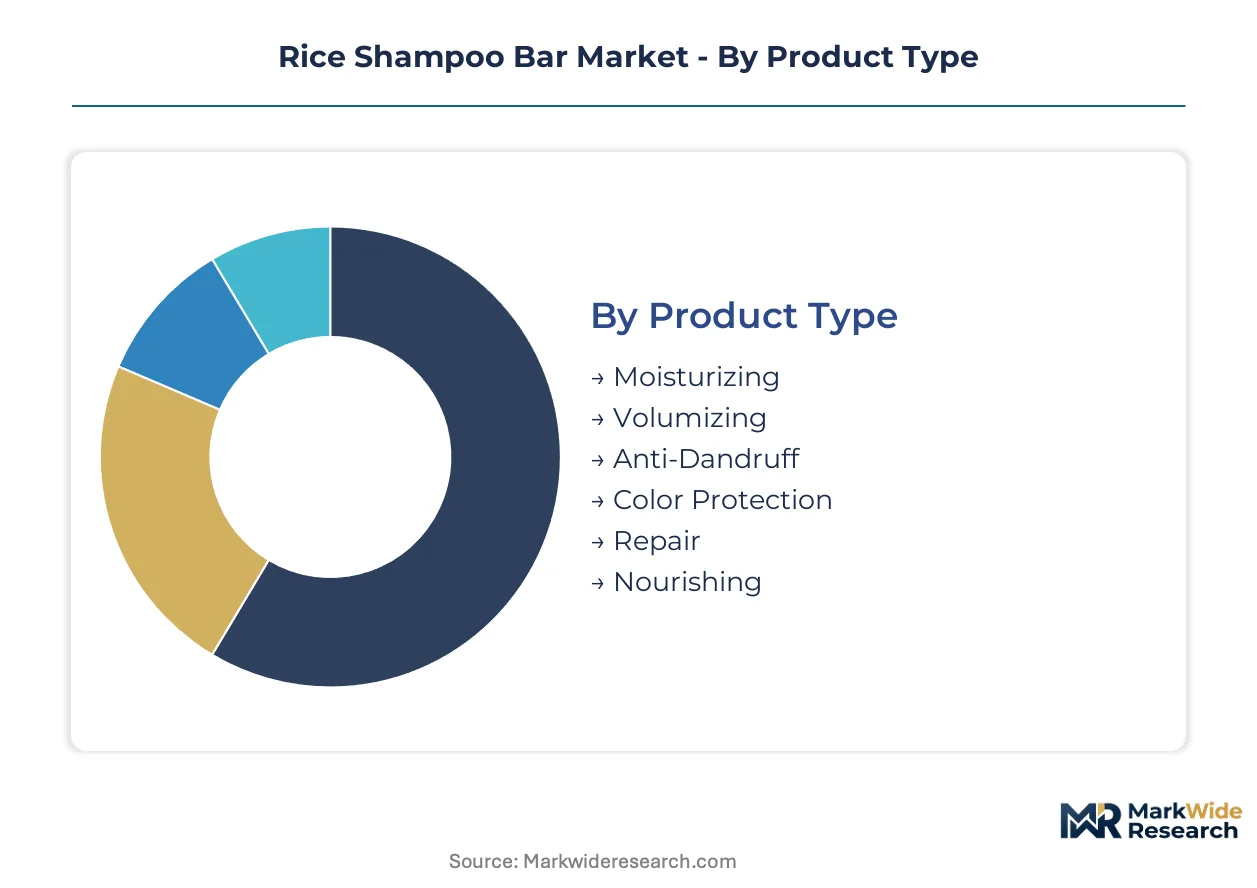
Rice shampoo bar manufacturers navigate distinct substitution pressures across product formulations, application contexts, and channel configurations. Segment-level positioning determines vulnerability to liquid shampoo alternatives, solid bar competitors, and private-label entrants.
Product Type:
Substitution pressure from silicone-based liquid conditioners and bond-repair treatments is reshaping formulation investment priorities across functional variants.
- Moisturizing:Rice bran oil and ceramide-rich formulations target chemically treated and heat-damaged hair segments. Demand concentrates among consumers in California and New York seeking silicone alternatives under tightening state plastic reduction mandates.
- Repair:Hydrolyzed rice protein and amino acid complexes address structural damage from bleaching and thermal styling. Salon professionals in Germany and France prescribe these bars for post-coloring protocols, driving repeat purchase loyalty above other functional categories.
- Volumizing:Lightweight rice starch bases absorb excess sebum without residue buildup.
- Anti-Dandruff:Fermented rice water with piroctone olamine addresses fungal scalp conditions.
- Color Protection:UV-filtering rice bran extracts preserve artificial pigment deposits.
- Nourishing:Vitamin E-enriched rice germ oil formulations target aging hair demographics.
Moisturizing variants anchor the volume base while Repair formulations gain share at the steepest rate.
Application:
Cost tier stratification separates premium positioning for complex scalp conditions from mass-market daily cleansing applications.
- Dry Hair Care:High-lipid rice bran oil bars with occlusive film-forming properties restore barrier function in low-humidity climates. Consumers in Japan and South Korea purchase these at premium price points through pharmacy channels.
- Sensitive Scalp Treatment:Fragrance-free, pH-buffered formulations with minimal ingredient lists reduce contact dermatitis incidence. Pediatric and post-chemotherapy segments in the United States drive prescription-adjacent distribution through dermatology clinics.
- Oily Hair Care:Rice starch absorbent bases with astringent botanicals regulate sebum production.
- Curly Hair Management:Protein-balanced bars maintain curl pattern definition without stiffness.
- Daily Use:Mild surfactant-free bases suit frequent washing routines.
- Natural Hair Care:Uncolored, unprocessed hair maintenance with minimal intervention.
Daily Use commands the broadest addressable base while Sensitive Scalp Treatment expands most quickly among clinical-adjacent channels.
Customer Type:
Volume concentration in digital-native channels is forcing traditional service providers to develop exclusive bar-format protocols or cede trial conversion.
- E-commerce Platforms:Subscription models capture longitudinal purchase data enabling algorithmic variant matching. Direct-to-consumer brands bypass retailer margin stacking while building cohort-specific retention programs.
- Specialty Retailers:Curated assortments with in-store testing stations convert skeptical liquid shampoo users through sensory trial.
- Salons:Professional-only SKUs with concentrated active loads support service upselling.
- Spas:Ritual-integrated applications in wellness treatment protocols.
- Beauty Salons:Stylist recommendation drives post-appointment retail attachment.
- Wellness Centers:Holistic positioning aligns with Ayurvedic and traditional medicine frameworks.
E-commerce Platforms anchor the volume base while Specialty Retailers gain share at the steepest rate through experiential conversion tactics.
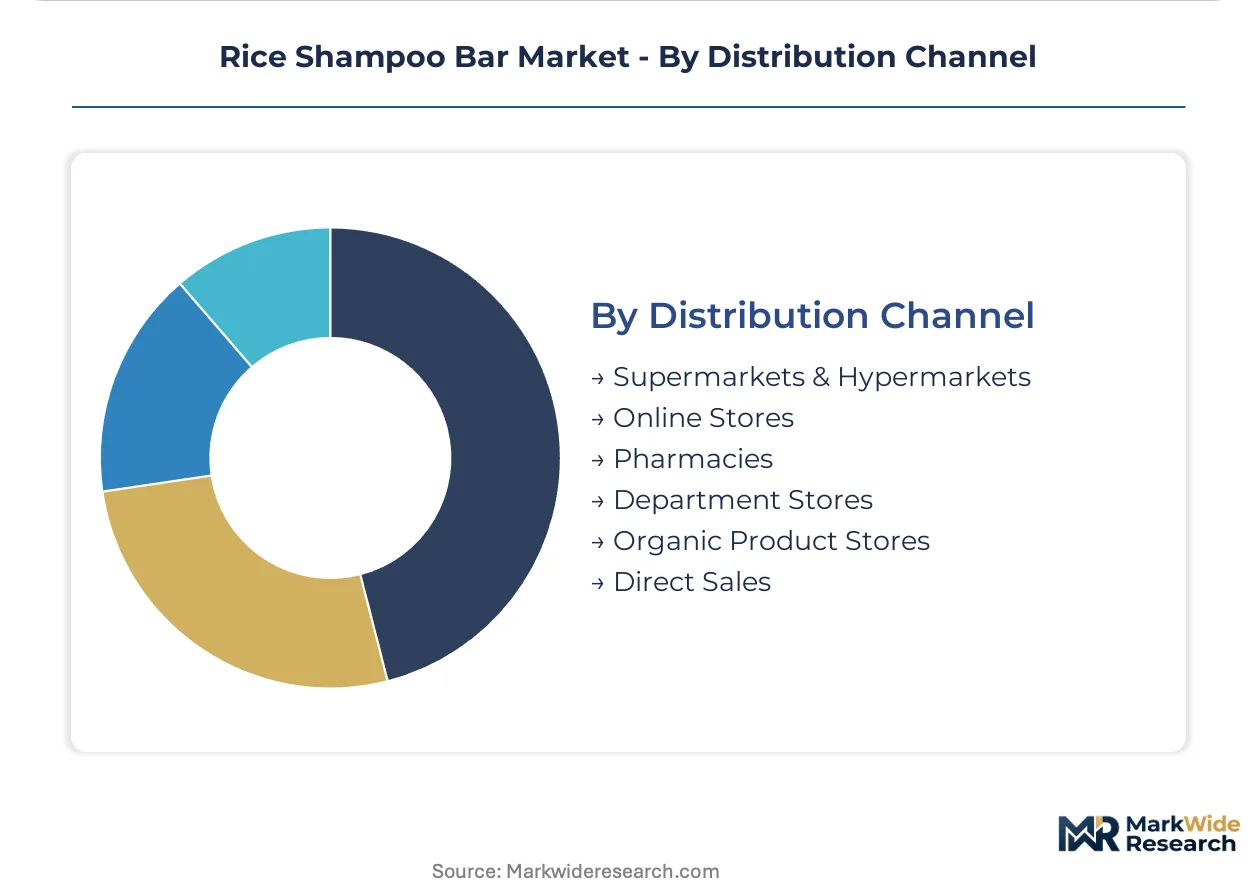
Distribution Channel:
Margin tier separation between mass retail and direct channels is fragmenting pricing architecture and promotional investment.
- Online Stores:Aggregator platforms and brand-owned sites capture subscription renewals with lowest customer acquisition costs. Inventory flexibility enables rapid variant testing without shelf-space constraints.
- Direct Sales:Consultant networks and brand ambassadors deliver personalized scalp assessments with highest per-unit economics. Social commerce integration in South Korea and China accelerates peer-to-peer conversion.
- Supermarkets & Hypermarkets:Mass-market penetration requires price compression and simplified packaging.
- Pharmacies:Clinical credibility positioning supports premium pricing for therapeutic claims.
- Department Stores:Prestige beauty counters with gift-with-purchase programs.
- Organic Product Stores:Certification-driven assortments targeting ingredient-conscious purists.
Online Stores anchor the volume base while Direct Sales gains share at the steepest rate through relationship-based retention.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cosmetic labeling requirements in the United States anchor the regulatory framework shaping formulation standards across major demand centers. National regulators in Germany, France, Japan, and South Korea each impose distinct compliance burdens on cold-process saponification methods and natural-origin certification claims.
United States
California and New York state-level plastic reduction mandates are accelerating bar-format shelf presence ahead of 2025 compliance deadlines. FDA ingredient disclosure rules require six-month substantiation cycles for therapeutic scalp claims. Brooklyn and Los Angeles host the densest zero-waste retail experimentation, with subscription brands testing direct-to-consumer retention algorithms.
Germany
ECHA REACH authorization requirements for surfactant precursors are elevating bar-format alternatives that bypass ethoxylated chemistries entirely. EU Green Deal packaging directives mandate binding single-use plastic reduction targets across mass retail channels by 2025. Cologne and Hamburg concentrate enzymatic rice protein processing capacity, with specialty chemical suppliers scaling threefold.
France
ANSM cosmetic safety assessments enforce stricter pH stability documentation for cuticle-safe formulations targeting professional salon channels. The country's national pharmaceutical regulator maintains accelerated review pathways for dermatology-adjacent scalp treatments. Paris anchors prestige beauty counter distribution, while Lyon clusters artisanal cold-process manufacturing heritage.
Japan
METI sustainability guidelines promote plastic-free personal care adoption through consumer education subsidies and retail certification programs. The national standards body enforces JIS-compliant natural origin labeling that exceeds ISO 16128 thresholds. Osaka and Tokyo concentrate fermented rice water extraction expertise, with enzymatic hydrolysis yields surpassing traditional methods.
South Korea
MFDS cosmetic ingredient disclosure rules mandate granular rice protein fraction reporting for film-forming and penetration claims. The country's national pharmaceutical regulator requires OECD 301B biodegradability certification for aquatic toxicity marketing. Seoul anchors social commerce integration, with peer-to-peer conversion rates exceeding specialty retail attachment.
Rice Shampoo Bar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the rice shampoo bar sector. Vertically integrated manufacturers with captive saponification expertise command consistent multi-continental output, while concentrated bar-format specialists eliminate water content entirely to compress logistics costs. Three archetypes dominate: heritage cold-process artisans, precision enzymatic processors, and direct-to-consumer subscription operators. Competitive moves center on backward integration into rice protein supply and exclusive retail SKU development for pharmacy and salon channels.
Within the heritage artisan tier, JR Liggett's and Chagrin Valley Soap & Salve occupy positions defined by minimal-ingredient recipes and regional manufacturing heritage. Lush Fresh Handmade Cosmetics anchors the vertically integrated archetype through in-house production of cold-process bases across multiple continents. Ethique exemplifies the concentrated-format specialist model with water-free bars that bypass liquid shampoo logistics entirely. Friendly Soap and Beauty and the Bees sit within the mid-scale natural positioning tier, while Little Seed Farm and Basin White represent farm-to-bar provenance claims targeting ingredient-conscious purists.
| Leading Market Players |
|---|
| Lush Fresh Handmade Cosmetics |
| Ethique |
| JR Liggett's |
| Chagrin Valley Soap & Salve |
| Friendly Soap |
| Basin White |
| Beauty and the Bees |
| Little Seed Farm |
| Plaine Products |
| Others |
Pricing and Supply Chain Analysis
Enzymatic rice protein hydrolysis displacing traditional solvent extraction is redrawing supply geography toward South Korea and Japan while compressing legacy processor margins through certified organic positioning rather than cost leadership. This input substitution simultaneously elevates formulation premiums for high-molecular-weight conditioning fractions and destabilizes pricing power among Thai and Vietnamese rice bran oil suppliers facing weather-driven harvest volatility.
Pricing Analysis
Geographic price spreads widen significantly between enzymatic-processed premium tiers in Germany and Japan versus commodity cold-process variants in mass North American retail. Three-tier pricing structure across premium, standard, and economy levels differentiates by ISO 16128 certification grade and volume subscription commitment. Pricing pressure stems from cold-process chemist scarcity capping output expansion in the United States and Germany. E-commerce subscription buyers show lowest price sensitivity while supermarket mass-market segments drive hardest bargain.
Supply Chain Analysis
Strategic stockpiling of rice bran oil dominates manufacturer inventory strategy given Thai and Vietnamese harvest volatility, contrasting with just-in-time enzymatic protein sourcing from South Korean specialty chemical suppliers. Supply concentrates in Thailand and Vietnam for raw rice bran oil, South Korea and Japan for enzymatic processing capacity, and Germany for REACH-compliant formulation expertise. Raw material dependencies include rice bran oil, hydrolyzed rice protein fractions, and pH-buffering botanical extracts. Single-source vulnerability runs through Thai rice bran oil processors exposed to monsoon disruption. Distribution runs through direct-to-consumer subscription channels and specialty retail with experiential conversion stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription platform economics is concentrating buyer data and retention algorithms into defensible moats, with interoperability between personalized variant matching and replenishment timing emerging as the critical ecosystem battleground for rice shampoo bar adoption.
For Market Incumbents: Shield formulation expertise through captive cold-process saponification training programs in Germany and Japan, countering chemist scarcity that threatens output expansion. Deepen backward integration into enzymatic rice protein supply from South Korean processors to defend margin position against specialty chemical supplier price power. Prioritize ISO 16128 certification investment ahead of EU Green Deal packaging mandate deadlines.
For New Entrants and Emerging Players: Anchor in men's grooming verticals where simplified single-bar cleansing routines show elevated trial rates versus multi-step liquid regimens. Target California and New York state mandates creating first-mover shelf presence ahead of plastic reduction compliance deadlines. Pursue direct-to-consumer subscription launch with algorithmic variant matching built on purchase data capture.
For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive saponification expertise spanning multiple continents, offering consistent output capacity amid chemist scarcity. Long-term viability hinges on backward integration depth into rice protein supply and exclusive pharmacy or salon channel SKU development. Watch for ECHA REACH surfactant precursor authorization tightening as inflection signal elevating bar-format alternatives.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rice Protein Supply | Captive enzymatic processing capacity in South Korea insulates against specialty chemical supplier margin compression. |
| Direct-to-Consumer Subscription Launch | Algorithmic variant matching using longitudinal purchase data builds retention moats unavailable to retail-dependent competitors. |
| ISO 16128 Certification Investment | Natural origin substantiation opens EU pharmacy channels where ANSM enforces stricter pH stability documentation. |
| Men's Grooming Vertical Expansion | Simplified single-bar protocols convert trial at rates exceeding multi-step liquid regimens in underpenetrated male segments. |
| Cold-Process Saponification Training Programs | In-house chemist development counters acute formulation specialist shortages capping output expansion in Germany and Japan. |
Research Methodology
The analysis maps moisturizing, repair, and volumizing formulation tiers, each validated through formulation chemists, specialty retail category buyers, e-commerce subscription operations heads, and salon professional channels. Primary interviews with cold-process saponification specialists and enzymatic processing engineers combined with secondary validation from ECHA REACH filings, FDA cosmetic labeling databases, ISO 16128 certification records, and EU Green Deal packaging directive documentation. Bottom-up variant-level demand modeling and top-down channel revenue triangulation anchored volume and value outputs.
Consistency checks against external benchmarks validated projection outputs across the analysis window, with segmentation dimensions spanning functional variant, application context, customer type, and distribution channel. CAGRs derived from cohort-specific adoption curves for millennial and Gen Z plastic-free pledges, layered against regulatory mandate acceleration timelines. Industry-specific forecast inputs include enzymatic rice protein hydrolysis capacity expansion rates and cold-process chemist graduation pipeline data from German and Japanese technical institutes.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and millennial cohort retention stability; material deviation in either would warrant model refresh. Forecasts reflect these base conditions alongside rice bran oil harvest volatility patterns. Revision becomes warranted when ECHA surfactant authorization scope or California state plastic reduction implementation crosses regulatory stringency thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.