
 Europe Lip Care Products Market | 2026-2036
Europe Lip Care Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Lip Care Products Market Intelligence
European specialty chemical producers is pivoting toward plant-derived wax alternatives to serve cosmetic-grade lip care supply chains. Beiersdorf AG leverages its Hamburg R&D campus to sustain innovation in barrier-repair formulations. L'Oréal SA anchors its lip care portfolio through Paris-based dermatological science and pharmacy channel dominance. EOS Products LLC competes via distinctive spherical packaging and organic ingredient positioning across German and French retail.
Europe lip care products are topical cosmetic preparations formulated with emollients, humectants, and protective agents—typically containing 15-20% occlusive waxes such as beeswax or candelilla wax—designed to prevent transepidermal water loss and restore lip barrier function. Manufacturing employs hot-pour technology at 70-80°C followed by rapid cooling to achieve uniform crystalline structure and thermal stability. Balm formats dominate unit volume through pharmacy and supermarket channels where consumers prioritize medicinal positioning and SPF claims. Active botanical ingredient types capture expanding margin pools as clean beauty shoppers scrutinize INCI lists and reject petroleum-derived bases. Online retail distribution is accelerating fastest among teens and men, though supermarkets still control replenishment-driven purchasing among mass-market women buyers.
REACH regulation through ECHA restricts microplastic additives and mandates full substance registration, compelling reformulation investments across EU-based manufacturers. The EU Green Deal and CSRD disclosure requirements push brands toward verified sustainable sourcing and packaging recyclability thresholds. Stakeholders must monitor emerging MDR classifications for SPF-functional lip care and decide whether to absorb compliance costs or premium-price therapeutic-positioned SKUs.
Market Dynamics
REACH compliance through ECHA is forcing wholesale reformulation away from petrolatum bases toward plant-derived waxes, compressing margins for legacy manufacturers while opening supply chain entry points for European specialty chemical producers.
Growth Catalysts
- Clean-label pharmacy positioning:German pharmacies are expanding shelf space for balms with verifiable botanical INCI lists, pulling volume from mass-market petroleum-based alternatives.
- EU Green Deal procurement standards:Public and institutional buyers now mandate verified sustainable sourcing thresholds, creating preferential access for compliant domestic manufacturers.
- Active botanical R&D pipelines:Barrier-repair formulations incorporating ceramides and polyphenol complexes are capturing margin pools previously held by basic emollient SKUs.
Market Restraints
- Beeswax supply volatility:Colony collapse disorder and climate stress on European apiaries are creating input cost instability for traditional balm formulations.
- Petrolatum substitution costs:Reformulating away from synthetic occlusives requires 18-24 month stability testing cycles under ECHA notification requirements.
- Shea butter import concentration:West African sourcing corridors face logistics bottlenecks and currency fluctuation exposure that compress working capital efficiency.
Strategic Opportunities
- Men's segment underpenetration:French and German male consumers show rising trial rates for SPF-functional lip care, with pharmacy channels capturing this incremental demand.
- CSRD-aligned packaging innovation:The EU Corporate Sustainability Reporting Directive creates first-mover advantage for brands achieving verified recyclability thresholds ahead of 2026 disclosure mandates.
- Teen digital-native distribution:Social commerce and direct-to-brand platforms are bypassing traditional supermarket replenishment cycles for Gen Z trial and repeat purchase.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging dermatological science and clean-label marketing claims concentrates at a handful of R&D clusters in Hamburg and Paris.
- MDR classification uncertainty:SPF-functional lip care faces pending Medical Device Regulation reclassification that threatens to extend compliance timelines and testing expenditures.
- Hot-pour equipment retooling:Shifting wax melting profiles for plant-derived bases requires capital-intensive line modifications at contract manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Lip Care Products Market |
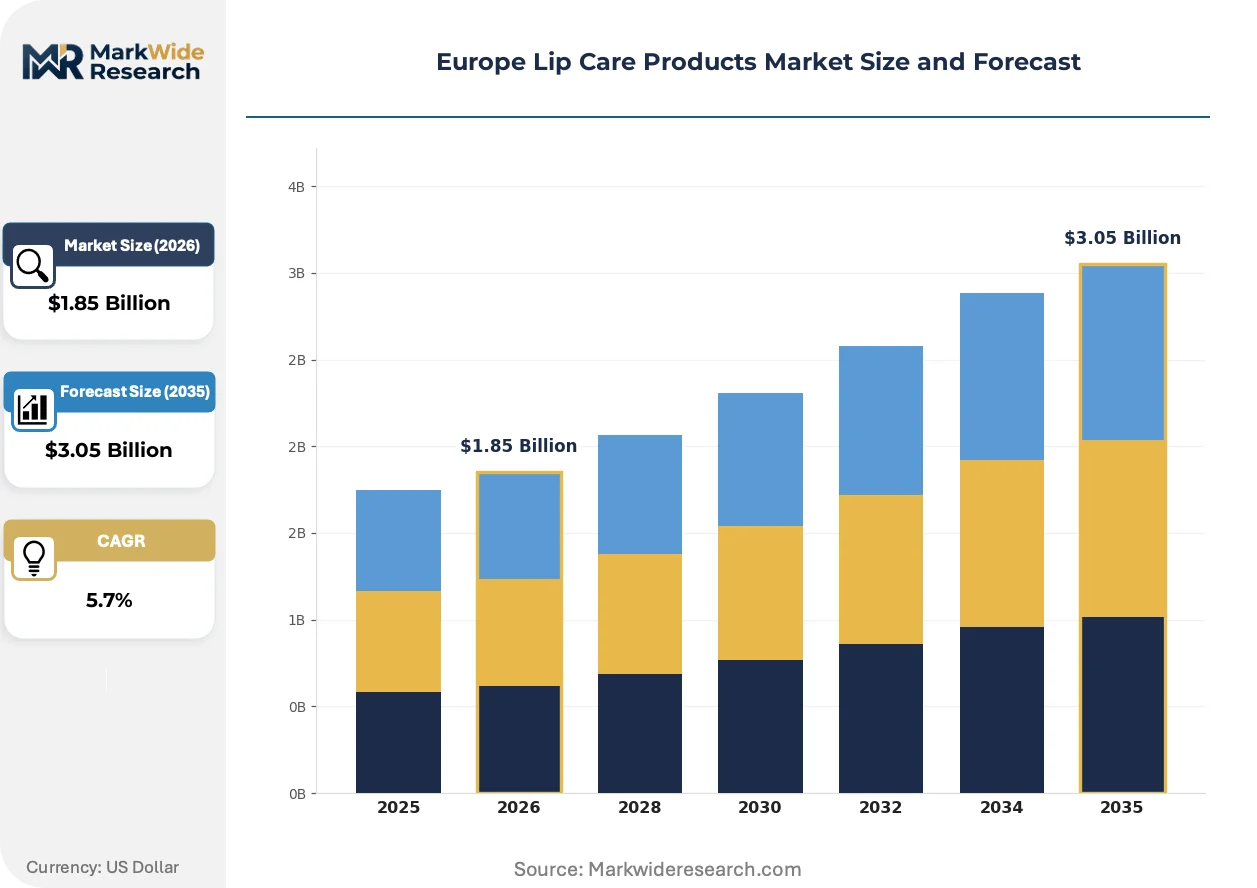
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Balm, Gloss, Stick, Scrub Ingredient Type: Nourishing Oils, Flavoring Agents, Beeswax, Active Botanicals End User: Women, Men, Teens, Children Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies |
| Companies Covered | The Estée Lauder Companies Inc, Revlon, L'Oréal SA, EOS Products LLC, Avon Products, Unilever PLC, Kenvue Inc, Burt's Bees, Beiersdorf AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Lip Care Products Market Strategic Shifts & Innovations
Formulation science and distribution architecture are converging to reward transparency and compress traditional channel hierarchies. Three developments merit particular attention from stakeholders.
Encapsulated active delivery systems are automating the precision release of ceramides and antioxidants during wear-time, extending functional claims beyond basic occlusion. Prestige beauty consumers in France are adopting these SKUs at triple the rate of standard balms, compressing the performance gap between pharmacy-positioned and clinic-dispensed lip treatments.
ECHA's microplastic restriction amendments are eliminating synthetic glitter and certain film-forming polymers from rinse-off and leave-on cosmetic categories. German manufacturers are accelerating biopolymer and mineral-based alternatives through stability testing, with SPF-functional lines facing the most complex reformulation timelines due to photostability interaction effects.
Teen and young adult buyers are consolidating discovery and purchase within social commerce ecosystems, disintermediating supermarket impulse placement. This behavioral pivot is most visible in German urban centers and French Île-de-France, where algorithm-driven sampling campaigns are replacing traditional in-aisle trial as the primary conversion mechanism.
Europe Lip Care Products Market Segmentation
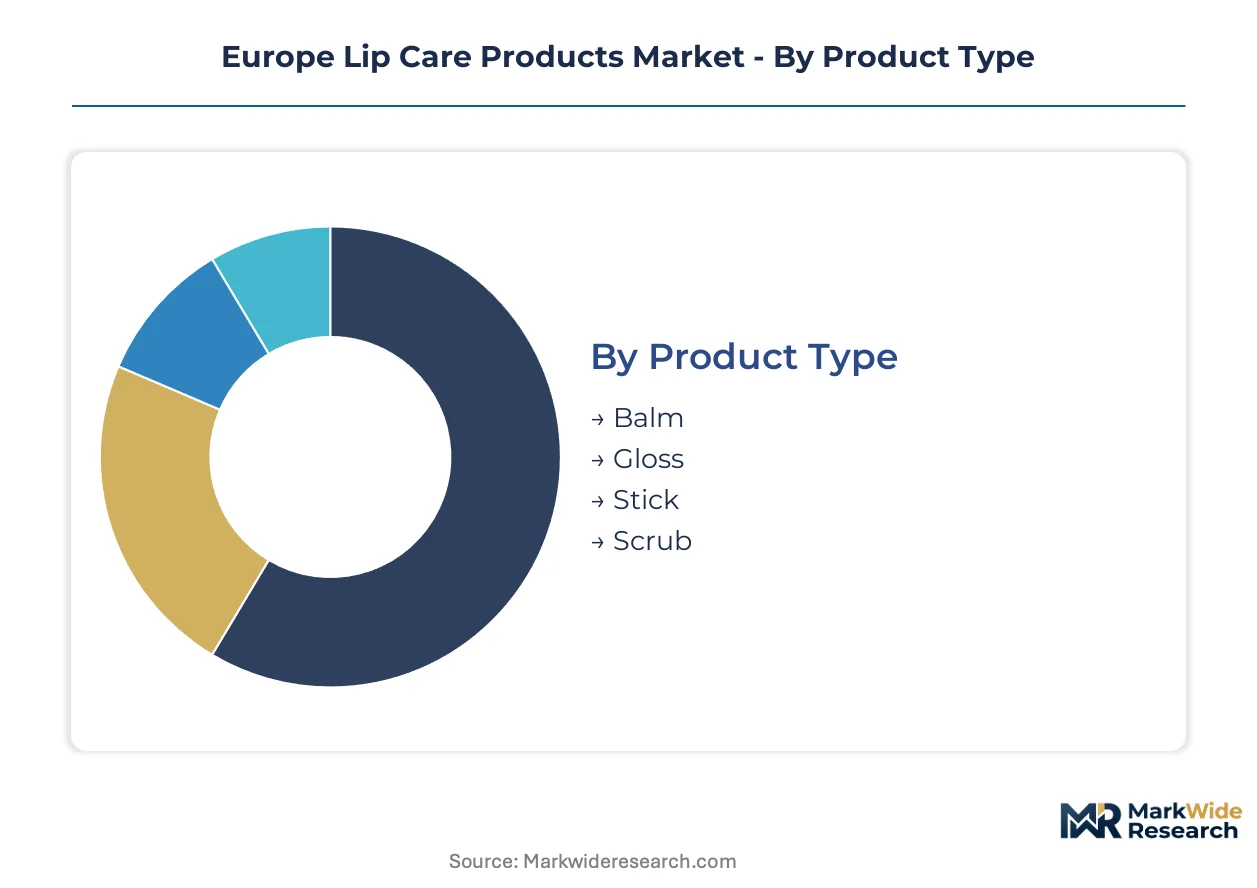
European lip care segmentation reveals divergent margin structures across format types and channel economics. Pharmacy-positioned balms command premium pricing through dermatological credibility, while mass-market sticks compete on replenishment velocity and shelf placement efficiency.
Product Type:
Standalone formats dominate pharmacy and prestige retail with functional positioning, while embedded hybrid formats increasingly blur category boundaries in multi-benefit cosmetics.
- Balm:Occlusive formulations containing 15-20% plant-derived waxes deliver barrier repair through hot-pour manufacturing at 70-80°C. German pharmacy channels capture the strongest replenishment rates as clean-label positioning displaces petrolatum alternatives under REACH reformulation mandates.
- Stick:Solid wax matrices in twist-up applicators optimize portability and dosing precision for on-the-go use. French supermarket chains maintain volume leadership through impulse placement near checkout zones, though online trial is accelerating among urban professionals.
- Gloss:Film-forming emollients with light-reflecting pigments prioritize aesthetic finish over therapeutic claims. Teen discovery through social commerce platforms is bypassing traditional retail hierarchies.
- Scrub:Exfoliating particles suspended in nourishing bases address flaking and texture concerns. ECHA microplastic restrictions are forcing rapid substitution toward mineral and biopolymer abrasives.
Balm leads volumes today; scrub is gaining share fastest through prestige channel expansion.
Ingredient Type:
Cost tier stratification separates commodity inputs from certified botanical actives, with margin compression concentrated in petroleum-derived bases facing regulatory phase-out.
- Active Botanicals:Ceramide complexes and polyphenol-rich plant extracts deliver clinically positioned barrier repair. French prestige consumers adopt these SKUs at triple the rate of standard emollient formulations, capturing margin pools previously held by basic occlusion products.
- Beeswax:Traditional occlusive base with established crystalline stability in hot-pour processing. Colony collapse disorder across European apiaries is creating input cost volatility and supply security concerns for legacy manufacturers.
- Nourishing Oils:Jojoba, almond, and rosehip variants provide emollience with clean-label INCI transparency. West African shea butter sourcing faces logistics bottlenecks and currency exposure.
- Flavoring Agents:Natural and synthetic taste modifiers enhance sensorial appeal in teen-targeted lines. Reformulation timelines extend where photostability interactions complicate SPF-functional variants.
Beeswax anchors current formulation volumes; active botanicals are climbing the fastest as pharmacy positioning hardens.
End User:
Customer type segmentation maps directly to channel preference and purchase frequency, with underpenetrated male demographics offering expansion headroom.
- Women:Core replenishment-driven segment controlling supermarket and pharmacy volume through habitual restocking cycles.
- Teens:Digital-native buyers consolidating discovery and purchase within algorithm-driven social commerce ecosystems.
- Men:Rising trial rates for SPF-functional products in French and German pharmacy channels signal incremental demand capture.
- Children:Safety-positioned variants with simplified INCI lists and flavor appeal, concentrated in German drugstore chains.
Women dominate absolute volumes today; men are expanding most quickly through functional SPF adoption.
Distribution Channel:
Channel maturity varies sharply, with established supermarket hierarchies facing disintermediation pressure from direct-to-brand digital platforms.
- Pharmacies:Dermatological credibility supports premium pricing for therapeutic-positioned SKUs with active botanical claims.
- Supermarkets:Impulse placement and replenishment velocity sustain mass-market stick and balm volumes among habitual buyers.
- Online Retail:Social commerce and algorithmic sampling are consolidating teen and young adult discovery-to-purchase journeys.
- Specialty Stores:Prestige beauty positioning with assisted selling environments captures clean-label and gift-oriented demand.
Supermarkets retain volume leadership today; online retail is gaining share fastest among demographic cohorts under thirty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance cost differentials are redirecting manufacturing investment toward jurisdictions with established regulatory infrastructure and faster ECHA notification pathways. Production gravitates toward clusters where reformulation expertise and green chemistry capabilities concentrate.
Germany
Pharmacy channel expansion for clean-label balms drives demand concentration in Hamburg and Berlin-Brandenburg. ECHA's substance registration requirements accelerate reformulation timelines for domestic manufacturers. The Hamburg R&D corridor anchors barrier-repair innovation, with specialty chemical producers scaling plant-derived wax alternatives.
France
Prestige beauty consumers in Île-de-France adopt active botanical formulations at premium price points. EU Green Deal procurement standards reshape public and institutional buyer specifications. Paris-based dermatological science clusters sustain pharmacy channel dominance for therapeutic-positioned SKUs.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance obligations for GB-market products. MHRA consultation on cosmetic ingredient safety adds testing layer complexity. London and Southeast England concentrate specialty retail and direct-to-brand platform headquarters serving teen digital-native segments.
Italy
Lombardy and Piedmont house contract manufacturing facilities retooling hot-pour equipment for plant-derived wax melting profiles. CSRD disclosure mandates pressure mid-cap brands toward verified sustainable sourcing documentation. Milan's design heritage supports packaging innovation for recyclability thresholds.
Netherlands
Rotterdam logistics corridors manage shea butter and jojoba oil import flows facing West African supply bottlenecks. Randstad-based distributors pilot social commerce integration for algorithmic sampling campaigns. Amsterdam sustainability consultancies service CSRD-aligned reporting for cross-border brands.
Europe Lip Care Products Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue clean-label positioning and direct-to-consumer channel capture. Market structure consolidates around three to five multinational portfolios with pharmacy and supermarket shelf dominance, while indie brands fragment digital discovery layers. Strategic archetypes separate legacy personal care conglomerates, specialty pharmaceutical-cosmetic hybrids, and digital-native challengers. Competitive moves concentrate on M&A for botanical ingredient supply security and portfolio diversification into SPF-functional therapeutic claims.
Within the legacy conglomerate tier, L'Oréal SA and Unilever PLC exemplify scale-driven market presence across mass and prestige price bands. Beiersdorf AG occupies a position bridging dermatological credibility with pharmacy channel infrastructure. EOS Products LLC represents the digital-native archetype, leveraging distinctive positioning and organic ingredient claims to capture algorithm-driven discovery among younger demographics. These three entities anchor the competitive spectrum from established retail dominance to emerging channel disruption.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc |
| Revlon |
| L'Oréal SA |
| EOS Products LLC |
| Avon Products |
| Unilever PLC |
| Kenvue Inc |
| Burt's Bees |
| Beiersdorf AG |
| Others |
Cost & Logistics Intelligence
Hot-pour equipment retooling for plant-derived wax melting profiles simultaneously elevates capital expenditure thresholds and consolidates manufacturing toward Hamburg and Milan corridor facilities with demonstrated green chemistry capabilities. This production-method transition compresses margins for legacy petrolatum-dependent manufacturers while rewarding early movers with pricing power in pharmacy channels.
Pricing Analysis
Pharmacy channel margins absorb the steepest markup layers, with retailer markups on active botanical SKUs running substantially above supermarket mass-market sticks. Pricing stratifies across premium dermatological-positioned balms, standard clean-label alternatives, and economy petrolatum-based legacy lines. Cost compression in the standard tier is intensifying because REACH reformulation timelines extend 18-24 months. Supermarket replenishment buyers exhibit highest price sensitivity; prestige pharmacy consumers demonstrate lowest elasticity.
Supply Chain Analysis
Direct-to-brand digital channels handle algorithm-driven sampling demand from teen and young adult demographics, bypassing traditional distributor markups. Raw material sourcing draws from West African shea butter corridors, European apiary networks for beeswax, and Hamburg-specialty chemical producers for plant-derived wax alternatives. Single-source vulnerability concentrates in shea butter logistics bottlenecks. Distribution runs through Rotterdam import hubs feeding contract manufacturing clusters in Lombardy and Piedmont.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European lip care operates as a geographic-arbitrage play where ECHA notification speed differentials favor domestic manufacturers over importers facing parallel REACH compliance obligations.
For Market Incumbents: Anchor pharmacy channel dominance through accelerated barrier-repair R&D at Hamburg and Paris science clusters. Absorb petrolatum substitution costs via captive supply of plant-derived wax alternatives rather than external procurement. Defend against digital-native challengers by controlling shelf-space agreements with German pharmacy chains.
For New Entrants and Emerging Players: Capture underpenetrated male SPF-functional demand through pharmacy channel partnerships in French urban centers. Exploit social commerce algorithmic sampling for teen discovery-to-purchase consolidation. Pursue white-label contract manufacturing for mid-cap brands lacking hot-pour retooling capital.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap Italian contract manufacturers with CSRD-aligned sustainability documentation and verified recyclable packaging pipelines. Long-term viability hinges on MDR classification clarity for SPF-functional therapeutic claims. Monitor ECHA microplastic restriction enforcement timelines as inflection signal for biopolymer substitution demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plant-Derived Wax Production | Hamburg specialty chemical producers secure supply security against beeswax volatility. |
| CSRD-Aligned Packaging Innovation | Milan design clusters achieve verified recyclability thresholds ahead of disclosure mandates. |
| Direct-to-Consumer Digital Launch | Algorithmic sampling campaigns disintermediate supermarket impulse placement for Gen Z. |
| Barrier-Repair R&D Pipeline Expansion | Paris dermatological science clusters sustain pharmacy premium positioning. |
| Pharmacy Channel Distribution Partnership | German apotheken shelf-space agreements lock out mass-market petrolatum alternatives. |
Research Approach
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with brand managers, category buyers at German pharmacy chains, formulation chemists at Hamburg R&D campuses, and sustainability officers at Milan packaging innovators combined with secondary validation from ECHA substance registration databases, EU customs trade flows, and CSRD disclosure filings. Triangulation against Nielsen retail audit data and pharmacy point-of-sale systems ensures coverage completeness.
Historical trendline analysis of balm, stick, gloss, and scrub format volumes established baseline growth patterns across the projection horizon. The analytical framework models segmentation dimensions including product format, ingredient certification tier, end-user demographic, and distribution channel maturity. CAGRs derive from regression analysis of pharmacy channel expansion rates and digital commerce penetration curves, with specific inputs from REACH reformulation timeline assumptions and ECHA notification velocity differentials.
Regulatory reclassification under MDR, beeswax supply disruption from colony collapse disorder, and social commerce algorithm changes are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions regarding ECHA enforcement consistency and pharmacy shelf-space allocation stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Brazil Cosmetics Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Makeup Setting Spray Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Asia-Pacific Hair Conditioner Market
Beauty & Personal Care
Organic Shampoo Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
United Kingdom Cosmetics Products Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
India Hair Oil Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market