
 Lip Care Market | 2026-2036
Lip Care Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Care Market Analysis
Plant-derived waxes and oils are expanding their share of lip balm formulations as brands reformulate away from mineral oil and petrolatum. EOS Products LLC leverages its vertical integration in natural ingredient sourcing to control cost volatility. Beiersdorf AG anchors its portfolio through dermatological credibility and pharmacy channel dominance. L’Oréal SA competes by extending its skincare science into lip treatment hybrids with active ingredients.
Lip care comprises topical preparations designed to protect, moisturize, and repair the vermilion border and surrounding perioral skin, typically incorporating occlusive agents such as petrolatum or beeswax at 15-40% concentration, emollients like shea butter or squalane, and humectants including glycerin or hyaluronic acid to prevent transepidermal water loss in thin, non-keratinized tissue. Lip oil represents the fastest-growing product type as consumers prioritize glossy hydration over waxy occlusion, while natural and organic ingredient categories command margin premiums despite higher raw material costs. The stick packaging format retains volume leadership in convenience channels, though tube and jar formats capture premium positioning in specialty and professional settings.
FDA oversight of cosmetic labeling and ingredient safety under the Modernization of Cosmetics Regulation Act shapes product claims and substantiation requirements for US-market entrants. EU REACH restrictions on microplastics and certain fragrance allergens compel reformulation cycles for brands serving European consumers. Stakeholders must monitor evolving state-level chemical disclosure laws in California and New York that extend beyond federal minimums.
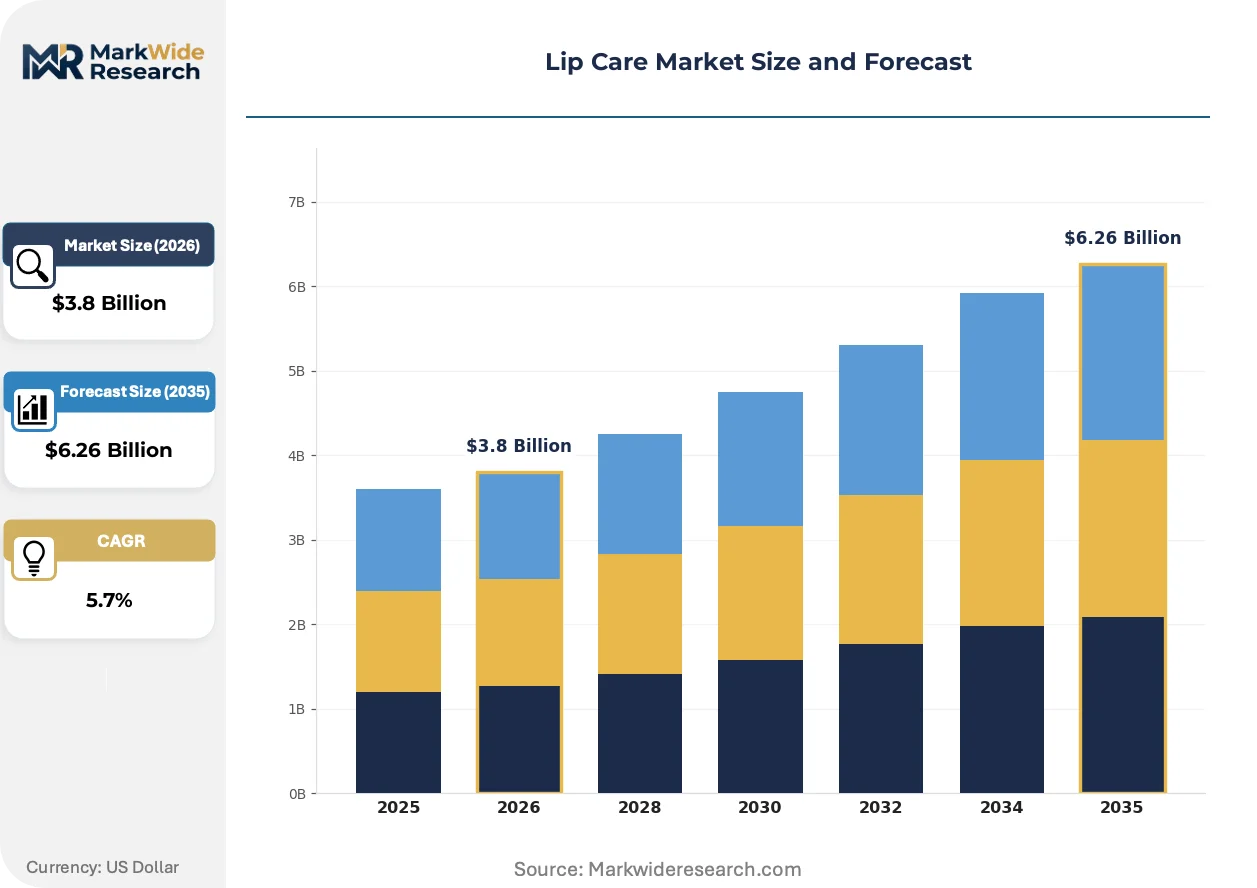
Market Dynamics
Clean beauty mandates are forcing wholesale reformulation across lip care portfolios as petroleum-derived occlusives face phasedown under EU REACH chemical safety protocols and parallel state disclosure laws in California and New York.
Growth Catalysts
- EU REACH chemical safety rules:Regulatory pressure on microplastics and petrolatum derivatives is accelerating brand investment in plant-based wax alternatives and certified organic supply chains.
- Men's grooming expansion:Male consumers are broadening daily routines to include dedicated lip treatment products, creating incremental volume in previously underpenetrated demographic segments.
- Lip oil format preference:Consumer pivot toward glossy, non-waxy hydration textures is pulling manufacturing capacity and retail shelf space away from traditional stick balms.
Market Restraints
- Natural ingredient cost volatility:Weather-dependent yields for shea butter, jojoba oil, and beeswax create margin compression that petroleum-based competitors do not face.
- Supply concentration in shea belt:West African sourcing dominance for shea nuts exposes formulators to regional political instability and currency fluctuation risks.
- Reformulation timeline friction:FDA Modernization of Cosmetics Regulation Act substantiation requirements extend new product development cycles by 12-18 months for US market entrants.
Strategic Opportunities
- Professional channel penetration:Dermatology clinics and medical spas represent underdeveloped distribution for clinically-positioned lip treatment hybrids with active ingredients.
- Biotechnology-derived emollients:Fermentation-based squalane and lab-grown ceramides offer supply security and narrative differentiation for premium positioning.
- Refill and concentrated formats:Solid balm concentrates and reusable applicator systems align with packaging waste reduction mandates emerging in France and Germany.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in natural emulsion stability and preservative-free systems commands premium compensation and lengthens hiring timelines.
- Cross-border labeling complexity:Divergent INCI disclosure requirements between FDA, Health Canada, and EU cosmetic regulations multiply SKUs and compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Care Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lip Balm, Lip Scrub, Lip Mask, Lip Oil Ingredient Type: Natural, Organic, Synthetic, Herbal End User: Women, Men, Teens, Children Packaging Type: Tube, Jar, Stick, Pouch |
| Companies Covered | Procter & Gamble, Colgate-Palmolive Company, Unilever PLC, EOS Products LLC, Revlon, L’Oréal SA, Johnson & Johnson, Shiseido Company, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Care Market Emerging Trajectories
Biotechnology and precision fermentation are rewriting ingredient sourcing economics while regulatory chemistry restrictions and male grooming normalization simultaneously reshape demand patterns and competitive positioning.
Precision fermentation is automating the production of squalane, ceramides, and peptide actives that previously required animal or plant extraction. Premium skincare brands are integrating these bioidentical lipids into treatment-oriented lip products at scale. This automation is compressing raw material lead times from agricultural cycles to bioreactor batches and eroding the cost premium that once separated biotechnology ingredients from petroleum synthetics.
EU REACH restrictions on microplastics in rinse-off and leave-on cosmetics are forcing reformulation of glitter, film-forming agents, and certain silicone derivatives by 2027. Brands serving European consumers must validate biodegradability through OECD testing protocols or remove affected ingredients entirely. Color cosmetics with lip treatment benefits face the steepest compliance burden given pigment and texture complexity.
Subscription and auto-replenishment models are capturing routine lip care purchases that previously flowed through impulse retail channels. Direct-to-consumer brands with personalized flavor and ingredient profiles are displacing convenience-store volume in millennial and Gen Z cohorts. This behavioral shift concentrates most visibly in the United States, where specialty beauty retailers have built fulfillment infrastructure supporting recurring shipment models.
Lip Care Market Segmentation
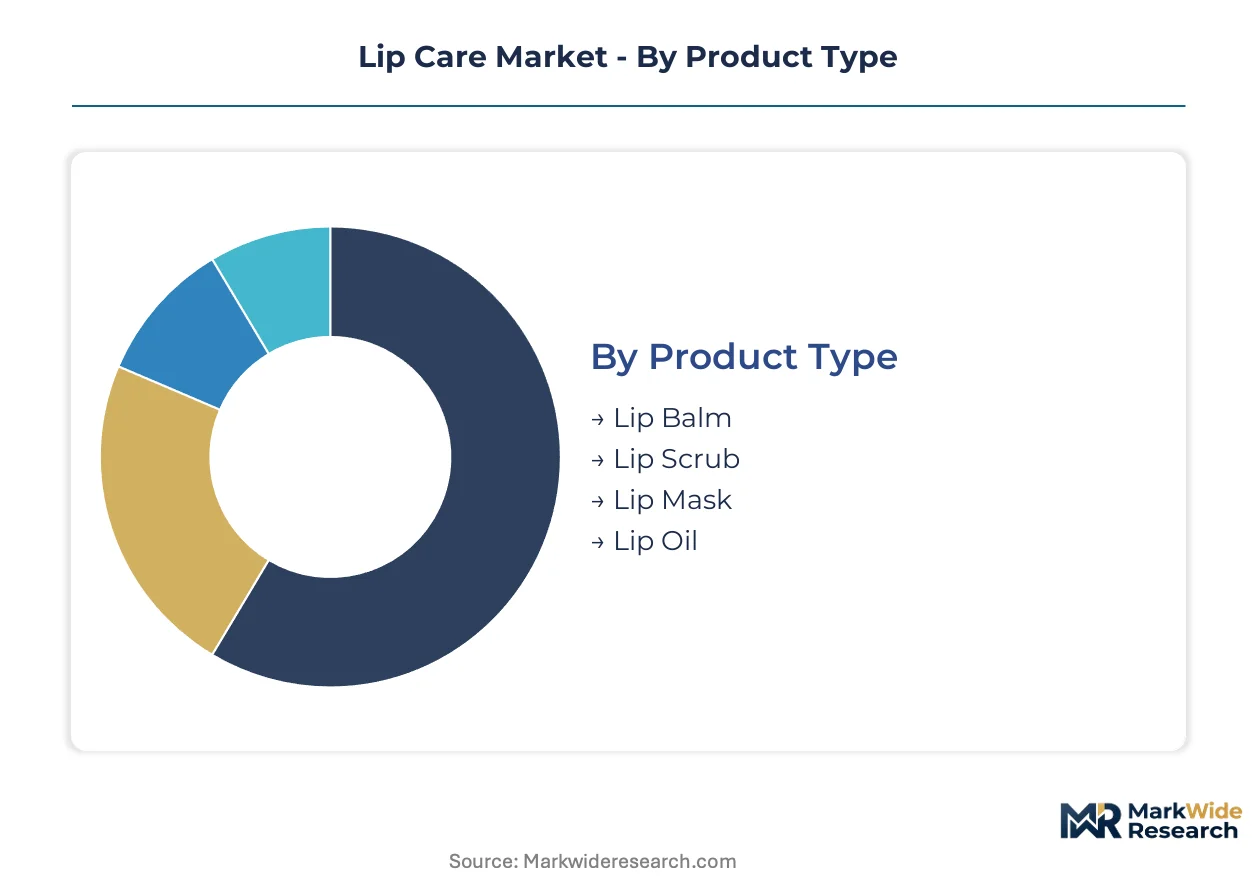
Lip care segmentation reveals divergent growth vectors across formulation chemistry, user demographics, and retail channel economics. Product format and ingredient sourcing decisions increasingly determine margin structure and regulatory exposure.
Product Type:
Technology and texture specifications differentiate competitive positioning across formats.
- Lip Oil:Lightweight emollient systems deliver glossy hydration through squalane, jojoba, and plant-derived esters without waxy occlusion. Demand concentrates in United States specialty retailers where premium natural lip oils command shelf space from traditional balms.
- Lip Balm:Occlusive preparations incorporating petrolatum or beeswax at 15-40% concentration remain the volume foundation in convenience channels. FDA oversight of cosmetic labeling under the Modernization of Cosmetics Regulation Act shapes substantiation requirements for claims.
- Lip Scrub:Exfoliating formulations with sugar, salt, or microcrystalline cellulose address flaking and texture improvement.
- Lip Mask:Intensive overnight treatments with higher humectant loads and occlusive films for repair positioning.
Mature deployment sits with lip balm. Newer deployment is concentrated in lip oil.
Ingredient Type:
Raw material sourcing tier determines regulatory compliance burden and cost volatility exposure.
- Natural:Plant-derived waxes and oils from shea, coconut, and jojoba sources displace petroleum-based ingredients under EU REACH chemical safety pressure. Weather-dependent yields for shea butter create margin compression that synthetic competitors avoid.
- Organic:Certified supply chains with third-party verification command price premiums in European and North American premium channels. West African sourcing dominance for shea nuts exposes formulators to regional political instability and currency fluctuation risks.
- Synthetic:Petrolatum and mineral oil derivatives face phasedown under EU REACH protocols and parallel state disclosure laws in California and New York.
- Herbal:Botanical extracts with traditional medicine positioning targeting specific therapeutic claims.
Volume concentration rests with natural formulations. Steepest expansion trajectory belongs to organic certification tiers.
End User:
Demographic penetration depth varies dramatically across gender and age cohorts.
- Men:Grooming routine broadening beyond traditional categories creates incremental volume in previously underpenetrated segments. Male consumers in United States and Western European markets are adopting dedicated lip treatment products as daily essentials.
- Women:Established core users with highest per-capita consumption and willingness to purchase treatment-positioned hybrids.
- Teens:Flavor-driven purchasing with social media-influenced brand discovery patterns.
- Children:Safety-formulated segments with restricted ingredient lists and pediatric positioning.
Established penetration sits with women. Gaining share fastest is the men's segment.
Packaging Type:
Format selection channels distribution economics and sustainability compliance requirements.
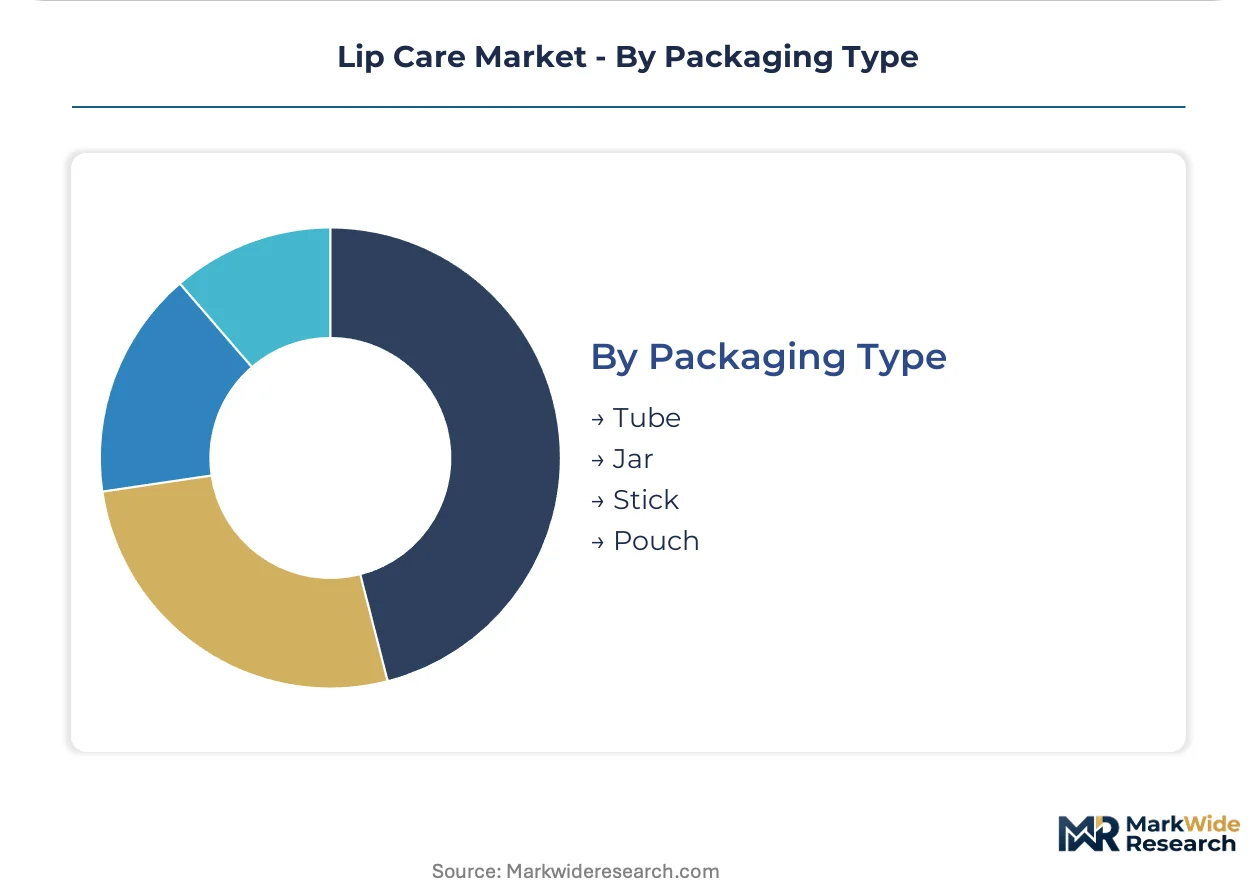
- Stick:Retains volume leadership in convenience channels with lowest per-unit cost and highest portability. Solid balm concentrates and reusable applicator systems align with packaging waste reduction mandates emerging in France and Germany.
- Tube:Squeeze formats capture premium positioning in specialty retail with controlled dispensing and hygiene perception.
- Jar:Pot containers dominate professional and medical spa settings with scoop-applied treatment textures.
- Pouch:Single-use and sample formats for trial generation and travel retail.
Volume concentration sits with stick formats. Newer deployment is concentrated in tube and jar premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for lip care products concentrates heavily in the United States, where premium natural formulations command shelf space at specialty retailers and male grooming adoption accelerates fastest.
United States
Specialty beauty retailers and direct-to-consumer subscription models capture routine purchases from millennial and Gen Z cohorts. The FDA Modernization of Cosmetics Regulation Act extends new product development timelines by 12-18 months for substantiation requirements. Greater Los Angeles and New York City host clusters of clean beauty formulators developing plant-derived alternatives to petroleum-based occlusives.
Germany
Pharmacy channel dominance and dermatological credibility anchor consumer trust in clinically-positioned lip treatments. The EU REACH regulation on microplastics and petrolatum derivatives compels reformulation by 2027. The Rhine-Ruhr industrial corridor concentrates contract manufacturing capacity for certified organic supply chains serving European markets.
France
Premium positioning and heritage beauty houses sustain margin premiums for treatment-oriented hybrids with active ingredients. Packaging waste reduction mandates emerging from Paris and Brussels drive investment in refill and concentrated formats. The Île-de-France region hosts fermentation-based ingredient startups supplying bioidentical lipids to luxury brands.
Japan
Advanced skincare science and hybrid product development blur boundaries between color cosmetics and lip treatment. METI standards on ingredient safety and biodegradability testing shape export compliance for brands serving Asian markets. The Kanto region around Tokyo concentrates R&D facilities for peptide-active formulations.
Brazil
Expanding middle-class consumption and tropical climate conditions drive demand for protective and repair-positioned products. ANVISA oversight of cosmetic labeling and ingredient disclosure creates compliance complexity for imported formulations. São Paulo anchors distribution infrastructure for brands targeting Latin American volume growth.
Lip Care Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with convenience channels favoring scale-driven multinationals while specialty retail rewards niche positioning. The vendor base organizes around three strategic archetypes: vertically integrated natural ingredient specialists, dermatology-credentialed pharmacy anchors, and skincare science extenders from adjacent beauty categories. Competitive moves concentrate on reformulation investment to meet EU REACH deadlines and professional channel penetration into dermatology clinics and medical spas.
Among multinational consumer goods conglomerates, Procter & Gamble and Unilever PLC exemplify scale-driven portfolio breadth across mass-market channels. L'Oréal SA occupies a position bridging premium skincare science with color cosmetic adjacencies. Beiersdorf AG anchors the dermatological credibility archetype through pharmacy channel relationships. EOS Products LLC represents vertical integration into natural ingredient sourcing as a differentiation mechanism against petroleum-dependent competitors.
| Leading Market Players |
|---|
| Procter & Gamble |
| Colgate-Palmolive Company |
| Unilever PLC |
| EOS Products LLC |
| Revlon |
| L’Oréal SA |
| Johnson & Johnson |
| Shiseido Company |
| Beiersdorf AG |
| Others |
Supply Flow & Price Mechanics
Precision fermentation is displacing agricultural extraction for squalane and ceramide production, simultaneously compressing bioreactor batch costs and reducing geographic supply concentration away from West African shea belt dependency. This biotechnology transition is redrawing cost curves for premium lip care tiers while exposing legacy petroleum-based formulators to margin compression from dual-direction raw material substitution.
Pricing Analysis
Volume-mass stick balms trade at commodity margins in convenience channels, while premium lip oils and certified organic tiers capture threefold price multiples through specialty retail positioning. Price differentiation rests on certification grade and brand heritage, with EU organic seals and dermatological endorsements commanding measurable premiums. Cost compression in natural ingredient tiers is intensifying because fermentation-based alternatives erode agricultural yield volatility. Mass-market buyers exhibit highest price sensitivity, whereas professional channel purchasers prioritize clinical substantiation over per-unit cost.
Supply Chain Analysis
Single-source vulnerability sits with West African shea nut harvesting, where Ghana, Burkina Faso, and Nigeria collectively feed 80% of global cosmetic-grade supply. Formulation chemistry draws from Malaysian palm derivatives, Indian castor oil, and Brazilian carnauba wax as secondary inputs. Regulatory restriction through EU REACH petrolatum phasedown is forcing rapid supplier qualification for biotech-derived alternatives. Distribution runs through pharmacy networks in Germany, specialty beauty retailers in the United States, and direct-to-consumer subscription platforms capturing recurring replenishment demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lip care sector is executing a biotechnology-transition phase, with precision fermentation replacing plant-extracted squalane and ceramides as the dominant emollient sourcing paradigm.
For Market Incumbents: Anticipate EU REACH compliance deadlines by accelerating biotech ingredient partnerships before 2027 reformulation mandates crystallize. Secure captive supply of fermentation-derived lipids through exclusive offtake agreements with emerging ingredient biotechnology firms. Defensive consolidation around dermatological credibility and pharmacy channel control will insulate margin position against clean beauty entrants.
For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting male grooming segments in the United States and Western Europe, where daily lip treatment adoption remains underpenetrated relative to female cohorts. White-space opportunity concentrates in professional channel penetration—dermatology clinics and medical spas lack clinically-positioned lip treatment hybrids with active ingredient profiles.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by skincare science extenders seeking lip category adjacencies. Long-term viability favors biotechnology-enabled ingredient platforms over petroleum-dependent legacy formulators. Monitor EU REACH enforcement velocity as the critical inflection signal—accelerated petrolatum restriction timelines would compress incumbent valuation multiples while elevating biotech-enabled target premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology Ingredient Partnership | Fermentation-based squalane supply secures margin stability against shea price volatility. |
| Professional Channel Expansion | Dermatology clinic placement captures treatment-positioned premium pricing unavailable in mass retail. |
| Subscription Model Launch | Auto-replenishment platforms displace impulse convenience-store volume with predictable recurring revenue. |
| EU Organic Certification Investment | Third-party verification unlocks pharmacy channel access and price premiums in German-speaking markets. |
| Refill Format Development | Reusable applicator systems align with French and German packaging waste reduction mandates. |
Methodological Framework
Multi-period observation of formulation chemistry transitions, regulatory compliance timelines, and channel migration patterns anchored the trend analysis, supplemented by interviews with clean beauty formulators, pharmacy category buyers, and biotechnology ingredient suppliers. Secondary validation drew from FDA Modernization of Cosmetics Regulation Act filings, EU REACH substance restriction updates, and specialty retailer point-of-sale data. Bottom-up volume modeling across product formats and ingredient tiers was cross-checked against top-down market sizing from trade customs records and industry association estimates.
Input-output matrices mapped raw material flow from shea belt harvesting through contract manufacturing to retail shelf placement, with segmentation dimensions covering product type, ingredient sourcing tier, end-user demographic, and distribution channel. CAGRs were derived from regression analysis of historical volume trajectories against projected regulatory enforcement schedules and consumer format preference shifts. Forecast inputs incorporated biotechnology capacity buildout timelines and male grooming penetration elasticity estimates.
Regulatory enforcement delays, biotechnology scale-up failures, and West African supply disruptions are the dominant revision risks to projection assumptions. Deviation in EU REACH petrolatum restriction timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Hand Care Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Europe Hair Styling Products Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Middle East and Africa Bath and Shower Products Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
DIY Eyelash Extension Market