
 North America Beauty Devices Market | 2026-2036
North America Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Beauty Devices Market Analytics
The EU Green Deal's influence on North American beauty supply chains is realigning ingredient sourcing and packaging standards for device-compatible topicals. FOREO leverages its silicone-engineered facial cleansing platforms to dominate premium direct-to-consumer channels. Candela Corporation sustains its position through specialized laser and energy-based systems for professional dermatology settings. Koninklijke Philips N.V. anchors mass-market penetration with broad retail distribution across the United States and Canada.
North America beauty devices encompass electrically powered instruments engineered with specific wavelength outputs, energy densities, or oscillation frequencies designed for skin treatment, hair removal, or facial cleansing applications. These devices typically operate within FDA-cleared parameters ranging from non-ablative fractional lasers at 1550 nm to LED arrays emitting at 415 nm (blue) or 633 nm (red) for targeted dermatological effects. Hair removal devices utilizing diode laser or intense pulsed light technology command substantial professional segment revenue due to recurring treatment protocols and higher per-session pricing. LED technology for at-home skin care tools represents the fastest-expanding technology dimension as consumers seek clinic-grade outcomes without appointment dependencies. Retail consumers purchasing through online retail channels now constitute the dominant end-user volume pool, though dermatologists retain disproportionate margin capture through prescription-strength device recommendations.
FDA clearance requirements under 21 CFR Part 892 for laser and light-based devices create substantial barriers to market entry while ensuring clinical safety validation for new entrants. Health Canada and the EPA jointly influence device material compliance through electromagnetic emissions standards and battery disposal regulations affecting product lifecycle design. Stakeholders must monitor evolving state-level aesthetic practice scope regulations in Texas, California, and Florida where device operator certification requirements directly impact professional segment addressable demand.
Market Dynamics
FDA clearance pathways for at-home laser and LED devices are compressing time-to-market cycles while simultaneously fragmenting competitive positioning between professional dermatology settings and direct-to-consumer retail channels across the United States and Canada.
Growth Catalysts
- 21 CFR Part 892 pathways:FDA clearance frameworks for laser and light-based devices provide validated safety benchmarks that accelerate insurer reimbursement negotiations and professional adoption.
- LED wavelength convergence:At-home devices emitting at 415 nm and 633 nm now replicate clinical photobiomodulation protocols, expanding addressable demand beyond clinic-dependent consumers.
- California-Texas-New York corridor density:Metropolitan aesthetic service concentration and elevated disposable income in these three state clusters concentrate early adoption velocity and pricing power.
Market Restraints
- Electromagnetic emissions compliance:Health Canada and EPA joint standards on battery disposal and electromagnetic compatibility add material cost layers and lifecycle design constraints.
- Diode laser component concentration:Specialized optical components for hair removal devices source from limited Asian manufacturing bases, creating supply vulnerability.
- State-level operator certification fragmentation:Texas, California, and Florida maintain divergent aesthetic practice scope regulations that complicate professional segment expansion planning.
Strategic Opportunities
- Canadian provincial expansion:Ontario and British Columbia medical spa density lags US metropolitan benchmarks, presenting whitespace for device placement and service network buildout.
- Silicone-engineered platform convergence:Integration of cleansing, microcurrent, and LED modalities into single-form-factor devices opens premium direct-to-consumer positioning.
- EU Green Deal alignment:North American device-compatible topical reformulation around REACH-compliant ingredient sourcing creates differentiation for export-oriented manufacturers.
Industry Challenges
- Photobiology specialist scarcity:Dermatology clinics face recruitment friction for technicians trained in fractional laser parameter optimization and patient-specific wavelength selection.
- FDA 510(k) timeline variability:Substantial equivalence determinations for novel energy-based devices exhibit unpredictable review durations that compress commercialization planning windows.
- Legacy clinic management system integration:Professional-grade devices require API connectivity with electronic health record platforms that lack standardized interoperability protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Beauty Devices Market |
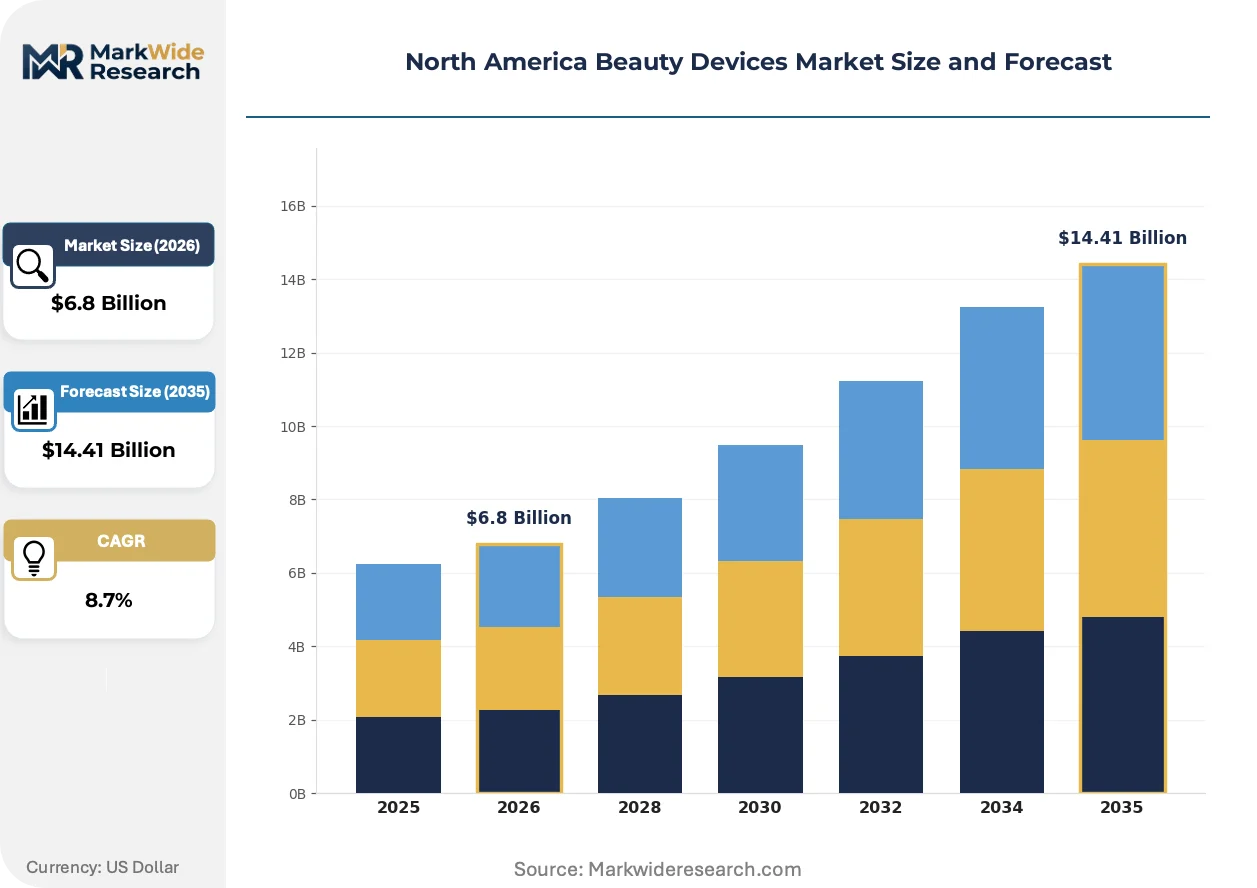
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Cleansing Brushes, Hair Removal Devices, Skin Care Tools, Anti-Aging Devices Technology: LED, Radio Frequency, Ultrasound, Laser End User: Dermatologists, Salons, Retail Consumers, Spa Therapists Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Nu Skin, Candela Corporation, Curallux LLC, FOREO, Koninklijke Philips N.V., Conair Corporation, Lumenis Be Ltd, Cynosure, Sciton, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Beauty Devices Market Evolving Landscape
Device intelligence and connectivity protocols are redefining treatment personalization boundaries, shifting competitive advantage from hardware specifications toward algorithmic skin analysis and adaptive energy delivery systems.
Multi-sensor facial mapping technology is automating real-time skin condition assessment during device operation. Dermatology clinics in California and Texas are deploying these platforms to reduce technician calibration time and standardize outcomes across operator skill levels. The technology is automating the translation of visual skin data into wavelength and energy density parameters that previously required manual clinician judgment.
Health Canada has tightened electromagnetic emissions standards for battery-operated beauty devices under joint EPA coordination, forcing manufacturers to redesign power management architectures. The regulatory friction most impacts at-home LED and microcurrent segments where compact form factors complicate shielding compliance. Device makers are responding with modular battery systems that separate power cells from treatment heads to isolate emission sources.
Subscription-based device access models are displacing outright purchase patterns among millennial and Gen Z demographics. Direct-to-consumer channels in New York and Los Angeles metropolitan areas now lead volume for rental and lease programs bundled with topical consumables. This behavioral shift concentrates recurring revenue capture with platform operators while compressing brand loyalty stickiness for hardware-only manufacturers.
North America Beauty Devices Market Segmentation
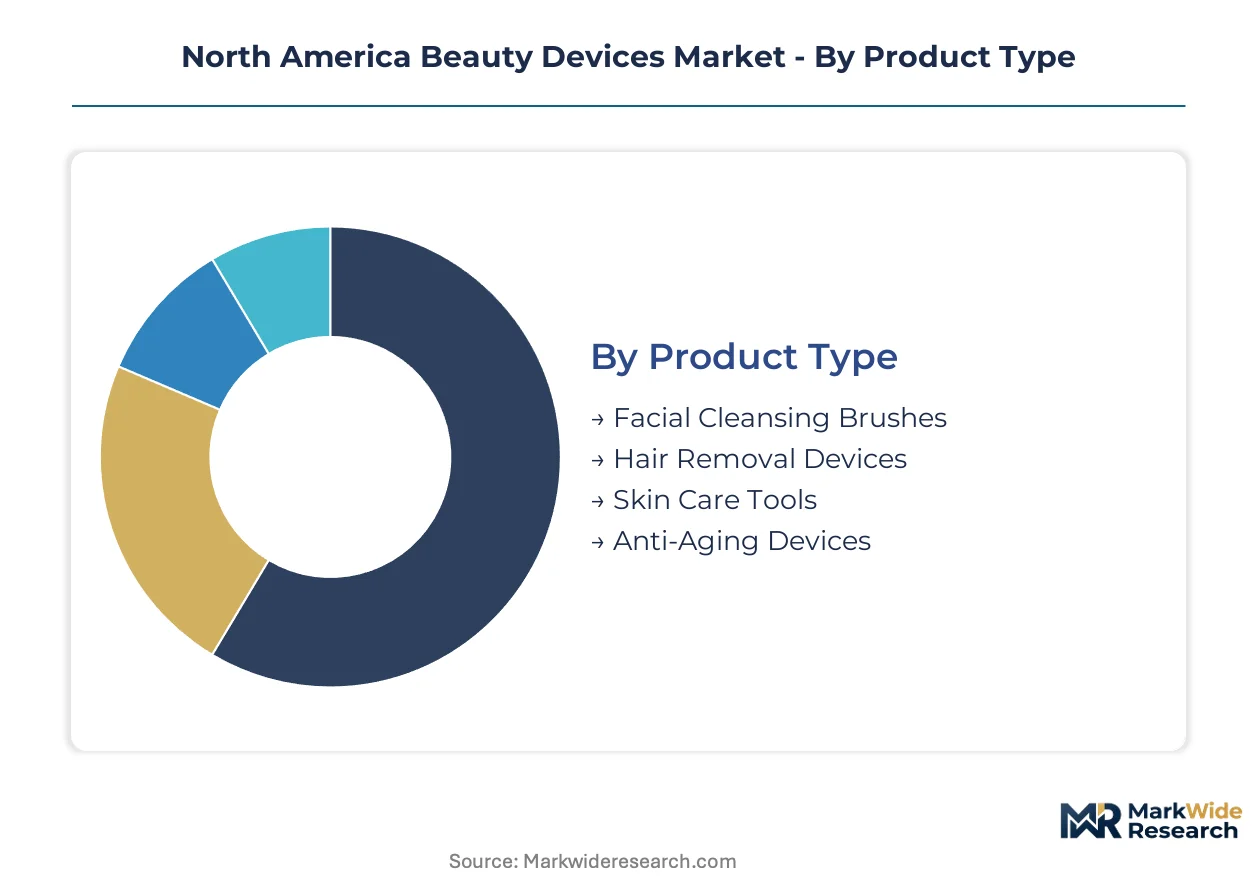
Segmentation in the North America Beauty Devices Market reveals divergent commercialization pathways between professional-grade systems requiring FDA clearance and consumer-accessible tools optimized for retail velocity. Understanding these divisions enables stakeholders to align R&D investment, regulatory strategy, and channel partnerships with the specific compliance burdens and margin profiles governing each segment cluster.
Product Type:
Standardized mass-market formats contrast with customizable professional systems across this category, with silicone-engineered platforms and wavelength-tunable devices occupying opposite ends of the manufacturing complexity spectrum.
- Facial Cleansing Brushes:Silicone-bristle platforms with sonic oscillation at 6,000-8,000 pulses per minute dominate at-home routines through waterproof form factors and minimal maintenance requirements. Demand concentrates in California and New York metropolitan corridors where premium direct-to-consumer brands have established subscription-based replenishment models for brush head replacements.
- Hair Removal Devices:Diode laser and intense pulsed light systems operating at 755-1064 nm wavelengths require FDA 510(k) clearance for home use, creating substantial entry barriers that professional clinic systems exploit through recurring treatment protocols. Texas medical spas drive professional segment volume given permissive aesthetic practice scope regulations and high disposable income density in Dallas-Houston corridors.
- Skin Care Tools:Microcurrent and ultrasonic exfoliation devices serve intermediate users seeking clinic-adjacent outcomes without prescription requirements.
- Anti-Aging Devices:Fractional laser and radio frequency platforms target collagen remodeling with energy densities calibrated for home safety limits.
Leading the category by volume: Facial Cleansing Brushes. Expanding most quickly: Hair Removal Devices.
Technology:
Cost tier stratification separates high-investment laser platforms from accessible LED arrays, with manufacturing scale and component sourcing determining which technologies achieve mass-market price points.
- LED:Arrays emitting at 415 nm (blue) and 633 nm (red) wavelengths replicate clinical photobiomodulation for acne treatment and collagen stimulation at consumer price points. FDA clearance pathways for LED devices compress time-to-market cycles, accelerating product commercialization across United States and Canadian retail channels.
- Laser:Diode and fractional laser systems deliver precise thermal injury for hair removal and skin resurfacing, requiring substantial optical engineering and cooling architectures that concentrate manufacturing among specialized component suppliers.
- Radio Frequency:Thermal collagen remodeling through dermal heating attracts professional clinic investment given immediate visible outcomes and premium per-session pricing.
- Ultrasound:Micro-focused ultrasound penetrates deeper dermal layers for non-invasive lifting, occupying a niche between LED accessibility and laser precision.
Volume leadership: LED. Steepest expansion trajectory: Laser.
End User:
Customer type determines purchasing authority, with prescription requirements and operator certification creating distinct access barriers between medical professionals and retail consumers.
- Retail Consumers:Online retail channels now constitute the dominant end-user volume pool, with millennial and Gen Z demographics driving subscription-based device access models that displace outright purchase patterns in New York and Los Angeles metropolitan areas.
- Dermatologists:Prescription-strength device recommendations retain disproportionate margin capture through clinical validation and insurance reimbursement negotiations, with FDA clearance frameworks under 21 CFR Part 892 providing validated safety benchmarks that accelerate professional adoption.
- Salons:Aesthetic service providers in California, Texas, and Florida navigate divergent state-level operator certification requirements that complicate professional segment expansion planning.
- Spa Therapists:Medical spa density in Ontario and British Columbia lags United States metropolitan benchmarks, presenting whitespace for device placement and service network buildout.
Volume concentration: Retail Consumers. Margin capture: Dermatologists.
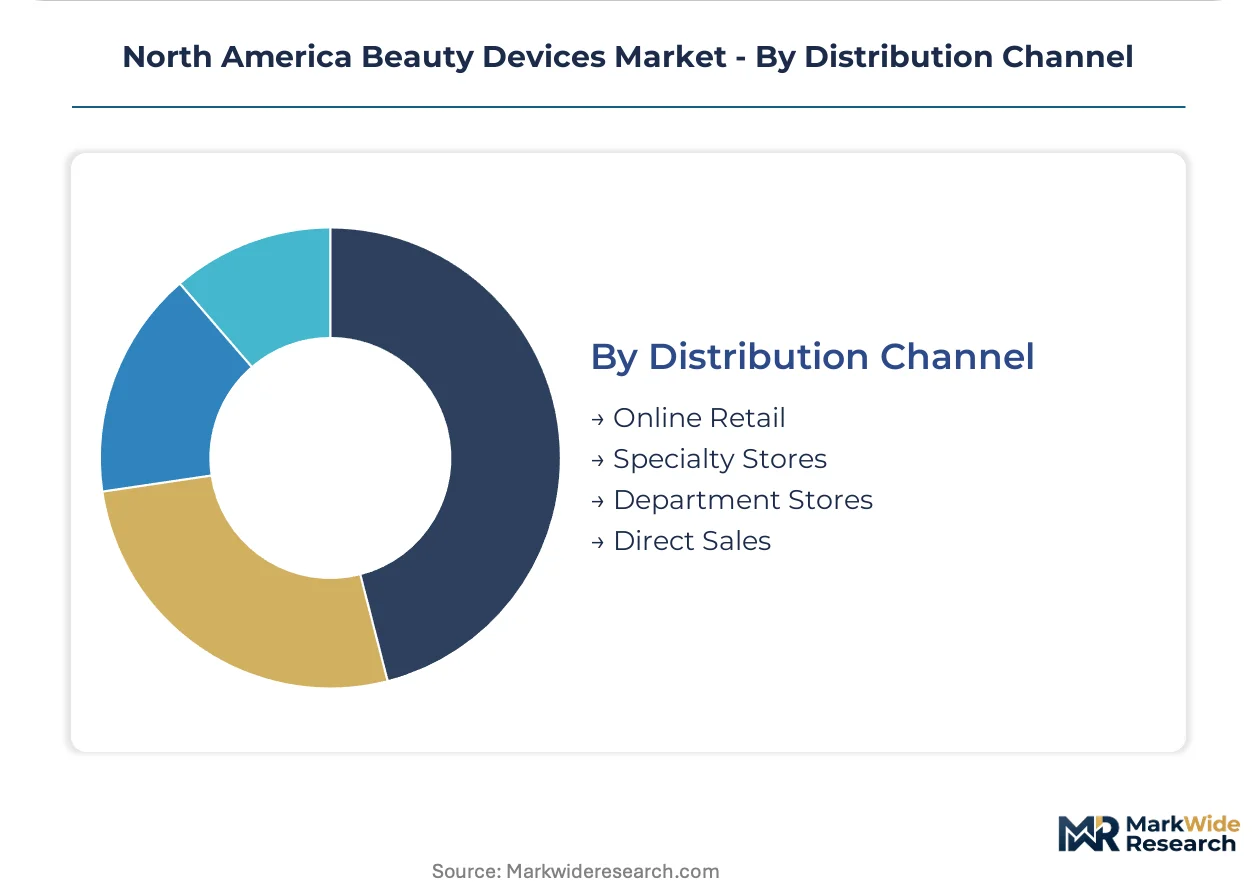
Distribution Channel:
Geography shapes channel effectiveness, with metropolitan corridor density determining whether physical retail or digital platforms achieve superior customer acquisition economics.
- Online Retail:Direct-to-consumer platforms dominate volume for rental and lease programs bundled with topical consumables, compressing brand loyalty stickiness for hardware-only manufacturers while concentrating recurring revenue with platform operators.
- Specialty Stores:Beauty retailers with trained staff provide education-intensive categories like multi-sensor facial mapping technology, reducing technician calibration time through hands-on demonstration.
- Department Stores:Premium positioning through established cosmetics counters leverages existing customer traffic for device upsell.
- Direct Sales:Professional device manufacturers maintain clinic relationships through field sales teams with photobiology expertise.
Volume leader: Online Retail. Fastest channel expansion: Specialty Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing clusters concentrate in Asian component supply bases while consumption gravity pulls toward metropolitan corridors in the United States and Canada. This production-consumption divide shapes logistics networks and regulatory compliance architectures across the trade corridor.
United States
California, Texas, and New York metropolitan corridors concentrate aesthetic service density and disposable income that accelerates early adoption velocity. FDA clearance pathways under 21 CFR Part 892 provide validated safety benchmarks that accelerate insurer reimbursement negotiations. Los Angeles and Dallas medical spa networks are deploying multi-sensor facial mapping technology to standardize outcomes across operator skill levels.
Canada
Ontario and British Columbia medical spa density lags United States metropolitan benchmarks, presenting whitespace for device placement and service network buildout. Health Canada and EPA joint standards on electromagnetic emissions and battery disposal add material cost layers and lifecycle design constraints. Toronto clinic operators are navigating tighter electromagnetic compatibility requirements through modular battery architectures that isolate emission sources.
Mexico
Cross-border manufacturing partnerships near Tijuana and Monterrey support component assembly for United States-bound device lines seeking tariff-advantaged production. COFEPRIS regulatory alignment with FDA standards facilitates streamlined market entry for cleared devices. Mexico City aesthetic service providers are expanding professional-grade laser adoption as disposable income rises in the metropolitan zone.
North America Beauty Devices Market Competitive Landscape
The competitive structure tilts toward specialized energy-based system manufacturers with deep photobiology expertise. Professional-grade laser and light-based platforms command premium pricing through recurring treatment protocols and higher per-session economics. Three archetypes dominate: silicone-engineered direct-to-consumer platform builders, professional dermatology equipment specialists, and mass-market retail distributors with broad channel penetration. Consolidation pressure operates through technology licensing agreements and strategic partnerships that bridge professional and at-home segments.
Within the professional equipment tier, Candela Corporation and Lumenis Be Ltd exemplify specialized laser and energy-based system builders. FOREO occupies a distinct position as a silicone-engineered platform developer targeting premium direct-to-consumer channels. Koninklijke Philips N.V. anchors mass-market penetration through established retail distribution networks across United States and Canadian consumer electronics channels.
| Leading Market Players |
|---|
| Nu Skin |
| Candela Corporation |
| Curallux LLC |
| FOREO |
| Koninklijke Philips N.V. |
| Conair Corporation |
| Lumenis Be Ltd |
| Cynosure |
| Sciton, Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal REACH compliance requirements gate qualified supply for device-compatible topicals and premium-tier pricing access, forcing North American manufacturers to reformulate ingredient sourcing or forfeit European export channels and domestic premium positioning.
Pricing Analysis
Per-treatment outcome metrics anchor value-based pricing across professional dermatology settings, with clinics in California and Texas commanding premium rates for FDA-cleared fractional laser protocols based on visible collagen remodeling results. Three-tier pricing structure across premium, standard, and economy levels separates prescription-strength professional systems from direct-to-consumer LED tools and mass-market facial cleansing devices. Cost compression in the at-home segment intensifies because Asian component manufacturers dominate diode laser optical supply, squeezing margins for hardware-only brands. Retail consumers purchasing through subscription models exhibit highest price sensitivity, while dermatology clinics demonstrate lowest sensitivity given insurance reimbursement and recurring patient revenue.
Supply Chain Analysis
Photonics engineering workforce availability in Taiwan, South Korea, and Japan concentrates specialized optical component manufacturing for laser and LED devices, limiting alternative sourcing for North American assemblers. Supply chains draw from gallium arsenide substrate suppliers, precision lens fabricators, and silicone polymer compounders for device housings. Single-source vulnerability in 755-1064 nm diode laser emitters creates procurement risk for hair removal device manufacturers dependent on Taiwanese foundry capacity. Distribution runs through direct-to-consumer platforms, dermatology equipment distributors, and retail electronics channels with diverging margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where FDA 510(k) clearance under 21 CFR Part 892 creates a barrier-to-entry moat that rewards compliant incumbents with insurer reimbursement access and professional segment pricing power.
For Market Incumbents: Deploy certification investment leverage to deepen Health Canada electromagnetic emissions compliance ahead of competitors, insulating premium positioning against regulatory friction. Candela Corporation and Lumenis Be Ltd demonstrate defensive consolidation through specialized photobiology expertise that emerging Asian manufacturers cannot replicate without multi-year FDA timeline investment. Capacity addition in Ontario and British Columbia medical spa networks counters state-level operator certification fragmentation in Texas and Florida. For New Entrants and Emerging Players: Launch via subscription-based device access models bundled with topical consumables, capturing millennial and Gen Z demographics in New York and Los Angeles metropolitan corridors where rental programs displace outright purchase patterns. Canadian provincial expansion presents the most penetrable geography given lagging medical spa density versus United States benchmarks. Direct-to-consumer platform partnerships offer the lowest customer acquisition cost angle for silicone-engineered facial cleansing platforms without professional certification burden. For Investors and Strategic Acquirers: FDA 510(k) clearance timeline compression for novel LED wavelengths is the leading indicator that at-home device commoditization is accelerating, shortening viable return windows for hardware-only investments. Acquisition targets should concentrate on vertically integrated mid-cap specialists with captive silicone polymer compounding and modular battery architecture capabilities. Photobiology technician recruitment friction signals professional clinic consolidation opportunity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Modality Platform Convergence | Integration of LED, microcurrent, and cleansing into single-form-factor devices captures premium direct-to-consumer positioning. |
| Canadian Provincial Expansion | Ontario and British Columbia medical spa network buildout addresses whitespace versus United States metropolitan benchmarks. |
| EU Green Deal Alignment | REACH-compliant ingredient sourcing for device-compatible topicals unlocks European export channels for North American manufacturers. |
| Subscription Access Model Deployment | Rental and lease programs bundled with consumables concentrate recurring revenue with platform operators in New York and Los Angeles. |
| Modular Battery Architecture Redesign | Health Canada electromagnetic emissions compliance through isolated power cell systems mitigates regulatory cost layers. |
Research Methodology
FDA 510(k) clearance databases, Health Canada medical device licenses, and EPA electromagnetic emissions filings formed the secondary backbone for regulatory pathway mapping and competitive positioning assessment. Primary interviews with dermatology clinic operators, medical spa franchise development executives, biomedical device procurement managers at hospital systems, and photonics component suppliers validated demand assumptions and supply chain concentration. Bottom-up and top-down triangulation reconciled unit shipment estimates from Asian optical component manufacturers with retail channel velocity data from United States and Canadian consumer electronics distributors.
Bottom-up modeling segmented volume and value outputs across product type, technology wavelength, end-user certification requirements, and distribution channel economics throughout the forecast period. CAGRs derived from historical FDA clearance velocity, metropolitan corridor aesthetic service density trends, and disposable income elasticity in California-Texas-New York clusters. Forecast inputs incorporated LED wavelength convergence adoption curves and subscription-based access model penetration rates among millennial and Gen Z demographics.
The model assumes a particular technology adoption path; alternative pathways for at-home fractional laser safety engineering would alter the outlook if FDA clearance timelines compress unexpectedly. Forecasts reflect assumptions regarding Health Canada-EPA regulatory alignment stability and Asian optical component supply continuity. Material deviation in electromagnetic emissions standard enforcement or diode laser foundry capacity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Organic Baby Shampoo Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
Depilatory Product Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Lip and Cheek Tint Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
South America E-Commerce Skin Care Products Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
US Sustainable Personal Care Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market