
 Personal Care Shower and Bath Market | 2026-2036
Personal Care Shower and Bath Market Size, Share, and Industry Trends Forecast 2026-2036
Personal Care Shower and Bath Market Intelligence
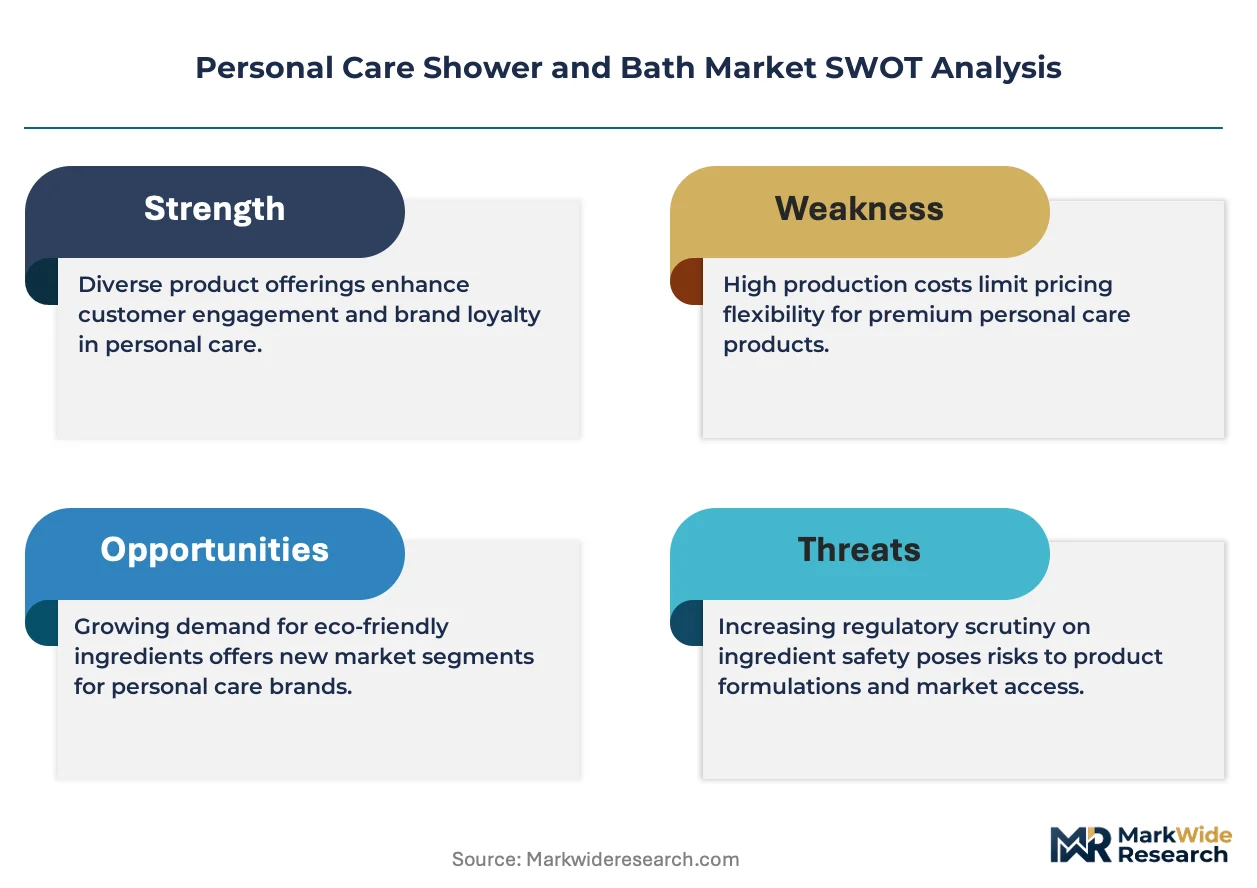
Divergent investment in sustainable ingredient sourcing and waterless formulation R&D is reorganizing the competitive landscape. Unilever leverages its extensive distribution network to maintain market presence across multiple price points. L'Oréal differentiates through premium brand positioning and innovation in specialized skincare-infused bath products. Procter & Gamble sustains its position through large-scale manufacturing and consistent marketing for its core brands.
Personal care shower and bath products encompass topical cleansing formulations designed for hygiene and skin maintenance. These products primarily utilize surfactants to remove dirt and oils, often combined with emollients and fragrances for an enhanced sensory experience. Shower gels continue to command the largest share by product type, though bath bombs show strong niche growth. Demand for organic and SLS-free formulations is driving margin expansion, while online stores are rapidly gaining share from traditional supermarkets.
Regulatory frameworks globally dictate product composition and labeling. In the United States, the FDA oversees cosmetic safety, while the EU's REACH regulation restricts certain chemical substances. China's NMPA enforces its own stringent pre-market approval standards for imported cosmetics. Success for brands now depends on managing a complex matrix of international ingredient regulations and consumer demand for transparency.
Market Dynamics
The central structural force shaping the market is the bifurcation of product development pathways. One path pursues mass-market scale via synthetic surfactant optimization, while the other targets premium niches with certified organic, water-conscious, and ethically sourced formulations.
Growth Catalysts
- Demand for Clean Formulations:Consumer preference for products free from sulfates, parabens, and phthalates, particularly among millennial and Gen Z demographics in North America and Europe, is stimulating demand for transparently labeled, minimalist ingredient lists.
- Sustainable Sourcing Mandates:The EU's Green Deal and associated corporate sustainability reporting directives are compelling brands to invest in traceable supply chains for botanicals like shea butter and essential oils, creating a premium for certified ingredients.
- E-commerce Channel Expansion:The rapid expansion of online retail platforms and social commerce in markets such as China and India provides a direct-to-consumer route for niche and emerging brands, bypassing traditional retail gatekeepers.
Market Restraints
- Raw Material Price Volatility:Prices for key natural inputs, such as coconut oil, palm oil derivatives, and essential oils, are subject to significant fluctuation based on climate events and agricultural yields, creating margin pressure for organic brands.
- Fragmented Regulatory Compliance:Navigating the divergent pre-market approval process of China's NMPA, the substance restrictions of the EU's REACH framework, and the FDA's post-market system in the US creates significant administrative and testing costs.
- Threat from Solid Formats:The rise of concentrated solid bars for shampoo and body wash presents a substitution threat to liquid gels and body washes, appealing to eco-conscious consumers and challenging established packaging and logistics models.
Strategic Opportunities
- Skincare-Infused Product Lines:The convergence of skincare and body care offers an opportunity to develop premium products incorporating active ingredients like hyaluronic acid, niacinamide, and prebiotics, targeting consumers seeking functional benefits beyond cleansing.
- Waterless and Concentrated Formulations:R&D into water-free or solid formats, such as powders and tablets that activate with water, opens new product categories that reduce packaging waste, lower shipping costs, and appeal to sustainability-focused consumers.
- Geographic Expansion in Southeast Asia:Rising disposable incomes and urbanization in countries like Vietnam, Indonesia, and the Philippines create significant white space for both mass-market and premium shower and bath products, representing a key growth frontier.
Industry Challenges
- Authenticating Sustainable Supply Chains:Verifying the ethical and environmental claims of raw material suppliers for botanical ingredients at scale remains a significant operational hurdle, exposing brands to risks of greenwashing accusations and supply disruptions.
- Managing Global Ingredient Dossiers:The complexity of maintaining and updating product ingredient documentation to comply with the distinct and evolving chemical safety databases of regulators like ECHA in Europe and the EPA in the US is a major challenge.
- Consumer Education on Formulation Science:Brands face the challenge of communicating the benefits and safety of scientifically formulated ingredients amidst widespread consumer misinformation and preference for "all-natural" products, which may lack efficacy or stability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personal Care Shower and Bath Market |
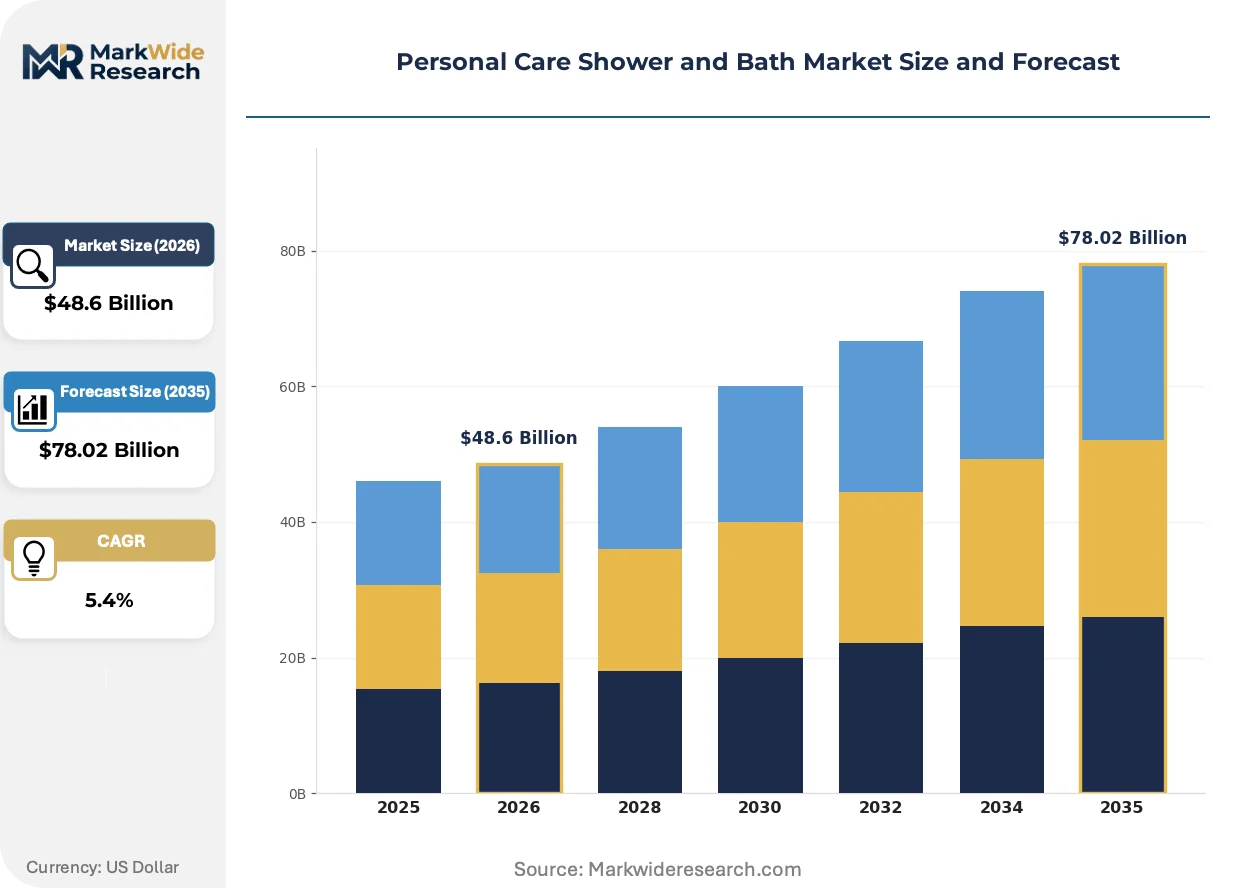
| Market Size in 2026 | $48.6 Billion |
| Market Size in 2035 | $78.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shower Gels, Bath Soaps, Shower Oils, Bath Bombs Formulation: Organic, SLS-Free, Moisturizing, Antibacterial Target Consumer: Men, Women, Children, Seniors Distribution Channel: Online Stores, Supermarkets, Specialty Shops, Salons |
| Companies Covered | Unilever, Procter & Gamble, L'Oréal, Henkel, Colgate-Palmolive, Johnson & Johnson, Beiersdorf AG, Natura & Co, Reckitt Benckiser Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personal Care Shower and Bath Market Strategic Shifts & Innovations
Product value is being redefined at the intersection of material science and sustainability ethics. The market is shifting from a focus on basic hygiene and fragrance to a more holistic approach encompassing skin health, environmental impact, and ingredient transparency.
Waterless or solid-state formulations are gaining traction as a key product innovation. These formats, including powder-to-foam cleansers and concentrated bars, are designed to eliminate water as a primary ingredient. Environmentally conscious consumers in urban centers are the earliest adopters, seeking to reduce their plastic waste and carbon footprint. This shift is decomposing the legacy logistics model built on shipping heavy, water-based liquids in single-use plastic containers.
Regulatory mandates for ingredient transparency are intensifying globally. Initiatives like the EU's push for a Digital Product Passport and stricter cosmetic labeling rules compel brands to provide granular data on product composition and sourcing. This forces investment in robust supply chain traceability systems, moving beyond simple compliance. The mass-market segment, which often relies on complex and less transparent supply chains, is most affected and must now adapt to new standards of disclosure.
A notable behavioral shift is the move from mass-produced products toward customized or personalized cleansing routines. This trend disrupts the traditional retail model of one-size-fits-all products by leveraging digital platforms for tailored recommendations. Direct-to-consumer brands are capitalizing on this by offering formulations based on quizzes about skin type, lifestyle, and scent preferences. This hyper-personalization is most advanced in digitally mature markets like South Korea and the United States.
Personal Care Shower and Bath Market Segmentation
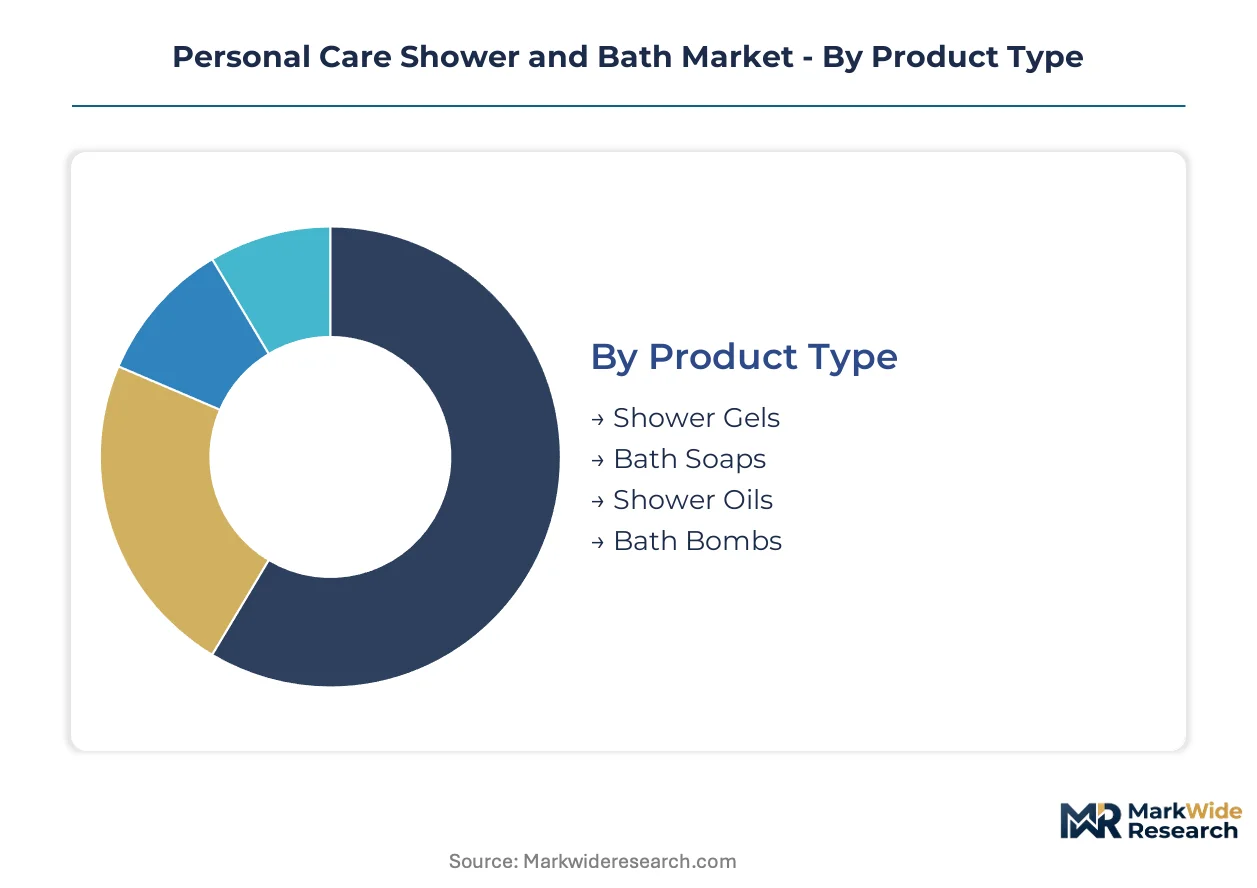
Segmentation provides a granular view of product preferences and purchasing behaviors within the personal care shower and bath market. Understanding these distinct segments helps brands tailor product development and marketing strategies. This detailed classification reveals where consumer needs are most acute and where competitive pressures are intensifying.
Product Type:
The product type category faces significant substitution pressure from alternative formats and evolving consumer preferences.
- Shower Gels:These viscous liquid formulations primarily utilize synthetic surfactants to cleanse the skin, often incorporating humectants and fragrances. Demand concentrates in urban centers across China and India, driven by convenience and a wide range of scent options.
- Bath Bombs:Effervescent spheres composed of baking soda, citric acid, and essential oils, designed to dissolve in bathwater for a sensory experience. Their niche demand is expanding rapidly in North America and Europe, appealing to consumers seeking indulgent, spa-like rituals and unique scents.
- Bath Soaps:Solid bars of saponified fats and oils, offering traditional cleansing with varying moisturizing properties.
- Shower Oils:Emollient-rich liquid cleansers that transform into a milky lather upon contact with water, providing hydration.
Shower Gels anchor the volume base while Bath Bombs gain share at the steepest rate.
Formulation:
Formulation types differentiate products across various price points and consumer value propositions.
- Organic:These formulations contain ingredients certified to be grown without synthetic pesticides, fertilizers, or GMOs, often commanding premium prices. Demand for organic personal care products is robust in Germany and France, influenced by strong consumer preference for natural ingredients and sustainability.
- SLS-Free:Products specifically formulated without Sodium Lauryl Sulfate (SLS), a common surfactant, often replaced by milder alternatives to reduce potential skin irritation. Consumer demand for SLS-free products is particularly high in the United States and the United Kingdom, driven by sensitive skin concerns.
- Moisturizing:Products enriched with emollients and humectants like glycerin or shea butter, designed to hydrate the skin during cleansing.
- Antibacterial:Formulations containing active agents such as triclosan or chloroxylenol, targeting germ reduction on the skin surface.
Organic formulations capture significant value, while moisturizing variants maintain a broad consumer appeal.
Target Consumer:
Target consumer segmentation defines specific product attributes and marketing approaches for distinct demographic groups.
- Women:This segment encompasses a broad range of products tailored for diverse skin types and aesthetic preferences, often emphasizing fragrance and skincare benefits. Demand is consistently high across all developed markets, including Japan and Canada, reflecting extensive product innovation.
- Children:Formulations designed for delicate skin, often hypoallergenic, tear-free, and featuring mild cleansers. The segment shows increasing innovation in playful packaging and natural ingredients, particularly in Italy and Spain, as parents prioritize gentle care.
- Men:Products often feature masculine fragrances and address specific concerns like post-shave irritation or oil control.
- Seniors:Formulations address mature skin needs, focusing on hydration, gentleness, and mild, often unscented, options.
The women's segment drives significant product diversification, while the children's segment responds to specialized care requirements.
Distribution Channel:
Distribution channels dictate consumer access and influence brand visibility across different retail environments.
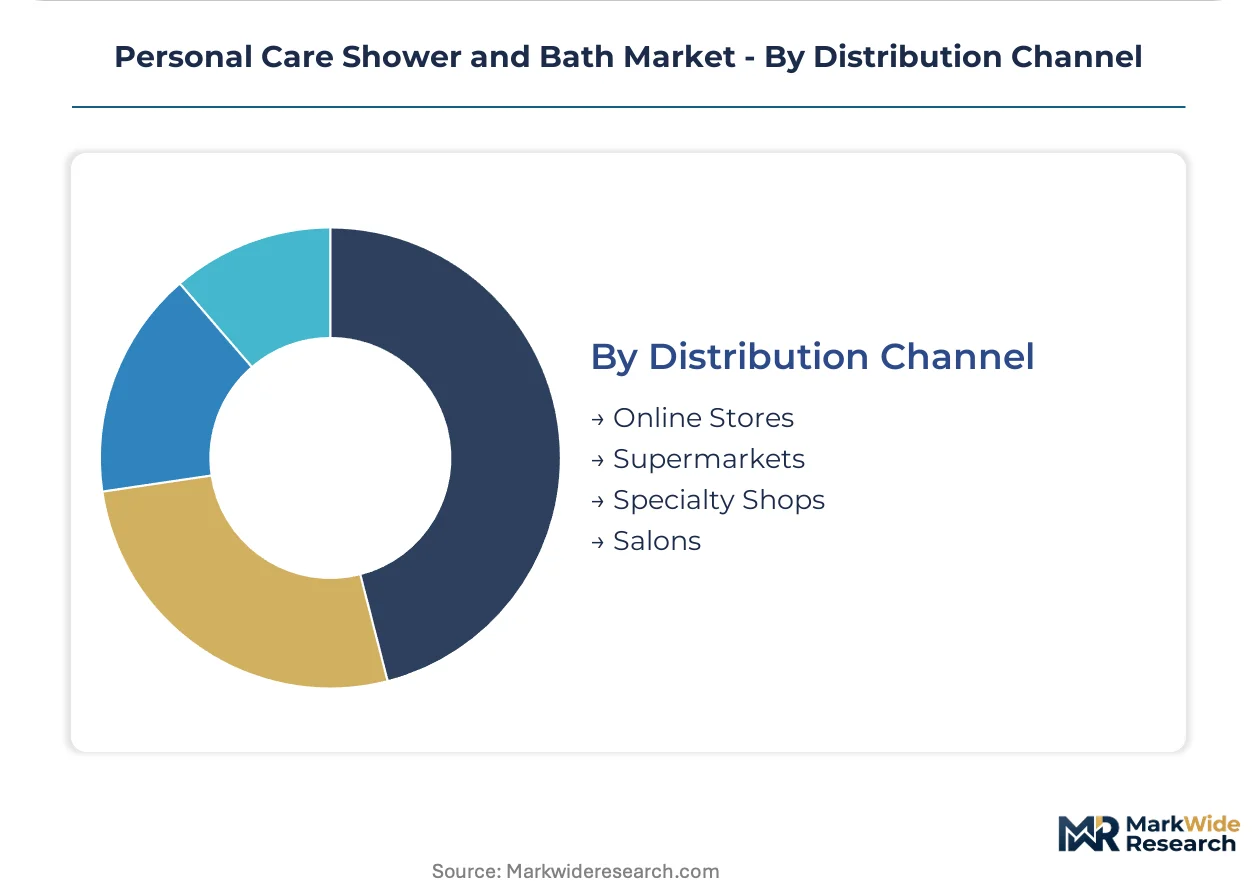
- Online Stores:E-commerce platforms provide direct-to-consumer access, offering extensive product ranges and personalized recommendations. This channel is expanding rapidly in China and India, driven by smartphone penetration and efficient logistics networks.
- Supermarkets:Large retail chains offering a wide selection of mass-market personal care products, emphasizing convenience and competitive pricing. Supermarkets remain a primary purchasing point in the United States and Germany, catering to routine household needs.
- Specialty Shops:Retail outlets focusing on niche or premium brands, providing curated selections and often personalized customer service.
- Salons:Professional establishments offering high-end or professional-grade products, often accompanied by expert advice and services.
Supermarkets maintain a substantial market share, but online stores are rapidly reshaping the competitive landscape.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption patterns for personal care shower and bath products vary significantly across different geographies, reflecting diverse cultural practices and economic development levels. While some regions prioritize basic hygiene and mass-market convenience, others exhibit a strong inclination towards premium, specialized, and sustainably sourced formulations. This differential consumption mix influences product development and market penetration strategies globally.
China
Demand for shower gels concentrates in urban centers across China, driven by convenience and diverse scent options. The NMPA enforces stringent pre-market approval standards for imported cosmetics, impacting market entry. Online stores in cities like Shanghai and Beijing are rapidly expanding, offering direct-to-consumer routes for niche brands.
United States
Consumer preference for SLS-free products is particularly high in the United States, driven by concerns for sensitive skin. The FDA oversees cosmetic safety post-market, guiding product formulation and labeling. Major retail hubs in New York and California remain primary purchasing points for routine household needs.
Germany
Robust demand for organic personal care products is evident in Germany, influenced by strong consumer preference for natural ingredients. The EU's REACH regulation restricts certain chemical substances, shaping ingredient choices for manufacturers. Brands in cities like Hamburg focus on transparently labeled, minimalist ingredient lists to meet local expectations.
India
The rapid expansion of online retail platforms in India provides a direct-to-consumer route for niche and emerging brands. Traditional supermarkets in cities such as Mumbai and Delhi remain significant purchasing points, catering to a broad consumer base. The country's regulatory bodies increasingly focus on product safety and labeling standards for mass-market offerings.
Japan
High demand for women's segment products is consistent across Japan, reflecting extensive product innovation. The Ministry of Health, Labour and Welfare (MHLW) regulates cosmetic ingredients and product claims. Companies in Tokyo prioritize specialized skincare-infused bath products, targeting consumers seeking functional benefits beyond cleansing.
Personal Care Shower and Bath Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the personal care shower and bath market. This structure creates a competitive environment where scale players coexist with agile, niche brands. Strategic archetypes include multinational conglomerates focused on mass-market penetration and specialized firms targeting premium, sustainable segments. Portfolio diversification and geographic expansion represent dominant competitive moves among larger entities.
On the premium-tier vector, L'Oréal exemplifies a strategy of brand differentiation through innovation in specialized skincare-infused bath products. Unilever, a multinational entity, represents a market presence maintained via extensive distribution networks across multiple price points. Procter & Gamble, another global player, sustains its position through large-scale manufacturing and consistent marketing for its core brands. These firms collectively demonstrate diverse approaches to capturing consumer demand across various segments, from basic hygiene to functional body care. Their operational scale allows for significant investment in research and development, influencing broader market trends and product cycles.
| Leading Market Players |
|---|
| Unilever |
| Procter & Gamble |
| L'Oréal |
| Henkel |
| Colgate-Palmolive |
| Johnson & Johnson |
| Beiersdorf AG |
| Natura & Co |
| Reckitt Benckiser Group |
| Others |
Cost & Logistics Intelligence
The shift from water-based liquid formulations to concentrated solid formats is simultaneously reshaping the logistics geography for personal care products and introducing new pricing tiers based on environmental value. This transformation impacts traditional supply chain economics.
Pricing Analysis
Premium product differentiation, driven by specialized skincare-infused formulations, drives consumer lifetime value through sustained brand loyalty and repeat purchases of higher-margin items. The market primarily operates on a tiered pricing structure across premium, standard, and economy levels. Brand premium and organic certification levels differentiate product pricing significantly. Raw material price volatility for natural inputs like essential oils creates margin pressure for organic brands. Mass-market consumers exhibit higher price sensitivity compared to those seeking specialized, certified organic formulations.
Supply Chain Analysis
Reliance on specific agricultural regions for botanical ingredients like shea butter and essential oils creates a chokepoint for certified organic formulations. Supply chains draw heavily from global sources for surfactants and emollients, with raw material sourcing for natural inputs often concentrated in regions susceptible to climate events. Commodity price volatility for inputs like coconut oil and palm oil derivatives presents a structural supply chain risk. Distribution runs through a dual model, with traditional supermarkets anchoring mass-market sales and online stores rapidly gaining share for niche and premium brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The personal care shower and bath market is undergoing a significant buyer-power shift, driven by the fragmentation of consumer preferences towards personalized cleansing routines. This shift empowers niche direct-to-consumer brands and redefines traditional retail dynamics.
For Market Incumbents:Consolidate brand portfolios by integrating sustainable and specialized formulations to counter the threat from solid formats and niche organic brands. Invest in R&D for waterless and concentrated products, leveraging existing large-scale manufacturing capabilities. Strengthen distribution networks, particularly online channels, to maintain presence across diverse consumer segments. Navigate fragmented international regulations by centralizing ingredient dossier management, mitigating compliance risks.
For New Entrants and Emerging Players:Hyper-personalization for specific skin types and lifestyle needs represents a service-layer gap where incumbents under-serve. Target digitally mature markets like South Korea and the United States with formulations based on quizzes and user preferences. Leverage e-commerce and social commerce platforms to establish a direct-to-consumer go-to-market angle. Focus on transparently labeled, minimalist ingredient lists to appeal to millennial and Gen Z demographics.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with niche direct-to-consumer brands focused on organic and waterless formulations, offering attractive acquisition opportunities. The long-term viability of the market is anchored in the convergence of skincare and body care, alongside sustained demand for sustainability-focused products. Identify agile D2C brands with strong online presence and certified clean formulations as prime acquisition targets. A signal to watch is the successful scaling and market acceptance of waterless or solid-format product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Brand Extension | Introduce premium skincare-infused bath products to capture higher margin consumer segments. |
| Distribution Channel Expansion | Prioritize online stores and social commerce platforms for direct consumer engagement. |
| Product Innovation | Develop waterless and concentrated formulations to meet eco-conscious consumer demand. |
| Supply Chain Certification | Invest in traceable supply chains for botanical ingredients to authenticate sustainability claims. |
| Strategic Partnership | Collaborate with dermatology experts for specialized skincare-infused product lines. |
Research Approach
A spread of perspectives from brand managers, procurement leads, regulatory affairs specialists, and retail buyers converged on the working assumptions underpinning this analysis. The methodology combined primary interviews with industry stakeholders and secondary validation from sources such as company reports, customs data, and regulatory filings from the FDA, ECHA, and NMPA. This approach ensured bottom-up and top-down triangulation across diverse data points.
Product type, formulation, target consumer, and distribution channel formed the core segmentation dimensions modeled across the analysis window. The analytical framework integrated historical trends with identified growth catalysts, including material science innovation for waterless formats. Compound Annual Growth Rates were derived from a synthesis of market dynamics and expert insights. Forecast inputs included evolving consumer preferences and raw material price trends.
Forecasts assume regulatory continuity in the EU's REACH framework, China's NMPA, and the US FDA; material policy shifts would require re-modeling. The analysis reflects assumptions regarding raw material availability and consumer demand patterns. Practitioners should keep alternative scenarios live as global trade policies and climate events evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Leave-In Conditioner Market
Beauty & Personal Care
Personal Care and Cosmetic Preservatives Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Sun Protection Spray Market
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
DIY Eyelash Extension Market
Beauty & Personal Care
Facial Care Products Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Bath Oil Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Beauty Fridge Market
Beauty & Personal Care
Anti-Dandruff Shampoo Market
Beauty & Personal Care
Asia-Pacific Hair Removal Wax Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Cosmetics Foundation Market