
 France Sustainable Personal Care Market | 2026-2036
France Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
France Sustainable Personal Care Market Insights
Aftermarket refill and repair services is reconfiguring margin pools away from virgin-product manufacturing toward circular consumption models. L'Oréal SA leverages its extensive R&D infrastructure to develop concentrated formulas that reduce water and packaging intensity. Pierre Fabre SA anchors its competitive position through dermatological credibility and provenance-controlled botanical supply chains. Yves Rocher SA controls one of France's largest vertically integrated plant cultivation networks, securing raw material traceability.
France sustainable personal care encompasses cosmetic and hygiene products formulated with renewable, minimally processed ingredients and packaged in recyclable, compostable, or reusable materials, typically excluding synthetic parabens, sulfates, and petroleum-derived compounds. The category serves consumers seeking reduced environmental toxicity across daily grooming rituals, with performance benchmarks including biodegradability exceeding 60 percent within 28 days and minimum 95 percent naturally derived content under ISO 16128 guidelines. Organic skincare commands the deepest margin pool due to certification premiums and pharmacy-channel positioning, while biodegradable packaging experiences the steepest growth trajectory as France's AGEC law mandates phased elimination of single-use plastic cosmetics containers. Natural haircare remains comparatively mature, though solid shampoo bars and refillable conditioners are gaining shelf space in specialty stores and health shops.
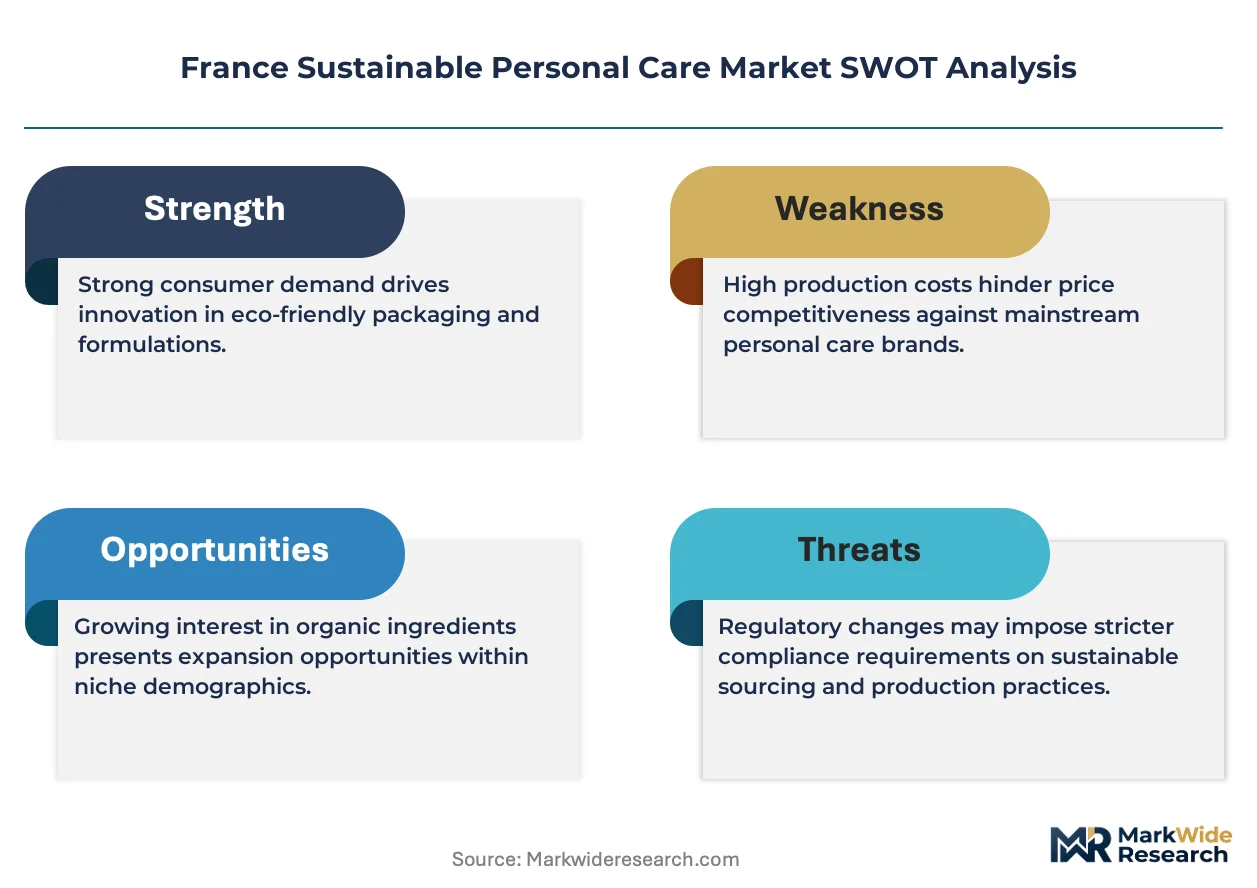
France's national environmental regulator enforces AGEC circular economy provisions that obligate producers to finance packaging collection and mandate recycled content minimums, directly elevating compliance costs for non-reformulated entrants. ECHA's REACH restrictions on microplastics in rinse-off products and the EU Green Deal's carbon border adjustments further tighten formulation and sourcing standards for goods circulating in French territory. Stakeholders must monitor pending revisions to the EU Cosmetics Regulation that could expand nanomaterial disclosure requirements and restrict additional preservative chemistries.
Market Dynamics
France's AGEC anti-waste law and tightening EU Green Deal packaging mandates are forcing reformulation across the entire value chain, compressing timelines for biodegradable material adoption and concentrated product development.
Growth Catalysts
- AGEC Compliance Deadlines:France's circular economy law mandates phased elimination of single-use plastic cosmetics containers, compelling brands to accelerate refillable format deployment.
- Paris-Lyon Urban Clusters:Millennial consumers in these metropolitan centers demonstrate disproportionate willingness to pay certification premiums for organic skincare with traceable provenance.
- Plant-Based Chemistry:Advances in enzymatic processing of locally cultivated botanicals is reducing dependency on imported petrochemical feedstocks.
Market Restraints
- Organic Certification Cost Structure:Bureau Veritas and ECOCERT audit fees for ISO 16128 compliance impose disproportionate burdens on sub-€10M revenue brands.
- Glass Supply Concentration:Refillable format adoption depends on concentrated Italian and Spanish glass packaging suppliers vulnerable to energy price volatility.
- Preservative Efficacy Limitations:Plant-derived antimicrobial systems demonstrate shorter shelf stability versus synthetic parabens, constraining distribution reach.
Strategic Opportunities
- Provence-Alpes-Côte d'Azur Cultivation Zones:Lavender and immortelle supply chains in this southern region offer untapped capacity for vertically integrated ingredient sourcing.
- Pharmacy Channel Expansion:Dermocosmetic positioning through French pharmacy networks commands margin premiums unavailable in mass retail.
- ECHA Microplastic Bans:Pending REACH restrictions on rinse-off microplastics create first-mover advantage for biodegradable exfoliant alternatives.
Industry Challenges
- Green Chemistry Talent Scarcity:Formulation chemists with dual expertise in natural product chemistry and regulatory compliance remain critically undersupplied in French labor markets.
- Packaging Reconfiguration Capex:Transitioning filling lines to accommodate concentrated solids and refillable formats demands capital outlays exceeding mid-tier brand liquidity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Sustainable Personal Care Market |
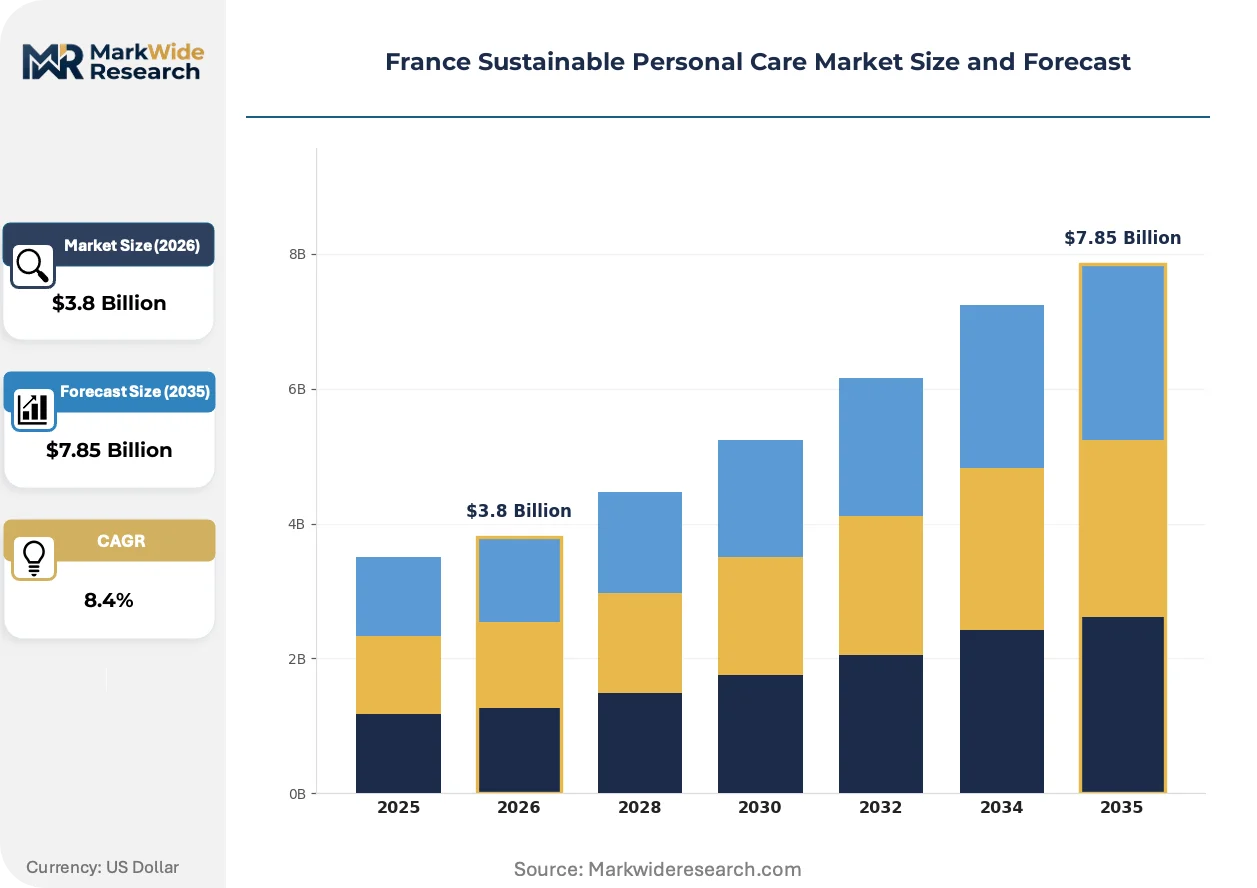
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Skincare, Biodegradable Packaging, Natural Haircare, Eco-Friendly Makeup Customer Type: Eco-Conscious Consumers, Luxury Shoppers, Millennials, Health-Aware Individuals Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Health Shops Ingredient Source: Plant-Based, Fair Trade, Locally Sourced, Sustainable Ingredients |
| Companies Covered | Laboratoires NAOS SAS, Pierre Fabre SA, L'Oréal SA, Henkel France SA, Beiersdorf France SA, Clarins SA, Yves Rocher SA, Aroma-Zone, Caudalie Sarl, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Sustainable Personal Care Market Trends and Innovations
Digital formulation platforms and AI-driven ingredient matching are compressing R&D cycles while regulatory disclosure requirements reshape transparency protocols across French personal care manufacturing.
Biotechnology-derived actives is virtualizing traditional botanical extraction methods. Fermentation-based production of squalane and hyaluronic acid precursors now dominates new product pipelines. Premium skincare brands in Paris and Lyon are adopting these bio-identical molecules at accelerated rates. This technology is virtualizing the competitive advantage of legacy vertically integrated cultivation networks.
ECHA's REACH microplastic restrictions and France's AGEC implementation decrees are converging to eliminate synthetic polymer beads from rinse-off cosmetics by enforced deadlines. Manufacturing facilities must validate biodegradability exceeding 60 percent within 28 days under OECD 301B testing protocols. Solid shampoo and powder concentrate segments are capturing disproportionate innovation investment as brands preempt compliance exposure.
Subscription-based refill programs are displacing conventional replenishment purchasing in urban French markets. Direct-to-consumer channels with scheduled delivery intervals are capturing pharmacy-adjacent consumers previously loyal to brick-and-mortar. This behavioral shift concentrates most visibly among millennial households in Île-de-France and Auvergne-Rhône-Alpes regions where logistics density supports viable unit economics.
France Sustainable Personal Care Market Segmentation
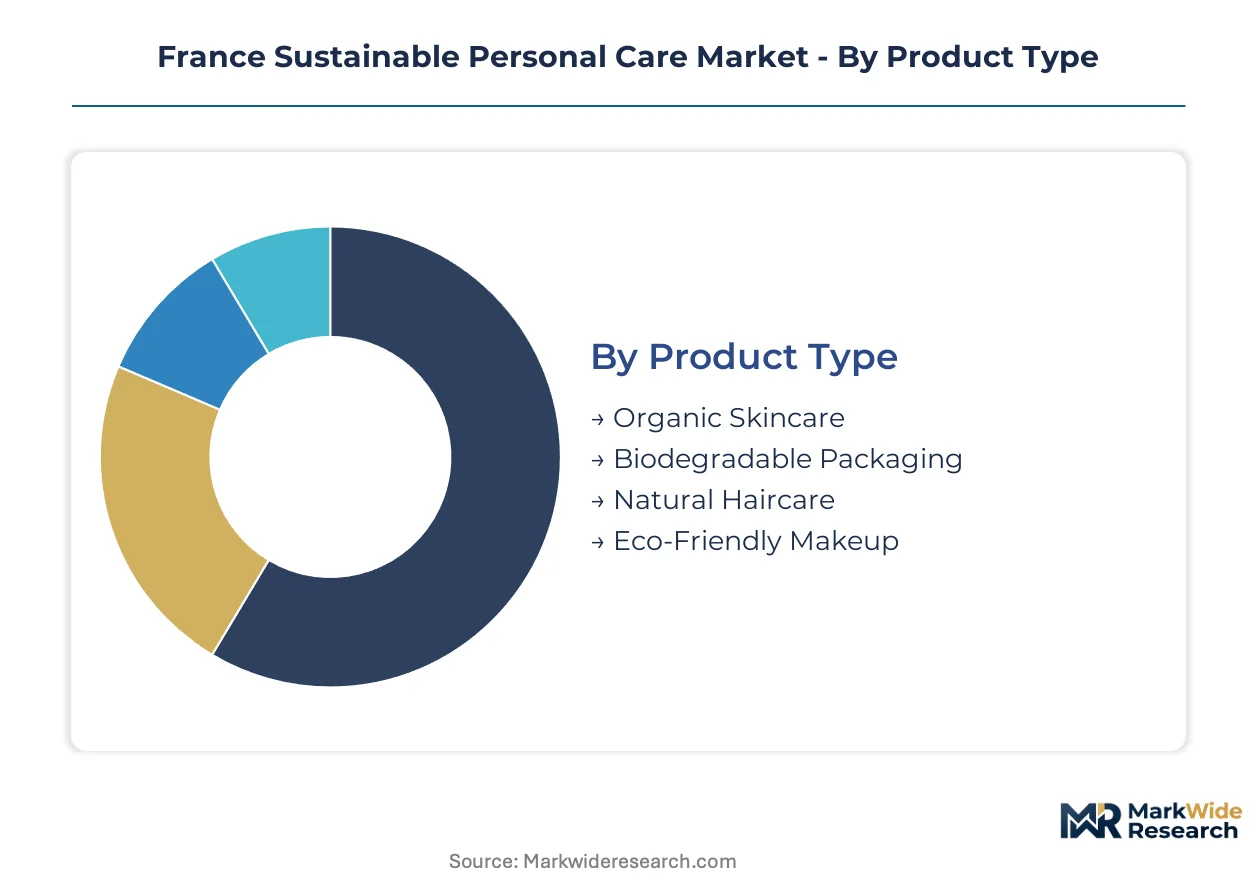
Segmentation in France's sustainable personal care market reveals how regulatory pressure and urban consumption clusters fragment demand across distinct value propositions. Each dimension exposes different margin pools and compliance burdens for brands navigating AGEC mandates and certification premiums.
Product Type:
Mature formats coexist with emerging technologies as brands balance proven revenue streams against reformulation investments.
- Organic Skincare:Formulations meeting ISO 16128 standards with minimum 95 percent naturally derived content command pharmacy-channel positioning. Certification premiums concentrate demand among millennial households in Paris and Lyon willing to pay traceability premiums for provenance-controlled botanicals.
- Biodegradable Packaging:Materials validated under OECD 301B protocols with 60 percent biodegradability within 28 days are capturing disproportionate innovation investment. AGEC law deadlines are accelerating adoption of refillable glass and compostable alternatives ahead of single-use plastic phaseouts.
- Natural Haircare:Solid shampoo bars and concentrated conditioners reduce water and packaging intensity. Shelf space expansion in specialty stores and health shops indicates format maturation.
- Eco-Friendly Makeup:Color cosmetics excluding petroleum-derived pigments and synthetic film-formers. Clean beauty positioning targets younger demographics seeking ingredient transparency.
Organic skincare handles the majority of throughput; biodegradable packaging is the fastest mover on share.
Customer Type:
Purchasing behavior stratifies across price sensitivity and information intensity, creating distinct channel and messaging requirements.
- Eco-Conscious Consumers:Systematic evaluators of lifecycle environmental impact across ingredient sourcing, manufacturing energy, and end-of-life disposal. Subscription refill programs capture this cohort's loyalty through scheduled replenishment.
- Luxury Shoppers:Premium positioning seekers who treat sustainability certification as a quality signal. Dermocosmetic pharmacy channels command their sustained spend.
- Millennials:Urban clusters in Île-de-France and Auvergne-Rhône-Alpes demonstrate highest willingness to adopt concentrated solids and zero-waste formats. Logistics density in these regions supports viable direct-to-consumer unit economics.
- Health-Aware Individuals:Consumers prioritizing dermatological safety and allergen avoidance. ECHA REACH restrictions on synthetic preservatives align with their formulation preferences.
Millennials drive volume expansion; eco-conscious consumers deliver the highest lifetime value through subscription retention.
Distribution Channel:
Channel economics are restructuring as refillable formats and concentrated products alter fulfillment infrastructure requirements.
- Online Retailers:Direct-to-consumer platforms with scheduled delivery intervals are displacing conventional replenishment purchasing. Digital-native brands leverage first-party data to personalize concentrated formula recommendations.
- Specialty Stores:Curated assortments of solid formats and refill stations provide tactile education for format-switching consumers. Staff expertise justifies location premiums in urban centers.
- Supermarkets:Mass retail access for certified organic basics with ECOCERT or COSMOS labeling. Price competition compresses margins for undifferentiated entrants.
- Health Shops:Independent retailers emphasizing local provenance and small-batch production. Community trust sustains premium pricing for regional botanical brands.
Online retailers capture the fastest share gains; specialty stores anchor margin preservation through service differentiation.
Ingredient Source:
Supply chain provenance is becoming a competitive differentiator as AGEC transparency requirements and carbon accounting reshape sourcing decisions.
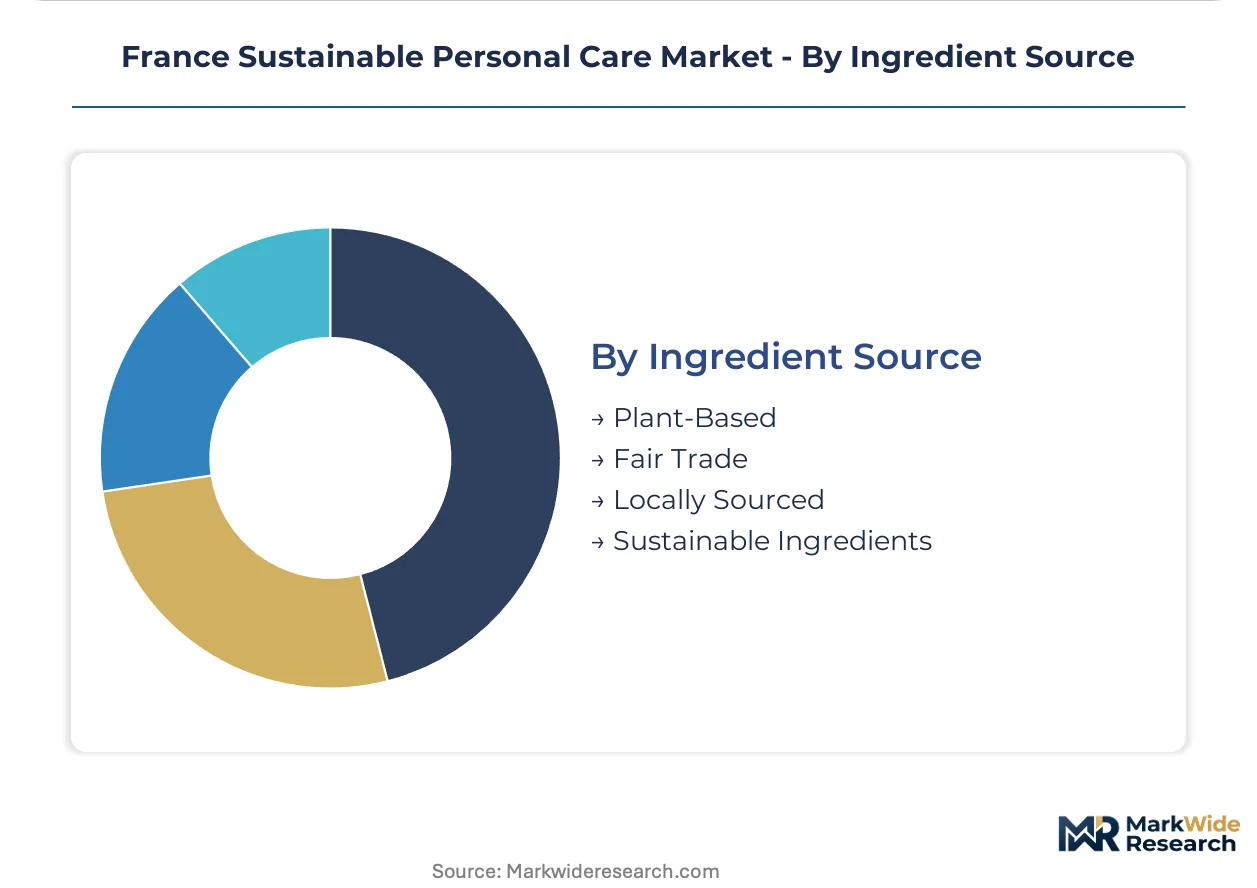
- Plant-Based:Enzymatic processing of domestically cultivated botanicals reduces petrochemical dependency. Lavender and immortelle from Provence-Alpes-Côte d'Azur cultivation zones offer untapped vertical integration potential.
- Fair Trade:Certified supply chains for shea, argan, and other imported botanicals meeting ethical labor standards. Premium positioning justifies cost premiums in conscious consumer segments.
- Locally Sourced:French-grown ingredients with traceable provenance within 300-kilometer radius. AGEC compliance advantages and reduced transport emissions support brand narratives.
- Sustainable Ingredients:Biotechnology-derived actives including fermentation-based squalane and hyaluronic acid precursors. Virtualized production methods challenge legacy cultivation network advantages.
Plant-based ingredients dominate current formulation volumes; biotechnology-derived actives are expanding most quickly as R&D cycles compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across French sub-regions. Urban consumers in Île-de-France absorb certification premiums with minimal price sensitivity, while price-conscious buyers in peripheral zones require mass-market entry points before upgrading to sustainable formats.
Île-de-France
Paris and its metropolitan ring concentrate the highest per-capita spending on organic skincare with traceable provenance. ANSM enforces strict nanomaterial disclosure requirements that elevate compliance costs for entrants. The capital's pharmacy networks and specialty boutiques anchor premium positioning for dermocosmetic brands.
Auvergne-Rhône-Alpes
Lyon's millennial households demonstrate disproportionate adoption of concentrated solids and zero-waste formats. The EU Green Deal's carbon border adjustments reshape sourcing decisions for brands distributing through this logistics hub. Grenoble's biotechnology cluster feeds fermentation-based active ingredient development for regional formulators.
Provence-Alpes-Côte d'Azur
Lavender and immortelle cultivation zones supply vertically integrated botanical networks with provenance-controlled raw materials. France's AGEC anti-waste law mandates phased elimination of single-use plastics, accelerating local packaging reconfiguration. Nice and Marseille serve as export gateways for provenance-branded regional producers.
Hauts-de-France
Price-sensitive mass-market demand concentrates in Lille and surrounding industrial cities where supermarket channels dominate sustainable personal care distribution. ECOCERT audit fees for ISO 16128 compliance impose disproportionate burdens on smaller regional brands. The sub-region's proximity to Belgian and Dutch logistics corridors supports cross-border e-commerce fulfillment.
Nouvelle-Aquitaine
Bordeaux and Biarritz anchor coastal demand for reef-safe formulations ahead of ECHA's REACH microplastic restrictions. The sub-region's wine industry expertise in fermentation science transfers to biotechnology-derived cosmetic active production. Local health shops emphasize small-batch production with community-trusted provenance narratives.
France Sustainable Personal Care Market Competitive Landscape
Multinational conglomerates and heritage French houses split the market between scale-driven R&D platforms and provenance-authenticated botanical positioning. Three archetypes dominate: vertically integrated cultivation networks controlling raw material traceability, dermatology-credentialed pharmacy-channel specialists, and digital-native refill platforms bypassing traditional retail. Competitive intensity centers on M&A activity to secure biotechnology capabilities and strategic partnerships to lock in glass packaging supply.
Within the heritage botanical tier, Yves Rocher SA exemplifies captive supply chain control through France's largest vertically integrated plant cultivation network. Pierre Fabre SA anchors dermatological credibility through pharmacy-channel positioning with provenance-controlled ingredient sourcing. L'Oréal SA represents concentrated R&D investment in water-reduced formulations and refillable format deployment. These three French-origin entities occupy distinct strategic positions without direct segment overlap.
| Leading Market Players |
|---|
| Laboratoires NAOS SAS |
| Pierre Fabre SA |
| L'Oréal SA |
| Henkel France SA |
| Beiersdorf France SA |
| Clarins SA |
| Yves Rocher SA |
| Aroma-Zone |
| Caudalie Sarl |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at Italian and Spanish glass packaging suppliers is elevating input costs for refillable format producers while compressing margin buffers for mid-tier French brands unable to pass through AGEC compliance investments.
Pricing Analysis
Aftermarket refill services and subscription renewals drive lifetime value for direct-to-consumer brands. Three-tier pricing structure across pharmacy-premium, specialty-store-mid, and mass-economy levels stratifies by certification grade and channel positioning. Pricing pressure stems from ECOCERT audit fees disproportionately burdening sub-€10M revenue brands. Mass retail buyers exhibit highest price sensitivity; pharmacy-channel consumers absorb certification premiums with minimal elasticity.
Supply Chain Analysis
Contract manufacturing for solid formats and concentrated products concentrates among Italian glass suppliers and Spanish packaging specialists. Raw material sourcing draws from Provence-Alpes-Côte d'Azur lavender cultivation, Italian glass foundries, and biotechnology fermentation facilities in Grenoble. Single-source vulnerability in glass supply creates exposure to energy price volatility. Distribution runs through pharmacy networks, specialty retail refill stations, and scheduled direct-to-consumer delivery intervals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemists with dual expertise in natural product chemistry and regulatory compliance remain critically undersupplied in French labor markets, constraining R&D velocity for brands navigating AGEC mandates.
For Market Incumbents: Entrench dermatological credibility through ANSM nanomaterial disclosure compliance and pharmacy-channel exclusivity. Lock in glass packaging supply through long-term offtake agreements with Italian and Spanish suppliers. Biotechnology-derived actives from Grenoble fermentation clusters threaten legacy botanical network advantages—invest in captive biotech capabilities or partnership structures. For New Entrants and Emerging Players: Mid-market health shops in Hauts-de-France and Nouvelle-Aquitaine represent the most penetrable entry point where ECOCERT audit burdens have cleared smaller competitors. Solid shampoo bars and powder concentrates in these price-sensitive sub-regions face limited incumbent presence. Launch through community-trusted provenance narratives emphasizing sub-300-kilometer ingredient sourcing. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refillable format manufacturing as filling line reconfiguration demands exceed mid-tier brand liquidity. Long-term viability favors vertically integrated cultivation networks with captive Provence-Alpes-Côte d'Azur botanical supply. Watch ECHA REACH microplastic restriction implementation timelines as inflection signal for biodegradable exfoliant alternative valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Refillable Format Deployment | AGEC compliance deadlines mandate accelerated single-use plastic phaseout across French cosmetics. |
| Biotechnology Active Investment | Fermentation-based squalane production from Grenoble clusters challenges legacy botanical extraction. |
| Pharmacy Channel Expansion | ANSM disclosure requirements elevate barrier to entry for dermocosmetic positioning. |
| Provence Cultivation Integration | Lavender and immortelle supply chains offer provenance-controlled raw material traceability. |
| Subscription Platform Launch | Scheduled delivery intervals capture millennial households in Île-de-France and Auvergne-Rhône-Alpes. |
Research Methodology
Initial hypotheses were tested against primary input from formulation chemists, pharmacy category buyers, packaging procurement leads, and regulatory affairs specialists and refined through secondary validation. Primary fieldwork combined structured interviews with supply chain directors at heritage botanical houses and digital-native refill platforms. Secondary sources included ANSM nanomaterial disclosure filings, ECOCERT certification databases, AGEC implementation decrees, and OECD 301B biodegradability test protocols. Bottom-up brand revenue estimates and top-down category sizing were triangulated against customs trade data.
Demand-supply balance modeling across the analysis window incorporated segmentation by product type, customer archetype, distribution channel, and ingredient source. CAGRs were derived from category growth rate reconciliation against macroeconomic consumption indicators. Forecast inputs included AGEC plastic phaseout timelines, ECHA REACH restriction schedules, and urban logistics density indices for subscription economics viability.
Practitioners should monitor ECHA microplastic restriction finalization, Italian glass supplier capacity utilization, and millennial subscription churn rates for early signals. Forecasts reflect assumptions on regulatory enforcement consistency and biotechnology cost curves. Quarterly review of ANSM disclosure requirement revisions and Provence cultivation yield data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Nail Salon Market
Beauty & Personal Care
US Personal Care Products Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Hair Removal Creams for Private Parts Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Global Bath Bomb Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Saudi Arabia Beauty and Personal Care Market
Beauty & Personal Care
China Antibacterial Soap Market