
 Glass Like Carbon Market | 2026-2036
Glass Like Carbon Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Like Carbon Market Foresight
REACH is decoupling European market access from legacy carbon processing methods, forcing suppliers to certify impurity thresholds below 50 ppm for biomedical-grade substrates. Tokai Carbon leverages captive pyrolysis capacity in Japan to sustain cost advantages on ultra-thin film supply. Morgan Advanced Materials anchors its position through specialized rods and blocks for mechanical seals in chemical processing. Schunk differentiates via integrated CVD systems that control deposition uniformity across wafer-scale formats.
Glass like carbon denotes a non-graphitizing carbon material with isotropic properties, zero gas permeability, and a glass-like fracture surface, produced through controlled pyrolysis of thermosetting resins at temperatures exceeding 1000°C. Its primary purpose centers on delivering dimensional stability and chemical inertness in semiconductor etching chambers, aerospace thermal protection layers, and implantable biomedical housings. Sheets and films command the largest volume share due to wafer-handling demand from semiconductor fabricators, while coatings produced through CVD and PVD routes capture the fastest growth trajectory as device miniaturization requires conformal barrier layers. Pyrolysis-derived rods and blocks retain entrenched positions in mechanical seal applications where bulk fracture resistance outweighs thin-film precision needs.
The EPA regulates particulate emissions from carbon pyrolysis furnaces under Clean Air Act provisions, while the FDA governs biocompatibility testing for implantable glass-like carbon components through ISO 10993-aligned pathways. ECHA's REACH authorization list continues restricting polycyclic aromatic hydrocarbon precursors, elevating compliance costs for European coating specialists. METI's material innovation roadmaps in Japan channel public-private funding toward next-generation CVD reactor designs. Stakeholders must weigh regional regulatory divergence against concentrated equipment supplier bases when siting new pyrolysis capacity.
Market Dynamics
Semiconductor fabricators are consolidating substrate specifications around ultra-thin glass-like carbon formats, forcing pyrolysis specialists to retool furnace configurations for wafer-scale uniformity rather than legacy rod and block geometries.
Growth Catalysts
- Semiconductor etching chamber demand:Fabricators in Japan and South Korea are specifying glass-like carbon susceptors for plasma etch uniformity, pulling volume from traditional graphite suppliers.
- REACH authorization thresholds:ECHA's tightened polycyclic aromatic hydrocarbon restrictions are disqualifying legacy carbon precursors, creating certified-supplier premiums for compliant pyrolysis houses.
- METI material roadmaps:Japan's public-private funding for CVD reactor development is accelerating domestic capacity for aerospace thermal protection layers.
Market Restraints
- Precursor resin cost volatility:Phenolic and polyfurfuryl alcohol feedstock prices fluctuate with benzene and agricultural commodity markets, compressing margins for non-integrated producers.
- Japan supply concentration:Tokai Carbon and two domestic competitors control over seventy percent of ultra-thin film capacity, creating single-source vulnerability for wafer-handling equipment OEMs.
- Non-graphitizing carbon limitation:Glass-like carbon cannot match synthetic graphite's thermal conductivity above 2000°C, restricting adoption in extreme-temperature furnace applications.
Strategic Opportunities
- India semiconductor fabs:Tata Electronics and ISMC Digital are qualifying glass-like carbon substrates for planned 28nm fabrication lines, opening import-substitution pathways for certified suppliers.
- Biomedical implant convergence:ISO 10993-aligned glass-like carbon housings for neurostimulators and cochlear implants are penetrating cardiac rhythm management device supply chains.
- US CHIPS Act incentives:Department of Commerce funding for domestic semiconductor materials is creating offtake guarantees for pyrolysis capacity sited near Arizona and Texas fabrication clusters.
Industry Challenges
- Pyrolysis furnace operator scarcity:Temperature profile control for isotropic carbon formation requires decade-long apprenticeship pipelines that Japanese suppliers have not replicated abroad.
- Biocompatibility certification timelines:FDA 510(k) pathways for implantable glass-like carbon components extend eighteen to thirty-six months, freezing working capital for biomedical-grade production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Like Carbon Market |
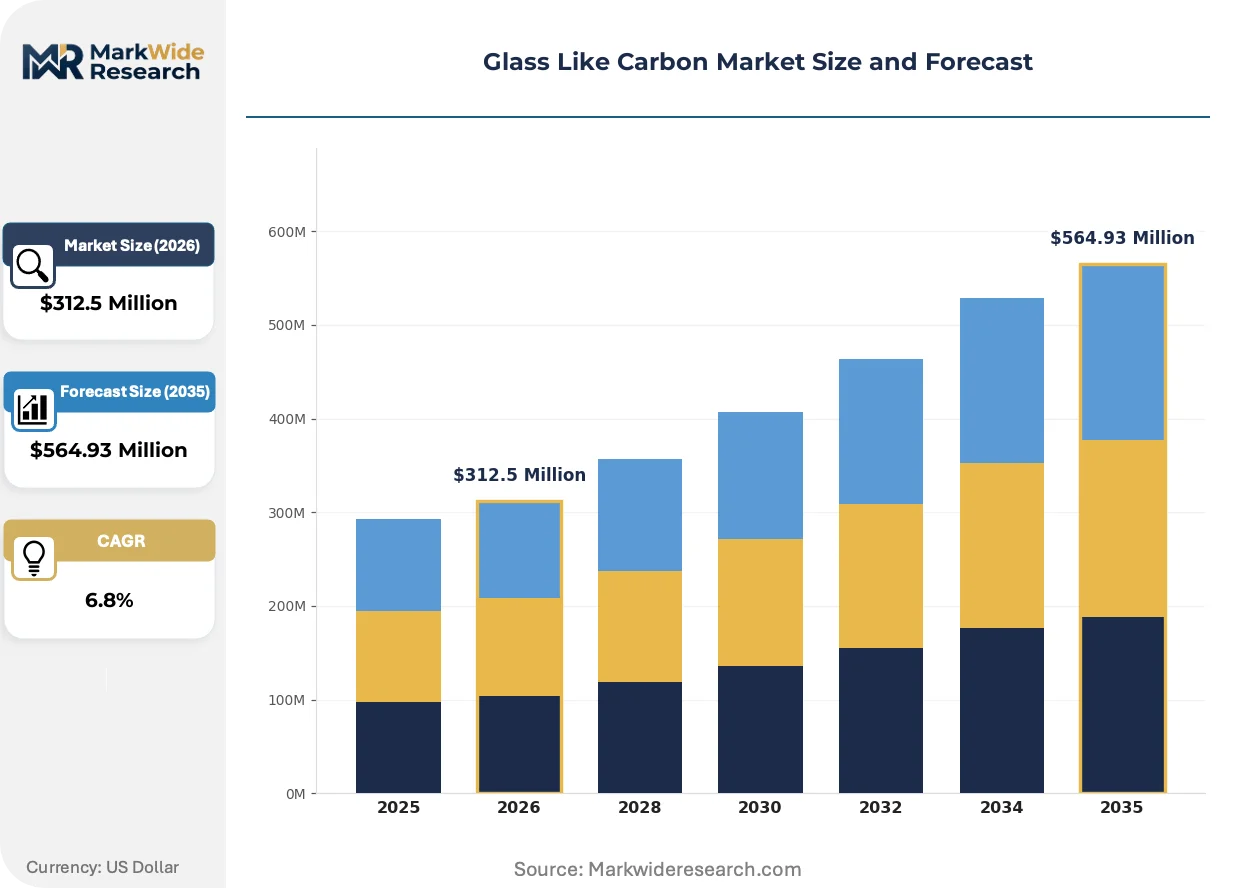
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
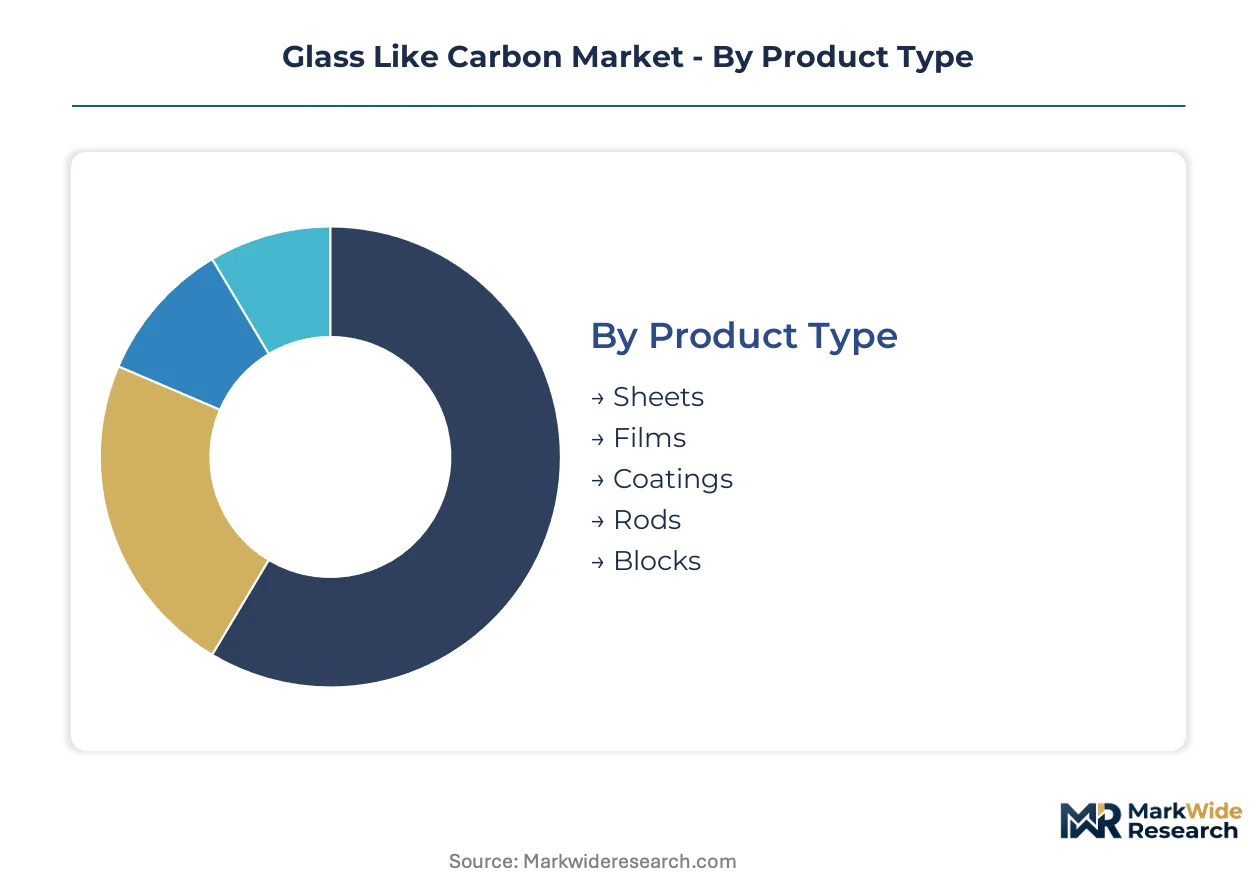
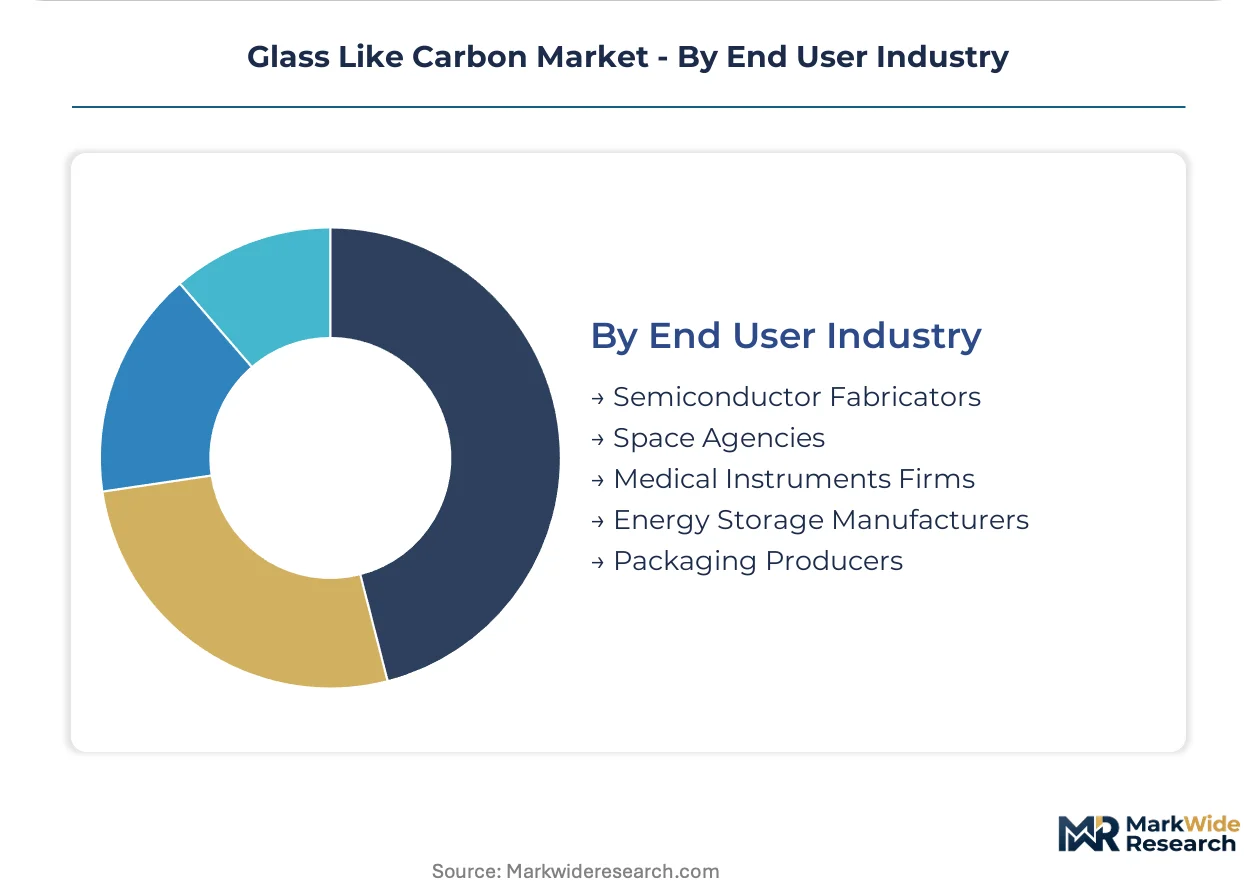
| Segmentation | Product Type: Sheets, Films, Coatings, Rods, Blocks Technology: CVD, PVD, Pyrolysis, Sputtering, Sol-Gel Application: Electronics, Aerospace Components, Biomedical Devices, Electrochemical Sensors, Mechanical Seals End User Industry: Semiconductor Fabricators, Space Agencies, Medical Instruments Firms, Energy Storage Manufacturers, Packaging Producers |
| Companies Covered | Tokai Carbon, Merck KGaA, ALS Co., Ltd, Bioanalytical Systems, Inc., SGL Group, Toyo Tanso, Schunk, Morgan Advanced Materials, HTW Hochtemperatur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Like Carbon Market Shifts & Advancements
Wafer-scale CVD deposition is compressing the addressable market for bulk pyrolysis formats while opening conformal coating opportunities for device miniaturization. Three developments are restructuring competitive positioning.
Atmospheric-pressure plasma-enhanced CVD is decentralizing barrier-layer production from centralized furnace operations to on-site semiconductor tool integration. Equipment OEMs in Japan are embedding compact carbon deposition modules directly into etch chamber retrofits. This distributed architecture is collapsing the traditional separation between substrate supplier and tool manufacturer.
EPA Clean Air Act enforcement against pyrolysis furnace particulate emissions is forcing US-based producers to install regenerative thermal oxidizers or relocate capacity to jurisdictions with less stringent MEE oversight. The compliance burden falls heaviest on rod and block specialists serving mechanical seal markets, who lack the volume to amortize abatement capital.
Semiconductor fabricators are consolidating supplier bases around certified-threshold material purity, displacing spot-market procurement with multi-year offtake agreements tied to specific impurity specifications. This specification-driven consolidation is visible most acutely in Japan, where Tokyo Electron and Shin-Etsu Chemical have reduced qualified glass-like carbon vendors from twelve to four since 2022.
Glass Like Carbon Market Segmentation
Glass like carbon's heterogeneous demand profile spans precision semiconductor handling, implantable medical housings, and extreme-environment aerospace protection. Segmentation reveals how fabrication technology and dimensional format jointly determine addressable end-use economics.
Product Type:
Customization intensity varies sharply across this category, from commodity bulk formats to wafer-scale precision substrates demanding sub-micron thickness tolerances.
- Sheets:Planar substrates ranging from 0.1mm to 5mm thickness serve semiconductor wafer-handling applications where dimensional stability under thermal cycling is critical. Demand concentrates in Japan and South Korea, where Tokyo Electron and Shin-Etsu Chemical have consolidated qualified supplier bases from twelve vendors to four.
- Films:Ultra-thin formats below 100 micrometers enable conformal barrier layers for plasma etch chambers. Tokai Carbon leverages captive pyrolysis capacity to sustain cost advantages on ultra-thin supply, though Japan's three-firm concentration creates single-source vulnerability for equipment OEMs.
- Coatings:CVD and PVD-deposited layers achieve conformal coverage on complex geometries for device miniaturization.
- Rods:Cylindrical stock for mechanical seals and electrochemical electrodes prioritizes bulk fracture resistance.
- Blocks:Machined billets for custom fabrications retain entrenched positions in chemical processing seals.
Leading the category by volume: Sheets. Growing fastest: Coatings.
Technology:
Cost tiers separate high-capital CVD systems from furnace-based pyrolysis, with deposition uniformity commanding premium pricing in semiconductor-qualified supply chains.
- CVD:Chemical vapor deposition controls carbon layer thickness uniformity across wafer-scale formats, enabling conformal barrier specifications for sub-7nm device nodes. Schunk differentiates via integrated CVD systems that meet semiconductor fabricator impurity thresholds below 50 ppm.
- Pyrolysis:Controlled thermal decomposition of phenolic and polyfurfuryl alcohol precursors at temperatures exceeding 1000°C produces isotropic glass-like carbon with zero gas permeability. Temperature profile control requires decade-long apprenticeship pipelines that Japanese suppliers have not replicated abroad.
- PVD:Physical vapor deposition offers lower-temperature processing for temperature-sensitive substrates.
- Sputtering:Ion-assisted deposition achieves dense carbon films for electrochemical sensor electrodes.
- Sol-Gel:Solution-based processing enables low-volume biomedical prototyping with shorter qualification timelines.
Highest volume throughput: Pyrolysis. Steepest expansion trajectory: CVD.
Application:
Application maturity separates established aerospace thermal protection from emerging biomedical implant convergence.
- Electronics:Semiconductor etching chamber susceptors and wafer-handling components demand plasma resistance and minimal particulate generation. Fabricators in Japan and South Korea are specifying glass-like carbon for plasma etch uniformity, pulling volume from traditional graphite suppliers.
- Biomedical Devices:Implantable housings for neurostimulators and cochlear implants require ISO 10993-aligned biocompatibility certification. FDA 510(k) pathways extend eighteen to thirty-six months, freezing working capital for biomedical-grade production runs.
- Aerospace Components:Thermal protection layers for re-entry vehicles and propulsion systems leverage METI-backed carbon material programs in Japan.
- Electrochemical Sensors:Inert electrode substrates for analytical chemistry and environmental monitoring.
- Mechanical Seals:Chemical processing equipment relies on bulk fracture resistance where dimensional precision is secondary.
Dominant by revenue: Electronics. Gaining share fastest: Biomedical Devices.
End User Industry:
Customer concentration creates divergent procurement patterns, from multi-year offtake agreements with semiconductor fabricators to project-based space agency contracts.
- Semiconductor Fabricators:Consolidating substrate specifications around ultra-thin formats, these buyers force pyrolysis specialists to retool furnace configurations for wafer-scale uniformity. US CHIPS Act Department of Commerce funding creates offtake guarantees for capacity sited near Arizona and Texas fabrication clusters.
- Space Agencies:Thermal protection procurement for re-entry vehicles and satellite propulsion operates on extended development timelines with rigorous qualification protocols.
- Medical Instruments Firms:Cardiac rhythm management device manufacturers are penetrating supply chains with ISO 10993-aligned glass-like carbon housings.
- Energy Storage Manufacturers:Electrochemical cell developers evaluate glass-like carbon current collectors for lithium-metal battery architectures.
- Packaging Producers:Barrier coating applications for pharmaceutical and electronics packaging explore atmospheric-pressure plasma-enhanced CVD integration.
Largest procurement volume: Semiconductor Fabricators. Fastest qualification activity: Medical Instruments Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI-backed industrial zones concentrate glass-like carbon capacity, with Yokohama-Kawasaki corridor housing specialized pyrolysis operations serving semiconductor equipment manufacturers.
Japan
Tokyo Electron and Shin-Etsu Chemical have consolidated qualified substrate vendors from twelve to four since 2022, tightening procurement around certified-threshold purity. METI's material innovation roadmaps channel public-private funding toward next-generation CVD reactor designs. The Kanto region around Tokyo anchors domestic supply chains for aerospace thermal protection layers.
United States
Department of Commerce CHIPS Act funding creates offtake guarantees for pyrolysis capacity sited near Arizona and Texas fabrication clusters. EPA Clean Air Act enforcement forces domestic producers to install regenerative thermal oxidizers or relocate capacity. Phoenix and Austin metro areas host emerging substrate qualification programs for 28nm fabrication lines.
Germany
ECHA's REACH authorization list restricts polycyclic aromatic hydrocarbon precursors, elevating compliance costs for European coating specialists. The country's national materials regulator enforces impurity thresholds below 50 ppm for biomedical-grade substrates. Bavaria's industrial corridor sustains specialized rod and block production for chemical processing mechanical seals.
South Korea
Fabricators specify glass-like carbon susceptors for plasma etch uniformity, pulling volume from traditional graphite suppliers. The national semiconductor regulator aligns with ISO standards for chamber component certification. Seoul-Incheon manufacturing belt hosts qualification programs for ultra-thin film formats in sub-7nm device nodes.
India
Tata Electronics and ISMC Digital qualify glass-like carbon substrates for planned 28nm fabrication lines, opening import-substitution pathways. The Bureau of Indian Standards develops domestic certification frameworks for semiconductor materials. Gujarat's Dholera special investment region attracts pyrolysis capacity proposals from certified international suppliers.
Glass Like Carbon Market Competitive Landscape
Japanese producers anchor one tier; German specialists hold differentiated positions in mechanical seal applications. The vendor base concentrates around three domestic Japanese firms controlling over seventy percent of ultra-thin film capacity, creating single-source vulnerability for equipment OEMs. Two strategic archetypes dominate: integrated pyrolysis operators with captive resin supply, and CVD system integrators targeting wafer-scale uniformity. Competitive moves center on furnace reconfiguration for wafer-scale formats and multi-year offtake agreements tied to specific impurity specifications.
Among Japan-based fabricators, Tokai Carbon exemplifies the integrated pyrolysis archetype through captive capacity advantages. Toyo Tanso occupies a position within the same geographic tier. Morgan Advanced Materials represents European specialization in bulk mechanical formats. Schunk anchors German CVD system integration capabilities.
| Leading Market Players |
|---|
| Tokai Carbon |
| Merck KGaA |
| ALS Co., Ltd |
| Bioanalytical Systems, Inc. |
| SGL Group |
| Toyo Tanso |
| Schunk |
| Morgan Advanced Materials |
| HTW Hochtemperatur |
| Others |
Supply & Pricing Matrix
EPA Clean Air Act enforcement gates both qualified supply and premium-tier pricing access, as regenerative thermal oxidizer mandates disqualify non-compliant pyrolysis operators from semiconductor-qualified supply chains while elevating certified-threshold material premiums.
Pricing Analysis
Short lead-time premiums of 15-25 percent separate multi-year offtake agreements from spot procurement, with contract-based long-term commitments dominating semiconductor fabricator procurement. Price differentiation hinges on impurity certification grade below 50 ppm and captive pyrolysis integration status. Cost compression in rod and block formats intensifies as mechanical seal buyers lack volume to amortize abatement capital. Medical instrument firms exhibit highest price sensitivity due to eighteen-to-thirty-six-month FDA 510(k) timelines freezing working capital.
Supply Chain Analysis
Dual-sourcing requirements from Tokyo Electron and Shin-Etsu Chemical mandate multi-supplier qualification, yet Japan, South Korea, and Germany anchor over eighty percent of certified capacity. Phenolic resin and polyfurfuryl alcohol precursors draw from benzene and agricultural commodity markets, creating feedstock cost volatility. Single-source vulnerability concentrates in ultra-thin film supply where Tokai Carbon and two domestic competitors control dominant share. Distribution runs through direct mill relationships with semiconductor equipment OEMs and specialized distributors serving biomedical and aerospace qualified programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wafer-scale CVD deposition is displacing bulk pyrolysis formats, creating transition-phase winners among integrated deposition system suppliers and losers among legacy furnace operators unable to retool for conformal barrier specifications.
For Market Incumbents: Acquire captive resin pyrolysis capacity to defend margin position against phenolic feedstock volatility and REACH-compliant precursor shortages. Consolidate around multi-year offtake agreements tied to specific impurity thresholds below 50 ppm, displacing spot-market exposure. Retool furnace configurations for wafer-scale uniformity rather than legacy rod and block geometries to match semiconductor fabricator substrate consolidation. For New Entrants and Emerging Players: Atmospheric-pressure plasma-enhanced CVD equipment integration offers a technology-first wedge into on-site semiconductor tool retrofit markets, bypassing centralized furnace competition. Target India's 28nm fabrication qualification programs through Bureau of Indian Standards certification pathways. Pursue biomedical implant convergence via ISO 10993-aligned sol-gel prototyping with shorter qualification timelines than pyrolysis routes. For Investors and Strategic Acquirers: METI public-private funding announcements for next-generation CVD reactor designs are the leading indicator that Japanese domestic capacity expansion will accelerate, shifting competitive positioning toward equipment-integrated deposition architectures. Five-to-ten-year viability favors backward-integrated pyrolysis operators with captive resin supply and certified-threshold purity capabilities. Watch for EPA enforcement actions against particulate emissions as the signal for US-based capacity relocation or consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenolic Resin Supply | Captive precursor production insulates margins from benzene commodity volatility and REACH authorization restrictions. |
| Wafer-Scale CVD Reactor Development | METI-funded designs enable conformal barrier specifications for sub-7nm device nodes at Tokyo Electron. |
| Multi-Year Offtake Agreement Structuring | Shin-Etsu Chemical consolidation from twelve to four vendors rewards certified-threshold purity with volume guarantees. |
| Biomedical-Grade ISO 10993 Certification Investment | FDA 510(k) pathway completion unlocks cardiac rhythm management device supply chain penetration. |
| Regenerative Thermal Oxidizer Installation | EPA Clean Air Act compliance sustains US pyrolysis capacity access against relocation pressures. |
Research Methodology
SEC 10-K filings, customs and trade databases, and Japan Carbon Society technical publications formed the secondary backbone, supplemented by primary interviews with pyrolysis furnace operators, semiconductor equipment procurement managers, biomedical device regulatory affairs leads, and aerospace thermal protection materials engineers. Bottom-up triangulation across resin precursor cost structures, furnace capacity utilization, and wafer-handling equipment demand combined with top-down validation against METI material roadmaps and EPA enforcement disclosures.
Historical trendline analysis of pyrolysis capacity expansion, CVD equipment shipments, and semiconductor fabrication buildouts established baseline growth patterns across the projection horizon. Segmentation modeling incorporated product type dimensional formats, deposition technology cost tiers, application maturity stages, and end-user industry procurement concentration. CAGRs derived from elasticity-adjusted demand curves for etching chamber susceptors, thermal protection layers, and implantable biomedical housings.
Several conditions sit outside the modeled scope, including unannounced regulatory threshold revisions, breakthrough synthetic graphite formulations above 2000°C, and geopolitical trade restrictions on carbon precursor flows. Forecasts reflect documented assumptions regarding apprenticeship pipeline replication timelines and biomedical certification completion rates. Deviation in EPA enforcement intensity or METI funding disbursement schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Birefringent Crystals Market
Glass
Glass Reactors Market
Glass
Double Glazing Glass Market
Glass
East Africa Flat Glass Market
Glass
Latin America Flat Glass Market
Glass
Global Glass Tempering System Market
Glass
North America Architectural Flat Glass Market
Glass
France Silica Sand Market
Glass
Coated Solar Control Glass Market
Glass
Pharma Glass Tubing Market
Glass
Glazing Gel Market
Glass
Low-E Glass Market
Glass
Europe Glassware Market
Glass
Global Energy Efficient Glass Market
Glass
Glass Prepreg Market
Glass
Asia-Pacific Fiberglass Window Market