
 Glazing Gel Market | 2026-2036
Glazing Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Glazing Gel Market Analysis
European hydrocolloid supply is hardening as specialty ingredient producers expand capacity for food-grade glazing systems. Cargill, Inc. leverages its corn-derived starch portfolio to dominate water-based gel formulations for industrial bakeries. Kerry Group sustains competitive positioning through integrated flavor-glazing R&D platforms across multiple European processing hubs. Mantrose-Haeuser Co., Inc. anchors the North American market with shellac-based confectionery coatings that meet kosher and halher certification requirements.
Glazing gel denotes a viscous, transparent or semi-transparent coating compound formulated from hydrocolloids, gums, oils, or resin bases, typically applied at temperatures between 35°C and 80°C depending on substrate sensitivity, to impart gloss, moisture retention, or protective sealing. Its primary commercial purpose spans food decoration, cosmetic finishing, and industrial surface protection where visual appeal and barrier functionality converge. Water-based gel formulations command the largest volume share among product types due to clean-label alignment and reduced regulatory burden in food applications, while hybrid gels represent the fastest-expanding category as manufacturers blend synthetic and natural hydrocolloids to optimize cost-performance ratios. Food decoration applications generate the deepest margin pools among end uses, driven by premium confectionery and artisan bakery demand for mirror-finish aesthetics.
EMA food-contact guidelines, REACH substance restrictions, and FDA GRAS determinations collectively shape formulation choices, labeling obligations, and cross-border market access for glazing gel producers. ECHA's evolving restrictions on microplastics and persistent organic compounds directly impact oil-based and solvent-based gel segments, accelerating reformulation investments toward biodegradable alternatives. Stakeholders must monitor regulatory divergence between EU hazard-based frameworks and US risk-based assessments when designing unified product platforms for multinational deployment.
Market Dynamics
Clean-label mandates from ECHA and FDA are forcing wholesale reformulation of hydrocolloid-based coatings, as synthetic glazing agents face phased restrictions across major food-contact jurisdictions. This regulatory compression is redrawing competitive advantage toward suppliers with integrated natural ingredient sourcing and certified biopolymer capabilities.
Growth Catalysts
- REACH substance restrictions:European formulators are accelerating migration from shellac and petroleum-derived coatings to plant-based hydrocolloids ahead of 2026 microplastic prohibitions, creating replacement demand across confectionery applications.
- Artisan bakery segment:Mirror-finish aesthetics for premium pastries and entremets are driving specification of high-clarity water-based gels in professional kitchen supply channels.
- Edible film technology:Integration of pullulan and alginate matrices into multilayer glazing systems is extending shelf-life performance for fresh-cut fruit processors in North American retail.
Market Restraints
- Carrageenan supply concentration:Philippine and Indonesian seaweed harvest disruptions transmit directly to gel viscosity consistency, forcing European manufacturers to maintain six-month strategic inventories.
- Technical limitation:Water-based formulations fail to achieve equivalent moisture barrier performance of solvent-based shellac at humidity levels above 75%, restricting deployment in tropical climate distribution.
- Substitution threat:Cocoa butter-based enrobing systems are recapturing share in premium chocolate confectionery where mouthfeel differentiation outweighs cost premiums.
Strategic Opportunities
- Underpenetrated geography:Brazilian and Mexican bakery cooperatives represent unserved demand for kosher-certified glazing systems as domestic halal and kosher certification infrastructure matures.
- Regulatory tailwind:EU Green Deal bioeconomy funding streams are subsidizing pilot-scale production of bacterial cellulose-derived glazing films for pharmaceutical tablet coating applications.
- Technology convergence:Combination of cold-plasma surface activation with nano-cellulose deposition is enabling solvent-free gel adhesion to hydrophobic substrates previously requiring synthetic primers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hydrocolloid rheology and food-grade polymer science commands premium compensation, constraining R&D throughput at mid-tier producers.
- Certification timeline:GRAS self-determination pathways for novel plant-derived gums require 18-24 month toxicological documentation cycles, delaying commercialization of acacia-senegal alternatives.
- Integration complexity:Legacy spray-application equipment at industrial bakeries requires retrofitting for temperature-sensitive water-based gel viscosity profiles, generating capital allocation conflicts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glazing Gel Market |
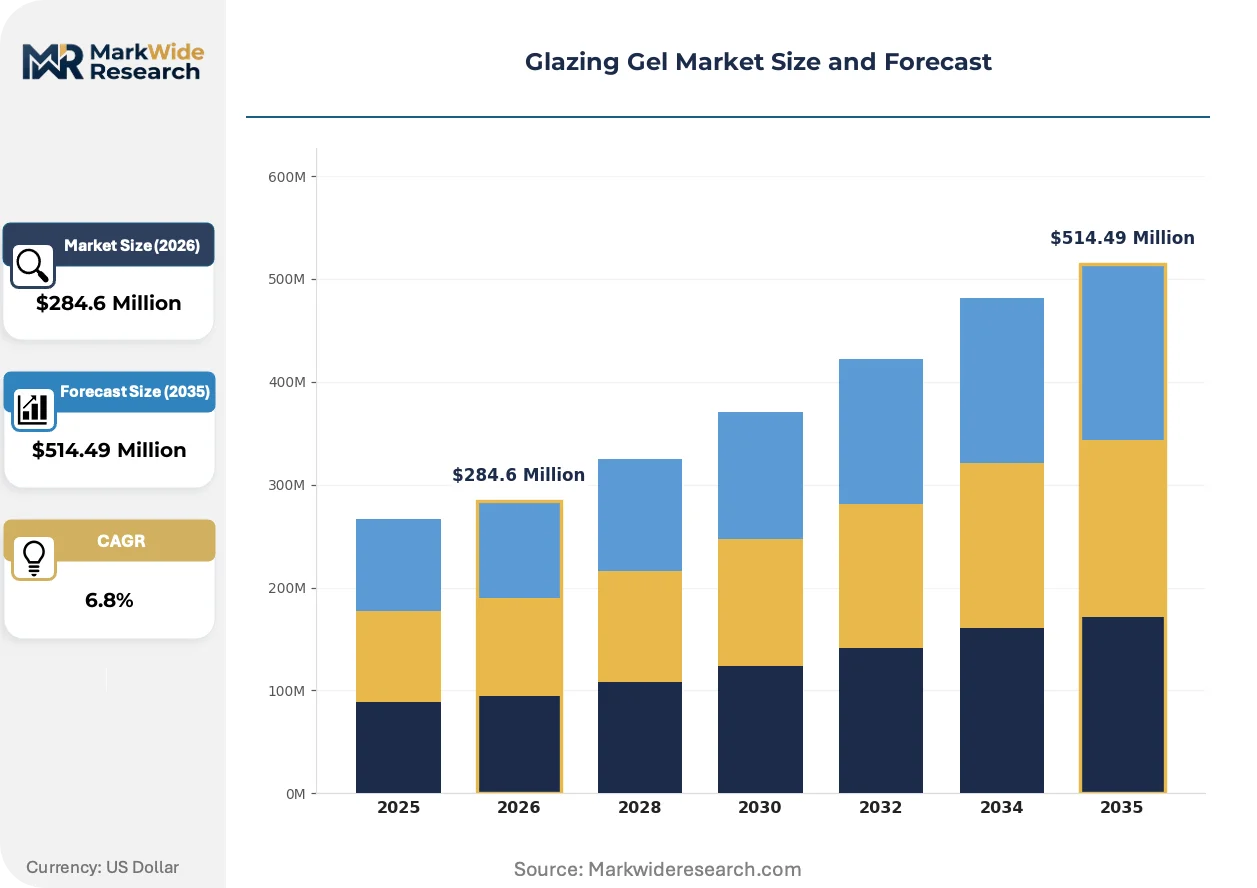
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based Gel, Oil-Based Gel, Solvent-Based Gel, Hybrid Gel Application: Food Decoration, Cosmetic Use, Art & Craft, Industrial Finishing End User: Food Manufacturers, Cosmetic Brands, Artisans, Industrial Painters Packaging Type: Tubes, Jars, Squeeze Bottles, Pouches |
| Companies Covered | Cargill, Inc., Kerry Group, Arla Foods, AUI Fine Foods, Inc., Mantrose-Haeuser Co., Inc., Sprinkles & Co., Stearinerie Dubois, Koster Keunen, Freudenberg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glazing Gel Market Emerging Trajectories
Active reformulation toward biodegradable hydrocolloids is compressing development cycles, as regulatory deadlines and buyer sustainability scorecards converge to accelerate technology substitution across coating applications.
Hybrid gel systems combining modified starch with pectin or gellan gum are overtaking single-hydrocolloid formulations in industrial bakery applications. Mid-scale contract manufacturers are adopting these blends to achieve clean-label compliance without sacrificing production line speeds. The technology is overtaking conventional water-based gels in margin-sensitive segments where performance consistency must match cost parity.
ECHA restrictions on intentionally added microplastics are compelling oil-based gel producers to eliminate synthetic polymer additives from confectionery coatings by 2026. This regulatory compression is redirecting R&D investment toward shellac-alternative resin systems derived from agricultural waste streams. European confectionery exporters are most affected, with reformulation timelines now determining market access continuity for seasonal product lines.
Specification authority is migrating from procurement departments to sustainability compliance officers at multinational food manufacturers. Direct supplier relationships are replacing distributor intermediaries for certified organic and non-GMO glazing inputs. This shift is most visible in German and Dutch bakery conglomerates where Scope 3 emissions reporting requirements demand ingredient-level traceability documentation.
Glazing Gel Market Segmentation
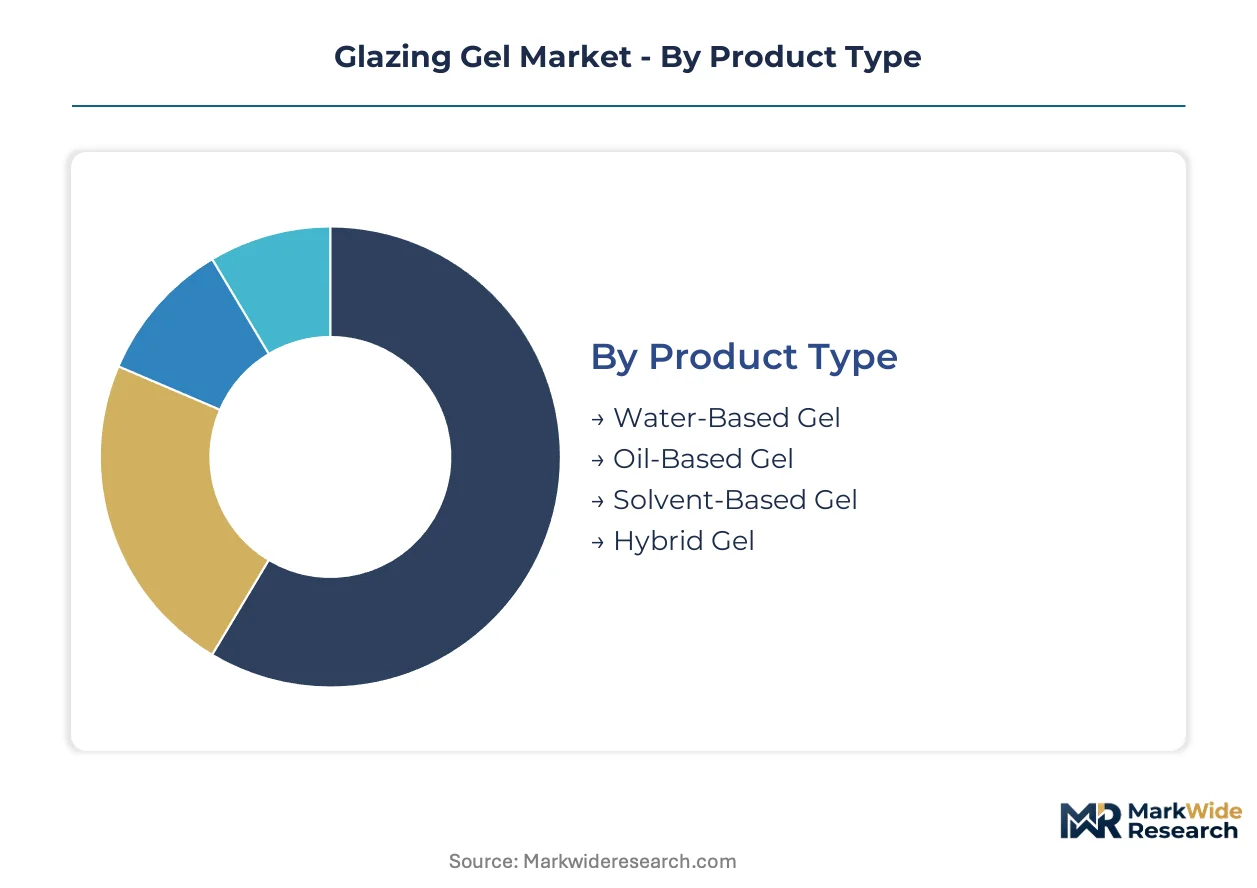
Glazing gel procurement decisions pivot on substrate compatibility, regulatory clearance, and application temperature requirements. Manufacturers segment offerings to align hydrocolloid chemistry with end-use performance thresholds and clean-label compliance obligations.
Product Type:
Reformulation cycles are accelerating as REACH substance restrictions force replacement of legacy coating chemistries with biodegradable alternatives.
- Water-Based Gel:Formulations employ modified starches, pectin, or gellan gum suspended in aqueous solution, applied at 35-50°C for heat-sensitive substrates. Industrial bakeries in Germany specify these systems for mirror-finish entremets where EFSA food-contact compliance is mandatory. Clean-label alignment drives replacement of synthetic coatings in European confectionery.
- Hybrid Gel:Blended hydrocolloid systems combine natural gums with controlled synthetic modifiers to optimize viscosity stability and production line speed. Mid-scale contract manufacturers adopt these formulations to achieve cost-performance parity without sacrificing clean-label positioning. The category gains share fastest where regulatory deadlines compress development timelines.
- Oil-Based Gel:Petroleum-derived or vegetable oil carriers suspend resin bases for moisture barrier applications in tropical distribution.
- Solvent-Based Gel:Shellac or synthetic resin solutions in alcohol or hydrocarbon carriers deliver superior gloss and humidity resistance.
Volume placements concentrate in water-based formulations; the faster expansion belongs to hybrid gels bridging performance and compliance requirements.
Application:
Margin structures diverge sharply between premium aesthetic applications and functional industrial coatings.
- Food Decoration:Mirror-finish glazes for pastries, cakes, and confectionery demand high-clarity hydrocolloid systems with precise viscosity control. Artisan bakeries and premium patisseries in France and Belgium drive specification of pullulan-based coatings for entremet finishing. ECHA microplastic restrictions are eliminating synthetic polymer additives from seasonal product lines.
- Cosmetic Use:Skincare and color cosmetic applications require biocompatible film-formers with sensory neutrality. Korean and Japanese beauty manufacturers specify glazing gels for cushion compact coatings and lip gloss suspensions where MFDS and PMDA cosmetic safety standards apply. The segment climbs fastest as K-beauty export volumes expand.
- Art & Craft:Hobbyist and professional artists employ glazing gels for mixed-media collage and acrylic painting surface effects.
- Industrial Finishing:Protective coatings for wood, metal, and ceramic substrates emphasize barrier functionality over visual appeal.
Food decoration commands the deepest margin pools; cosmetic use demonstrates the steepest expansion trajectory as Asian beauty exports accelerate.
End User:
Procurement authority is migrating from operations managers to sustainability compliance officers at scale.
- Food Manufacturers:Industrial bakeries and confectionery producers specify glazing systems with documented supply chain traceability for Scope 3 emissions reporting. German and Dutch bakery conglomerates demand kosher and halal certification infrastructure with ingredient-level documentation. Direct supplier relationships are replacing distributor channels for certified organic inputs.
- Cosmetic Brands:Multinational beauty houses require glazing gel suppliers to meet clean beauty standards and regional cosmetic safety regulations. The customer category expands most quickly as indie beauty brands scale through contract manufacturing partnerships.
- Artisans:Small-scale pastry chefs and studio artists purchase through professional kitchen supply and art material retail channels.
- Industrial Painters:Furniture and automotive finishing operations prioritize moisture barrier performance and application efficiency.
Food manufacturers place the largest volume orders; cosmetic brands are gaining share fastest in premium formulation development.
Packaging Type:
Packaging selection reflects application scale, viscosity profile, and shelf-life requirements.
- Tubes:Aluminum or laminate tubes with precision nozzles serve professional pastry chefs and cosmetic formulators requiring controlled dispensing of high-viscosity gels. French and Italian artisan bakery supply channels favor this format for mirror-glaze application in plated dessert production.
- Jars:Wide-mouth glass or PET containers accommodate dipping and brushing applications for craft and industrial finishing uses. The format grows fastest in North American hobbyist retail as DIY craft participation rises.
- Squeeze Bottles:Flexible LDPE bottles with flip-top closures target food service and home baking segments.
- Pouches:Flexible film pouches with spout fitments serve industrial bulk users and private-label food manufacturers.
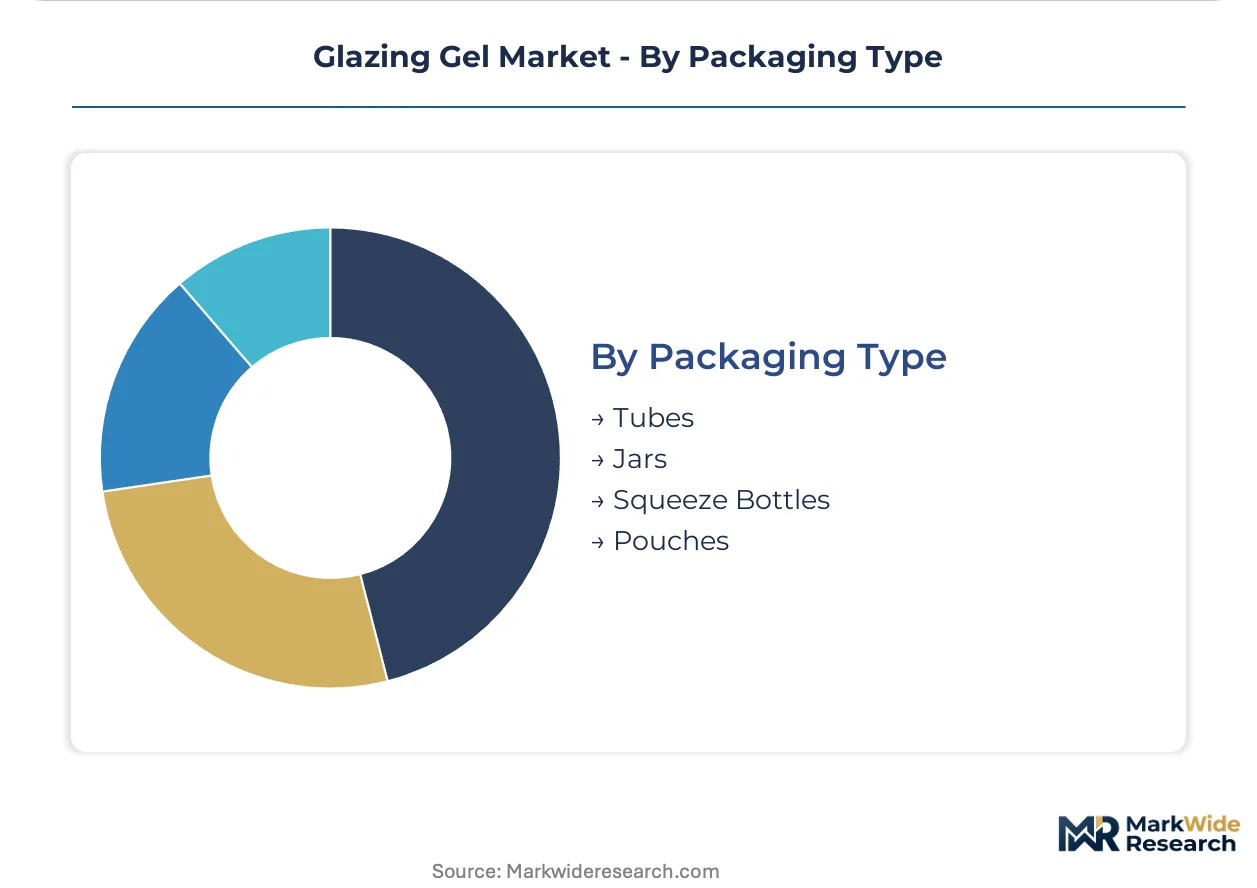
Tube packaging dominates professional channel volume; jar formats are expanding most quickly in consumer craft applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seaweed harvests in the Philippines and Indonesia anchor hydrocolloid supply chains for glazing gel manufacturers worldwide. ECHA microplastic restrictions and FDA GRAS pathways reshape formulation requirements across major consumption markets. Industrial bakery clusters in Northern Europe and confectionery corridors in North America concentrate specification authority.
Germany
Mirror-finish entremet demand from artisan bakeries drives pullulan-based gel specifications. REACH substance restrictions accelerate reformulation away from shellac toward plant-derived hydrocolloids. The Rhine-Ruhr food processing belt hosts industrial bakery cooperatives demanding kosher-certified glazing systems with full supply chain documentation.
United States
Fresh-cut fruit processors in California integrate alginate-matrix glazing for retail shelf-life extension. FDA GRAS self-determination pathways for novel plant gums require 18-24 month toxicological cycles. Chicago-area industrial bakeries retrofit spray equipment for temperature-sensitive water-based viscosity profiles.
France
Premium patisseries in Paris and Lyon specify high-clarity gels for plated dessert aesthetics. ECHA restrictions on intentionally added microplastics eliminate synthetic polymer additives from seasonal confectionery lines. The Grand Est region concentrates private-label manufacturers adopting hybrid gel systems for cost-performance parity.
Japan
K-beauty export expansion drives glazing gel demand for cushion compact coatings and lip gloss suspensions. PMDA cosmetic safety standards govern biocompatible film-former specifications. Osaka-based beauty manufacturers source glazing inputs through direct supplier relationships replacing distributor channels.
Brazil
Domestic bakery cooperatives represent unserved demand as halal and kosher certification infrastructure matures. ANVISA food-contact regulations align with Mercosur trade bloc standards for cross-border confectionery exports. São Paulo state hosts emerging contract manufacturers piloting bacterial cellulose-derived glazing films.
Glazing Gel Market Vendor Landscape
Global majors compete with regional champions across hydrocolloid sourcing networks and certification infrastructure. The vendor base stratifies between integrated ingredient conglomerates, specialty hydrocolloid refiners, and regional coating compound blenders. Three archetypes dominate: corn-starch processors leveraging agricultural supply chains, seaweed-derived gum specialists controlling viscosity consistency, and resin-system formulators serving confectionery moisture barriers. Capacity expansion in Southeast Asian seaweed processing and backward integration into modified starch production represent the dominant competitive moves.
Within the integrated ingredient tier, Cargill, Inc. and Kerry Group exemplify scale-driven positioning through captive supply of corn-derived starches and integrated flavor-glazing R&D platforms. Mantrose-Haeuser Co., Inc. occupies a specialist position representing shellac-based coating expertise for kosher and halal-certified confectionery applications. These three companies anchor the competitive structure while mid-tier producers compete on reformulation agility and regional certification speed.
| Leading Market Players |
|---|
| Cargill, Inc. |
| Kerry Group |
| Arla Foods |
| AUI Fine Foods, Inc. |
| Mantrose-Haeuser Co., Inc. |
| Sprinkles & Co. |
| Stearinerie Dubois |
| Koster Keunen |
| Freudenberg |
| Others |
Supply Flow & Price Mechanics
Hybrid gel formulation technology is simultaneously compressing production economics and redistributing supplier power toward integrated hydrocolloid processors with captive starch and gum capabilities. This production-method transition forces mid-tier compounders to absorb margin erosion or surrender share to backward-integrated competitors controlling modified pectin and gellan gum supply.
Pricing Analysis
Service bundling separates premium suppliers offering kosher-halal certification support and application engineering from unbundled commodity sellers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Pricing pressure stems from REACH-driven reformulation costs passing through to industrial bakeries. Mid-scale contract manufacturers exhibit highest price sensitivity; premium patisseries demonstrate lowest.
Supply Chain Analysis
EU Green Deal local-content incentives and bioeconomy funding streams are reshaping sourcing toward European bacterial cellulose pilot facilities and domestic modified starch processing. Raw material flows draw from Philippine and Indonesian seaweed harvests, Midwest US corn processing, and Brazilian gum arabic extraction. Single-source vulnerability concentrates in carrageenan supply from Southeast Asian seaweed operations. Distribution runs through direct supplier relationships replacing distributor channels at multinational food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
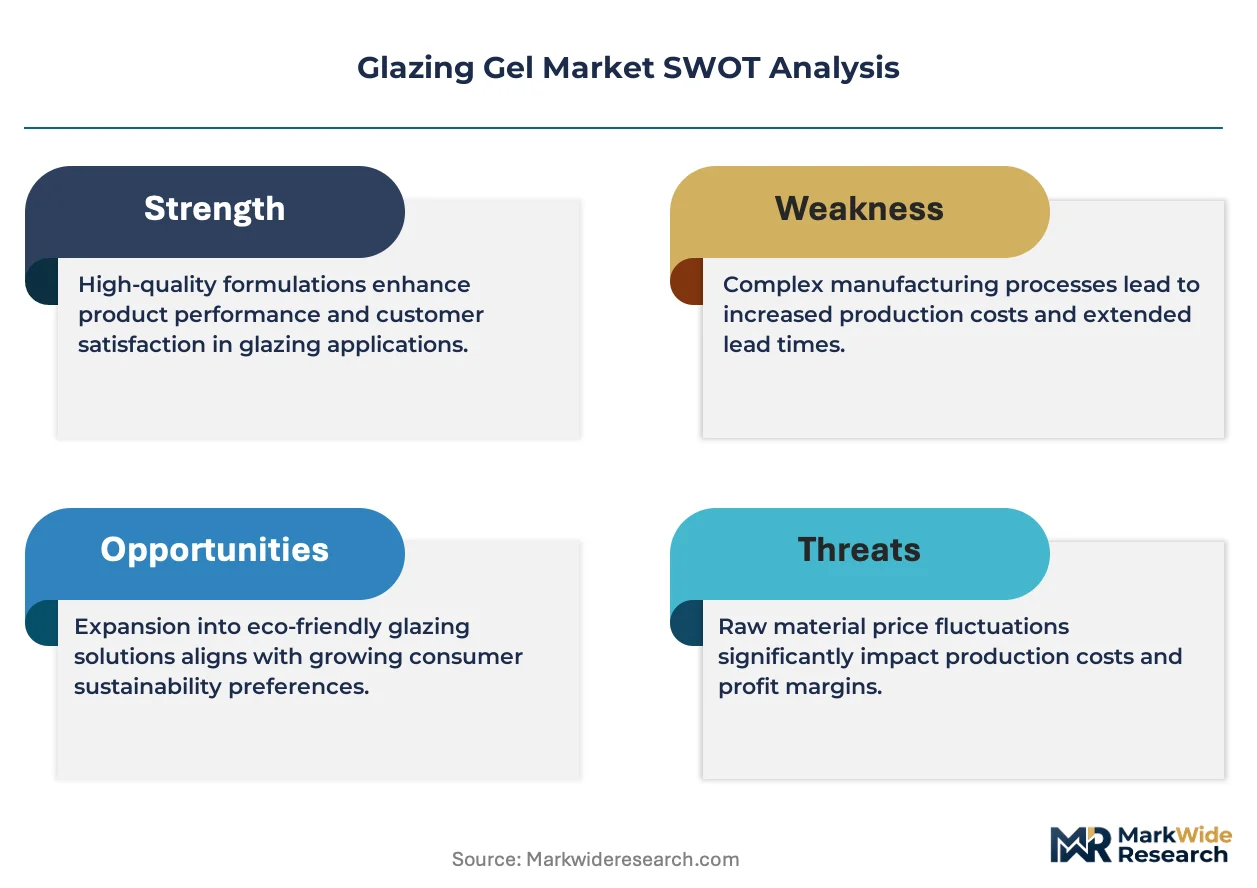
The glazing gel market sits in a technology-transition phase where water-based and hybrid hydrocolloid systems displace shellac and petroleum-derived coatings under regulatory compression.
For Market Incumbents: Extend backward integration into modified starch and specialty gum production to defend margin position against commodity price volatility in seaweed-derived inputs. Accelerate kosher-halal certification infrastructure investment ahead of Brazilian and Mexican bakery cooperative demand maturation. Prioritize R&D platforms integrating flavor-glazing combinations to lock in industrial bakery specifications. For New Entrants and Emerging Players: Contract manufacturers serving mid-scale industrial bakeries represent the most penetrable channel partner type for hybrid gel market entry. Target unserved Brazilian bakery cooperatives with certified organic positioning as domestic halal infrastructure matures. Pursue direct supplier relationships with sustainability compliance officers at German and Dutch conglomerates seeking Scope 3 traceability. For Investors and Strategic Acquirers: Re-rating potential sits with bacterial cellulose-derived glazing film specialists given EU Green Deal bioeconomy subsidy flows and pharmaceutical coating application expansion. Long-term viability favors upstream hydrocolloid refiners with Southeast Asian seaweed processing assets and European modified starch capabilities. Watch ECHA microplastic restriction enforcement timelines as inflection indicator for shellac-alternative demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Modified Starch | Cargill's corn-derived portfolio demonstrates captive supply advantages for water-based gel cost control. |
| Hybrid Gel System Launch | Kerry Group's integrated flavor-glazing R&D platforms accelerate clean-label compliance without production speed sacrifice. |
| Kosher-Halal Certification Infrastructure | Mantrose-Haeuser's shellac-based expertise anchors confectionery coating access to religious dietary markets. |
| Bacterial Cellulose Pilot Production | EU Green Deal funding streams subsidize pharmaceutical tablet coating alternatives to synthetic polymers. |
| Direct Supplier Relationship Development | German bakery conglomerates bypass distributors for certified organic inputs with ingredient-level traceability. |
Methodological Framework
Multi-period observation of hydrocolloid pricing volatility, REACH regulatory filing timelines, and industrial bakery equipment retrofit cycles anchored the trend analysis, supplemented by interviews with formulation chemists, procurement leads at European food manufacturers, seaweed processing operators, and cosmetic R&D directors. Secondary validation drew from ECHA restriction updates, FDA GRAS determination databases, FAO trade statistics for seaweed derivatives, and customs records for modified starch flows. Bottom-up volume modeling triangulated against top-down market sizing across product type and application segments.
Input-output matrices mapped hydrocolloid supply volumes to end-use consumption patterns across water-based, hybrid, oil-based, and solvent-based gel categories, with segmentation dimensions covering formulation chemistry, application temperature requirements, substrate compatibility, and clean-label compliance tier. CAGRs were derived from elasticity-adjusted demand projections incorporating regulatory deadline impacts and buyer substitution behavior. Industry-specific forecast inputs included ECHA microplastic prohibition phase-in schedules and fresh-cut fruit retail shelf-life extension adoption curves.
Caveats apply where Philippine and Indonesian seaweed harvest disruptions, ECHA substance restriction scope expansions, or FDA GRAS pathway delays for novel plant gums could materially shift the outlook. Forecasts reflect documented assumptions regarding reformulation timeline adherence and industrial bakery capital expenditure continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass
Insulated Glass Market
Glass
Fiberglass Window Market
Glass
Glass Recycling Market
Glass
Recycled Glass Aggregates Market
Glass
Glass Vials Market
Glass
Ultra Violet Glass Bottles Market
Glass
Europe Glass Insulators Market
Glass
Global Glass Flake Coatings Market
Glass
Glass Tableware Market
Glass
Glass Grade Dolomite Market
Glass
Global Ultra-Thin Glass Market
Glass
Coated Glass Market
Glass
Asia-Pacific Silica Sand Market
Glass
Optical Glass Market
Glass
Glass Reactors Market
Glass
Solar Reflective Glass Market