
 Japan Generic Drug Market | 2026-2036
Japan Generic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Generic Drug Market Intelligence
The capital-intensity divergence between domestic and multinational players is bifurcating competitive dynamics in Japan's generic drug sector. Takeda Pharmaceutical leverages its deep manufacturing infrastructure and established hospital relationships to sustain volume leadership across chronic therapy categories. Teva Pharmaceuticals Industries competes through specialized complex generic capabilities and regulatory navigation across multiple therapy areas.
A generic drug is a pharmaceutical product containing the same active pharmaceutical ingredient, strength, dosage form, and route of administration as its branded reference, demonstrated through bioequivalence studies per Japanese pharmacopoeia standards, manufactured to deliver identical therapeutic outcomes at reduced cost. The primary purpose is expanding patient access to essential medications while controlling national healthcare expenditure under Japan's universal insurance framework. Tablet formulations dominate prescription volumes due to patient compliance advantages and manufacturing scalability, while parenteral delivery modes command premium positioning in hospital settings where administration control and bioavailability requirements are stringent. Oncology therapy areas represent the fastest-expanding segment as patent expirations for biologic and small-molecule cancer therapies accelerate generic substitution opportunities.
PMDA bioequivalence guidelines and MHLW drug pricing policies shape product approval timelines and reimbursement levels, directly determining manufacturer profitability and market access conditions. Japan's Ministry of Economy, Trade and Industry (METI) pharmaceutical industry revitalization policies incentivize domestic production capacity and supply chain resilience for critical medicines. Stakeholders must monitor evolving quality consistency evaluation requirements and regional production incentives to align portfolio and facility decisions with regulatory trajectory.

Market Dynamics
MHLW pricing reforms are compressing generic margins while simultaneously mandating substitution rates that force manufacturers to absorb cost efficiencies at scale. Municipal hospital procurement consolidation under these reforms is reshaping competitive positioning toward volume-based survival.
Growth Catalysts
- Kanto and Kansai regional concentration:Aging demographics and chronic disease prevalence in these prefectural clusters generate prescription volume density that rewards manufacturing scale investments.
- METI pharmaceutical industry revitalization policies:Domestic production capacity incentives and supply chain resilience mandates for critical medicines accelerate facility localization decisions.
- PMDA bioequivalence guidelines:Streamlined approval pathways for established molecular categories reduce time-to-market for qualified manufacturers with demonstrated quality consistency.
Market Restraints
- Active pharmaceutical ingredient import dependency:Concentrated sourcing from specific Asian manufacturing clusters exposes margin volatility to raw material cost swings and logistics disruption.
- MHLW biennial price revision mechanism:Mandatory reimbursement cuts for long-listed generics compress sustainable profitability windows and deter portfolio expansion.
- Complex generic technical barriers:Parenteral formulation bioequivalence demonstration requires specialized analytical capabilities and extended stability testing that smaller domestic players cannot resource.
Strategic Opportunities
- Oncology biosimilar convergence:Patent expiration waves for biologic cancer therapies open substitution opportunities in hospital infusion centers where administration control requirements favor qualified suppliers.
- Quality consistency evaluation premium tiering:MHLW differentiation between standard and premium-grade generics creates pricing stratification for manufacturers with superior manufacturing process validation.
- Regional pharmacy chain consolidation:Independent pharmacy absorption into cooperative purchasing organizations concentrates dispensing volume and creates preferred supplier arrangements for generic portfolios.
Industry Challenges
- Bioequivalence study specialist scarcity:Qualified clinical pharmacology investigators and biostatisticians for Japanese pharmacopoeia compliance are concentrated among limited contract research organizations, creating study scheduling bottlenecks.
- Legacy ERP-to-PMDA e-submission integration:Electronic common technical document migration requires substantial validation expenditure for established manufacturers with customized quality management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Generic Drug Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $43.34 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injection, Ointment Delivery Mode: Oral, Parenteral, Topical, Inhalation End User: Hospitals, Pharmacies, Clinics, Homecare Therapy Area: Cardiovascular, Oncology, Neurology, Infectious Disease |
| Companies Covered | Takeda Pharmaceutical, Teva Pharmaceuticals Industries, Sun Pharmaceutical, Nichi-Iko Pharmaceutical, Sawai Pharmaceutical, Daiichi Sankyo, Meiji Seika Pharma, Sandoz, Mylan, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Generic Drug Market Strategic Shifts & Innovations
Continuous manufacturing adoption is bifurcating competitive capabilities between capital-equipped multinationals and batch-process-dependent domestic players. Regulatory data integrity requirements and quality-by-design mandates are simultaneously elevating technical barriers and rewarding process innovation investments.
Continuous direct compression and hot-melt extrusion systems are replacing conventional wet granulation for high-volume oral solid dosages. Takeda Pharmaceutical and qualified multinational subsidiaries are deploying these platforms for chronic therapy categories. This technology is bifurcating the market between manufacturers with real-time release testing capabilities and those dependent on end-point batch testing.
PMDA quality consistency evaluation requirements now mandate enhanced in-process controls and parametric release protocols for premium generic designation. Manufacturers must demonstrate sustained process capability indices across commercial batches to maintain reimbursement tier advantages. Oncology and cardiovascular therapy areas face the most stringent enforcement, driving facility upgrade cycles among mid-tier domestic producers.
Hospital procurement committees are consolidating annual tender awards around single-source or dual-source frameworks with strict quality deviation penalties. Municipal hospital networks in Osaka and Tokyo prefectures have pioneered multi-year volume commitments that displace fragmented spot purchasing. This concentration is most visible in parenteral antibiotic and oncology supportive care categories where supply security outweighs marginal price differentiation.
Japan Generic Drug Market Segmentation
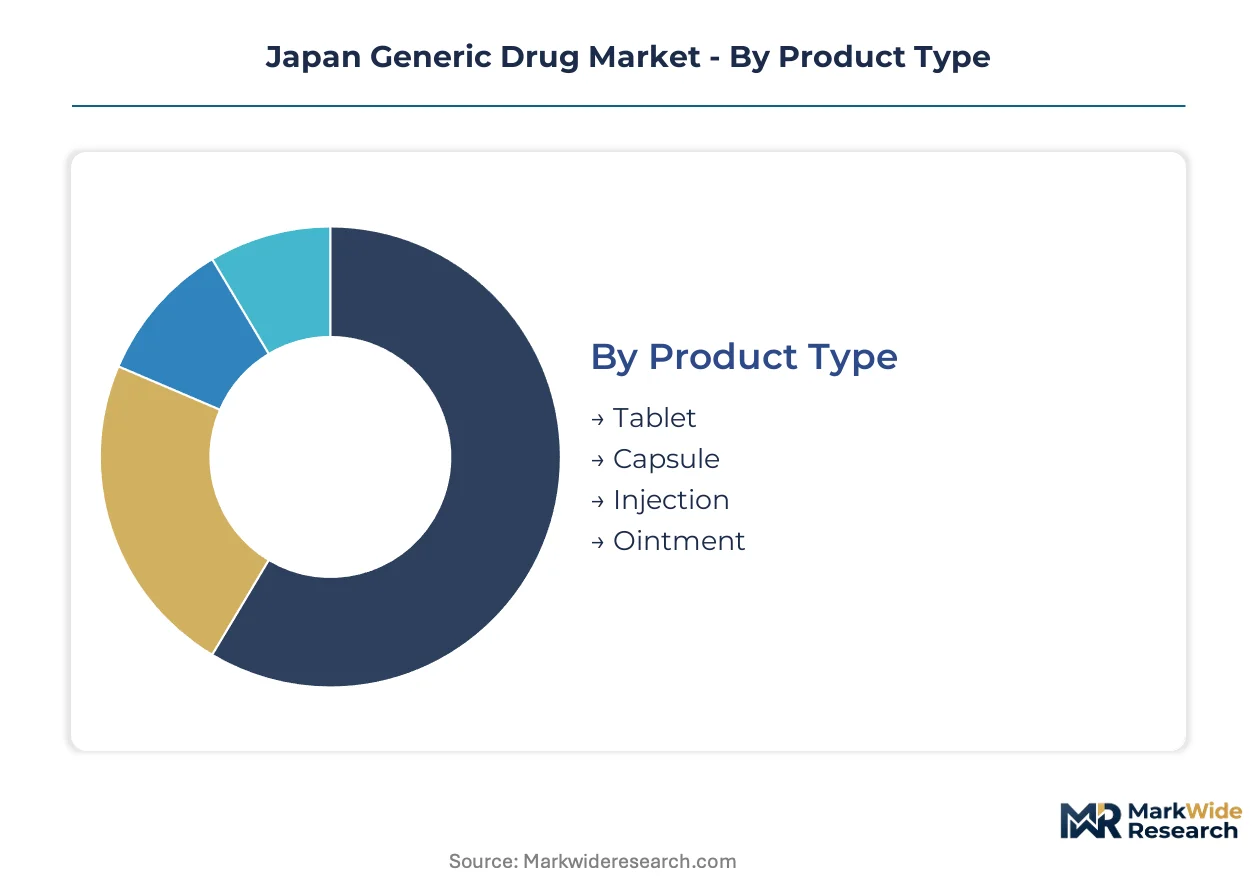
Japan's generic drug segmentation reflects distinct channel economics shaped by MHLW pricing tiers and hospital procurement consolidation. Each dimension reveals how product characteristics align with reimbursement pathways and distribution infrastructure across Kanto and Kansai prefectural clusters.
Product Type:
Tablet formulations dominate municipal hospital tenders and pharmacy dispensing volumes due to manufacturing scale advantages and patient compliance protocols. Capsule and parenteral formats concentrate in specialized therapeutic applications where bioavailability requirements override cost considerations.
- Tablet:Direct compression and continuous manufacturing platforms enable real-time release testing that satisfies PMDA quality consistency evaluation requirements. Municipal hospital networks in Tokyo and Osaka prefectures consolidate annual procurement around high-volume tablet contracts for chronic cardiovascular and metabolic therapies where patient adherence programs drive prescription loyalty.
- Capsule:Gelatin and hypromelshell encapsulation accommodates moisture-sensitive APIs and modified-release formulations that tablet compression cannot achieve. Regional pharmacy chains in Kanagawa and Kyoto prefectures favor capsule alternatives for elderly patients with swallowing difficulties, creating niche volume pools outside hospital tender systems.
- Injection:Parenteral generics command premium reimbursement tiers under MHLW price differentiation frameworks.
- Ointment:Topical semisolids serve dermatology and localized pain management through clinic and pharmacy channels.
By volume, Tablet leads. By growth pace, Injection is ahead.
Delivery Mode:
Cost tier stratification separates oral solid dosages from parenteral and inhalation formats where technical barriers sustain margin premiums. Oral delivery concentrates prescription volume while parenteral modes capture value concentration in hospital infusion centers.
- Oral:Swallowed tablets and capsules constitute the reimbursement backbone of Japan's generic substitution program. Kanto region municipal hospitals achieve substitution rates above national averages through centralized oral generic formularies that streamline physician prescribing patterns and pharmacy inventory management.
- Parenteral:Intravenous and subcutaneous administration requires sterile manufacturing suites and endotoxin control protocols that filter out domestic mid-tier competitors. Oncology biosimilar convergence in Osaka and Aichi prefecture hospital networks drives parenteral volume expansion as patent-expired biologics transition to qualified generic substitutes.
- Topical:Transdermal and mucosal applications serve localized therapy areas with limited systemic exposure.
- Inhalation:Metered-dose and dry-powder devices face device-generic combination complexity that delays substitution.
Oral formats dominate prescription counts. Parenteral modes show the steepest expansion trajectory.
End User:
Customer type determines procurement mechanism and pricing flexibility, with hospitals exercising volume leverage unavailable to fragmented clinic and homecare channels.
- Hospitals:Municipal and prefectural hospital networks conduct consolidated annual tenders with multi-year volume commitments that displace spot purchasing. Tokyo and Osaka metropolitan clusters pioneer single-source frameworks with strict quality deviation penalties, concentrating demand among manufacturers with demonstrated supply security.
- Pharmacies:Independent dispensing absorption into cooperative purchasing organizations creates preferred supplier arrangements. Kansai region pharmacy chains leverage collective bargaining to secure generic portfolio access that matches hospital tier pricing for chronic maintenance therapies.
- Clinics:Physician-owned outpatient facilities generate prescription volume for acute and specialty therapies outside hospital formularies.
- Homecare:Long-term care insurance reimbursement supports patient-administered therapies for mobility-limited elderly populations.
Hospitals anchor procurement volume. Pharmacies are gaining share fastest through cooperative consolidation.
Therapy Area:
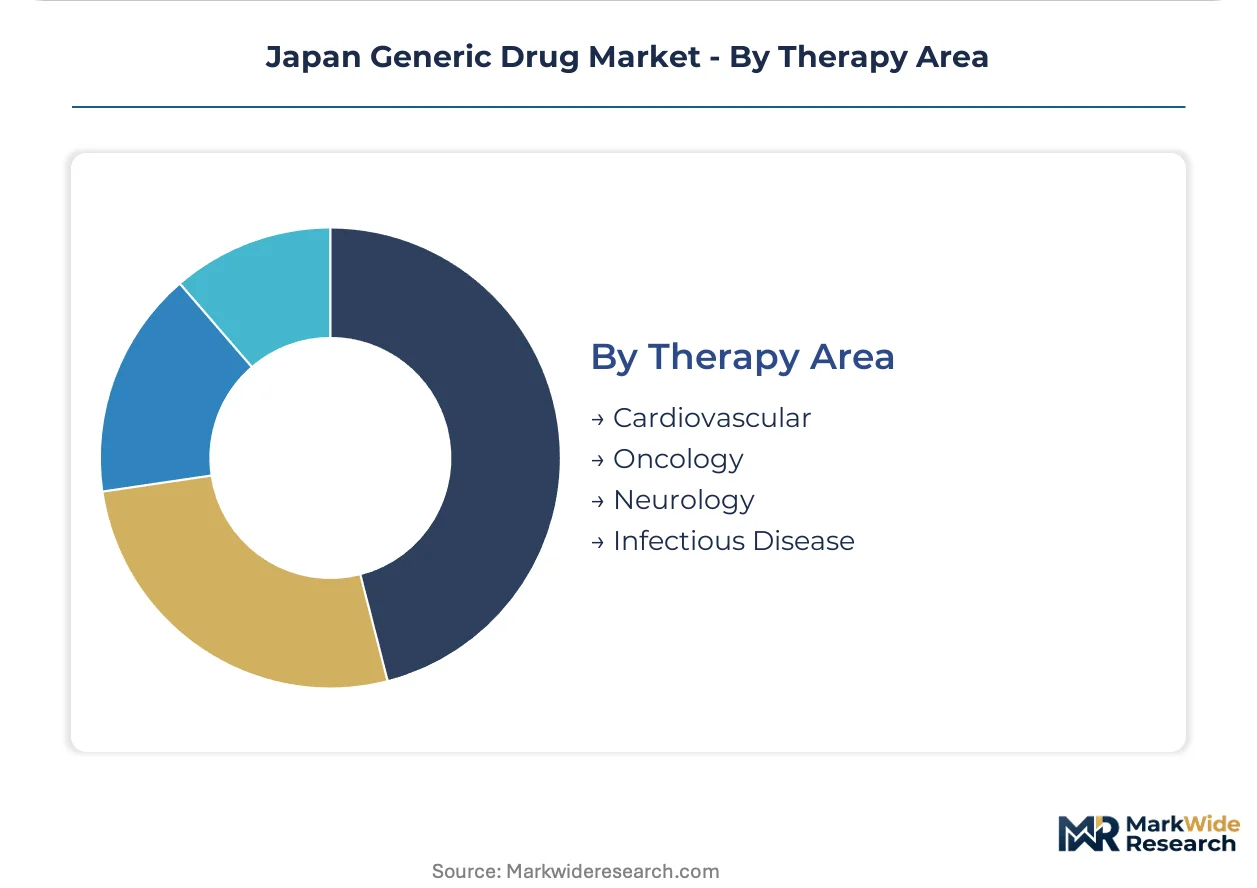
Maturity gradients separate established chronic disease categories from oncology and neurology segments where patent expiration waves and unmet medical need create substitution opportunities.
- Cardiovascular:Hypertension and dyslipidemia generics constitute the volume foundation of Japan's substitution program with decades of bioequivalence data supporting physician confidence. Kanagawa and Saitama prefecture aging demographics sustain prescription density for statin and ACE inhibitor categories where manufacturing scale determines tender competitiveness.
- Oncology:Biologic and small-molecule cancer therapy patent expirations accelerate hospital infusion center substitution. Osaka and Aichi prefecture oncology departments prioritize qualified suppliers with cold-chain integrity and batch traceability systems that satisfy PMDA enhanced pharmacovigilance requirements for cytotoxic generics.
- Neurology:Central nervous system therapies face bioequivalence demonstration challenges for blood-brain barrier penetration.
- Infectious Disease:Antibiotic generics concentrate in parenteral formats for hospital-acquired infection protocols.
Cardiovascular leads by prescription volume. Oncology climbs the fastest as biosimilar substitution accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's generic drug trade maintains a structural deficit in active pharmaceutical ingredient sourcing, with domestic formulation capacity dependent on imported chemical intermediates from concentrated Asian manufacturing clusters. This import dependency shapes regional facility placement and inventory positioning strategies across the archipelago.
Kanto
Tokyo and surrounding prefectures generate the highest prescription volume density nationally, driven by aging populations in Saitama and Kanagawa. MHLW pricing reforms incentivize municipal hospital consolidation here. The Keihin industrial corridor hosts continuous manufacturing facilities serving chronic therapy categories.
Kansai
Osaka prefecture anchors hospital procurement innovation with multi-year tender frameworks and single-source supply arrangements. METI pharmaceutical revitalization policies support domestic production capacity expansion in this cluster. The Osaka-Kobe pharmaceutical belt concentrates parenteral manufacturing for oncology and infectious disease segments.
Chubu
Aichi prefecture's automotive-to-pharma industrial diversification creates contract manufacturing opportunities for generic sponsors. PMDA bioequivalence study infrastructure concentrates in Nagoya's clinical pharmacology network. The Tokai region's logistics connectivity supports cold-chain distribution for temperature-sensitive formulations.
Kyushu
Fukuoka prefecture's pharmaceutical port infrastructure handles API import volumes for western Japan formulation sites. Regional pharmacy cooperative purchasing organizations here negotiate preferred supplier terms matching Kanto pricing tiers. The Kitakyushu industrial zone maintains legacy batch-process facilities for established oral solid dosages.
Japan Generic Drug Market Key Industry Players
Concentration sits with integrated domestic incumbents and multinational specialists operating through Japanese subsidiaries. The vendor base stratifies across three tiers: capital-equipped continuous manufacturers, batch-process domestic players, and import-dependent niche specialists. Competitive maneuvering centers on MHLW quality consistency evaluation attainment and municipal hospital tender positioning. Facility upgrade cycles and PMDA e-submission capability investments constitute the dominant competitive moves.
Among domestic integrated pharmaceutical companies, Takeda Pharmaceutical and Daiichi Sankyo exemplify the capital-intensive archetype with established hospital relationships and manufacturing infrastructure. Multinational specialists Teva Pharmaceuticals Industries and Sandoz occupy positions leveraging complex generic capabilities and regulatory navigation across multiple therapy areas. Sawai Pharmaceutical and Nichi-Iko Pharmaceutical represent mid-tier domestic players navigating consolidation pressure through cooperative purchasing alignment and regional pharmacy chain partnerships.
| Leading Market Players |
|---|
| Takeda Pharmaceutical |
| Teva Pharmaceuticals Industries |
| Sun Pharmaceutical |
| Nichi-Iko Pharmaceutical |
| Sawai Pharmaceutical |
| Daiichi Sankyo |
| Meiji Seika Pharma |
| Sandoz |
| Mylan |
| Others |
Cost & Logistics Intelligence
Capacity utilization at continuous manufacturing facilities in the Keihin industrial corridor shapes competitive pricing floors across Japan's generic drug sector. Municipal hospital procurement consolidation amplifies scale advantages for manufacturers with real-time release testing capabilities, compressing margins for batch-process competitors while reinforcing tiered reimbursement stratification under MHLW quality consistency evaluation frameworks.
Pricing Analysis
Municipal hospital buyers anchor Japan's generic pricing structure through consolidated annual tenders with multi-year volume commitments. Three-tier pricing separates premium-grade generics with demonstrated process capability indices from standard and economy tiers based on manufacturing validation depth and supply security track records. Pricing pressure stems from MHLW biennial reimbursement cuts for long-listed products, forcing manufacturers to absorb cost efficiencies. Regional pharmacy cooperatives exhibit highest price sensitivity due to fragmented dispensing volumes, while hospital networks prioritize supply reliability over marginal cost differentials.
Supply Chain Analysis
Inventory positioning for active pharmaceutical ingredients maintains six-to-nine-month coverage given concentrated sourcing from India and China for chemical intermediates. Japanese formulation capacity rests on imported APIs for approximately three-quarters of generic volume, with sterile manufacturing suites for parenteral products concentrated in the Osaka-Kobe pharmaceutical belt. Single-source vulnerability for oncology cytotoxic precursors creates exposure to logistics disruption at major Asian manufacturing clusters. Distribution runs through wholesaler consignment models to municipal hospital networks and cooperative purchasing organizations serving regional pharmacy chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's generic drug market is recovering from cyclical margin compression driven by MHLW pricing reform implementation, with quality-tier differentiation creating selective expansion opportunities for capital-equipped manufacturers.
For Market Incumbents: Fortify manufacturing infrastructure through continuous processing upgrades that satisfy PMDA quality consistency evaluation requirements for premium reimbursement tiers. Secure backward integration into critical API sourcing through METI incentivized domestic capacity expansion, defending against supply disruption threats from concentrated Asian intermediate suppliers. For New Entrants and Emerging Players: Differentiate on complex generic capabilities in parenteral oncology and biosimilar categories where technical barriers filter out mid-tier competitors. Target the Aichi prefecture contract manufacturing segment for sponsor partnerships, leveraging Nagoya's clinical pharmacology infrastructure and existing PMDA bioequivalence study networks as the primary go-to-market pathway. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with demonstrated continuous processing validation and premium-tier MHLW designation across cardiovascular and metabolic therapy portfolios. Acquisition candidates with facility upgrade completion and established municipal hospital tender positioning offer strongest viability across the extended analysis window. Watch for inflection when MHLW announces quality consistency evaluation tier recalibration schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Platform Deployment | PMDA quality consistency evaluation attainment enables premium reimbursement tier access for chronic therapy categories. |
| API Backward Integration | METI pharmaceutical revitalization incentives reduce import dependency exposure for critical generic intermediates. |
| Municipal Hospital Tender Positioning | Multi-year volume commitments in Tokyo and Osaka prefectures displace fragmented spot purchasing arrangements. |
| Oncology Biosimilar Development | Patent expiration waves for biologic cancer therapies open substitution opportunities in hospital infusion centers. |
| Regional Pharmacy Cooperative Alignment | Preferred supplier arrangements through Kansai purchasing organizations match hospital tier pricing for chronic maintenance therapies. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with pharmaceutical manufacturing executives, regulatory affairs specialists, hospital procurement managers, and formulary directors; and secondary validation through PMDA approval databases, MHLW pricing circulars, municipal hospital tender records, and METI pharmaceutical industry reports. Bottom-up prescription volume modeling triangulated against top-down manufacturer capacity assessments across Kanto and Kansai regional clusters.
Across the analysis window, forecasts applied segmented growth rate derivation by product type, delivery mode, end-user channel, and therapy area, with particular weighting for oncology biosimilar substitution velocity and cardiovascular generic maturity gradients. CAGRs were computed from annual prescription volume trajectories and reimbursement tier evolution under MHLW pricing reform schedules, incorporating bioequivalence study completion rates and facility upgrade cycle timing as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained MHLW quality consistency evaluation enforcement or METI domestic production incentive continuity would require recalibration. Forecasts reflect documented assumptions regarding patent expiration waves, regional demographic aging trajectories, and API import logistics stability. Revision becomes warranted when MHLW biennial price revision magnitude or PMDA bioequivalence guideline stringency crosses established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Canagliflozin Market
Pharmaceuticals
Demerol (Meperidine) Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Emedastine Difumarate Market
Pharmaceuticals
Asia-Pacific Over-The-Counter (OTC) Drugs Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Polypill Products Market
Pharmaceuticals
Global Acne Medication Market
Pharmaceuticals
Eperisone Hcl Market
Pharmaceuticals
Metoprolol Tartrate Market