
 Seasonal Affective Disorder (SAD) Market | 2026-2036
Seasonal Affective Disorder (SAD) Market Size, Share, and Industry Trends Forecast 2026-2036
Seasonal Affective Disorder (SAD) Market Analytics
LED phosphor technology is pivoting away from narrow-spectrum fluorescent tubes toward broad-band white and dawn-simulation arrays that cut device costs and improve circadian efficacy. Novartis leverages its neuroscience pipeline depth to sustain presence across antidepressant and emerging digital therapeutic categories. Eli Lilly anchors its position through psychiatric drug portfolios that compete directly with seasonal indication extensions. Pfizer differentiates via distribution scale that controls pharmacy and direct-to-patient channels for SAD-related prescriptions.
Seasonal Affective Disorder denotes a recurrent major depressive episode subtype linked to reduced daylight exposure, typically treated through bright light therapy at 10,000 lux intensity, selective serotonin reuptake inhibitors, or cognitive behavioral therapy adapted to seasonal patterns. Light Therapy Lamps occupy the largest product volume tier, though margin pools concentrate in Medications where patent-protected formulations command pricing power. Mobile Apps represent the fastest-growing solution vector, while Professional Treatment settings still capture the majority of behavioral therapy revenue due to insurer preference for supervised administration.
FDA digital health guidance and the EU MDR framework for wellness-to-medical device reclassification both shape product standards and market access timelines for SAD interventions. The EPA Energy Star program and IEC 62471 photobiological safety standards further constrain lamp design parameters, favoring manufacturers with in-house optical engineering. Stakeholders must monitor how CMS and national European health technology assessment bodies redefine reimbursement for app-delivered cognitive behavioral therapy against hardware-based light therapy.
Market Dynamics
LED phosphor technology is compressing device costs while FDA digital health guidance accelerates mobile therapeutic entry, restructuring competitive barriers between hardware incumbents and software-native entrants.
Growth Catalysts
- IEC 62471 photobiological safety standards:Manufacturers with in-house optical engineering capture margin expansion as compliance complexity filters out contract-assemblers.
- CMS reimbursement frameworks:United States outpatient networks expand SAD screening protocols, pulling demand toward supervised behavioral health integration.
- Dawn-simulation arrays:Broad-band white LED configurations improve circadian efficacy over narrow-spectrum fluorescent tubes, opening residential replacement cycles.
Market Restraints
- Patent-protected medication pricing:Selective serotonin reuptake inhibitor formulations command premium positioning that limits generic substitution pressure.
- EPA Energy Star program constraints:Lamp design parameters restrict component sourcing flexibility, favoring vertically integrated manufacturers with captive LED supply.
- Supervised administration preference:Insurer reimbursement policies steer behavioral therapy revenue toward professional treatment settings rather than self-directed hardware use.
Strategic Opportunities
- App-delivered cognitive behavioral therapy:CMS and European health technology assessment bodies are redefining reimbursement categories, creating white space for digital-native entrants.
- EU MDR wellness-to-medical device reclassification:The framework extends market access timelines for validated mobile interventions, rewarding early regulatory investment.
- Direct-to-patient pharmacy channels:Distribution scale controls for prescription SAD interventions are consolidating, enabling platform-level bundling with adjacent mental health services.
Industry Challenges
- Optical engineering talent scarcity:In-house phosphor design capability concentrates among legacy lighting manufacturers, constraining new entrant R&D velocity.
- FDA 510(k) pathway complexity:Digital therapeutic submissions require clinical validation timelines that compress startup runway before revenue generation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seasonal Affective Disorder (SAD) Market |
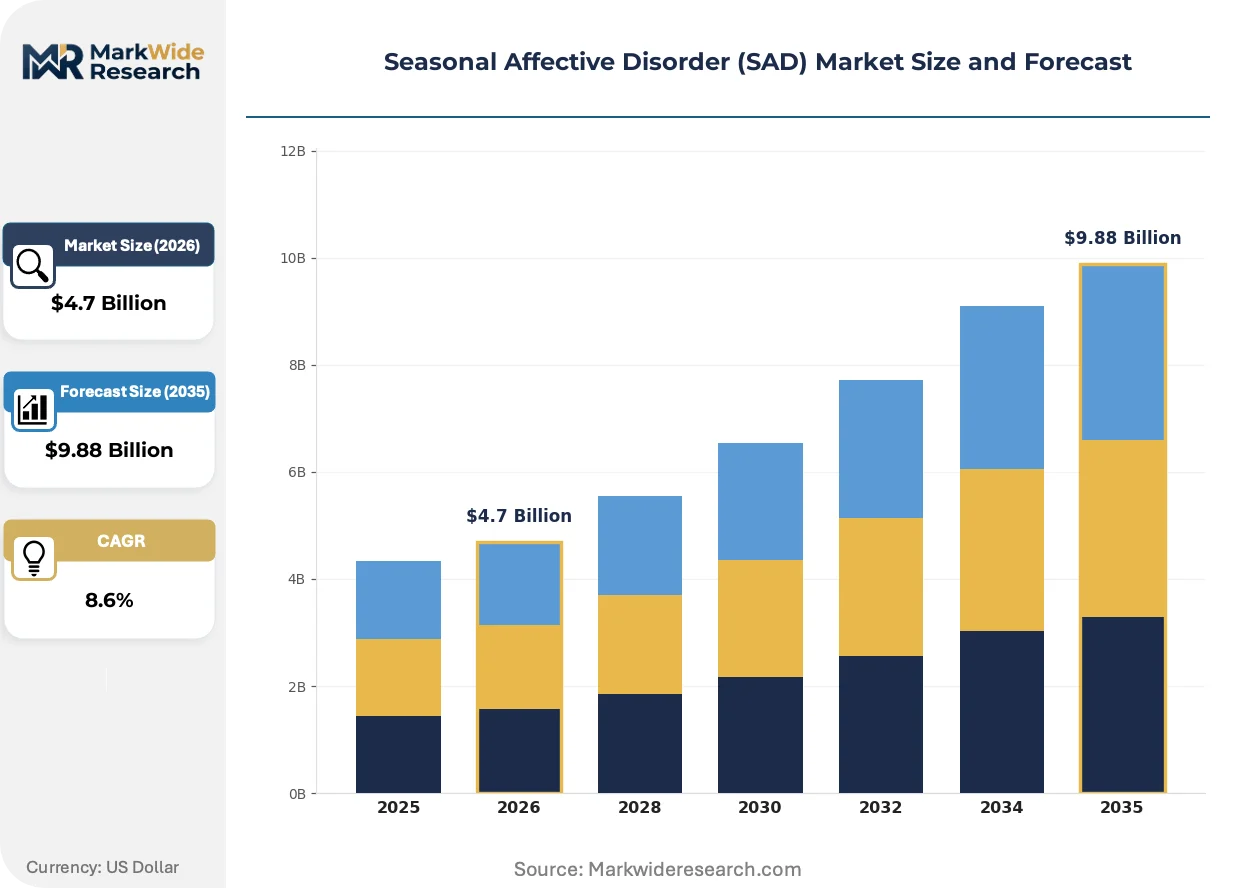
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $9.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Therapy Lamps, Medications, Behavioral Therapy, Mobile Apps End User: Patients, Healthcare Providers, Clinics, Mental Health Facilities Distribution Channel: Online Stores, Pharmacies, Hospitals, Specialty Retailers Solution: Home Treatment, Professional Treatment, Mobile Solutions, Community Programs |
| Companies Covered | Novartis, Eli Lilly, Pfizer, Teva Pharmaceutical, Sanofi, GlaxoSmithKline, AbbVie, F. Hoffmann-La Roche, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seasonal Affective Disorder (SAD) Market Evolving Landscape
Technology convergence between circadian science and consumer electronics is dissolving traditional boundaries between medical devices and wellness products, forcing regulatory recalibration and channel restructuring simultaneously.
Mobile-based light metering and personalized dosing algorithms are decentralizing treatment protocols away from fixed 10,000 lux lamp installations toward adaptive, environment-responsive interventions. Employers and payers in the United States are piloting these platforms for workforce mental health programs. The shift compresses hardware replacement cycles while expanding addressable user bases beyond diagnosed SAD populations.
FDA digital health guidance for software-as-medical-device classification is tightening evidentiary requirements for mood-tracking applications. Developers must now demonstrate clinical equivalence to established behavioral interventions. European manufacturers targeting US market entry are restructuring quality management systems to accommodate pre-market submission timelines.
Self-directed purchasing through pharmacy and direct-to-consumer channels is fragmenting traditional prescriber gatekeeper roles for light therapy hardware. Retailers are merchandising dawn-simulation lamps alongside sleep and wellness categories rather than durable medical equipment. Germany and the United Kingdom show the strongest channel shift velocity, where pharmacy deregulation permits broader wellness product placement.
Seasonal Affective Disorder (SAD) Market Segmentation
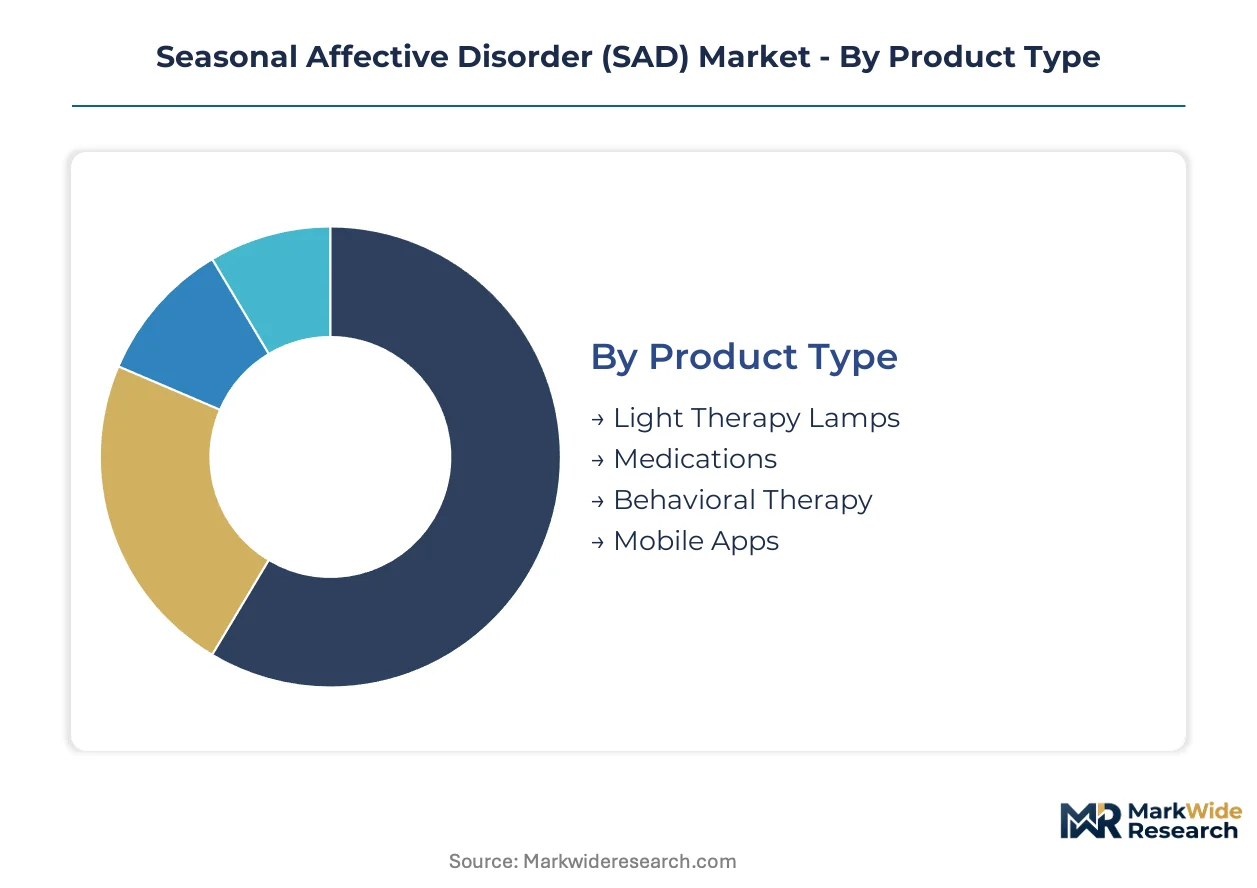
SAD market segmentation reveals divergent margin profiles across hardware, pharmaceutical, and digital therapeutic modalities. Volume concentration and premium capture split unevenly across product categories, forcing distinct competitive positioning strategies for each segment tier.
Product Type:
Volume leadership clusters in legacy hardware categories, while margin pools concentrate in patent-protected formulations and emerging digital platforms.
- Light Therapy Lamps:LED phosphor arrays at 10,000 lux intensity dominate residential installations. Demand concentrates in United States suburban markets where CMS reimbursement codes support outpatient acquisition. Circadian efficacy improvements from dawn-simulation configurations are accelerating replacement cycles.
- Medications:Selective serotonin reuptake inhibitor formulations anchor clinical protocols for moderate-to-severe presentations. Prescription volumes cluster in Nordic countries and Pacific Northwest regions with pronounced seasonal daylight variation. Patent protection sustains pricing power against generic substitution pressure.
- Behavioral Therapy:Cognitive behavioral protocols adapted to seasonal patterns require trained administrator delivery.
- Mobile Apps:FDA 510(k) pathway submissions for software-as-medical-device classification are climbing fastest among digital-native entrants.
Mature deployment sits with Light Therapy Lamps. Newer deployment is concentrated in Mobile Apps.
End User:
Revenue concentration follows the supervised administration preference embedded in insurer reimbursement frameworks.
- Healthcare Providers:Outpatient networks in United States metropolitan areas are expanding systematic SAD screening protocols. Reimbursement velocity for integrated behavioral health pulls demand toward clinically supervised settings over self-directed alternatives.
- Mental Health Facilities:Specialized psychiatric institutions command premium positioning for severe or treatment-resistant cases. Concentrated demand in Germany, Sweden, and United States academic medical centers reflects established light therapy protocol adoption.
- Patients:Direct acquisition of hardware and app-based solutions is climbing fastest through pharmacy and direct-to-consumer channels.
- Clinics:Primary care integration of seasonal screening drives hardware procurement at scale.
Established revenue capture centers on Healthcare Providers. Patient-directed segments are expanding most quickly.
Distribution Channel:
Channel restructuring is fragmenting traditional prescriber gatekeeper roles while consolidating platform-level bundling power.
- Pharmacies:Deregulation in Germany and United Kingdom permits wellness product placement alongside prescription fulfillment. Retail merchandising of dawn-simulation lamps beside sleep categories is displacing durable medical equipment positioning.
- Online Stores:Direct-to-patient platforms enable algorithm-driven personalization of light therapy protocols. United States employer wellness programs are piloting centralized procurement through these channels.
- Hospitals:Inpatient psychiatric units maintain concentrated demand for clinical-grade hardware specifications.
- Specialty Retailers:Electronics and wellness-focused retailers are gaining shelf space for consumer-grade LED arrays.
Institutional procurement remains anchored in Hospital channels. Pharmacy and Online Store segments are gaining share fastest.
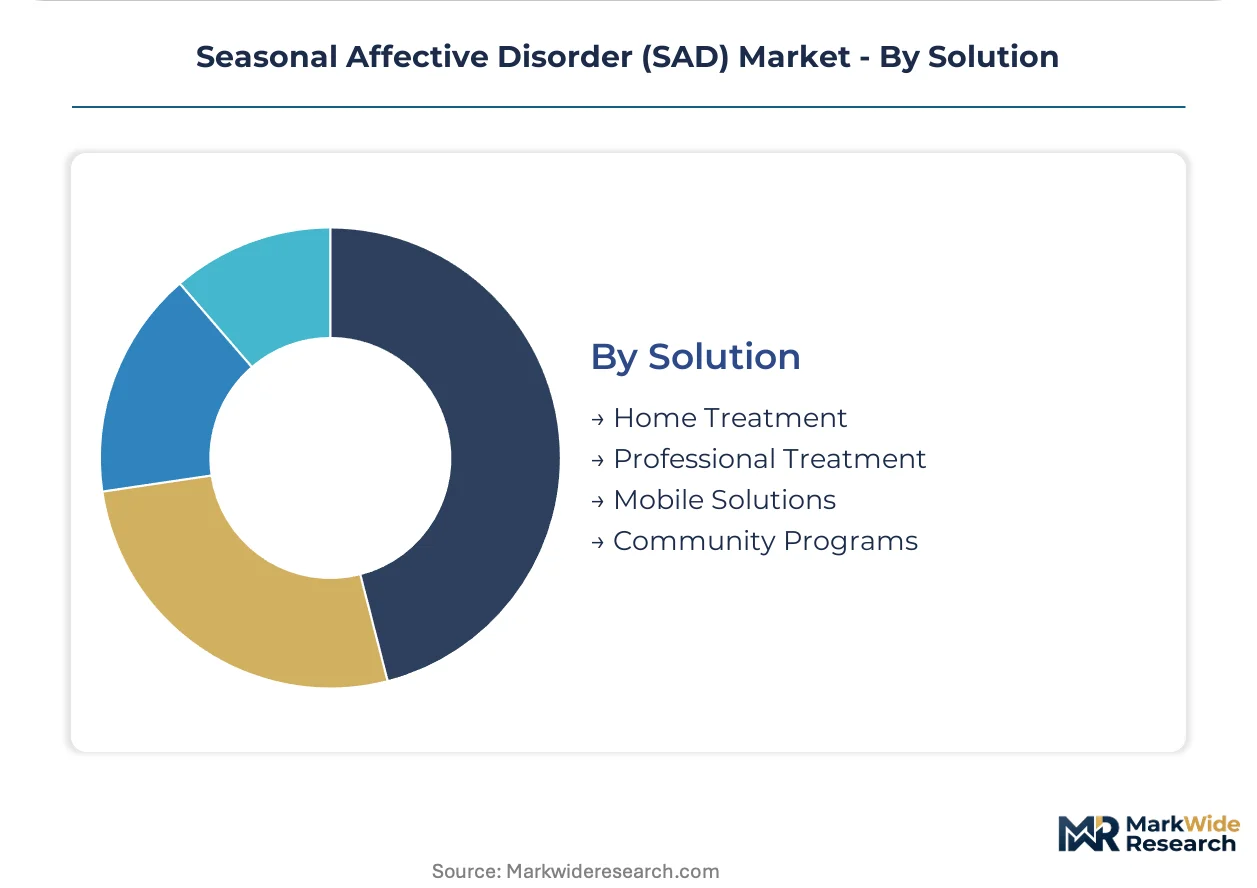
Solution:
Delivery modality segmentation tracks the shift from fixed installations toward adaptive, environment-responsive interventions.
- Professional Treatment:Supervised administration in clinical settings captures majority behavioral therapy revenue. Insurer preference for documented outcomes sustains reimbursement advantage over self-directed alternatives.
- Mobile Solutions:Personalized dosing algorithms and ambient light metering are decentralizing protocols away from fixed 10,000 lux installations. FDA digital health guidance tightening evidentiary requirements is filtering developer entry.
- Home Treatment:Residential LED lamp installation remains the largest addressable user base by volume.
- Community Programs:Employer-sponsored workforce mental health pilots are emerging in United States technology and financial services sectors.
Revenue concentration persists in Professional Treatment. Mobile Solutions demonstrate the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Seasonal Affective Disorder interventions concentrates in high-latitude developed economies where seasonal daylight variation is most pronounced and reimbursement infrastructure is mature. The United States anchors prescription volumes for antidepressant therapies, while Nordic markets drive per-capita adoption of light therapy hardware. Regulatory frameworks and channel structures vary significantly across national boundaries.
United States
CMS reimbursement codes for outpatient behavioral health integration are expanding SAD screening protocols across metropolitan hospital networks. FDA digital health guidance for software-as-medical-device classification is tightening evidentiary requirements for mood-tracking applications entering the market. The Pacific Northwest corridor from Seattle to Portland exhibits the highest residential penetration of dawn-simulation LED arrays due to pronounced winter daylight deficits.
Germany
Pharmacy deregulation permits wellness product placement of light therapy lamps alongside prescription fulfillment, accelerating channel shift velocity. The EU MDR framework for wellness-to-medical device reclassification extends market access timelines for validated mobile interventions. Munich and Berlin academic medical centers maintain concentrated demand for clinical-grade hardware specifications in psychiatric inpatient units.
Sweden
Public health system integration of seasonal depression protocols sustains per-capita prescription volumes for SSRI formulations above European averages. The country's national pharmaceutical regulator aligns with EMA guidelines for antidepressant indication extensions. Stockholm-based research institutions are piloting employer-sponsored workforce mental health programs using mobile-based light metering platforms.
United Kingdom
NICE technology appraisals are redefining reimbursement categories for app-delivered cognitive behavioral therapy against hardware-based interventions. The MHRA operates under retained EU MDR provisions while developing post-Brexit digital health guidance. London and Manchester outpatient networks are expanding systematic screening protocols, pulling demand toward clinically supervised behavioral health settings.
Canada
Health Canada regulatory pathways for photobiological safety standards favor manufacturers with in-house optical engineering capabilities. Provincial health technology assessment bodies in Ontario and British Columbia are evaluating reimbursement frameworks for light therapy devices. The Prairie Provinces exhibit concentrated residential demand due to extreme winter daylight variation and established Nordic-heritage wellness practices.
Seasonal Affective Disorder (SAD) Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents commanding margin pools in medications while hardware specialists defend position in LED lamp categories. The vendor base organizes around three strategic archetypes: multinational drug developers with neuroscience pipeline depth, legacy lighting manufacturers with captive optical engineering, and digital-native entrants pursuing FDA 510(k) clearance for software interventions. Competitive moves concentrate on portfolio diversification into adjacent mental health indications and strategic partnerships bridging hardware-software integration.
Within the multinational pharmaceutical tier, Novartis, Eli Lilly, and Pfizer exemplify divergent positioning strategies. Novartis leverages its neuroscience pipeline depth across antidepressant and emerging digital therapeutic categories. Eli Lilly anchors its position through psychiatric drug portfolios that compete directly with seasonal indication extensions. Pfizer differentiates via distribution scale that controls pharmacy and direct-to-patient channels for SAD-related prescriptions.
| Leading Market Players |
|---|
| Novartis |
| Eli Lilly |
| Pfizer |
| Teva Pharmaceutical |
| Sanofi |
| GlaxoSmithKline |
| AbbVie |
| F. Hoffmann-La Roche |
| Johnson & Johnson |
| Others |
Value Network & Pricing Analysis
Optical engineering talent concentration in Germany and the United States drives labor-cost differentials that widen pricing-tier spreads between clinical-grade and consumer-grade light therapy hardware.
Pricing Analysis
Volume leadership clusters in consumer-grade LED lamps while margin capture concentrates in prescription SSRI formulations and FDA-cleared digital therapeutics. Three-tier pricing structure across premium clinical, standard retail, and economy direct-to-consumer levels separates certified medical devices from wellness-positioned alternatives. Price differentiation hinges on IEC 62471 photobiological safety certification and after-sales clinical support bundling. Cost compression in the lamp segment is intensifying because LED phosphor commoditization erodes hardware premiums, though psychiatric medication buyers show lowest price sensitivity due to limited generic substitution for seasonal indications.
Supply Chain Analysis
Domestic-content mandates in the United States and EU MDR local-assembly requirements are reshaping sourcing patterns for SAD device manufacturers. LED chip fabrication concentrates in Taiwan, South Korea, and China, while final assembly of clinical-grade lamps clusters in Germany and the United States. Raw material dependencies include rare-earth phosphors, precision optical components, and medical-grade power management systems. Single-source vulnerability sits with Taiwanese LED foundries serving multiple competing lamp brands. Distribution runs through pharmacy networks in deregulated European markets and direct-to-patient platforms in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from FDA digital health guidance tightening evidentiary requirements will force weaker software-native entrants out before revenue generation.
For Market Incumbents: Acquire regulatory affairs capabilities and optical engineering talent pools to defend against digital-native entrants seeking 510(k) clearance. Novartis and Eli Lilly should deepen backward integration into circadian science research platforms, while legacy lighting manufacturers must secure captive LED supply before phosphor cost compression eliminates contract-assembler margins. Patent-protected SSRI formulations remain the priority defensive asset against biosimilar pressure. For New Entrants and Emerging Players: Begin with employer-sponsored workforce mental health pilots in United States technology corridors, where centralized procurement through online platforms offers lowest customer acquisition cost. The most penetrable white space sits in app-delivered cognitive behavioral therapy for subclinical seasonal mood variation, a population tenfold larger than diagnosed SAD cases. Reimbursement strategy development must precede product launch to align with CMS category redefinition timelines. For Investors and Strategic Acquirers: Re-rating potential sits with digital-native platforms possessing FDA 510(k) submissions in progress given the regulatory moat widening against uncertified wellness applications. Target acquisition archetypes include mobile therapeutic developers with completed clinical validation and European manufacturers restructuring quality management systems for US market entry. The signal to watch is CMS reimbursement code expansion for app-delivered behavioral interventions, which would validate software-as-medical-device business models across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Pathway | Software-as-medical-device classification tightens evidentiary requirements for mood-tracking applications entering US markets. |
| EU MDR Reclassification Strategy | Wellness-to-medical device pathway extends market access timelines for validated mobile interventions in European markets. |
| Hospital System Partnership | Academic medical centers in Stockholm and Berlin pilot employer-sponsored workforce mental health programs using mobile platforms. |
| Software Companion Development | Adaptive dosing algorithms decentralize protocols away from fixed 10,000 lux lamp installations toward environment-responsive interventions. |
| Reimbursement Strategy | NICE technology appraisals redefine categories for app-delivered cognitive behavioral therapy against hardware-based light therapy. |
Research Methodology
Multi-period observation of FDA 510(k) submission volumes, CMS reimbursement code expansions, and LED phosphor cost curves anchored the trend analysis, supplemented by interviews with regulatory affairs directors at digital therapeutic developers, biomedical engineers at legacy lighting manufacturers, formulary directors at US payers, and procurement managers at German hospital networks. Secondary validation drew from FDA digital health guidance documents, EU MDR implementation timelines, ClinicalTrials.gov entries for SAD interventions, and CMS Medicare Part B reimbursement databases. Bottom-up demand modeling across product categories triangulated against top-down market sizing from pharmaceutical prescription data and hardware shipment records.
Segment-weighting approaches applied differential growth assumptions across light therapy lamps, SSRI medications, behavioral therapy protocols, and mobile applications, with further granularity by supervised versus self-directed administration settings. Deployment models, reimbursement pathway maturity, and regional regulatory cluster adoption patterns shaped the analytical framework throughout the projection horizon. CAGRs derived from fitted trend lines adjusted for technology substitution effects and patent expiration schedules, with circadian science research publication velocity and employer wellness program adoption serving as industry-specific forecast inputs.
Underlying measurement precision varies by segment; prescription pharmaceutical volumes carry tighter precision than emerging digital therapeutic markets where revenue recognition remains nascent. Forecasts reflect assumptions regarding FDA clearance timelines, CMS reimbursement decisions, and LED cost compression trajectories that could revise projections if regulatory pathways lengthen or phosphor substitution accelerates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mental Health Services
Global Behavioral Health Market
Mental Health Services
Mental Health Software Market
Mental Health Services
Maternal Mental Health Market
Mental Health Services
Post-Traumatic Stress Disorder (PTSD) Market
Mental Health Services
Behavioral Health Software Market
Mental Health Services
Mental Health Market
Mental Health Services
Global Mental Health Apps Market
Mental Health Services
North America Maternal Mental Health Market
Mental Health Services
Global Workplace Stress Management Market
Mental Health Services
Panic Attack Treatment Market
Mental Health Services
Global Mental Health Care Software and Services Market
Mental Health Services
Global Anxiety Disorder Treatment Market
Mental Health Services
Relationship Counselling Market
Mental Health Services
Obsessive-Compulsive Disorder Market
Mental Health Services
Post-Partum Depression Market
Mental Health Services
Spain Post-Traumatic Stress Disorder Treatment Market