
 Multiple Sclerosis Drugs Market | 2026-2036
Multiple Sclerosis Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Multiple Sclerosis Drugs Market Intelligence
A shift from single-source dependency for key active pharmaceutical ingredients is pivoting toward multi-source procurement strategies to mitigate supply chain disruptions and ensure therapeutic continuity. Biogen Inc. leverages its deep expertise in complex biologics to lead in the monoclonal antibodies segment. Novartis AG competes with a diverse portfolio across multiple delivery modes, while F. Hoffmann-La Roche specializes in innovative treatments for challenging primary progressive MS.
Multiple sclerosis drugs are therapeutic agents designed to modify the course of the disease, manage symptoms, and treat acute relapses. These pharmaceuticals function by modulating or suppressing the immune system's attack on the central nervous system's myelin sheath. Immunomodulators and monoclonal antibodies constitute the largest segments by drug type, addressing the prevalent relapsing-remitting therapy area. The oral delivery mode is steadily gaining share from traditional injectables, a shift driven by improved patient convenience and adherence.
Market access is governed by stringent clinical trial and approval processes overseen by bodies like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA. These regulators mandate extensive data on drug efficacy and safety, directly influencing development timelines and R&D investment priorities. Navigating the evolving landscape of biosimilar approvals and patient access programs will be a critical determinant of future market share.
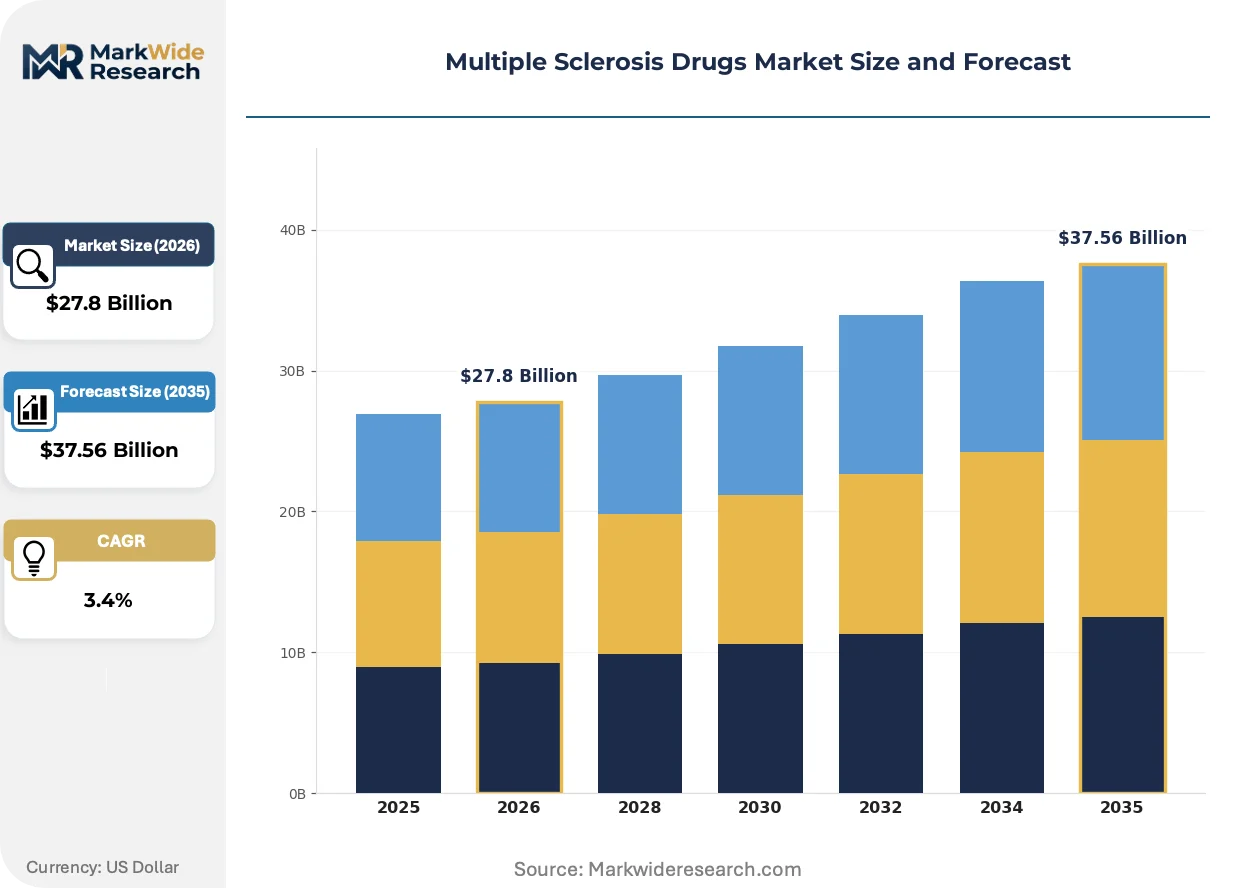
Market Dynamics
The market's structure is defined by the development of novel drug classes against a backdrop of intensifying cost-containment pressures from both regulators and healthcare payers, particularly for disease-modifying therapies with long-term treatment profiles.
Growth Catalysts
- Novel Drug Classes:The development of Bruton's Tyrosine Kinase (BTK) inhibitors offers new mechanisms of action for progressive forms of MS, expanding the addressable patient population beyond relapsing-remitting types.
- Orphan Drug Designations:Incentives from the US FDA's Orphan Drug Act and similar EMA programs accelerate development timelines and offer market exclusivity for drugs targeting less common forms of MS.
- Aging Populations in Developed Economies:Increased diagnosis rates and healthcare spending in countries like Germany and Japan support sustained demand for advanced therapies as health systems prioritize chronic disease management.
Market Restraints
- High Treatment Costs:The substantial price of monoclonal antibodies and new oral therapies creates significant reimbursement hurdles and patient access limitations, especially in healthcare systems with strict budget controls.
- Stringent Clinical Endpoints:Regulators like the EMA and Japan's PMDA require long-term disability progression data, extending clinical trial durations and increasing the overall cost and risk of drug development.
- Central Nervous System Penetration:A key technical barrier for many potential therapies is their limited ability to effectively cross the blood-brain barrier to target CNS inflammation and neurodegeneration directly.
Strategic Opportunities
- Biomarker Development:Investing in the identification and validation of biomarkers for disease progression and treatment response could enable more personalized medicine approaches and de-risk clinical trials.
- Untreated Populations in Latin America:Expanding access programs and clinical education in countries like Brazil and Mexico represents a significant opportunity as MS prevalence is better understood and diagnosed.
- Symptomatic Relief Therapies:A substantial unmet need exists for effective treatments targeting symptoms like fatigue and cognitive dysfunction, creating a market space adjacent to disease-modifying therapies.
Industry Challenges
- Patient Adherence Complexity:Ensuring long-term patient adherence to self-administered therapies remains a persistent operational challenge for clinicians, impacting real-world treatment efficacy and outcomes.
- Cold Chain Logistics:The distribution of temperature-sensitive biologics requires a complex and costly cold chain infrastructure, posing logistical hurdles and risks of product spoilage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiple Sclerosis Drugs Market |
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $37.56 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Immunomodulators, Corticosteroids, Monoclonal Antibodies, Sphingosine 1-Phosphate Receptor Modulators Therapy Area: Relapsing-Remitting, Primary Progressive, Secondary Progressive, Clinically Isolated Syndrome End User: Specialized Clinics, Research Laboratories, Neurology Centers, Pharmacies Delivery Mode: Oral, Injectable, Infusion, Topical |
| Companies Covered | Bristol-Myers Squibb Company, Merck KGaA, F. Hoffmann-La Roche, Amgen Inc., Teva Pharmaceutical Industries, Novartis AG, Sanofi, Bayer AG, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiple Sclerosis Drugs Market Strategic Shifts & Innovations
The MS drug market is moving from broad-spectrum immunomodulation towards more targeted therapeutic interventions. This evolution prioritizes specific disease pathways and patient convenience, fundamentally altering clinical practice and competitive strategy.
Sphingosine 1-phosphate receptor modulators are oral drugs that selectively sequester lymphocytes in lymph nodes. Neurologists and specialized clinics are adopting these therapies for relapsing forms of MS due to their efficacy and improved convenience over injectables. The shift to oral S1P modulators is rewriting the standard of care for first-line and second-line treatment, reducing reliance on injectable platforms.
Regulatory frameworks from bodies like the European Medicines Agency for biosimilar approvals are creating a new competitive dynamic. This pathway allows for abbreviated clinical data requirements, accelerating market entry for lower-cost alternatives to originator monoclonal antibodies. The monoclonal antibodies segment is most affected, forcing originator manufacturers to focus on next-generation therapies to defend their market position.
A notable shift in care delivery involves the administration of complex infusion therapies moving from hospital outpatient departments to specialized infusion centers. This change is driven by payer incentives for lower-cost sites of care and patient preference for more accessible clinical environments. The trend is most prominent in the United States, where it impacts the distribution and administration logistics for key infused MS therapies.
Multiple Sclerosis Drugs Market Segmentation
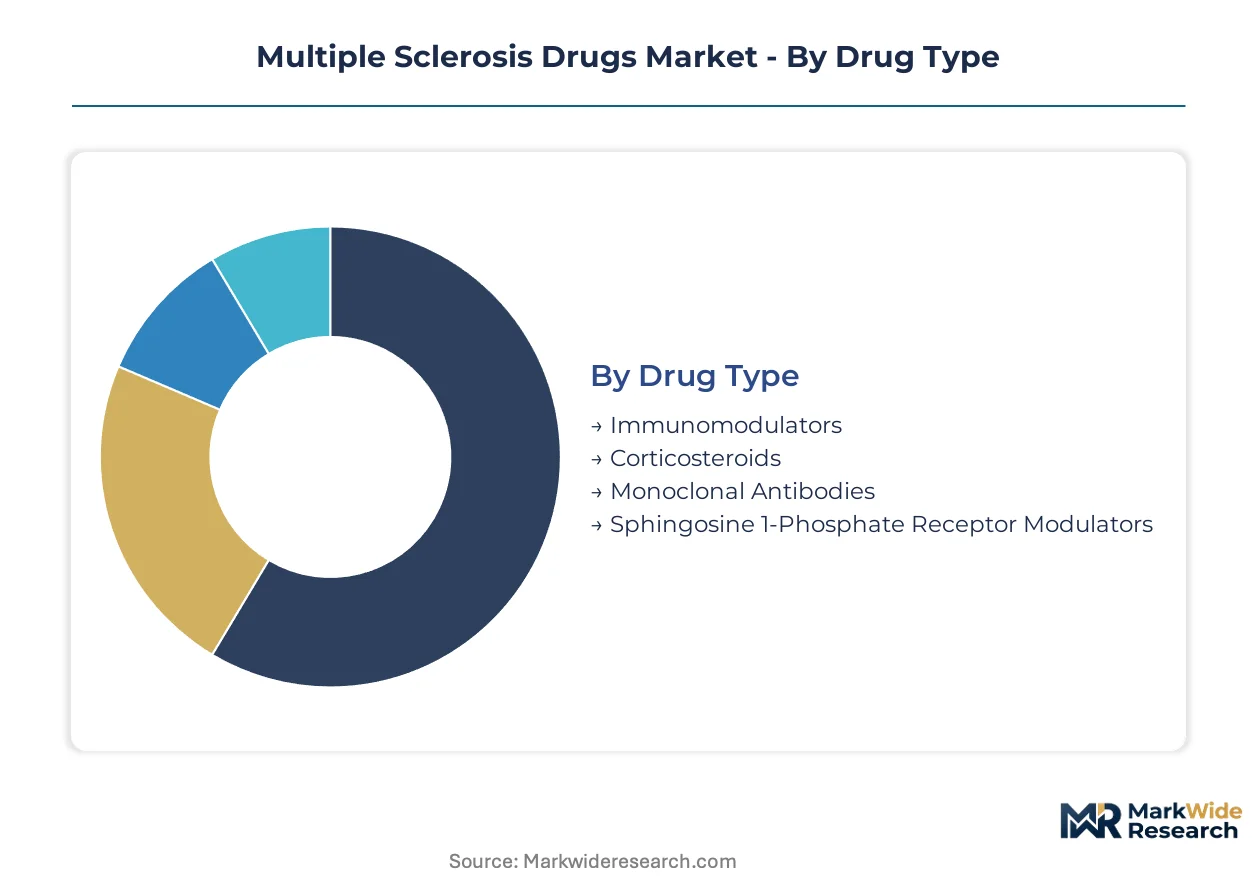
The Multiple Sclerosis Drugs market segmentation reveals distinct therapeutic approaches and patient management strategies. Understanding these divisions helps stakeholders allocate research and development resources effectively and tailor market access initiatives. Each segment reflects specific clinical needs and operational complexities within the broader MS treatment landscape.
Drug Type:
The capital-intensity of developing novel drug types significantly influences market entry and competitive dynamics.
- Monoclonal Antibodies:These complex biologics target specific immune cells or pathways, requiring substantial investment in research, manufacturing, and clinical trials. Biogen Inc. leads this segment, leveraging deep expertise in complex biologics for advanced MS therapies.
- Sphingosine 1-Phosphate Receptor Modulators:These oral drugs selectively sequester lymphocytes in lymph nodes, offering a more convenient and effective treatment for relapsing forms of MS. Neurologists and specialized clinics increasingly adopt these therapies, rewriting standard of care.
- Immunomodulators:This broad class of drugs modifies the immune system's activity to reduce inflammation and prevent myelin damage. They form a foundational component of disease-modifying therapies.
- Corticosteroids:These anti-inflammatory agents are primarily used for short-term management of acute MS relapses, reducing symptom severity. They address immediate disease exacerbations.
Monoclonal Antibodies absorbs the bulk of installed capacity; Sphingosine 1-Phosphate Receptor Modulators is expanding most quickly.
Therapy Area:
Understanding the application of therapies across different disease stages informs pharmaceutical development pipelines and patient stratification.
- Relapsing-Remitting:This therapy area addresses the most common form of MS, characterized by distinct attacks followed by periods of partial or complete recovery. Immunomodulators and monoclonal antibodies constitute the largest segments here.
- Primary Progressive:Treatments for this challenging form of MS, where neurological function progressively worsens from onset, represent a significant unmet need. F. Hoffmann-La Roche specializes in innovative treatments for this specific patient population.
- Secondary Progressive:This stage follows an initial relapsing-remitting course, with subsequent progressive worsening of neurological function. Therapeutic interventions aim to slow disease progression.
- Clinically Isolated Syndrome:This initial neurological episode with symptoms suggestive of MS often precedes a definite diagnosis. Early intervention aims to delay or prevent disease progression.
Relapsing-Remitting therapies command the largest patient volume; Primary Progressive treatments are gaining share fastest.
End User:
The distribution channels and points of patient care define the operational logistics and accessibility of MS drugs.
- Specialized Clinics:These facilities provide targeted patient management and complex infusion services, accelerating the adoption of advanced MS therapies. They are crucial for administering high-complexity treatments.
- Neurology Centers:These centers serve as primary diagnostic and treatment hubs for MS patients, offering comprehensive care and medication management. They integrate various therapeutic approaches.
- Pharmacies:Retail and specialty pharmacies dispense oral and self-injectable MS medications, ensuring patient access to ongoing treatment. They handle a significant volume of prescriptions.
- Research Laboratories:These entities focus on preclinical and clinical studies for new MS drug candidates, driving innovation and therapeutic advancements. They contribute to future treatment options.
Specialized Clinics and Neurology Centers together form the core of patient treatment; Research Laboratories exhibit a steep expansion trajectory for innovation.
Delivery Mode:
Patient convenience and adherence factors drive shifts in preferred delivery modes, influencing drug formulation and market uptake.
- Oral:This delivery mode offers improved patient convenience and adherence, steadily gaining share from traditional injectables. The shift to oral S1P modulators is rewriting standard of care.
- Infusion:Complex infusion therapies often move from hospital outpatient departments to specialized infusion centers, driven by payer incentives and patient preference. This impacts distribution logistics for key infused MS therapies.
- Injectable:Traditional injectable therapies, including self-administered subcutaneous or intramuscular options, remain a significant component of the MS drug market. These require patient training for proper administration.
- Topical:This delivery mode represents a niche area, with limited application in systemic MS treatment but potential for localized symptom management. It addresses specific symptomatic needs.
Oral delivery modes are experiencing the most significant uptake; Infusion services are adapting to new care delivery models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States, a prominent hub for pharmaceutical innovation, anchors the global Multiple Sclerosis Drugs market. Specialized clinics in major metropolitan areas drive the adoption of advanced therapies. This market expands across diverse healthcare ecosystems.
United States
High prevalence of MS and robust healthcare spending contribute to sustained demand for advanced therapies. The US FDA's stringent approval processes ensure high-quality drug development and market entry. Research institutions in Boston and San Francisco lead innovation in novel drug classes and personalized medicine.
Germany
Germany's advanced healthcare infrastructure and significant R&D investment support the uptake of disease-modifying therapies. The European Medicines Agency (EMA) influences market access and regulatory standards across the region. Pharmaceutical clusters in Bavaria and North Rhine-Westphalia foster drug development and clinical trials for MS.
Japan
Aging populations and increased diagnosis rates in Japan generate consistent demand for chronic disease management solutions. Japan's PMDA requires extensive clinical data, shaping drug development priorities for local and international firms. Research centers in Tokyo and Osaka focus on personalized medicine approaches for MS.
United Kingdom
The UK's National Health Service (NHS) prioritizes cost-effective and innovative MS treatments, driving demand for new drug classes. Regulatory alignment with EMA standards impacts market entry and biosimilar approvals. Biotech firms in Cambridge and London actively develop novel immunomodulators and advanced biologics.
France
France exhibits a growing demand for specialized MS care, supported by national health insurance programs. The Agence Nationale de Sécurité du Médicament et des produits de santé (ANSM) oversees drug safety and efficacy. Pharmaceutical research hubs in Paris and Lyon contribute to advancements in neuroinflammatory therapies.
Multiple Sclerosis Drugs Market Key Industry Players
Strategic partnerships dominate the current landscape, driving innovation and market expansion for complex MS therapies. The market structure is tiered, featuring established multinational pharmaceutical corporations alongside specialized biotech firms focusing on niche indications. These players employ portfolio diversification and technology licensing to secure intellectual property and expand therapeutic offerings. Geographic expansion into high-growth regions represents another key competitive move for market share.
On the premium-tier vector, Switzerland-based F. Hoffmann-La Roche AG exemplifies innovation in challenging primary progressive MS treatments, often focusing on unmet needs. Novartis AG, another prominent Swiss pharmaceutical company, occupies a diverse portfolio position across multiple delivery modes, including novel oral S1P modulators. US-based Biogen Inc. anchors the monoclonal antibodies segment, leveraging deep expertise in complex biologics for advanced MS therapies. These companies collectively represent the ongoing shift towards targeted therapeutic interventions and improved patient convenience in a competitive environment.
| Leading Market Players |
|---|
| Bristol-Myers Squibb Company |
| Merck KGaA |
| F. Hoffmann-La Roche |
| Amgen Inc. |
| Teva Pharmaceutical Industries |
| Novartis AG |
| Sanofi |
| Bayer AG |
| Biogen Inc. |
Cost & Logistics Intelligence
Active pharmaceutical ingredients (APIs) represent a significant cost component, directly influencing the final price of multiple sclerosis therapies and shaping procurement strategies across healthcare systems. These specialized inputs require complex manufacturing processes and stringent quality controls.
Pricing Analysis
Patient support programs, often bundled with high-cost therapies, differentiate pricing structures in the Multiple Sclerosis Drugs market. Value-based pricing models are increasingly prevalent, linking drug cost to clinical outcomes and patient benefit. Price differentiation stems from the level of clinical evidence (FDA/EMA approval status) and the brand premium associated with innovative drug classes. Pricing pressure stems from national health systems and private payers seeking to manage escalating healthcare expenditures. Government payers and large hospital systems exhibit the most price sensitivity, while individual patients, if adequately insured, show less direct sensitivity.
Supply Chain Analysis
Regulatory qualification and certification processes gate access for manufacturers within the Multiple Sclerosis drug supply chain. Supply of key active pharmaceutical ingredients concentrates in specialized manufacturing hubs in India and China, alongside advanced facilities in the United States. The supply chain relies on complex biologics and specialized chemical precursors, often with limited alternative sources. Single-source vulnerability for these critical inputs presents a structural risk, potentially leading to supply disruptions. Distribution for these therapies predominantly runs through specialized clinics and hospital pharmacies, particularly for infused and high-cost oral medications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Multiple Sclerosis Drugs market is increasingly a consolidation play, with intensifying cost-containment pressures from payers forcing smaller, less diversified players to exit or merge.
For Market Incumbents: Extend research and development efforts into novel mechanisms of action, particularly those addressing central nervous system penetration, to counter biosimilar competition. Diversify product portfolios to include symptomatic relief therapies, expanding beyond disease-modifying agents. Invest in patient adherence programs and real-world evidence generation to demonstrate long-term value and secure favorable reimbursement terms. Focus on strategic acquisitions of biotech firms possessing promising early-stage pipeline assets in neuroinflammation.
For New Entrants and Emerging Players: Contract research organizations represent a viable channel partner type for new entrants developing therapies for orphan MS indications. Target unmet needs within primary progressive MS, where therapeutic options remain limited, or focus on symptomatic relief. Developing Bruton's Tyrosine Kinase (BTK) inhibitors for progressive forms of MS represents a significant white-space opportunity. A go-to-market angle focused on strategic alliances with specialized neurology centers can facilitate rapid market penetration.
For Investors and Strategic Acquirers: Approval of a new class of highly effective, CNS-penetrant therapies is the leading indicator that could significantly reshape the long-term market landscape. The market offers sustained viability over a 5-10 year window due to increasing diagnosis rates and an aging population. Acquisition targets should include specialized biotech firms with innovative platforms in gene therapy or advanced biomarker development. Monitor regulatory shifts regarding accelerated approval pathways for rare neurological diseases.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for CNS Penetration | Enhances efficacy against neurodegeneration, addressing a critical unmet need in MS progression. |
| Licensing Agreement for BTK Inhibitors | Expands therapeutic reach into progressive MS forms, broadening the addressable patient population. |
| Manufacturing Scale-Up for Oral S1P Modulators | Supports the shift to convenient oral therapies, improving patient adherence and market access. |
| Partnership with Specialized Infusion Centers | Optimizes distribution logistics and reduces administration costs for complex biologic MS drugs. |
| Investment in Biomarker Development | Enables personalized medicine approaches, de-risking clinical trials and improving treatment selection. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, providing a foundational understanding of the Multiple Sclerosis Drugs market. This analysis integrated insights from primary interviews with key industry stakeholders, including pharmaceutical R&D executives, neurologists, payer access specialists, and specialized clinic administrators. Data triangulation across both top-down market sizing and bottom-up validation of segment revenues ensured robust quantitative estimates.
Market volume and value outputs were modeled at a granular level across key segmentation dimensions such as drug type, therapy area, end user, delivery mode, and regional regulatory clusters. The analytical framework projected market dynamics across the analysis window, with compound annual growth rates derived from historical trends and projected shifts in treatment paradigms. Key industry-specific forecast inputs included anticipated pipeline advancements and patent expiry schedules for leading therapies.
Caveats apply where unexpected clinical trial failures or major policy changes could materially shift the outlook for specific drug classes. Forecasts reflect assumptions regarding regulatory approval timelines and market access conditions. A model refresh is warranted upon material change in biosimilar market entry or novel therapeutic breakthroughs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Steroid Injections Market
Pharmaceuticals
Netupitant-Palonosetron FDC Market
Pharmaceuticals
Latin America Biguanide Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Blood Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Global Gout Therapeutics Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Global HER2 Antibodies Market
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Drug Designing Tools Market
Pharmaceuticals
Rheumatology Therapeutics Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
Gastrointestinal Diseases Drug Development Market
Pharmaceuticals
Global Cytotoxic Drugs Market
Pharmaceuticals
Skin Cancer Drugs Market