
 Montelukast Market | 2026-2036
Montelukast Market Size, Share, and Industry Trends Forecast 2026-2036
Montelukast Market Insights
India's API-to-formulation manufacturing corridor is reshaping cost structures across the Montelukast value chain. Merck & Co., Inc. anchors originator brand positioning in regulated markets through its Singulair franchise legacy. Teva Pharmaceutical Industries leverages vertical integration across generic tablets and oral solutions to sustain volume leadership. Cipla dominates pediatric formulation development, particularly chewable variants calibrated for emerging market access.
Montelukast sodium, a selective leukotriene receptor antagonist dosed at 4 mg, 5 mg, or 10 mg depending on patient age, functions by blocking cysteinyl leukotriene CysLT1 receptors to attenuate bronchoconstriction and inflammatory signaling in asthma and allergic rhinitis. Tablet formulations command the largest revenue pool due to adult chronic maintenance dosing, while granules represent the fastest-expanding segment as caregivers seek administration flexibility for children under six. Retail pharmacies occupy the dominant channel position, though online pharmacies are capturing incremental share through chronic prescription refill automation.
FDA safety labeling requirements for neuropsychiatric adverse events, EMA pharmacovigilance protocols under the EU MDR framework, and CDSCO bioequivalence standards for generic approvals collectively elevate compliance costs while restricting substandard market entry. India's PLI scheme for pharmaceutical intermediates reinforces domestic API capacity, altering import dependency trajectories. Stakeholders must monitor regulatory divergence between FDA boxed warning deliberations and EMA risk minimization measures to anticipate formulation-specific demand shifts.
Market Dynamics
India's API-to-formulation manufacturing corridor is compressing cost structures while FDA neuropsychiatric labeling reviews reshape prescribing confidence in regulated markets. These dual forces—supply concentration in South Asia and safety signal scrutiny in North America—define current competitive tension.
Growth Catalysts
- PLI Scheme for Pharmaceutical Intermediates:India's production-linked incentive program subsidizes domestic API capacity, reducing import dependency for montelukast sodium precursors and anchoring export-oriented generic supply.
- Pediatric Asthma Management Programs:Outpatient clinic initiatives across emerging markets are expanding chewable and granule formulation uptake among caregivers seeking administration flexibility for children under six.
- Chronic Prescription Refill Automation:Online pharmacy platforms are capturing incremental share through automated refill systems that reduce adherence gaps in adult maintenance dosing regimens.
Market Restraints
- API Supply Concentration Risk:Active pharmaceutical ingredient production clusters heavily in Indian chemical manufacturing zones, creating vulnerability to environmental compliance shutdowns or export restriction shocks.
- FDA Neuropsychiatric Labeling Friction:Ongoing safety reviews of suicidality and mood disorder signals are elevating prescriber caution and formulary restriction in United States markets.
- Leukotriene Inhibitor Substitution Pressure:Inhaled corticosteroid-long-acting beta agonist combinations and biologic therapies for severe asthma are displacing oral maintenance therapy in step-up treatment algorithms.
Strategic Opportunities
- Granule Formulation White Space:Underpenetrated markets in Southeast Asia and Latin America lack age-appropriate pediatric options, creating first-mover advantage for taste-masked granule developers.
- EMA Risk Minimization Measure Divergence:European Medicines Agency protocols under EU MDR framework may preserve broader labeling than FDA boxed warnings, enabling regulatory arbitrage for formulation-specific demand retention.
- Direct-to-Patient Subscription Models:Chronic disease management platforms are integrating montelukast into bundled allergic rhinitis-asthma care subscriptions, bypassing traditional pharmacy distribution.
Industry Challenges
- CDSCO Bioequivalence Certification Timelines:India's Central Drugs Standard Control Organization approval queues for generic chewable variants are extending, delaying market entry for pediatric-focused filings.
- Neuropsychiatric Signal Monitoring Infrastructure:Pharmacovigilance systems required for post-market surveillance of behavioral adverse events demand specialized data science capabilities that mid-scale generic manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Montelukast Market |
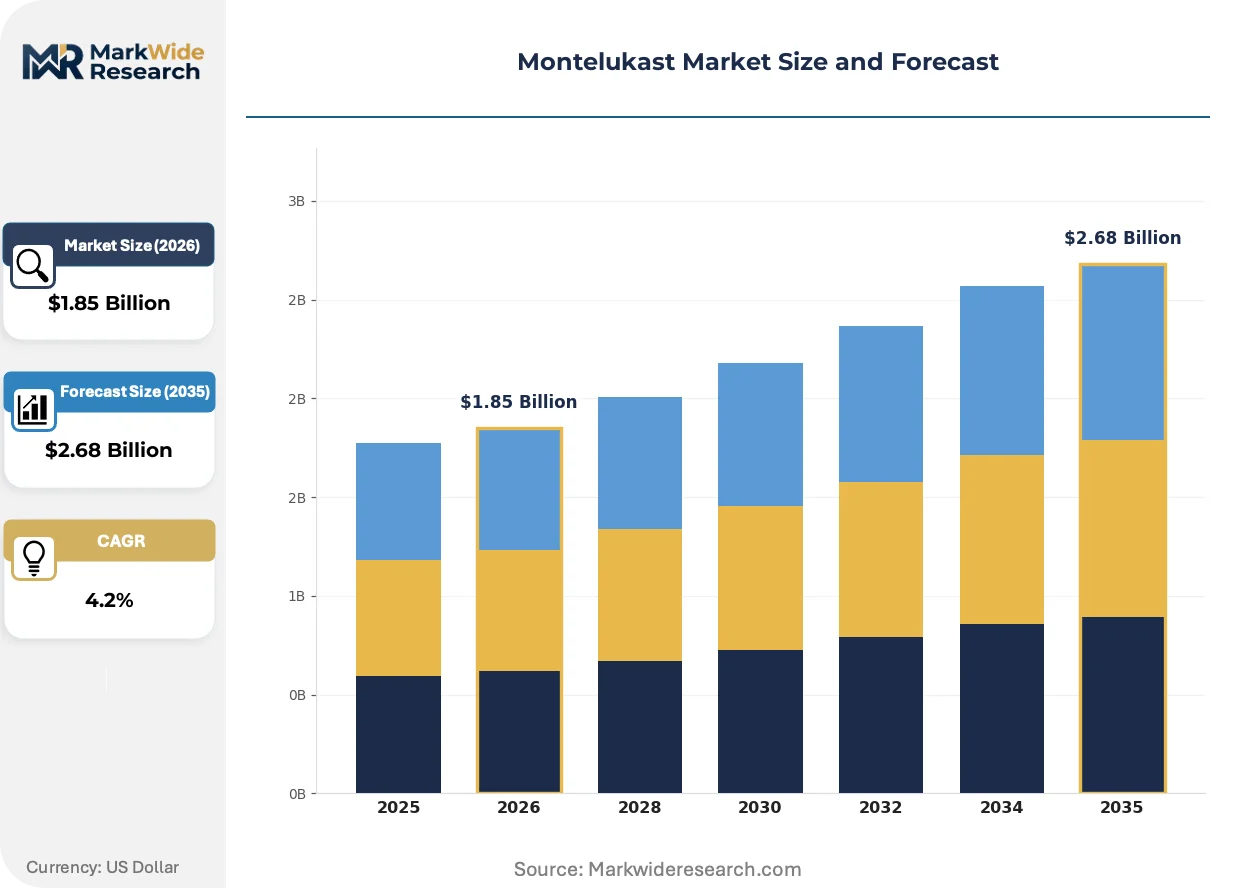
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.68 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Formulation Type: Tablets, Chewable Tablets, Granules, Oral Solution End User: Pediatric Patients, Adult Patients, Geriatric Patients, Caregivers Sales Channel: Retail Pharmacies, Online Pharmacies, Hospital Pharmacies, Clinics Packaging Type: Blister Packs, Bottles, Sachets, Bulk Packaging |
| Companies Covered | Merck & Co., Inc., Teva Pharmaceutical Industries, Cipla, Aurobindo Pharma, Dr. Reddy's Laboratories, Sun Pharmaceutical Industries, Viatris (Mylan), Morepen Laboratories, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Montelukast Market Trends and Innovations
Taste-masked pediatric formulations and real-world evidence generation platforms are displacing conventional tablet-centric development. These shifts respond to caregiver administration preferences and regulatory demands for safety signal quantification.
Oral disintegrating tablet technology is hybridizing with granule delivery systems to create flexible-dose platforms that accommodate children transitioning between age-based dosing tiers. Pediatric allergists in United States outpatient networks are piloting these hybrid formats for patients with swallowing difficulties. The convergence is compressing development timelines for age-appropriate line extensions while raising formulation complexity barriers for pure-play tablet manufacturers.
EMA pharmacovigilance protocols under EU MDR framework are mandating periodic safety update reports with neuropsychiatric event stratification by age and formulation type. Generic sponsors must now maintain active surveillance infrastructure comparable to originator standards. Pediatric chewable formulations face intensified scrutiny relative to adult tablets, driving divergence in European versus United States label preservation strategies.
Caregiver purchasing for chronic pediatric conditions is migrating toward integrated telehealth-pharmacy platforms that bundle prescription fulfillment with adherence monitoring. Allergist practices in India and Brazil are contracting directly with these platforms to secure patient retention. This channel shift is most visible in metropolitan markets where smartphone penetration enables real-time symptom logging and automated refill triggers.
Montelukast Market Segmentation
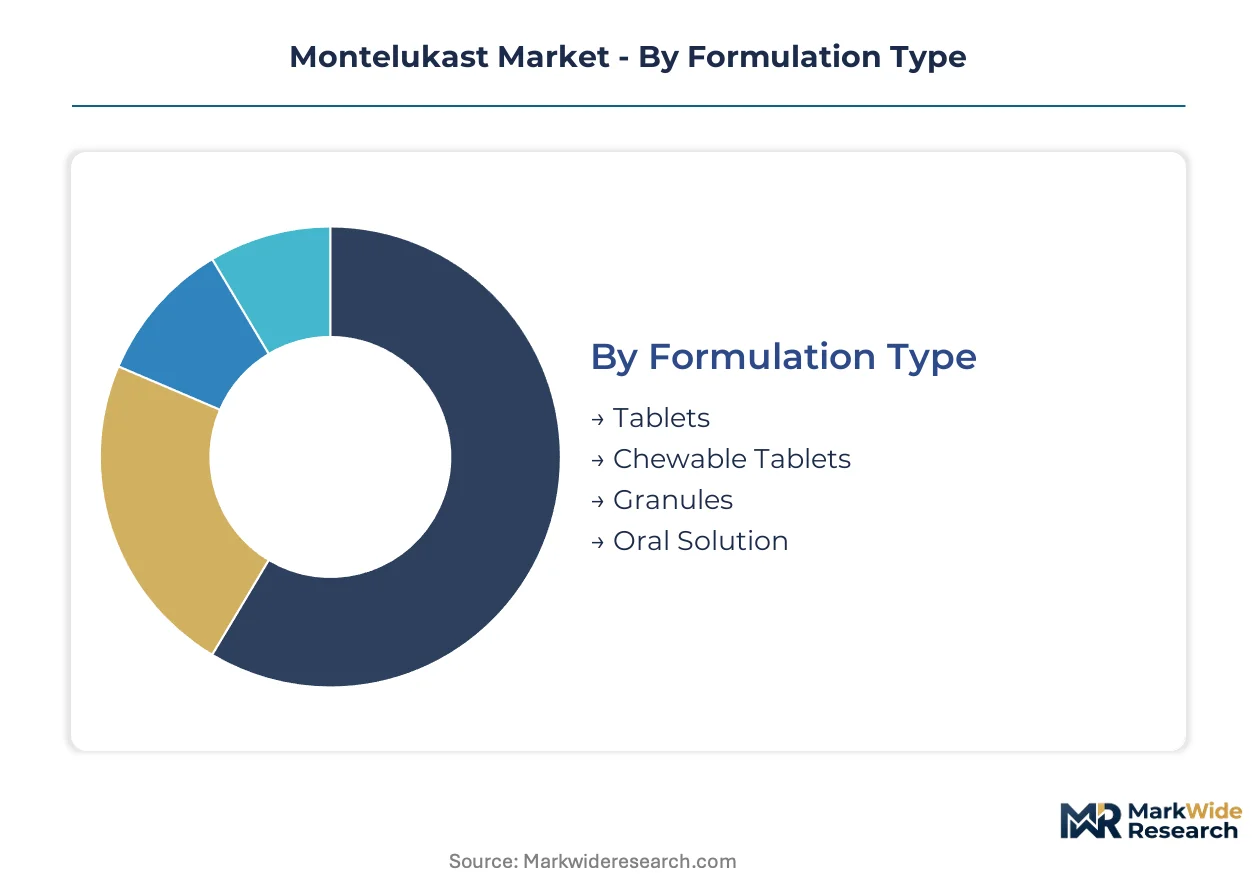
Montelukast formulation diversity reflects age-stratified dosing requirements and caregiver administration preferences across chronic asthma and allergic rhinitis populations. Segmentation reveals how pediatric-focused delivery systems command premium positioning while adult maintenance therapy drives volume throughput.
Formulation Type:
Mature tablet formats coexist with emerging pediatric delivery innovations, creating a spectrum from commodity maintenance therapy to differentiated administration solutions.
- Tablets:Standard 10 mg film-coated tablets for adult chronic maintenance dosing dominate prescription volumes through retail pharmacy channels. Adult asthma patients in the United States and India generate consistent refill demand for this established format.
- Chewable Tablets:4 mg and 5 mg fruit-flavored variants calibrated for children aged 2-14 years address swallowing difficulties while masking the bitter taste of montelukast sodium. Pediatric allergists in outpatient clinic networks prefer this format for patient compliance.
- Granules:Flexible-dose sachets enable precise weight-based administration for children under two years, particularly valued by caregivers in emerging markets with limited pediatric formulation access.
- Oral Solution:Liquid formulations serve patients with dysphagia or those transitioning between age-based dosing tiers, though stability requirements elevate manufacturing complexity.
Tablets handle the majority of throughput; granules are expanding most quickly on share as pediatric access programs proliferate.
End User:
Patient lifecycle segmentation maps directly to dosing tiers and caregiver involvement intensity, from dependent infants to self-administering adults.
- Pediatric Patients:Children aged 6 months to 14 years represent the fastest-expanding addressable population as national asthma management programs expand diagnostic coverage. Granule and chewable formulations dominate this cohort.
- Adult Patients:Self-managing adults aged 15-64 years constitute the largest chronic maintenance population, driving tablet demand through automated refill systems. Allergic rhinitis comorbidity extends prescription duration in this group.
- Geriatric Patients:Polypharmacy considerations and swallowing difficulties elevate oral solution preference among patients over 65, though this remains the smallest addressable segment.
- Caregivers:Parents and guardians function as the actual purchasing decision-makers for pediatric formulations, with administration convenience and taste acceptance determining brand loyalty.
Adult patients anchor volume commitment; pediatric patients show the steepest expansion trajectory as screening programs scale.
Sales Channel:
Channel fragmentation reflects chronic disease management automation versus acute prescription fulfillment, with digital platforms capturing adherence-critical refills.
- Retail Pharmacies:Community pharmacy networks remain the dominant fulfillment point for initial prescriptions and acute symptom management, particularly in suburban and rural geographies with limited hospital access.
- Online Pharmacies:Automated subscription models for chronic maintenance dosing are displacing periodic retail visits in metropolitan India and Brazil, with smartphone-enabled adherence tracking.
- Hospital Pharmacies:Inpatient initiation of therapy and discharge medication reconciliation sustain institutional channel relevance, though outpatient conversion reduces long-term dependence.
- Clinics:Direct dispensing at pediatric allergy and pulmonology practices streamlines first-dose administration and caregiver education, particularly for granule initiation.
Retail pharmacies retain the largest share of transactions; online pharmacies are gaining share fastest through chronic disease platform integration.
Packaging Type:
Packaging configuration balances unit-dose compliance with bulk procurement economics, diverging between patient-facing convenience and institutional efficiency.
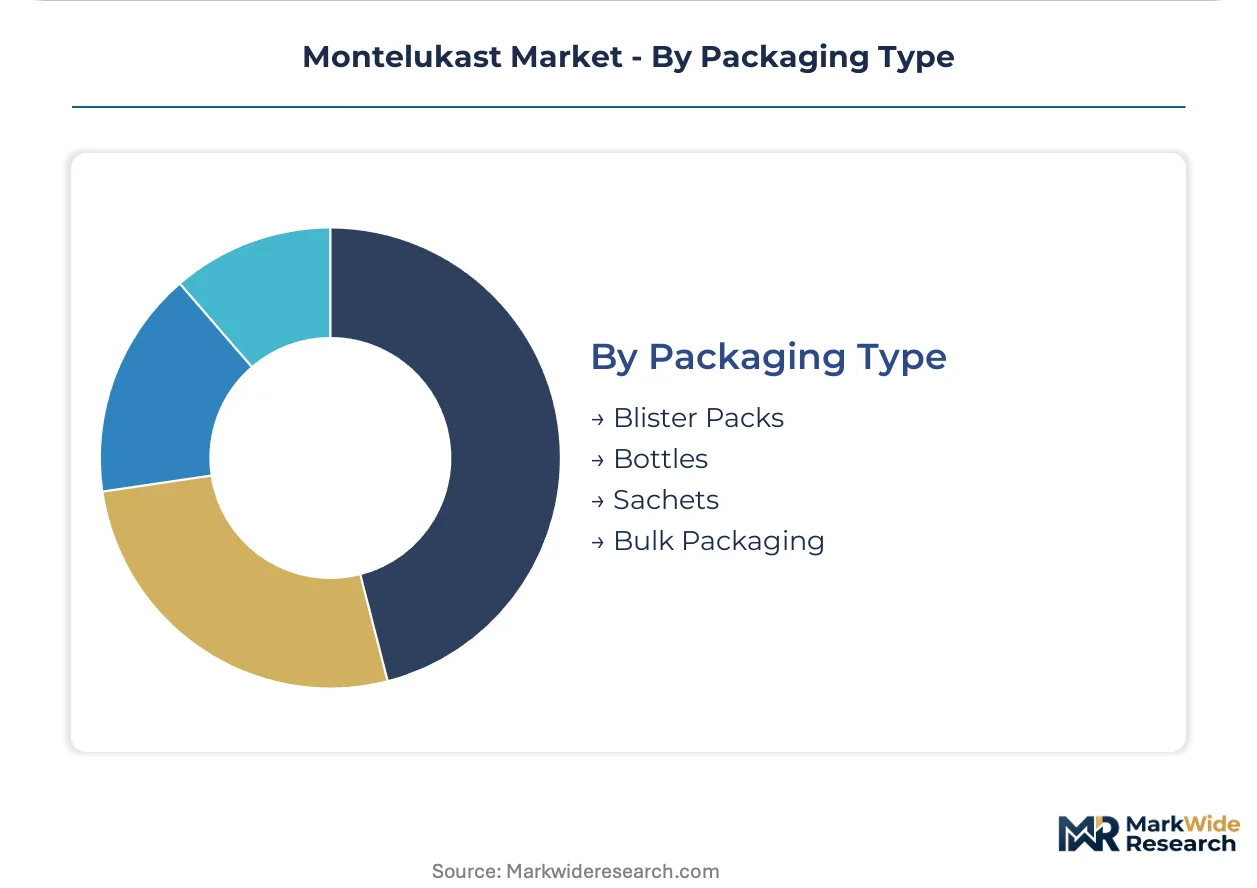
- Blister Packs:Calendarized aluminum-aluminum or aluminum-PVC blisters enable adherence verification for adult tablet regimens, preferred by reimbursement systems requiring proof-of-use.
- Bottles:Desiccant-equipped HDPE containers support 30-90 count tablet and chewable fills, optimizing cost per dose for maintenance populations with established compliance.
- Sachets:Unit-dose foil laminates protect granule stability and enable precise weight-based dosing, essential for pediatric administration flexibility.
- Bulk Packaging:Hospital and clinic procurement of 500-1000 count containers reduces per-unit cost for high-throughput dispensing operations.
Bottles capture the greatest volume throughput; sachets are climbing the fastest as pediatric granule demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jawaharlal Nehru Port Trust near Mumbai anchors Indian pharmaceutical exports to regulated markets, while the Port of Hamburg facilitates API transshipment into European formulation networks. These maritime corridors sustain the geographic distribution of montelukast supply chains.
United States
Pediatric asthma management programs in outpatient clinics drive chewable tablet demand among caregivers seeking administration flexibility. FDA neuropsychiatric labeling reviews continue reshaping prescriber confidence and formulary placement for maintenance therapy. The New Jersey pharmaceutical corridor hosts major generic sponsors navigating post-market surveillance requirements.
India
Domestic API manufacturing and export-oriented generic production anchor global montelukast supply, with pediatric formulation development expanding rapidly. CDSCO bioequivalence certification timelines for chewable variants are extending, delaying market entry for pediatric-focused filings. The Hyderabad-Visakhapatnam chemical manufacturing belt concentrates active pharmaceutical ingredient production for international markets.
Germany
EMA pharmacovigilance protocols under EU MDR framework mandate periodic safety update reports with neuropsychiatric event stratification by age and formulation type. German pediatric allergists pilot hybrid oral disintegrating tablet-granule formats for patients with swallowing difficulties. The Frankfurt-Rhine-Main logistics hub distributes finished formulations across continental European markets.
Brazil
Integrated telehealth-pharmacy platforms bundle montelukast into chronic allergic rhinitis-asthma care subscriptions, bypassing traditional pharmacy distribution in metropolitan São Paulo. ANVISA regulatory alignment with FDA safety signals influences prescribing patterns among pulmonologists. The São Paulo state pharmaceutical manufacturing cluster serves Latin American export markets.
Japan
PMDA post-market surveillance requirements for leukotriene receptor antagonists maintain stringent neuropsychiatric adverse event reporting standards. Geriatric polypharmacy considerations elevate oral solution preference among patients over 65 with swallowing difficulties. The Kanto region's pharmaceutical distribution networks prioritize stability-validated cold chain logistics for liquid formulations.
Montelukast Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API and intermediate supply. The montelukast market structures around originator legacy positioning in regulated markets versus high-volume generic manufacturing anchored in South Asia. Three archetypes dominate: vertically integrated multinational pharmaceutical companies, API-to-formulation specialists, and regional generic exporters. Competitive moves concentrate on pediatric formulation differentiation and regulatory arbitrage between FDA and EMA labeling frameworks.
Among vertically integrated multinationals, Merck & Co., Inc. and Teva Pharmaceutical Industries occupy positions reflecting divergent strategic postures—originator brand legacy versus generic volume leadership. Cipla exemplifies the API-to-formulation specialist archetype, with development capabilities concentrated on taste-masked pediatric delivery systems. These three anchors represent distinct competitive vectors: originator defense, generic scale, and emerging market access specialization.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries |
| Cipla |
| Aurobindo Pharma |
| Dr. Reddy's Laboratories |
| Sun Pharmaceutical Industries |
| Viatris (Mylan) |
| Morepen Laboratories |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
API supply concentration risk in Indian chemical manufacturing zones determines both pricing tier spreads and supply chain shape, with environmental compliance shutdowns or export restriction shocks compressing margins for formulation manufacturers while elevating premiums for dual-sourced buyers.
Pricing Analysis
Volume-discount tiering structures separate originator-branded maintenance therapy from high-volume generic tablet procurement and pediatric formulation premiums. Price differentiation hinges on FDA bioequivalence certification tier and taste-masking technology investment for chewable variants. Cost compression in standard adult tablets is intensifying because of API import dependency and CDSCO approval queue delays. Hospital procurement committees exhibit highest price sensitivity; pediatric allergists in outpatient networks show lowest sensitivity due to caregiver-driven brand loyalty.
Supply Chain Analysis
Export-control regime friction around pharmaceutical intermediates limits API flow flexibility from India to regulated markets, forcing inventory buffer strategies. Active pharmaceutical ingredient production draws from India, China, and limited European fermentation capacity; montelukast sodium precursors rest on quinoline derivative and cyclopropylacetic acid feedstock availability. Single-source vulnerability concentrates in the Hyderabad-Visakhapatnam chemical belt where environmental regulatory enforcement triggers sporadic production halts. Distribution runs through Jawaharlal Nehru Port Trust export corridors for international generic supply, with Hamburg and Rotterdam serving European transshipment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The montelukast market functions as a service-attach opportunity where chronic disease management platform subscriptions expand faster than standalone formulation revenue, with adherence monitoring and automated refill systems capturing recurring revenue layers.
For Market Incumbents: Insulate pediatric formulation margins by securing taste-masked granule patents and building captive API capacity in PLI-subsidized Indian corridors. Biologic therapy substitution for severe asthma threatens oral maintenance volumes; backward integration into quinoline intermediate production anchors cost position against API price volatility. For New Entrants and Emerging Players: Underpenetrated Southeast Asian markets for age-appropriate pediatric granules represent the most penetrable entry point, particularly Vietnam and Indonesia where national asthma screening programs scale diagnostic coverage. Direct-to-patient subscription models through telehealth-pharmacy platform partnerships offer the strongest go-to-market angle, bypassing fragmented retail pharmacy networks. For Investors and Strategic Acquirers: FDA boxed warning deliberations versus EMA risk minimization measure divergence reshapes the acquisition landscape, with European label preservation creating arbitrage value for formulation-specific assets. Long-term viability centers on pediatric delivery system capabilities and pharmacovigilance infrastructure rather than commodity tablet scale. CDSCO approval timeline acceleration for chewable variants signals inflection for pediatric-focused target valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO chewable variant certification accelerates pediatric market entry timelines. |
| Backward Integration | Captive quinoline intermediate production insulates margin from API price shocks. |
| Platform Integration | Telehealth-pharmacy subscription bundling locks in chronic patient retention. |
| Geographic Expansion | Southeast Asian granule launches exploit underpenetrated pediatric asthma programs. |
| Pipeline Diversification | Taste-masked oral disintegrating tablet hybrids address swallowing difficulty segments. |
Research Methodology
Desk research of FDA adverse event reporting databases, EMA periodic safety update repositories, and CDSCO approval filings preceded structured interviews with pediatric allergists, generic formulation development executives, and hospital pharmacy procurement directors. Primary fieldwork combined with secondary validation through Indian pharmaceutical export customs records, PLI scheme beneficiary disclosures, and clinical trial registries. Bottom-up demand modeling across patient age cohorts and formulation types triangulated against top-down API production capacity estimates.
Assumptions held fixed include current FDA neuropsychiatric labeling framework and Indian PLI subsidy continuity, while EMA risk minimization divergence and biologic therapy penetration rates varied across sensitivity scenarios. Segmentation dimensions encompassed formulation type, patient age tier, sales channel, and regional regulatory cluster. CAGRs derived from patient population growth, diagnostic coverage expansion, and formulation mix shift projections. Industry-specific inputs incorporated asthma prevalence epidemiology and pediatric medication adherence behavioral studies.
Macroeconomic conditions sit as an overlay; deviation in Indian rupee export competitiveness or API feedstock commodity pricing would shift the trajectory. Forecasts reflect these documented assumptions and modeled sensitivities. Material shifts in FDA boxed warning implementation or CDSCO bioequivalence certification timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Epilepsy Drug Market
Pharmaceuticals
Water for Injection Market
Pharmaceuticals
Global Specialty Pharmaceuticals Market
Pharmaceuticals
Middle-East and Africa Meglitinide Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Simvastatin Market
Pharmaceuticals
Neurological Disorder Drugs Market
Pharmaceuticals
Valsartan Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Croatia Pharmaceutical Market
Pharmaceuticals
Omeprazole and Antihistamine Market
Pharmaceuticals
Bispecific Antibody Therapeutics Contract Manufacturing Market
Pharmaceuticals
Pharmacy Dark Store Market
Pharmaceuticals
Migraine Drugs Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Peptic Ulcer Drugs Market