
 Castor Oil Market | 2026-2036
Castor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Castor Oil Market Intelligence
Buyer concentration among cosmetics multinationals is realigning procurement leverage toward contract growers with certified supply chains. Jayant Agro-Organics Limited anchors its position through backward integration into Gujarat's seed collection networks. Arkema SA differentiates via specialty polymer-grade derivatives for engineering plastics. Emery Oleochemicals GmbH operates integrated oleochemical complexes that sustain cost competitiveness in European markets.
Castor oil is a triglyceride derived from Ricinus communis seeds containing approximately 90% ricinoleic acid, extracted through mechanical pressing or solvent extraction followed by degumming and refining. The oil functions primarily as a bio-based feedstock for lubricants, surfactants, and polyurethane precursors. Cold pressed grades command premium positioning in cosmetic formulations where residual solvent content faces strict rejection. Hydrogenated castor oil represents the fastest-expanding product category as manufacturers seek oxidatively stable alternatives for coatings and greases. Biofuels application remains structurally constrained by feedstock competition from edible oils, though technical viability advances in aviation blend research.
REACH registration requirements in Europe mandate full toxicological dossiers for castor oil derivatives entering industrial chemical channels. India's BIS certification governs export-grade quality specifications for pharmaceutical and food-processing segments. The EU Green Deal's bioeconomy targets are redirecting public R&D funding toward non-food oilseed cultivation. Stakeholders must monitor evolving biodegradability certifications as downstream brands tighten scope-three emissions accountability.
Market Dynamics
Cosmetics formulators are consolidating procurement around certified seed-to-oil supply chains as REACH compliance tightens chemical feedstock traceability requirements across European industrial channels.
Growth Catalysts
- EU Green Deal bioeconomy targets:Public R&D funding redirects toward non-food oilseed cultivation, expanding castor acreage outside traditional monoculture zones.
- Hydrogenation process refinements:Oxidative stability improvements in hydrogenated castor oil are unlocking coatings and grease applications previously served by petroleum-derived alternatives.
- Aviation blend research:Technical viability advances in biofuel formulations sustain long-term offtake interest despite near-term feedstock competition constraints.
Market Restraints
- Seed supply concentration:Gujarat's collection networks dominate global raw material flows, creating geographic single-point vulnerability for price and volume stability.
- REACH toxicological dossier costs:Full registration requirements for derivatives entering industrial chemical channels impose fixed compliance burdens that disadvantage smaller compounders.
- Edible oil substitution economics:Palm and soybean oils maintain cost advantages in biofuel applications, structurally capping castor penetration in energy end-uses.
Strategic Opportunities
- Brazilian cultivation expansion:Favorable agroclimatic conditions in Minas Gerais and Bahia offer underexploited acreage for contract farming arrangements with cosmetics multinationals.
- Biodegradability certification premiums:Downstream scope-three emissions accountability is creating price differentiation for castor-derived surfactants in home care formulations.
- Cold-pressed cosmetic grade channel:Solvent-free extraction methods command positioning advantages in premium personal care where residual chemical content faces strict rejection thresholds.
Industry Challenges
- Skilled agronomist scarcity:Ricinus communis cultivation expertise concentrates in Gujarat, limiting knowledge transfer to new growing regions attempting supply diversification.
- Integrated oleochemical complex capex:Captive hydrogenation and refining capabilities require capital commitments that strain mid-scale processors competing against European and Indian majors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Castor Oil Market |
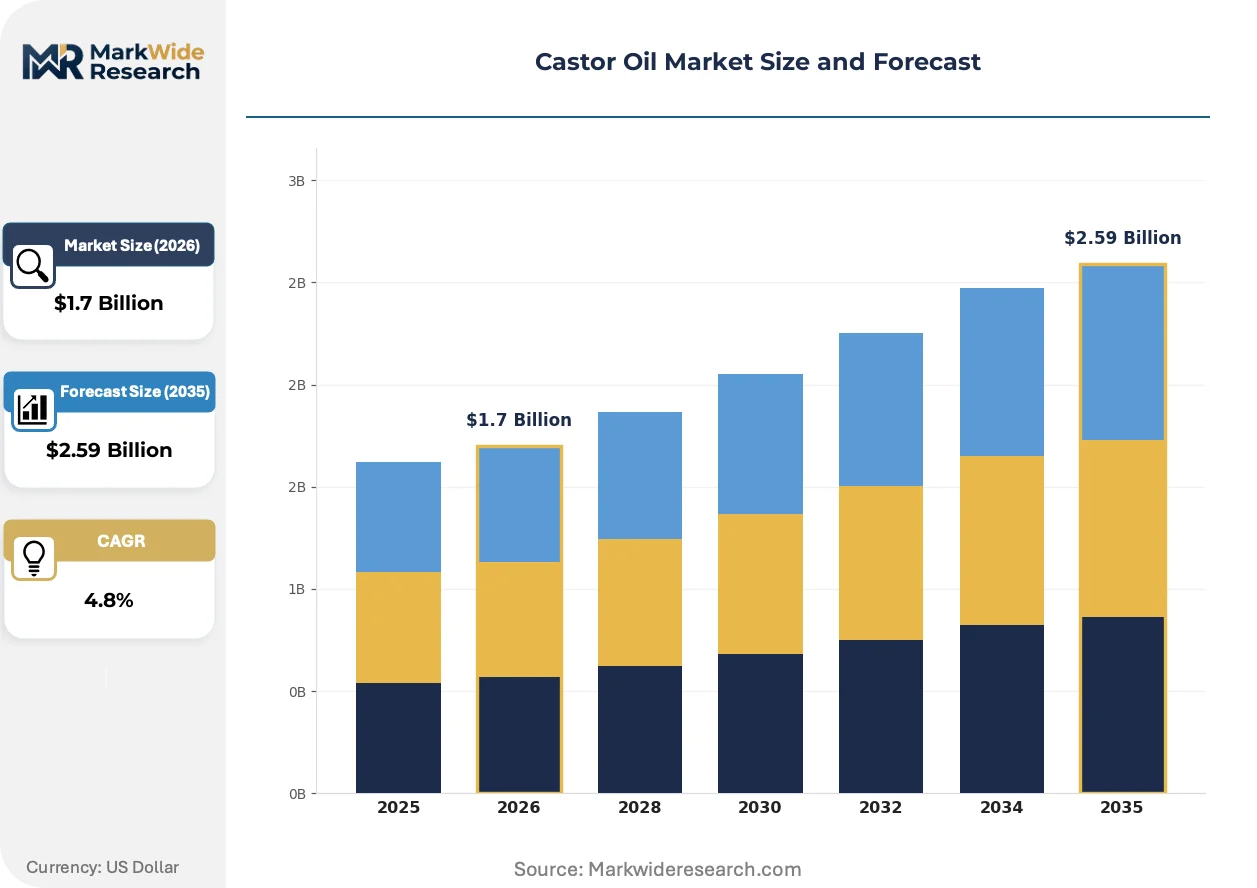
| Market Size in 2026 | $1.7 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Refined, Hydrogenated, Dehydrated End Use Industry: Cosmetics, Pharmaceuticals, Food Processing, Agriculture Application: Lubricants, Biofuels, Plastics, Coatings Packaging Type: Bottles, Drums, IBC Containers, Bulk |
| Companies Covered | Croda International PLC, NK Proteins Pvt Ltd., Arkema SA, Thai Castor Oil Industries Co., Gokul Agri International Ltd., Adani Wilmar Ltd., Emery Oleochemicals GmbH, Oleon NV, Jayant Agro-Organics Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Castor Oil Market Strategic Shifts & Innovations
Process intensification in seed crushing and derivative hydrogenation is compressing unit economics while regulatory pressure on petrochemical alternatives accelerates bio-based substitution timelines.
Supercritical CO2 extraction for pharmaceutical-grade castor oil is overtaking traditional mechanical pressing in high-purity applications. Specialty chemical manufacturers in Germany and Switzerland adopt the technology to eliminate solvent residues entirely. This shift is overtaking conventional refining infrastructure investments as the default capacity addition for new European facilities.
REACH registration requirements now mandate full substance identity documentation for castor oil derivatives entering polymer precursor channels. The European Chemicals Agency's dossier completeness checks have extended approval timelines for new market entrants. Specialty polymer compounders in the Netherlands and Belgium are responding by locking in multi-year supply agreements with established registrants to secure formulation continuity.
Direct contracting between cosmetics multinationals and certified seed collection networks is displacing spot market purchasing for cold-pressed grades. L'Oréal and Unilever procurement teams now specify blockchain-tracked provenance for emulsifier feedstocks. This pattern is most visible in French and German formulation facilities where scope-three emissions reporting has become a board-level compliance priority.
Castor Oil Market Segmentation
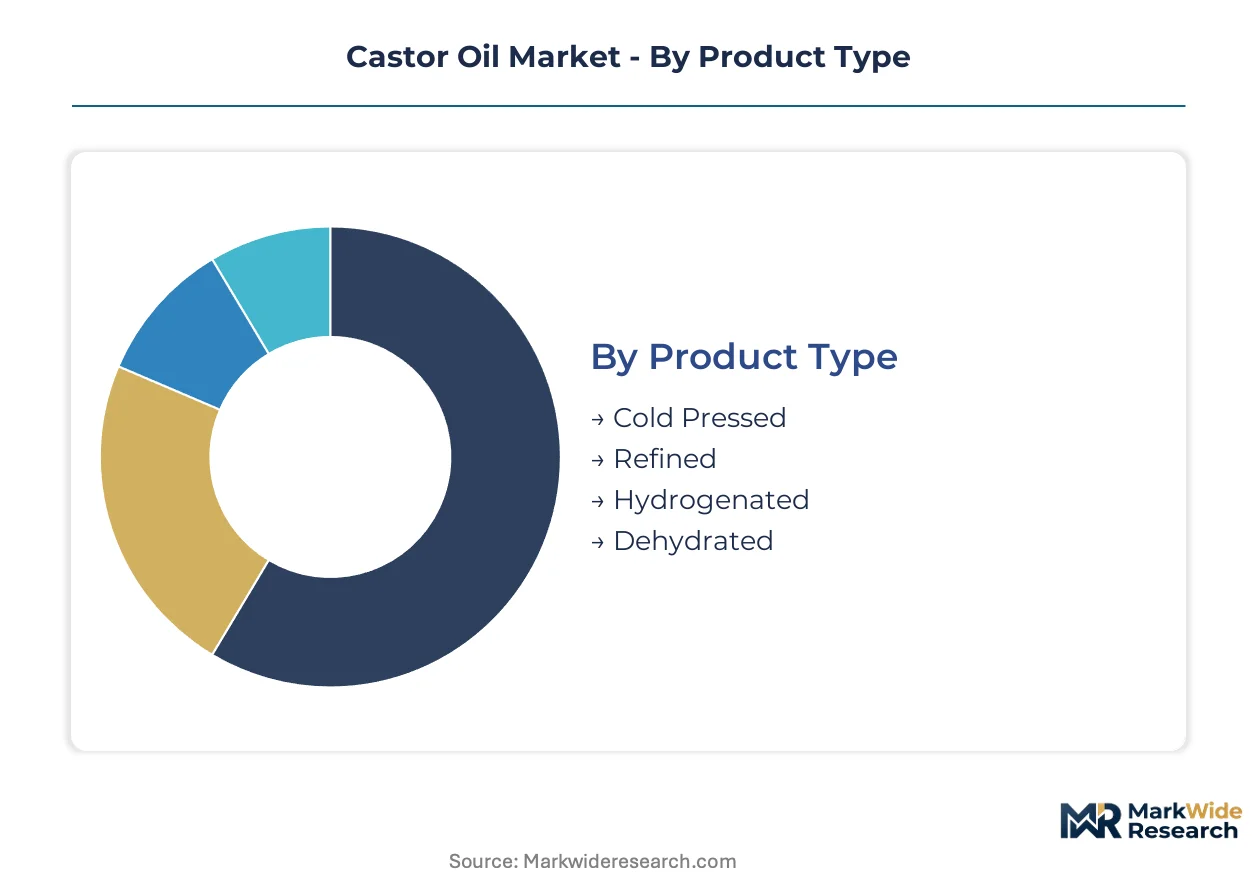
Castor oil's chemical versatility creates distinct value tiers across extraction methods and purity grades. Procurement teams segment purchases by end-use certification requirements and hydrogenation specifications rather than commodity pricing alone.
Product Type:
Capital intensity escalates sharply from mechanical pressing through catalytic hydrogenation, with solvent-free infrastructure commanding the highest upfront investment per ton of annual capacity.
- Hydrogenated:Catalytic hydrogenation of ricinoleic acid yields oxidatively stable waxes for coatings and grease formulations. German specialty chemical producers are expanding hydrogenation train capacity to serve automotive lubricant compounders seeking petroleum alternatives.
- Cold Pressed:Mechanical extraction at temperatures below 50°C preserves triglyceride integrity and eliminates solvent residues. French and German cosmetics formulators specify cold-pressed grades for facial oil formulations where residual hexane faces strict rejection under REACH substance identity requirements.
- Refined:Degummed and bleached oil meeting pharmaceutical and food-grade specifications. Indian BIS certification governs export quality for this segment.
- Dehydrated:Thermal processing removes hydroxyl groups to create drying oil precursors for alkyd resin production.
Most installed capacity flows through Refined. Expansion is steepest in Hydrogenated.
End Use Industry:
Customer concentration varies dramatically across end uses, with cosmetics multinationals consolidating procurement around three to five certified suppliers while agricultural buyers remain fragmented across hundreds of regional distributors.
- Cosmetics:Emulsifier and emollient applications in premium personal care. L'Oréal and Unilever procurement teams now mandate blockchain-tracked provenance for scope-three emissions reporting compliance.
- Pharmaceuticals:Laxative formulations and excipient applications requiring pharmacopeial-grade certification. Supercritical CO2 extraction is overtaking mechanical pressing for high-purity pharmaceutical supply.
- Food Processing:Food additive and flavor carrier applications governed by FSSAI specifications in India and EFSA requirements in Europe.
- Agriculture:Biopesticide formulations and organic fertilizer additives serving niche organic cultivation segments.
Cosmetics commands the highest unit margins. Pharmaceuticals is gaining share fastest on purity premium expansion.
Application:
Technical performance requirements segment castor oil derivatives by oxidative stability, viscosity index, and polyurethane reactivity rather than feedstock cost alone.
- Plastics:Polyol precursors for polyurethane foams and engineering thermoplastics. Arkema SA specializes in polymer-grade derivatives serving automotive interior applications.
- Lubricants:Bio-based base stocks and additive packages for hydraulic and metalworking fluids. Hydrogenated grades penetrate aviation blend research programs.
- Coatings:Alkyd resin and epoxy curing agent applications in industrial protective coatings.
- Biofuels:Aviation fuel blend research sustains long-term offtake interest despite near-term feedstock competition from edible oils.
Plastics absorbs the largest volume share. Lubricants shows the steepest climb on aviation sector technical validation.
Packaging Type:
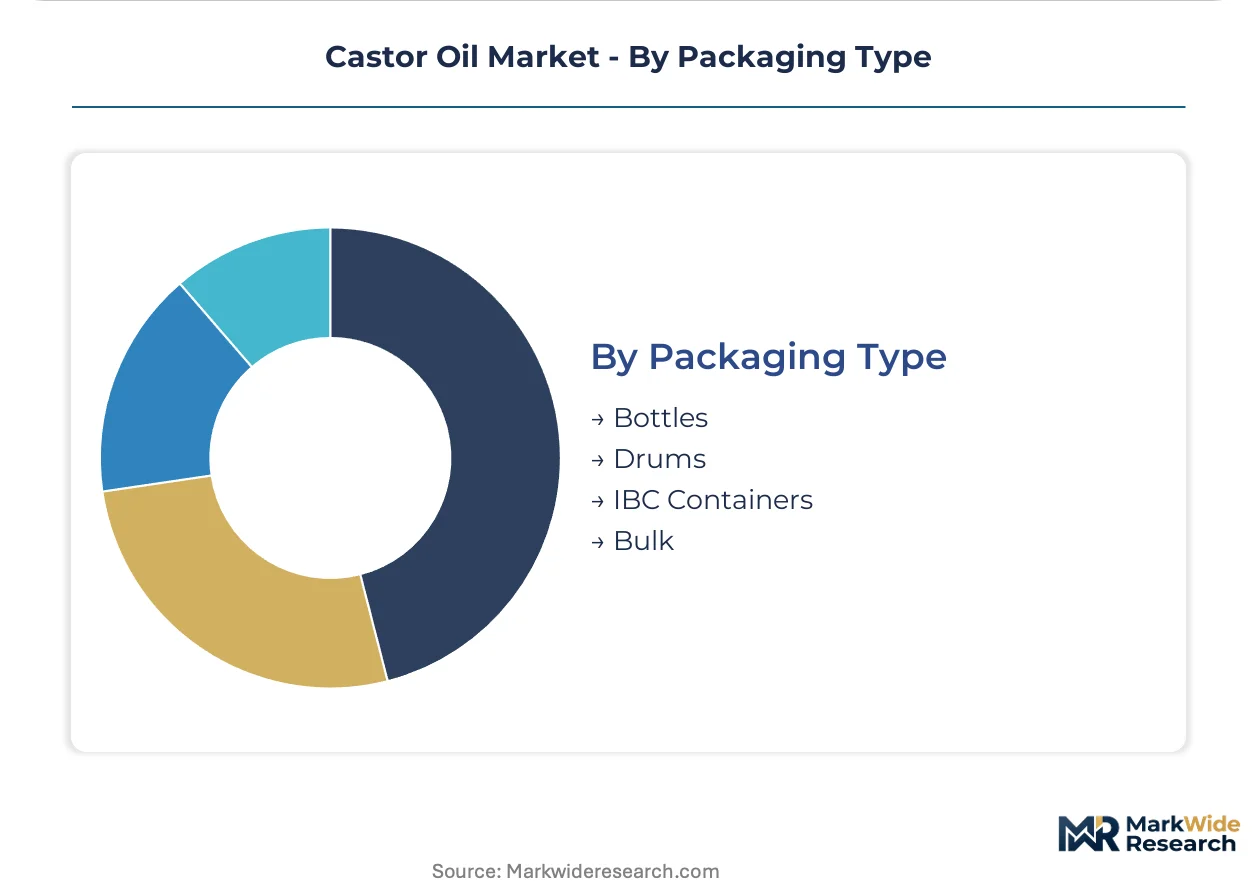
Handling economics and contamination risk segment packaging selection, with bulk infrastructure requiring dedicated tankage investments that exclude smaller compounders from direct mill procurement.
- Bulk:Tanker truck and railcar delivery for integrated oleochemical complexes and large-scale polymer producers. Emery Oleochemicals GmbH operates dedicated bulk handling at European port facilities.
- IBC Containers:Intermediate bulk containers serving mid-scale formulators requiring batch traceability without tank farm capital.
- Drums:Standard 200-liter steel drums for regional distributors and small-batch chemical processors.
- Bottles:Retail and sample packaging for cosmetic ingredient distributors and laboratory supply channels.
Bulk handles the greatest tonnage. IBC Containers is expanding most quickly on mid-scale processor procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India processes substantially more castor seed than any other nation, while Germany's specialty chemical sector drives hydrogenated derivative demand. Brazil cultivates expanding acreage but lacks integrated crushing infrastructure. This geographic split between raw material concentration and value-added processing defines competitive positioning.
India
Gujarat's Kutch and Saurashtra districts host the densest seed collection networks globally, with mechanical pressing clusters in Kadi and Palanpur supplying 85% of export-grade refined oil. The Bureau of Indian Standards mandates BIS IS 278:2017 certification for pharmaceutical and food-grade exports, tightening quality documentation for European-bound shipments. Jayant Agro-Organics anchors backward integration into village-level procurement cooperatives, securing volume commitments from 400,000+ farmers.
Germany
Specialty lubricant compounders in Hamburg and Cologne metropolitan areas absorb hydrogenated castor oil for automotive and aviation base stock formulations. REACH registration through ECHA requires full toxicological dossiers for derivatives entering polymer precursor channels, extending approval timelines for new market entrants. Emery Oleochemicals operates integrated hydrogenation trains at its Düsseldorf-area complex, serving coatings manufacturers seeking petroleum alternatives.
United States
Cosmetics formulators in New Jersey and California consolidate procurement around certified cold-pressed grades for premium personal care lines. FDA oversight of cosmetic ingredient safety intersects with state-level Prop 65 disclosure requirements for residual solvent content. Croda International's Delaware and New Jersey facilities process imported Indian feedstock into specialty surfactants for home care applications.
Brazil
Minas Gerais and Bahia states offer underexploited acreage with favorable agroclimatic conditions matching Ricinus communis cultivation requirements. ANVISA governs pharmaceutical-grade import specifications, creating regulatory familiarity for eventual domestic processing investments. Thai Castor Oil Industries and regional cooperatives pilot contract farming arrangements with cosmetics multinationals seeking supply diversification beyond Indian dependence.
France
L'Oréal's Paris-region formulation facilities mandate blockchain-tracked provenance for emulsifier feedstocks, driving procurement consolidation around certified seed-to-oil supply chains. The EU Green Deal's bioeconomy targets redirect public R&D funding toward non-food oilseed cultivation expansion. Arkema SA's specialty polymer-grade derivatives serve automotive interior applications from its Hauts-de-France production complex.
Castor Oil Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across extraction and derivative manufacturing tiers. The vendor base stratifies into three layers: integrated seed-to-derivative processors controlling Gujarat collection networks, European oleochemical complexes with captive hydrogenation capacity, and regional mechanical pressing operations serving spot markets. Strategic moves concentrate on backward integration into certified agriculture and forward integration into specialty polymer precursors.
Among Indian integrated processors, Jayant Agro-Organics Limited and Gokul Agri International Ltd. represent the backward-integrated archetype, anchoring procurement leverage through village-level seed collection networks. European specialists including Arkema SA and Emery Oleochemicals GmbH occupy positions defined by hydrogenation technology and REACH registration compliance, serving coatings and lubricant compounders with oxidatively stable derivatives. Thai Castor Oil Industries Co. exemplifies the geographic diversification play, attempting to replicate Indian supply chain structures in Brazilian acreage.
| Leading Market Players |
|---|
| Croda International PLC |
| NK Proteins Pvt Ltd. |
| Arkema SA |
| Thai Castor Oil Industries Co. |
| Gokul Agri International Ltd. |
| Adani Wilmar Ltd. |
| Emery Oleochemicals GmbH |
| Oleon NV |
| Jayant Agro-Organics Limited |
| Others |
Cost & Logistics Intelligence
Cold-pressed cosmetic grade premiums versus refined industrial feedstock discounts create a bifurcated value architecture that simultaneously rewards solvent-free extraction infrastructure in Gujarat and penalizes spot-market processors lacking certified seed-to-oil traceability. This divergence locks procurement contracts to BIS-certified collection networks while leaving unintegrated mechanical pressing operations exposed to price volatility from edible oil substitution economics.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for standard refined grades as contract farming pilots in Minas Gerais introduce marginal supply elasticity previously absent from Indian-dominated sourcing. Three-tier pricing structure across premium cold-pressed, standard refined, and economy dehydrated levels segments buyers by certification stringency and end-use performance requirements. Pricing pressure stems from REACH dossier compliance costs that compound fixed overheads for specialty derivative manufacturers serving European coatings compounders. Agricultural biopesticide formulators exhibit highest price sensitivity due to substitution elasticity with petroleum-derived surfactants, while cosmetics multinationals absorb premium differentials for blockchain-tracked provenance.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for oleochemical processing are reshaping sourcing patterns by incentivizing captive crushing capacity over export-raw-seed arbitrage. Geographic supply concentration centers on India, Brazil, and Thailand as cultivation expansion outpaces integrated infrastructure deployment in Latin American acreage. Raw material dependencies draw from Ricinus communis seed collection networks, hexane solvent for extraction, and hydrogenation catalysts for derivative upgrading. Single-source vulnerability concentrates in Gujarat's Kutch collection cooperatives, which anchor 85% of export-grade refined oil flows. Distribution runs through bulk tanker delivery to integrated European oleochemical complexes, IBC containers for mid-scale formulators, and drum packaging for regional spot market participants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Castor oil functions as a stable compounder anchored by irreversible bioeconomy substitution mandates in European industrial chemical channels that structurally displace petroleum-derived feedstocks regardless of near-term commodity price cycles.
For Market Incumbents: To counter Brazilian cultivation expansion threatening volume premiums, Jayant Agro-Organics and Gokul Agri International should deepen backward integration into seed genetics programs while locking multi-year offtake agreements with REACH-registered European compounders. Certification investment in BIS-IS 278:2017 pharmaceutical-grade capacity represents the priority defensive lever against supercritical CO2 extraction technology displacement in high-purity segments. For New Entrants and Emerging Players: Launch via contract farming arrangements with cosmetics multinationals seeking supply diversification beyond Indian dependence, targeting underexploited acreage in Bahia state where agronomic conditions match Ricinus communis requirements but crushing infrastructure remains absent. Cold-pressed cosmetic grade channels offer the most penetrable white space given strict solvent-free rejection thresholds that reward new supercritical CO2 extraction investments over legacy mechanical pressing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale Brazilian processors combining cultivation access with pending hydrogenation train investments that would unlock European coatings market entry. Long-term viability across the analysis window hinges on bioeconomy policy durability rather than feedstock cost parity. Acquisition targets should demonstrate captive seed collection networks or ECHA registration completion. The signal to watch is aviation blend technical validation milestones that would re-rate lubricant-grade derivative demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Collection Networks | Jayant Agro-Organics anchors procurement leverage through 400,000+ farmer cooperatives in Gujarat. |
| Hydrogenation Capacity Expansion | Emery Oleochemicals operates integrated trains at Düsseldorf serving automotive lubricant compounders. |
| Supercritical CO2 Extraction Adoption | German and Swiss manufacturers eliminate solvent residues for pharmaceutical-grade supply channels. |
| Blockchain-Tracked Provenance Implementation | L'Oréal procurement mandates chain-of-custody documentation for scope-three emissions compliance. |
| Brazilian Contract Farming Pilot Programs | Thai Castor Oil Industries replicates Indian supply structures in Minas Gerais acreage expansion. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with seed collection cooperative managers, oleochemical plant engineers, cosmetics procurement leads, and REACH regulatory consultants with secondary validation from BIS certification databases, ECHA registration filings, customs trade data, and EU Green Deal bioeconomy funding disclosures. Bottom-up triangulation across extraction method capacity installations and top-down reconciliation against end-use industry consumption patterns anchored volume estimates.
Historical reference periods spanning cultivation cycles through derivative hydrogenation lead times established baseline growth trajectories that were projected across the modeling period. Segmentation dimensions modeled include extraction grade tier, end-use industry concentration, hydrogenation specification, packaging format, and regional production hub clustering. CAGRs were derived from elasticity-adjusted demand curves incorporating bio-based substitution timelines and regulatory compliance cost trajectories. Forecast inputs integrated aviation blend research milestones and biodegradability certification adoption curves.
Several conditions sit outside the modeled scope, including extreme weather disruption to Gujarat monsoon patterns, abrupt REACH substance restriction amendments, and edible oil price shocks altering biofuel feedstock economics. Forecasts reflect documented assumptions regarding policy continuity and technology cost curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Global Seed Cotton Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Corn and Corn Starch Derivatives Market
Agricultural Commodities
Peat Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Alfalfa Powder Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Hermetic Food Grain Storage Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market