
 South America Feed Premix Market | 2026-2036
South America Feed Premix Market Size, Share, and Industry Trends Forecast 2026-2036
South America Feed Premix Market Analytics
ANVISA's updated veterinary residue monitoring protocols is recalibrating premix procurement across Brazilian integrators. Cargill Incorporated leverages its captive lysine fermentation capacity to secure cost-advantaged amino acid premix positions. Archer Daniels Midland Company (ADM) anchors South American supply through its Santos port terminal and regional blending network. BASF SE differentiates via carotenoid and enzyme premix technologies tailored to tropical heat stress conditions.
Feed premix denotes a homogeneous mixture of vitamins, minerals, amino acids, and functional additives dosed at 0.5% to 3% of finished feed weight, manufactured through sequential dilution and coating processes to ensure micronutrient stability during pelleting and storage. Its primary purpose is to deliver precise, uniform nutrient density that compensates for variable basal ingredient quality across commercial livestock operations. The poultry segment dominates volume due to Brazil's vertically integrated broiler chains, while amino acid premixes command margin premiums as synthetic lysine and methionine replace costlier protein meals. Mineral premixes sustain baseline demand across ruminant operations in Argentina's Pampas grazing zones.
ANVISA, Brazil's Ministry of Agriculture (MAPA), and Argentina's Senasa collectively enforce maximum residue limits, premix label accuracy, and import certification requirements that determine market access for both domestic blenders and imported concentrate suppliers. Compliance with these frameworks now requires batch-level traceability systems that elevate operational costs for smaller regional mills. Stakeholders must weigh backward integration into vitamin synthesis against sourcing flexibility as trade policy volatility reshapes input cost structures.
Market Dynamics
ANVISA's tightened veterinary drug residue protocols are forcing Brazilian integrators to rebuild premix sourcing around batch-level traceability, compressing supplier margins while elevating compliance costs for regional mills.
Growth Catalysts
- Precision nutrition protocols:Broiler integrators in Brazil's southern states are deploying amino acid premixes to optimize feed conversion ratios. Contract farming density supports centralized manufacturing scale.
- ANVISA residue monitoring expansion:The regulator's updated maximum residue limit enforcement is mandating reformulation with documented micronutrient sources. Mills must upgrade quality systems to maintain market access.
- Tropical heat stress mitigation:Carotenoid and enzyme premix technologies are penetrating poultry operations across Argentina's Pampas. Functional additives address oxidative stress in high-temperature production zones.
Market Restraints
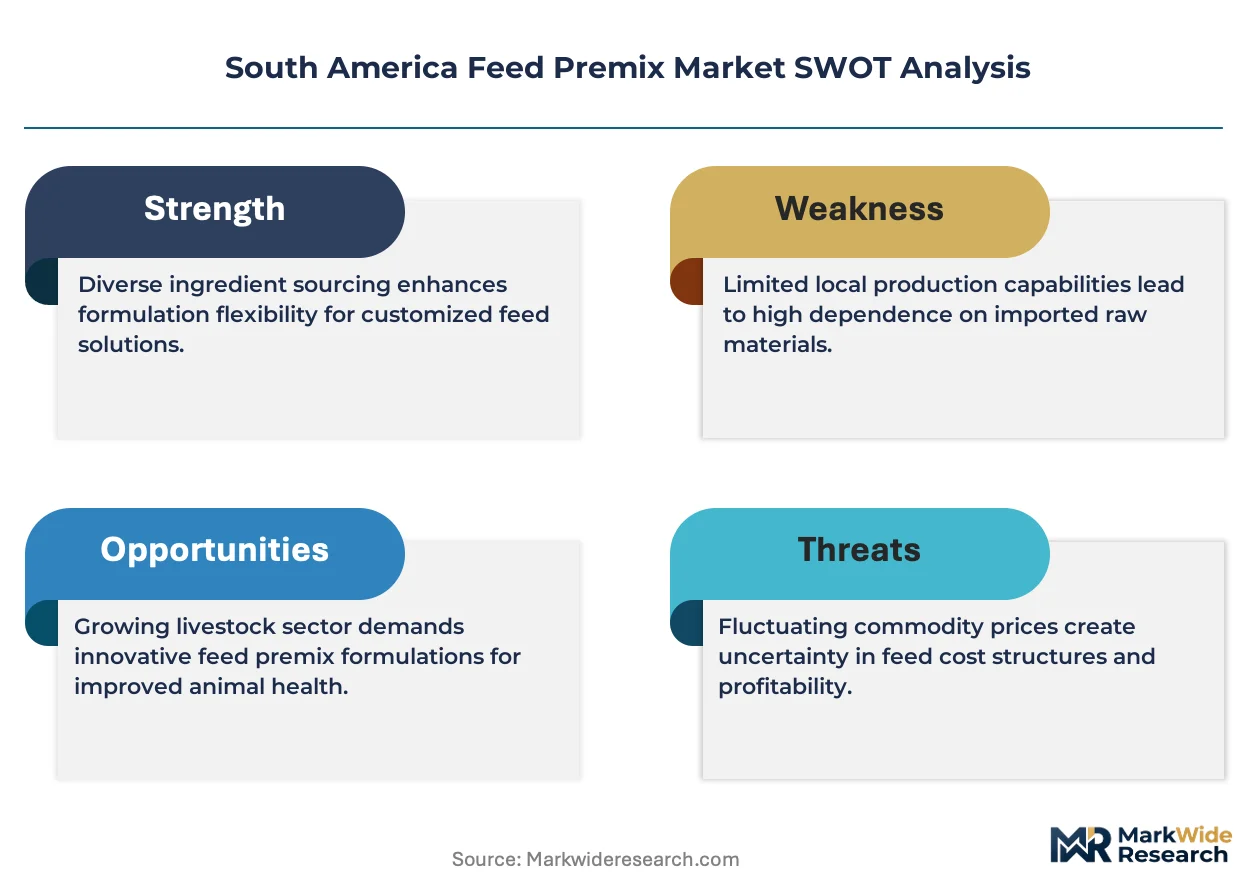
- Synthetic amino acid input volatility:Lysine and methionine pricing swings compress premix blender margins. Brazilian mills face margin pressure when protein meal alternatives spike.
- Import certification friction:Argentina's Senasa documentation requirements delay concentrate shipments from extra-regional suppliers. Border processing extends working capital cycles.
- Basal ingredient variability:Corn and soybean meal quality fluctuations in South American harvests force continuous premix recalibration. Micronutrient stability suffers from inconsistent carrier substrates.
Strategic Opportunities
- Uruguayan dairy expansion:Mineral premix demand is rising in the country's expanding intensive dairy sector. Ruminant nutrition precision lags poultry, creating white space for micronutrient suppliers.
- Backward integration into vitamin synthesis:Captive fermentation capacity for B-vitamins insulates blenders from import tariff volatility. Brazilian industrial policy favors domestic biotechnology investment.
- Digital traceability platforms:Blockchain-linked batch documentation aligns with ANVISA audit requirements. Early adopters capture integrator contracts from compliance-lagged competitors.
Industry Challenges
- Skilled formulation talent scarcity:Brazilian universities produce insufficient precision nutrition specialists. Mills compete for veterinarians with pharmaceutical and food safety sectors.
- Legacy equipment retrofit costs:Regional blenders face capital outlays for coating and sequential dilution systems. Microencapsulation upgrades strain sub-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Feed Premix Market |
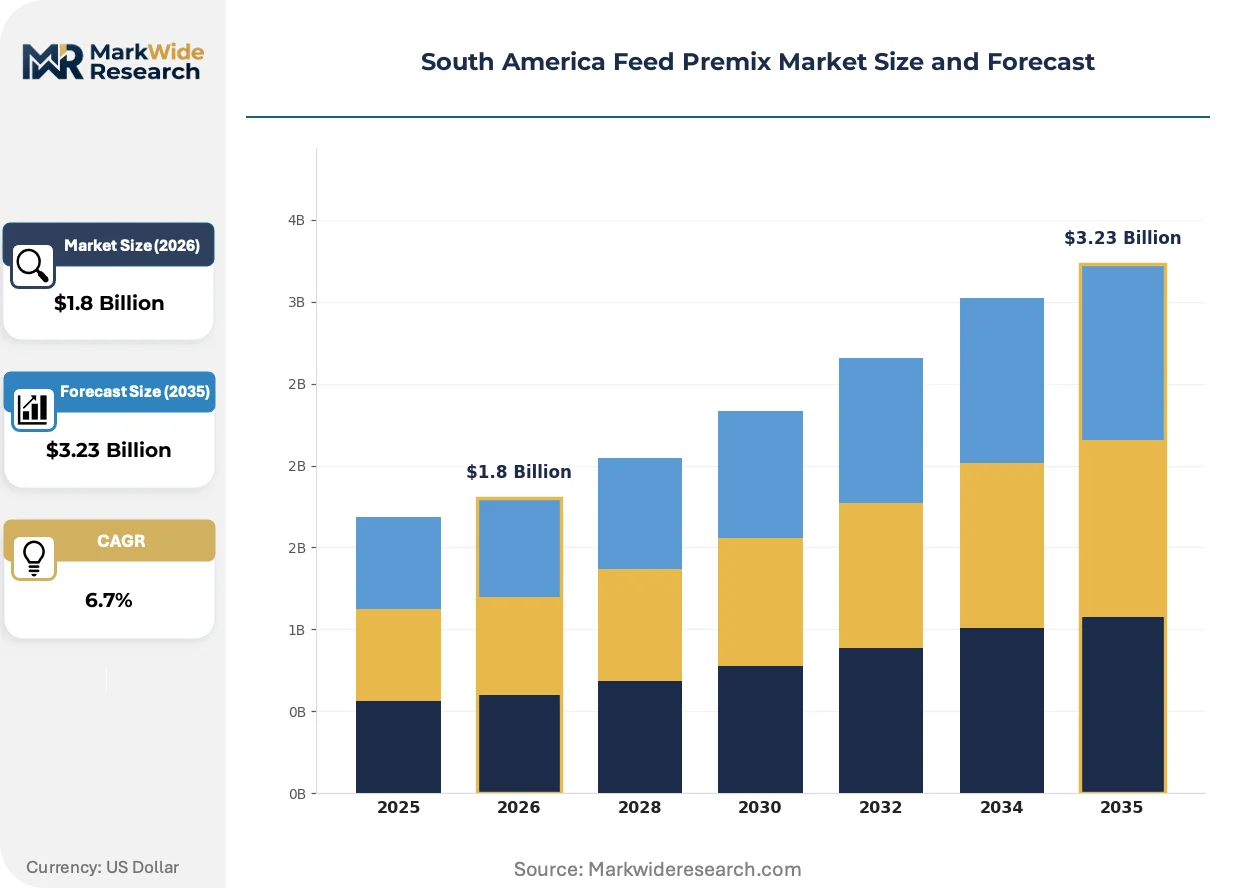
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Poultry, Swine, Ruminants, Aquaculture Ingredient Type: Minerals, Vitamins, Amino Acids, Preservatives Packaging Type: Bulk, Bagged, Canned, Sachets End User: Farmers, Feed Mills, Cooperatives, Distributors |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company (ADM), BASF SE, Alltech, Kemin Industries Inc, Nutreco, CCPA GROUP, ICC, Biomin, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Feed Premix Market Evolving Landscape
Digitalization of quality assurance and climate-adaptive formulation are converging to reshape premix manufacturing economics across Brazilian and Argentine feed corridors.
Near-infrared spectroscopy coupled with automated dosing systems is automating real-time micronutrient verification in Brazilian mill operations. Large integrators in Paraná and Santa Catarina are deploying these platforms at greenfield facilities. The technology is automating batch consistency checks that previously required manual laboratory sampling, compressing quality control labor costs by half.
ANVISA's 2023 veterinary residue monitoring protocol expansion mandates quarterly third-party audits of premix traceability systems. Brazilian mills must now document vitamin and mineral sourcing back to synthesis origin. Poultry operations in the country's southern corridor are accelerating supplier consolidation to reduce audit complexity.
Integrator procurement departments are consolidating premix contracts under three-year framework agreements with penalty clauses for residue violations. Spot purchasing through independent distributors is contracting in Brazil's broiler belt. The shift is most visible among the top ten poultry producers, who now specify batch-level blockchain documentation as a contract prerequisite.
South America Feed Premix Market Segmentation
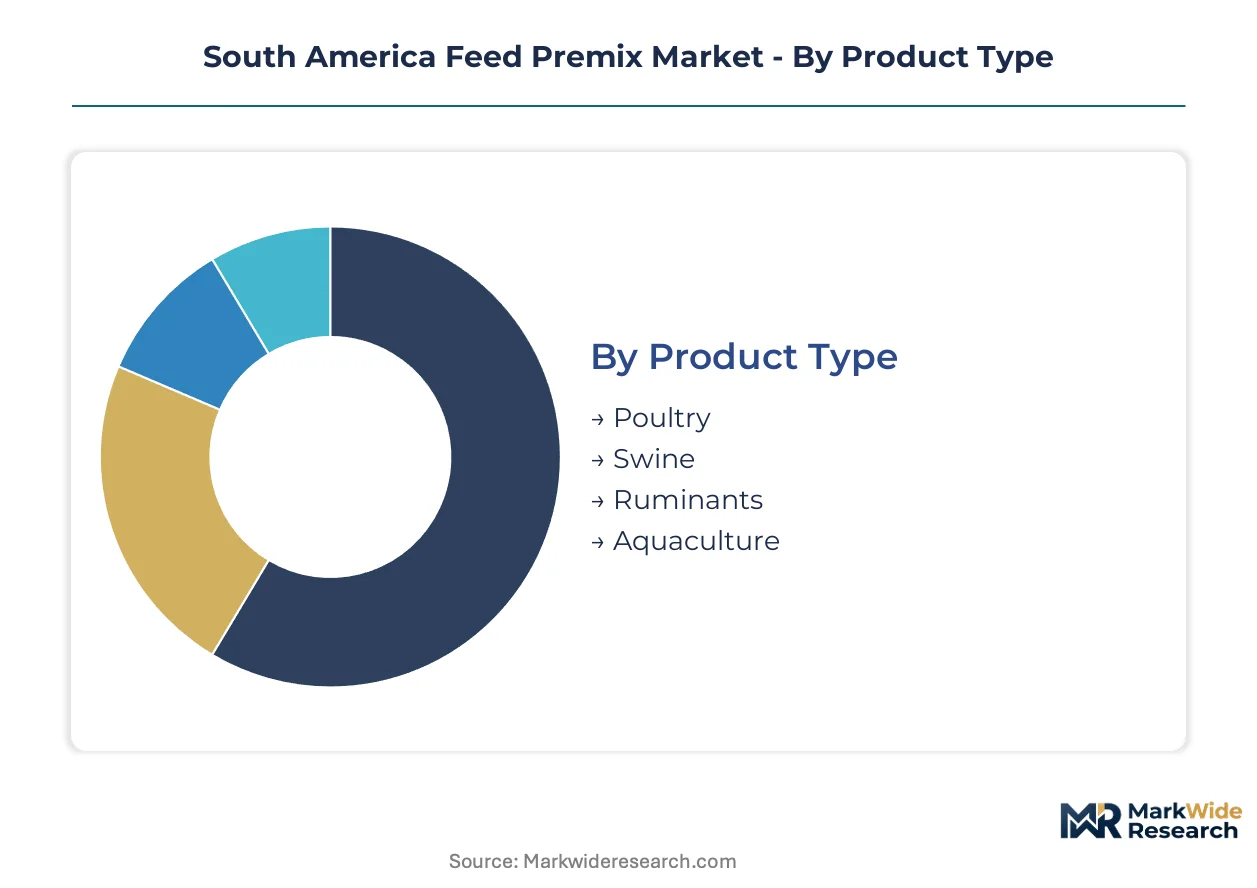
Feed premix segmentation in South America tracks closely with livestock production intensification patterns and regulatory compliance requirements. Understanding these divisions reveals where micronutrient precision commands premium positioning versus commodity supply.
Product Type:
Species-specific formulation requirements determine blending complexity and margin structure across Brazilian and Argentine production zones.
- Poultry:High-density vitamin and amino acid matrices support rapid growth phases in vertically integrated Brazilian broiler operations. Southern state integrators in Paraná and Santa Catarina specify heat-stable formulations for tropical conditions.
- Swine:Phytase-enriched premixes address phosphorus digestibility in corn-soy diets common across Brazilian pork production. Sow phase feeding demands precise trace mineral splits that elevate formulation sophistication.
- Ruminants:Mineral-dense premixes target Argentina's Pampas grazing operations where copper and selenium deficiencies persist. Beef backgrounding in Uruguay drives ionophore premix demand.
- Aquaculture:Specialized carotenoid and astaxanthin premixes serve Chilean salmon farms and emerging Brazilian tilapia ponds. Water-soluble vitamin stability requirements exceed land-animal specifications.
Mature deployment sits with poultry. Newer deployment is concentrated in aquaculture.
Ingredient Type:
Input cost volatility and synthetic substitution economics shape procurement priorities across South American mill operations.
- Minerals:Chelated trace elements (zinc, manganese, copper) command premium positioning in high-performance poultry and dairy rations. Argentine ruminant operations sustain baseline inorganic mineral demand across extensive grazing systems.
- Amino Acids:Crystalline lysine and methionine premixes displace soybean meal protein in Brazilian broiler cost optimization. Synthetic threonine and tryptophan penetration lags lysine-methionine pairs due to price elasticity.
- Vitamins:Stability-coated fat-soluble vitamins (A, D, E, K) address pelleting temperature degradation in tropical manufacturing. ANVISA documentation requirements now mandate synthesis-origin traceability for vitamin premix imports.
- Preservatives:Organic acid and antioxidant premixes extend finished feed shelf life in humid Brazilian storage conditions. Mycotoxin binder inclusion rates fluctuate with regional corn harvest quality.
Volume leadership belongs to minerals. Value capture concentrates in amino acids.
Packaging Type:
Scale of operation and inventory turnover velocity determine packaging economics across the supply chain.
- Bulk:Tanker and silo delivery systems serve major Brazilian integrators with dedicated mill infrastructure. Minimum order thresholds exclude smaller cooperatives from bulk pricing tiers.
- Bagged:Multiwall paper and woven polypropylene bags dominate mid-scale feed mill procurement across Argentina and Uruguay. Twenty-five kilogram units balance handling efficiency with inventory flexibility.
- Canned:Hermetically sealed metal containers protect hygroscopic vitamin premixes in high-humidity coastal zones. Premium positioning reflects nitrogen-flush preservation technology.
- Sachets:Single-dose foil pouches target smallholder poultry operations in Brazil's northeast and Colombian backyard production. Unit economics constrain sachet penetration above five hundred bird flock sizes.
Consolidation favors bulk. Fragmentation sustains bagged.
End User:
Procurement sophistication and technical service requirements diverge sharply across customer categories.
- Farmers:Direct premix purchasing concentrates among large-scale dairy and beef operations in Argentina's Córdoba province. Technical support demands limit farmer self-formulation to simple mineral blends.
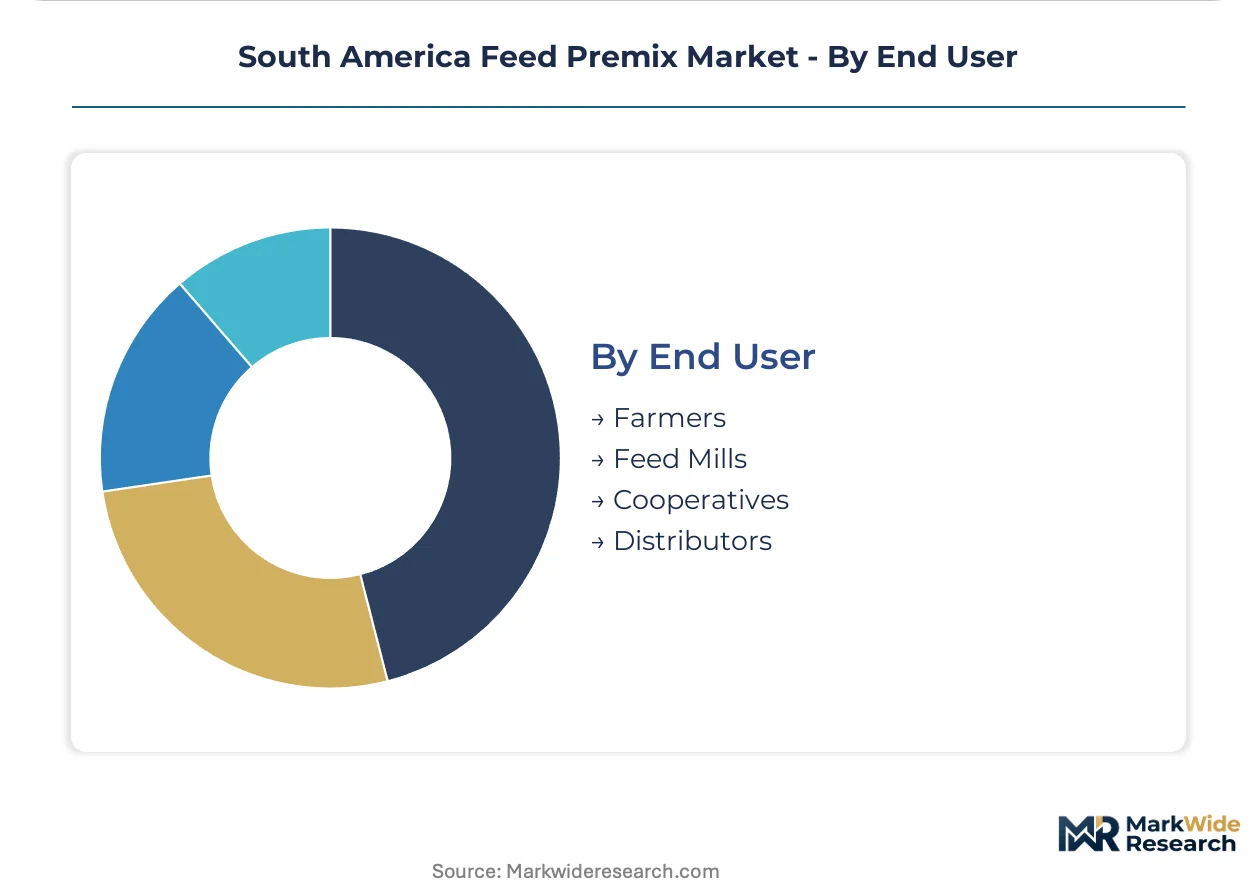
- Feed Mills:Independent Brazilian mills in Mato Grosso and Goiás represent the core volume channel, sourcing vitamin and amino acid premixes for custom formulation. ANVISA compliance investments favor larger mill consolidation.
- Cooperatives:Agricultural cooperatives in Rio Grande do Sul aggregate member demand for negotiated premix supply contracts. Shared technical staff reduce per-farm formulation expertise requirements.
- Distributors:Regional distributors serve fragmented poultry and swine producers in Colombia and Peru with stocked premix inventory. Working capital intensity constrains distributor geographic coverage.
Procurement centralization sits with feed mills. Procurement decentralization persists among farmers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Paraná's broiler belt concentrates South America's premix demand, where vertically integrated poultry operations in Toledo and Cascavel drive micronutrient procurement at industrial scale.
Brazil
São Paulo state's feed mill corridor consumes amino acid premixes for swine and poultry optimization. ANVISA's 2023 residue monitoring expansion mandates batch-level traceability for all imported vitamin concentrates. Southern integrators in Santa Catarina specify heat-stable formulations for tropical production conditions.
Argentina
Córdoba province's dairy and beef operations sustain mineral premix demand across intensive grazing systems. Senasa enforces import certification delays that extend working capital cycles for extra-regional concentrate suppliers. Rosario's agro-industrial cluster anchors blending capacity for Pampas ruminant nutrition.
Chile
Salmon farming operations in Los Lagos region deploy specialized carotenoid premixes for flesh coloration. Aquaculture feed mills in Puerto Montt source water-soluble vitamin matrices with stability specifications exceeding land-animal standards. National fisheries service regulations mandate documented additive provenance for export certification.
Uruguay
Intensive dairy expansion in Colonia and San José departments drives mineral premix adoption for precision ruminant nutrition. Cooperatives aggregate member demand for chelated trace element supply contracts. Montevideo's port infrastructure supports concentrate import logistics for domestic blenders.
Colombia
Poultry and swine production in Cundinamarca and Antioquia departments relies on distributor-stocked premix inventory for fragmented farm bases. Regional distributors face working capital constraints that limit geographic coverage expansion. Bogotá's feed manufacturing corridor serves as the primary blending hub for Andean operations.
South America Feed Premix Market Competitive Landscape
The competitive structure tilts toward multinational agricultural conglomerates with captive fermentation and port terminal assets. Brazilian and Argentine markets show moderate concentration at the top tier, with regional blenders occupying mid-scale positions. Three archetypes dominate: integrated agribusinesses with backward amino acid synthesis, specialized micronutrient technology licensors, and cooperative-affiliated domestic blenders. Capacity expansion and strategic port infrastructure anchoring represent the primary competitive vectors.
Within the integrated agribusiness tier, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven positioning through Santos port terminal operations and regional blending networks. BASF SE occupies a technology-specialist position, representing the functional additive archetype with tropical heat stress formulations. These three anchors demonstrate how multinational asset bases compete against cooperative-aligned domestic mills across Brazilian southern states and Argentine Pampas zones.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company (ADM) |
| BASF SE |
| Alltech |
| Kemin Industries Inc |
| Nutreco |
| CCPA GROUP |
| ICC |
| Biomin |
| Others |
Value Network & Pricing Analysis
Corn and soybean meal futures volatility cascades through South American premix supply chains into three-tier pricing structures across premium, standard, and economy levels. Brazilian integrators with captive lysine fermentation capacity capture margin insulation unavailable to regional mills sourcing synthetic amino acids on spot markets.
Pricing Analysis
Feed conversion ratio guarantees anchor value-based pricing for amino acid premixes in Brazilian broiler operations. Three-tier pricing separates heat-stabilized vitamin matrices from standard formulations and commodity mineral blends based on ANVISA traceability certification. Cost compression in economy-tier mineral premixes is intensifying because Argentine ruminant buyers prioritize volume scale over chelation quality. Smallholder cooperatives in Uruguay exhibit highest price sensitivity, while Chilean salmon farms accept premium positioning for astaxanthin stability specifications.
Supply Chain Analysis
Single-source vulnerability sits with Chinese crystalline lysine and methionine fermentation capacity that feeds Brazilian amino acid premix production. The supply chain draws from German vitamin synthesis clusters, Indian choline chloride manufacturers, and domestic Brazilian mineral processors. Tariff exposure on imported vitamin concentrates elevates working capital requirements for mills lacking backward integration. Distribution runs through Santos port terminal consolidation points into Paraná and Santa Catarina mill corridors, with cooperative-affiliated blenders in Rio Grande do Sul maintaining alternative import routes through Montevideo.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-capable scale players as ANVISA's batch-level traceability mandates force sub-scale regional mills toward exit or acquisition.
For Market Incumbents: Anticipate synthetic amino acid price volatility by securing captive fermentation capacity or long-term offtake agreements with Chinese suppliers. Defend integrator contracts through blockchain-linked batch documentation that exceeds ANVISA audit requirements, raising switching costs for competitors. Prioritize coating technology upgrades at greenfield Paraná facilities to capture heat-stable formulation premiums. For New Entrants and Emerging Players: Mid-scale dairy cooperatives in Uruguay's Colonia department represent underserved buyers lacking technical formulation support available to Brazilian poultry integrators. Penetrate this white space through mineral premix supply contracts bundled with veterinary nutrition consulting. Target Chilean aquaculture feed mills seeking water-soluble vitamin alternatives to incumbent European suppliers via stability-demonstration trials at Puerto Montt facilities. For Investors and Strategic Acquirers: Distressed-cycle entries favor cooperative-affiliated Brazilian mills in Mato Grosso facing ANVISA compliance capital requirements beyond their balance sheet capacity. These assets offer viable platforms for consolidation plays across Brazil's central-west feed corridor. Watch for inflection when ANVISA announces expanded veterinary residue testing protocols that accelerate smaller mill exits.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Synthesis | Captive B-vitamin fermentation insulates Brazilian blenders from import tariff volatility under industrial policy incentives. |
| Digital Traceability Platform Deployment | Blockchain-linked batch documentation aligns with ANVISA quarterly audit mandates and captures integrator procurement consolidation. |
| Heat-Stable Formulation R&D Investment | Tropical-adapted carotenoid and enzyme technologies command premium positioning in Santa Catarina poultry operations. |
| Cooperative Partnership Structuring | Shared technical staff models reduce per-farm expertise requirements in Uruguay's expanding dairy sector. |
| Port Terminal Capacity Anchoring | Santos infrastructure control secures cost-advantaged amino acid concentrate import logistics for southern Brazilian mill networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with feed mill procurement directors, veterinary nutritionists at Brazilian integrators, ANVISA compliance officers, and cooperative technical staff validated demand patterns. Secondary sources included MAPA production statistics, Senasa import certification databases, and port authority throughput disclosures. Bottom-up volume estimates from state-level feed production data triangulated against top-down premix consumption models derived from livestock population and intensification indices.
Data-stream reconciliation across the analysis window employed simultaneous equation modeling of amino acid inclusion rates, vitamin stability degradation curves, and mineral bioavailability coefficients. Segmentation dimensions tracked species-specific formulation complexity, ingredient type substitution elasticities, packaging scale economics, and end-user procurement sophistication. CAGRs were derived from trend extrapolation of broiler integration rates, dairy intensification trajectories, and regulatory compliance cost trajectories across the projection horizon.
Revisions become necessary when ANVISA modifies maximum residue limit protocols, when Brazilian trade policy shifts vitamin concentrate tariff structures, or when major integrators consolidate premix procurement under extended framework agreements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Aloe Vera Market
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
South America Feed Amino Acids Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
Marine Powder Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Growing Peat Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
North America Corn Glucose Market
Agricultural Commodities
Astrocaryum Murumuru Seed Butter Market
Agricultural Commodities
Cattle Feed Market
Agricultural Commodities
Cottonseed Hulls Market