
 Astrocaryum Murumuru Seed Butter Market | 2026-2036
Astrocaryum Murumuru Seed Butter Market Size, Share, and Industry Trends Forecast 2026-2036
Astrocaryum Murumuru Seed Butter Market Outlook
Specialty ingredient distribution is reconfiguring as cosmetic formulators bypass traditional importers to source directly from Amazonian processing cooperatives. Hallstar leverages its Latin American procurement network to secure consistent unrefined butter volumes. Jedwards International anchors its competitive stance through bulk wholesale channels serving mid-tier personal care manufacturers. Caribbean Natural Products differentiates by controlling small-batch refining operations in origin countries.
Astrocaryum murumuru seed butter is a hard, white-yellow lipid extracted from the seeds of the murumuru palm, with a melting point near 33°C and high lauric acid content exceeding 40 percent, rendering it structurally similar to coconut oil but with superior emollient stability in anhydrous formulations. The organic product type commands premium positioning among clean-beauty formulators seeking COSMOS-certified inputs, while unrefined grades retain volatile aroma compounds prized by niche aromatherapy brands. Refined murumuru butter dominates pharmaceutical applications where odor neutrality and standardized fatty acid profiles satisfy compendial requirements.
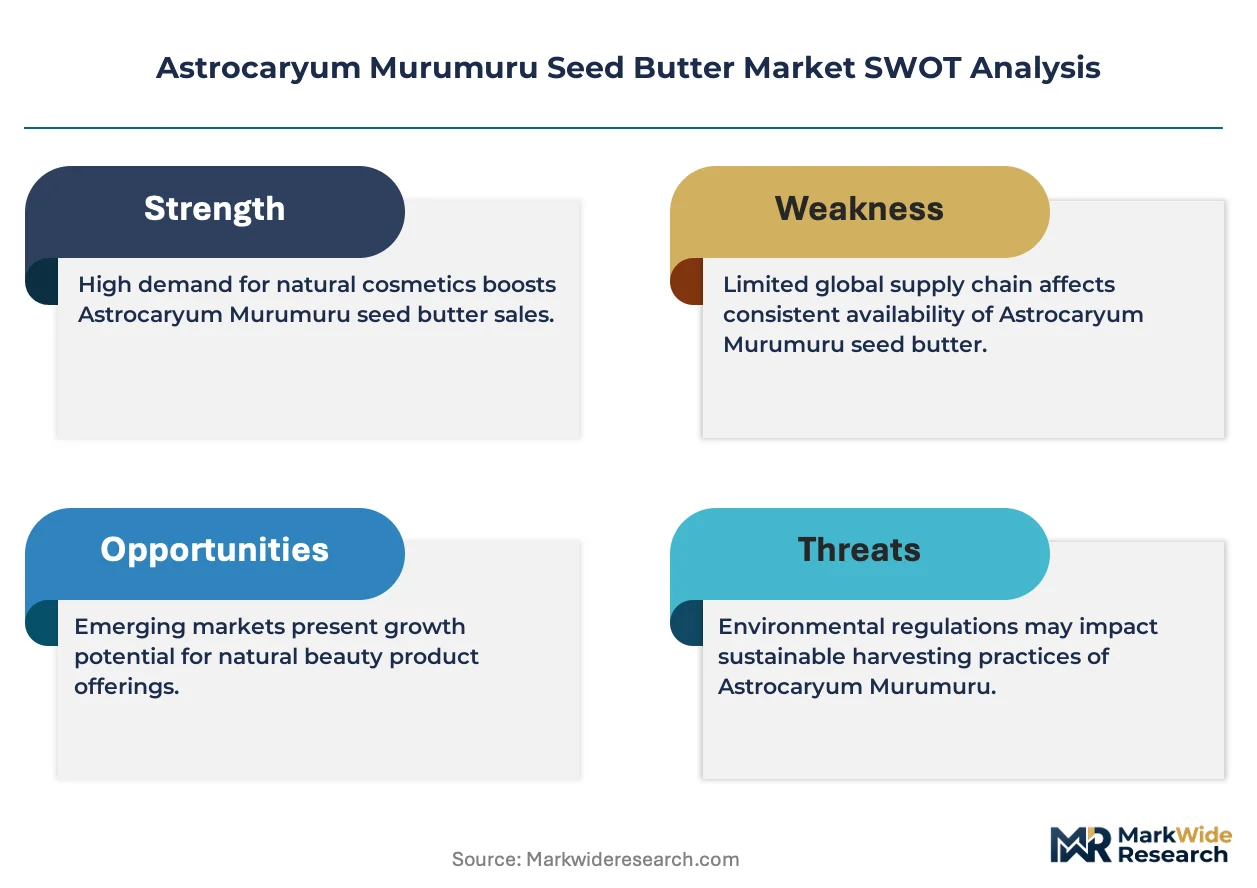
Brazil's ANVISA maintains strict cosmetic ingredient notification protocols that govern murumuru butter entry into regulated personal care supply chains, while EU REACH registration obligations compel European distributors to document full seed-to-butter substance dossiers. The US FDA exercises oversight through cosmetic labeling regulations under the Fair Packaging and Labeling Act, though murumuru butter remains exempt from pre-market approval as a botanical derivative. Stakeholders must weigh certification investments against channel-specific margin structures as regulatory fragmentation between major consuming jurisdictions intensifies compliance complexity.
Market Dynamics
EU REACH substance dossier requirements are forcing cosmetic formulators to restructure procurement relationships, bypassing commodity traders to secure documented seed-to-butter traceability from Amazonian cooperatives.
Growth Catalysts
- COSMOS certification uptake:Clean-beauty brands in France and Germany now mandate COSMOS-certified organic inputs, pulling premium-grade murumuru butter through validated supply chains.
- Shea butter price volatility:Formulators facing shea supply instability are accelerating technical trials of murumuru butter as a structurally similar emollient with superior oxidative stability.
- Pará state cooperative expansion:Sustainable harvesting collectives in Brazil's Amazon basin are scaling seed collection capacity to meet contracted volumes from European refiners.
Market Restraints
- Wild harvest dependency:Raw seed supply concentrates in seasonally floodable regions of the Amazon basin, exposing processors to climate-driven volume fluctuations.
- Refining capacity bottlenecks:Small-batch deodorization and bleaching infrastructure in origin countries limits output of pharmaceutical-grade refined butter.
- Fractionated coconut oil substitution:Cost-sensitive personal care manufacturers in mid-tier segments routinely specify fractionated coconut oil despite inferior emollient persistence.
Strategic Opportunities
- Pharmaceutical compendial adoption:USP and EP monograph development for murumuru butter would unlock prescription topical formulation channels currently served by petrolatum.
- Direct-to-formulator digital platforms:Amazonian cooperatives are piloting blockchain-traceable e-procurement portals that bypass traditional ingredient distributors.
- Japanese cosmetic ingredient recognition:METI's positive listing system for quasi-drug actives creates a regulatory pathway for murumuru butter in skin-barrier repair products.
Industry Challenges
- Phytosanitary certification timelines:Brazilian MAPA export documentation for untreated seeds creates 6-12 week procurement lead times that conflict with just-in-time manufacturing schedules.
- Analytical method standardization:Absence of harmonized GC-FID protocols for lauric acid quantification across laboratories complicates quality arbitration between buyers and sellers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Astrocaryum Murumuru Seed Butter Market |
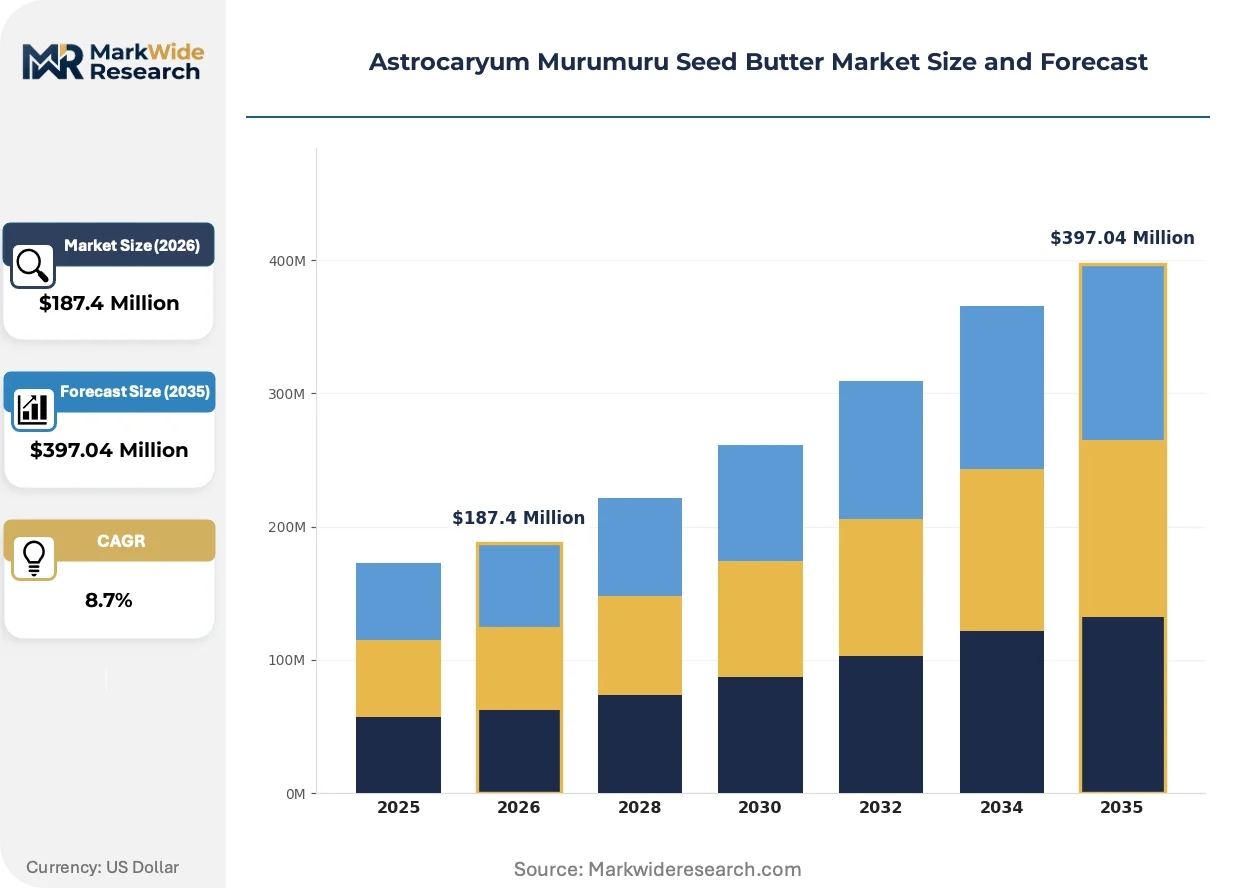
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Non-Organic, Refined, Unrefined Application: Cosmetics, Personal Care, Food Industry, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Manufacturers, Retailers, Consumers, Suppliers |
| Companies Covered | Hallstar, Parchem fine & specialty chemicals, Jedwards International, Vigon International, Natural Sourcing, Cosmetic Butters, Crafter's Choice Brands, Caribbean Natural Products, Amanaci Rohstoffe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Astrocaryum Murumuru Seed Butter Market Strategic Shifts
Cold-press extraction protocols are displacing traditional solvent-based methods across the Amazon basin, preserving heat-sensitive tocopherols while reducing residual solvent compliance burdens for EU-bound shipments.
Supercritical CO2 extraction technology is hybridizing with conventional mechanical pressing in Brazilian pilot facilities, enabling selective fractionation of murumuru butter into olein and stearin streams without thermal degradation. Specialty oleochemical manufacturers in São Paulo are adopting these hybrid systems to produce cosmetic-grade fractions with tailored melting profiles. The capital intensity of supercritical equipment is compressing competitive participation to processors with captive seed supply or long-term offtake agreements.
ECHA's 2023 updated guidance on natural substance UVCB registration is tightening documentation requirements for murumuru butter imported into EU cosmetic supply chains, compelling distributors to commission full analytical characterizations. The industrial consequence is a bifurcation between traders willing to invest in substance dossiers and those exiting the category. French and German formulators are responding by consolidating supplier relationships to entities with completed REACH registrations.
Ingredient procurement through cooperative-owned digital marketplaces is displacing traditional importer-distributor relationships for mid-tier personal care manufacturers. These platforms connect formulators directly to Pará-based harvester associations with lot-level traceability documentation. The channel shift is most visible among German natural cosmetics brands seeking to satisfy EU Green Deal supply chain due diligence requirements without intermediary markup.
Astrocaryum Murumuru Seed Butter Market Segmentation
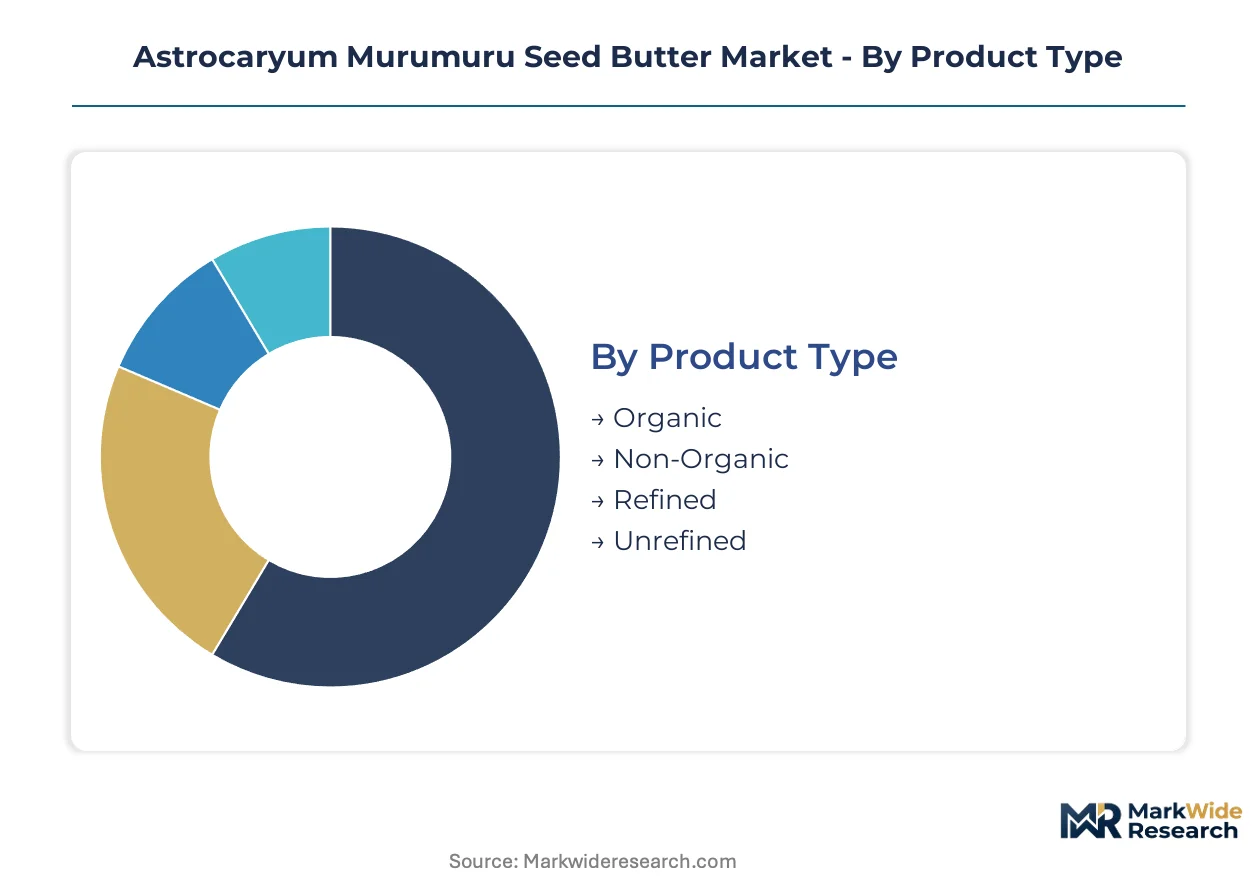
Ingredient certification grades and distribution channel selection directly determine margin capture for murumuru butter stakeholders. Formulators segment procurement strategies across organic credentials and refining intensity to match end-use regulatory requirements.
Product Type:
After-sales technical support intensity varies sharply across product grades, with organic and unrefined segments demanding traceability documentation and compliance advisory that refined commodity grades rarely require.
- Organic:COSMOS-certified grades command premium positioning among clean-beauty formulators in France and Germany. Supply contracts now mandate lot-level blockchain traceability from Pará state cooperatives to satisfy EU Green Deal due diligence obligations.
- Refined:Deodorized and bleached grades with standardized fatty acid profiles serve pharmaceutical compendial requirements where odor neutrality is mandatory. USP monograph development would unlock prescription topical channels currently blocked by analytical method gaps.
- Non-Organic:Conventional cultivation grades compete primarily on price against fractionated coconut oil in cost-sensitive personal care applications.
- Unrefined:Volatile aroma compounds retained through cold-press extraction attract niche aromatherapy brands seeking authentic Amazonian provenance markers.
Refined grades hold the largest share; momentum sits with organic certification as REACH documentation burdens intensify.
Application:
Cost tier stratification separates pharmaceutical-grade specifications from mass-market personal care absorption, with technical service requirements scaling directly with regulatory stringency.
- Cosmetics:Premium color cosmetics and skincare formulations leverage murumuru butter's superior emollient stability in anhydrous systems. French manufacturers anchor demand for validated organic inputs as ANSM tightens ingredient disclosure protocols.
- Pharmaceuticals:Compendial-grade refined butter targets barrier repair and dermatological applications where lauric acid content exceeds 40 percent. EP monograph absence currently blocks European prescription market entry.
- Personal Care:Mass-market lotions and hair conditioners specify unrefined or semi-refined grades based on price-positioning requirements.
- Food Industry:Edible-grade murumuru butter remains niche, concentrated in Brazilian domestic confectionery applications with ANVISA food additive clearance.
Cosmetics applications dominate current volume; pharmaceutical adoption represents the steepest expansion trajectory contingent on monograph standardization.
Distribution Channel:
Customer type concentration shapes channel economics, with manufacturer-direct procurement displacing traditional importer margins among mid-tier formulators.
- Wholesale:Bulk volume transactions from Amazonian processing cooperatives to European refiners anchor industry throughput. Hallstar and Jedwards International compete on procurement network depth and documentation capabilities.
- Online Retail:Cooperative-owned digital marketplaces with blockchain traceability are piloting direct-to-formulator sales, bypassing traditional distributor markups for German natural cosmetics brands.
- Specialty Stores:Small-batch refined butter for artisan cosmetic producers concentrates in São Paulo and Paris ingredient supply houses.
- Supermarkets:Limited presence restricted to finished personal care products containing murumuru butter rather than raw ingredient sales.
Wholesale channels capture the largest share; online retail platforms are gaining share fastest as traceability technology matures.
End User:
Volume concentration among manufacturers creates procurement power asymmetries that reshape upstream cooperative relationships.
- Manufacturers:Cosmetic and pharmaceutical formulators in France, Germany, and Brazil drive specification development and certification investment. Direct sourcing from Pará state cooperatives is consolidating supplier relationships among REACH-compliant distributors.
- Retailers:Natural products retailers and apothecary chains stock finished goods containing murumuru butter, with limited direct ingredient procurement.
- Consumers:DIY cosmetic formulators and aromatherapy practitioners purchase small-batch unrefined grades through specialty online channels.
- Suppliers:Seed collectors and primary processors in Brazil's Amazon basin function as captive supply sources for integrated refiners.
Manufacturers hold the largest share; supplier upstream integration is expanding most quickly as cooperatives develop in-house refining capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH substance dossier obligations are restructuring procurement geography as formulators seek documented seed-to-butter traceability from origin countries. Premium cosmetic manufacturers in France and Germany now mandate COSMOS-certified organic inputs with lot-level blockchain documentation from Amazonian cooperatives.
Brazil
Pará state cooperatives anchor raw seed supply as sustainable harvesting collectives scale collection capacity to meet contracted European volumes. ANVISA maintains strict cosmetic ingredient notification protocols governing murumuru butter entry into regulated personal care supply chains. São Paulo refiners pilot supercritical CO2 hybrid extraction systems enabling selective fractionation into cosmetic-grade olein and stearin streams.
Germany
Clean-beauty brands mandate COSMOS-certified organic murumuru butter through validated supply chains with full REACH documentation. ECHA's 2023 updated UVCB registration guidance compels distributors to commission complete analytical characterizations for natural substance imports. Natural cosmetics manufacturers in Hamburg and Berlin consolidate supplier relationships to entities with completed substance dossiers.
France
Premium color cosmetics formulators leverage murumuru butter's superior emollient stability in anhydrous systems as ANSM tightens ingredient disclosure protocols. ANSM cosmetic regulation enforcement drives specification development for documented Amazonian provenance. Paris-based ingredient supply houses concentrate small-batch refined butter distribution for artisan cosmetic producers seeking authentic origin markers.
United States
Personal care manufacturers specify unrefined and semi-refined grades based on price-positioning requirements for mass-market lotions and hair conditioners. FDA exercises oversight through cosmetic labeling regulations under the Fair Packaging and Labeling Act, though murumuru butter remains exempt from pre-market approval as a botanical derivative. Specialty ingredient distributors in New Jersey and California serve mid-tier formulators seeking bulk wholesale channels.
Astrocaryum Murumuru Seed Butter Market Competitive Environment
On the supply side, the industry is bifurcating between traders investing in REACH-compliant substance dossiers and those exiting the category under documentation burden. Procurement network depth in Latin America separates integrated refiners from commodity intermediaries. Two strategic archetypes dominate: Amazonian cooperative-owned processors controlling captive seed supply, and international distributors anchoring competitive stance through documentation capabilities and bulk wholesale infrastructure. Competitive moves concentrate on direct-to-formulator digital platform development and backward integration into origin-country refining operations.
Within the distributor tier, Hallstar leverages its Latin American procurement network to secure consistent unrefined butter volumes, while Jedwards International anchors its position through bulk wholesale channels serving mid-tier personal care manufacturers. Caribbean Natural Products exemplifies the cooperative-adjacent refining archetype by controlling small-batch deodorization and bleaching operations in origin countries. These three entities collectively represent the spectrum from international distribution scale to origin-country processing specialization.
| Leading Market Players |
|---|
| Hallstar |
| Parchem fine & specialty chemicals |
| Jedwards International |
| Vigon International |
| Natural Sourcing |
| Cosmetic Butters |
| Crafter's Choice Brands |
| Caribbean Natural Products |
| Amanaci Rohstoffe |
| Others |
Value Chain & Pricing Dynamics
Undercapacity at small-batch deodorization facilities in Pará state concentrates pricing power among integrated refiners while forcing commodity traders toward contract-based long-term offtake structures. European formulators absorbing REACH documentation costs pass through margin pressure to mid-tier buyers, compressing spot-market liquidity.
Pricing Analysis
Volume-discount tiering structures separate COSMOS-certified organic grades from semi-refined commodity streams, with certification investment and lot-level traceability documentation driving premium capture. Three-tier pricing structure across premium organic, standard refined, and economy unrefined levels reflects divergent compliance burdens. Cost compression in mid-tier segments intensifies as fractionated coconut oil substitutes erode technical differentiation. Mass-market personal care manufacturers exhibit highest price sensitivity; pharmaceutical formulators tolerate premium positioning for compendial-grade supply security.
Supply Chain Analysis
Contract-manufacturing concentration rests with São Paulo-based refiners and Pará state cooperative processing facilities, with Caribbean Natural Products anchoring small-batch capacity. Raw material flows draw from Brazil's Amazon basin, with secondary sourcing from Colombian and Peruvian harvester associations. Single-source vulnerability concentrates in seasonal flood-dependent wild collection zones. Distribution runs through wholesale bulk channels to European refiners, with cooperative-owned digital marketplaces piloting direct-to-formulator disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-traceable procurement platforms are disrupting traditional importer margins, creating asymmetric growth opportunities for REACH-compliant distributors and origin-country processors.
For Market Incumbents: Build documentation moats through completed EU REACH substance dossiers and captive seed supply agreements with Pará state cooperatives. Expand supercritical CO2 fractionation capacity in São Paulo to capture pharmaceutical-grade margin premiums. Consolidate supplier relationships among French and German formulators facing ANSM disclosure tightening. For New Entrants and Emerging Players: Japanese quasi-drug ingredient recognition under METI's positive listing system offers underpenetrated white-space for skin-barrier repair applications. Target pharmaceutical compendial adoption channels blocked by absent USP and EP monographs. Deploy direct-to-formulator digital platforms with blockchain traceability to bypass established distributor markups. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cooperative-owned processors with long-term offtake agreements and integrated refining capabilities. Five-to-ten year viability favors entities with backward integration into Amazonian seed supply and completed REACH registrations. Monitor ECHA guidance updates on natural substance UVCB documentation as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Substance Dossier Completion | Unlocks EU cosmetic supply chain access for Pará-based cooperatives facing ECHA compliance deadlines. |
| Supercritical CO2 Capacity Expansion | Enables São Paulo refiners to produce pharmaceutical-grade fractions with tailored melting profiles. |
| Blockchain Traceability Platform Launch | Allows Amazonian cooperatives to bypass traditional importer margins and satisfy EU Green Deal due diligence. |
| USP/EP Monograph Development | Opens prescription topical formulation channels currently served by petrolatum in dermatological applications. |
| Japanese Quasi-Drug Registration | Creates regulatory pathway for murumuru butter in METI-listed skin-barrier repair products. |
Study Parameters
Cross-validation between cooperative procurement managers and European cosmetic formulators anchors the qualitative findings on supply chain restructuring. Primary interviews with Pará state harvester association leaders, São Paulo refinery technical directors, and French ANSM regulatory consultants combined with secondary validation from ANVISA cosmetic ingredient notifications, ECHA REACH registration databases, and Brazilian MAPA export documentation records. Bottom-up seed collection volume estimates and top-down European import value triangulation constrain forecast ranges.
Calibration against historical COSMOS certification adoption curves and shea butter substitution elasticities shapes the analytical framework across the projection horizon. Segmentation dimensions span organic certification grade, refining intensity, application end-use, and distribution channel type. CAGRs derive from regression-weighted capacity expansion schedules and documented cooperative offtake agreements. Supercritical equipment deployment timelines and ECHA regulatory guidance evolution constitute industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by commodity traders investing in REACH compliance or pharmaceutical manufacturers accelerating monograph development would shift outcomes. Quarterly review of Pará state harvest volumes, ECHA substance dossier submission rates, and Japanese METI quasi-drug listing petitions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Feed Yeast Market
Agricultural Commodities
Global Wood Chips Market
Agricultural Commodities
Single Feed Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Soybean Derivatives Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Corn Hydrolysate Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Bladderpod Oil Market
Agricultural Commodities
Feed Sucrose Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Market
Agricultural Commodities
Cottonseed Meal Market
Agricultural Commodities
Roundwood Market
Agricultural Commodities
Hermetic Food Grain Storage Market