
 Global Seed Cotton Market | 2026-2036
Global Seed Cotton Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seed Cotton Market Foresight
Direct-to-farm digital procurement is reshaping how agricultural cooperatives and online platforms move certified seed cotton from breeders to growers. Bayer Crop Science leverages its TraitShield platform to anchor germplasm distribution across Brazil and India. Corteva Agriscience competes through its PhytoGen cotton seed portfolio, while Nuziveedu Seeds dominates India's open-pollinated and hybrid segments with extensive rural dealer networks.
Seed cotton comprises unginned cotton containing both lint and seed, typically harvested at moisture levels below 12 percent before mechanical ginning separates fibers from seeds for downstream textile and oil extraction uses. Upland cotton seed sustains volume leadership across temperate and subtropical growing belts due to its yield reliability and broad adaptability. Bt Cotton seed occupies premium positioning where bollworm resistance reduces pesticide applications, while organic seed varieties attract contracting premiums from sustainability-focused textile manufacturers and oil expellers seeking traceability certification.
The EPA regulates plant-incorporated protectants in genetically modified cotton seed across the United States, while India's CDSCO and BIS frameworks govern seed quality standards and germplasm import protocols. EFSA and REACH in Europe shape maximum residue limits and biocide approvals that affect seed treatment chemistries accessible to breeders. Stakeholders must monitor evolving gene-editing regulatory classifications as CRISPR-derived cotton varieties approach commercial readiness and threaten to redraw intellectual property and seed certification requirements.
Market Dynamics
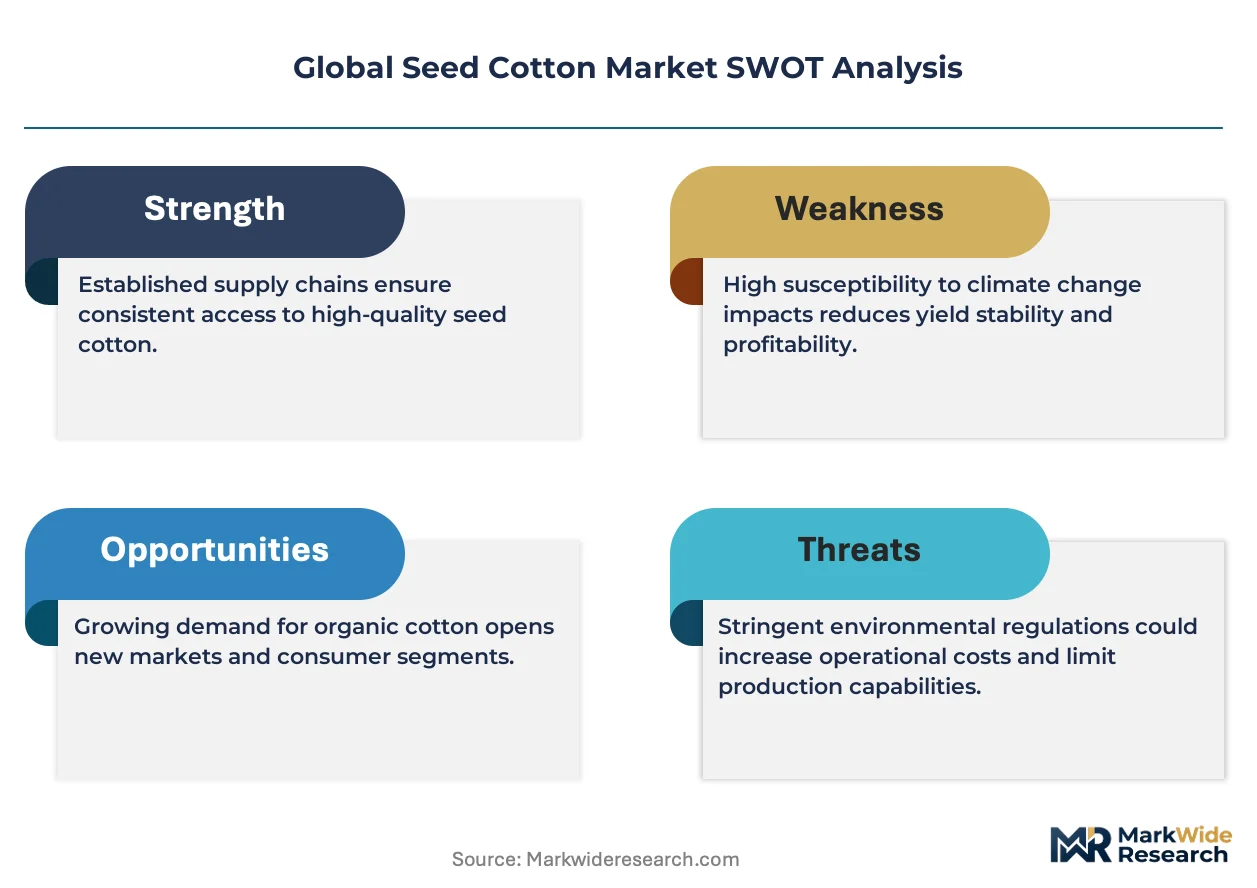
Direct-to-farm digital procurement platforms are compressing traditional breeder-to-grower distribution tiers, while gene-editing regulatory uncertainty around CRISPR-derived varieties threatens to fragment intellectual property frameworks and certification requirements across major cotton-producing jurisdictions.
Growth Catalysts
- India's PLI scheme:Textile value chain incentives redirect farmer procurement toward quality-assured planting stock, concentrating demand in Gujarat and Maharashtra as ginning infrastructure modernizes.
- Bt Cotton trait penetration:Bollworm-resistant germplasm reduces pesticide applications, lowering input costs for growers across temperate and subtropical belts.
- Organic certification premiums:Sustainability-focused textile manufacturers and oil expellers seek traceability-assured seed varieties, creating contracting price advantages for certified growers.
Market Restraints
- Seed treatment chemistry restrictions:EFSA and REACH maximum residue limits in Europe constrain biocide approvals accessible to breeders, limiting treatment options for export-oriented germplasm.
- Gene-editing regulatory ambiguity:Evolving CRISPR classification frameworks across EPA, CDSCO, and EFSA jurisdictions create intellectual property and certification timeline uncertainty.
- Input cost volatility:Fertilizer and fuel price fluctuations directly impact seed cotton production economics, squeezing margins for non-integrated growers.
Strategic Opportunities
- Brazilian germplasm expansion:TraitShield platform infrastructure enables direct breeder-to-farm distribution models in underpenetrated Cerrado cotton zones.
- CRISPR trait convergence:Gene-editing and marker-assisted breeding technologies accelerate drought-tolerance development for water-stressed growing regions.
- Blockchain traceability integration:Digital seed-to-textile tracking systems attract premium contracting from sustainability-certified textile supply chains.
Industry Challenges
- Regulatory compliance timeline compression:CDSCO and BIS seed quality standard updates require rapid germplasm retesting, straining breeder R&D schedules.
- Dealer network reconfiguration friction:Digital platform adoption disrupts established rural seed distribution relationships, creating channel conflict resolution costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seed Cotton Market |
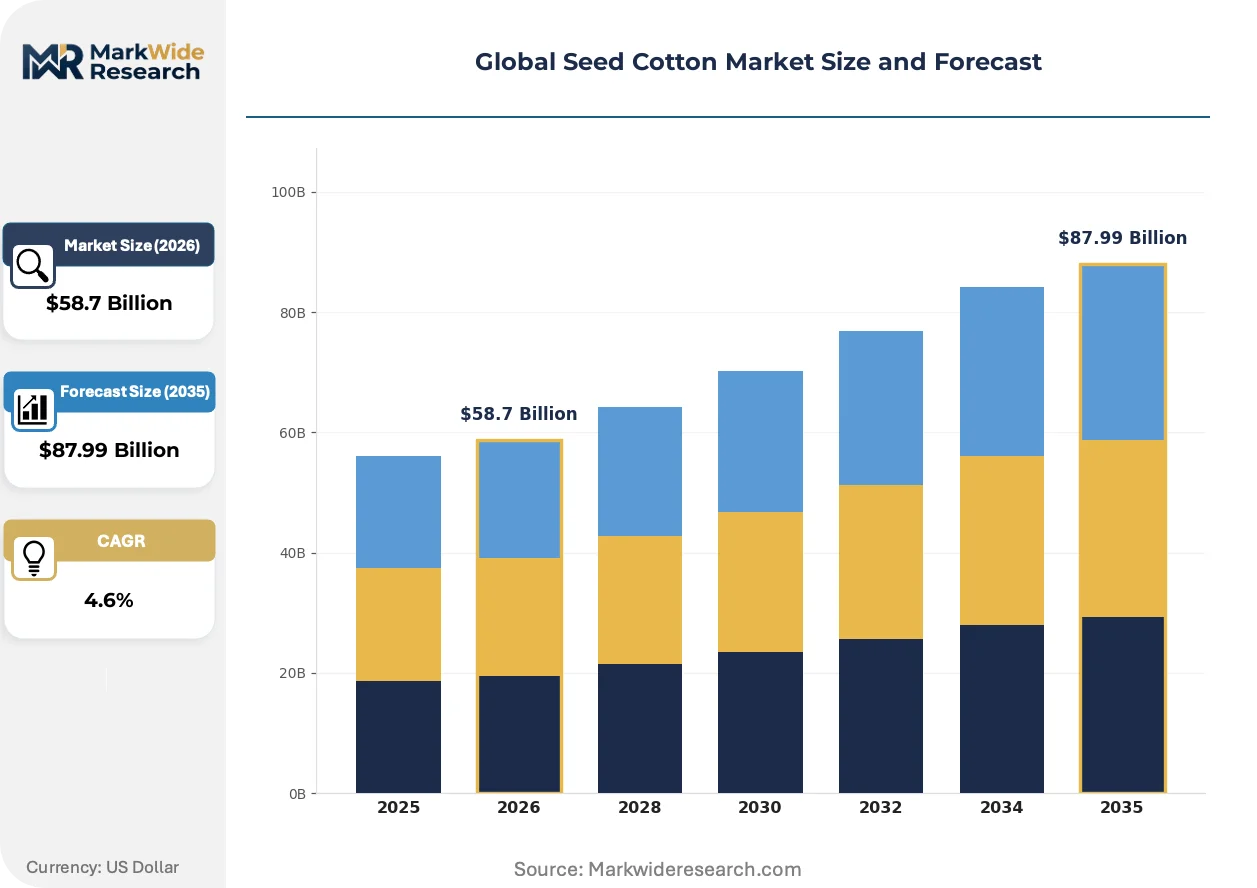
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $87.99 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Seed Type: Upland, Pima, Organic, Bt Cotton, Hybrid, Conventional Application: Textile Manufacturing, Oil Extraction, Animal Feed, Biofuel Production, Seed Production, Research End User: Spinning Mills, Oil Expellers, Feed Manufacturers, Bioenergy Firms, Agricultural Seed Companies, Research Institutes Distribution Channel: Wholesale Markets, Online Platforms, Agricultural Cooperatives, Retail Outlets, Direct Sales, Exporters |
| Companies Covered | Bayer Crop Science, Corteva Agriscience, BASF SE, Syngenta AG, Cargill, Inc., Nuziveedu Seeds Ltd., Kaveri Seed Company, Mahyco, Olam International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seed Cotton Market Shifts & Advancements
Gene-editing tools and digital distribution infrastructure are actively redrawing competitive boundaries between integrated breeding platforms and regional seed specialists, while sustainability certification requirements reshape downstream contracting structures.
CRISPR-Cas9 gene-editing is hybridizing conventional trait introgression timelines, enabling precise bollworm resistance and drought-tolerance stacking without transgenic regulatory burdens. Mid-size breeding programs in India and Brazil are adopting the technology fastest, compressing the historical five-to-seven-year variety development cycle into three-to-four-year windows and threatening to displace legacy backcrossing-dependent germplasm pipelines.
REACH and EFSA biocide approval frameworks are tightening seed treatment chemistry availability, forcing breeders toward biological and physical seed protection alternatives. The regulatory friction most acutely affects European export-oriented germplasm, where breeders are responding by accelerating investment in inherent pest-resistance genetics to reduce external treatment dependency.
Textile manufacturer sustainability mandates are rotating procurement preferences toward traceability-certified seed cotton, bypassing traditional commodity auction channels. Apparel brands in South Asia and Turkey now specify certified planting stock origins in spinning contracts, compressing the gin-to-mill verification chain and displacing anonymous bulk sourcing in premium fiber segments.
Global Seed Cotton Market Segmentation
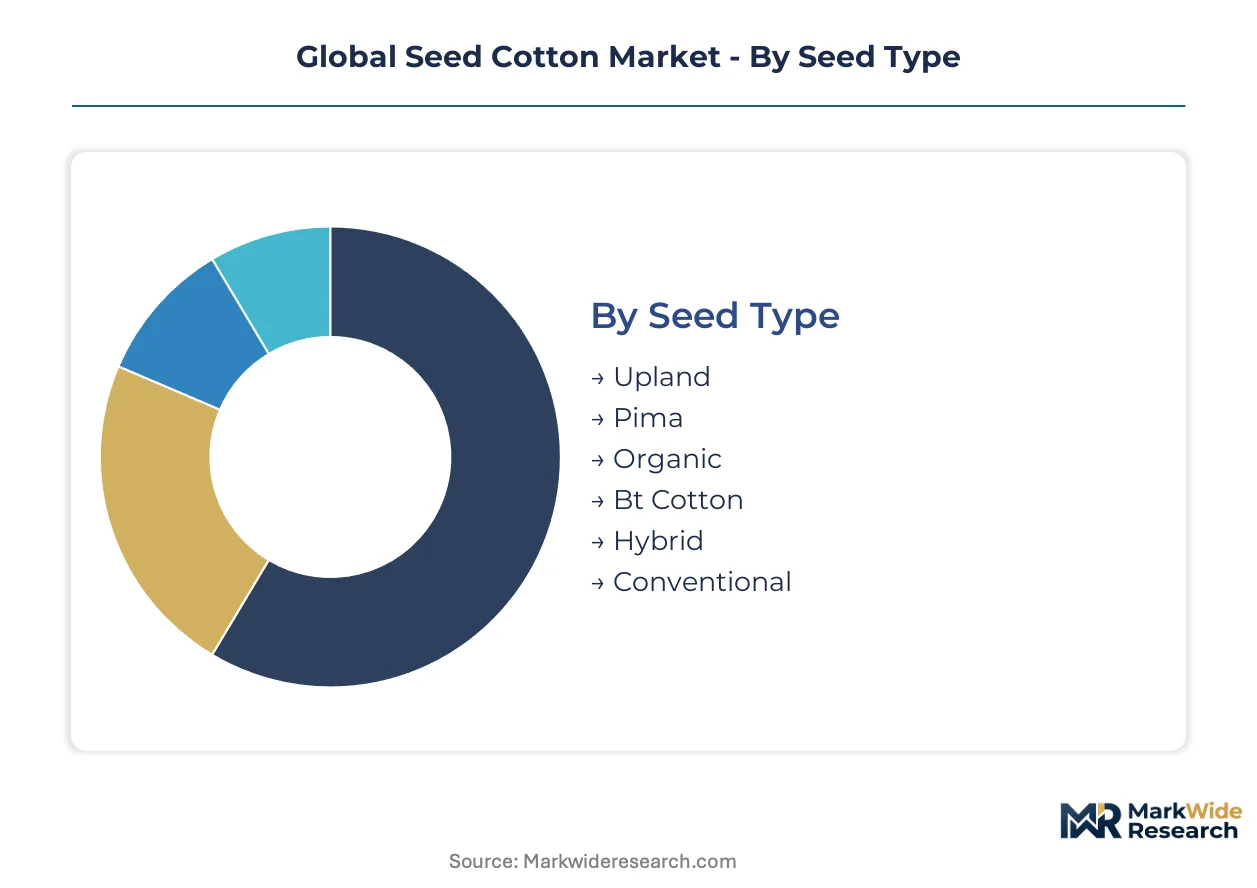
Seed cotton segmentation reveals divergent velocity profiles across breeding cycles, processing requirements, and procurement channels. Cycle time differentials between conventional open-pollinated varieties and gene-edited germplasm reshape inventory management and working capital structures for distributors.
Seed Type:
Upland and Bt Cotton varieties turn inventory fastest due to established regulatory pathways and broad farmer familiarity, while Organic and gene-edited segments face extended certification timelines that compress turnover metrics.
- Upland:Standard short-staple Gossypium hirsutum germplasm dominates temperate and subtropical planting belts through yield reliability and mechanical harvest compatibility. Demand concentrates in Gujarat and Maharashtra as India's PLI scheme redirects textile value chain procurement toward quality-assured stock.
- Bt Cotton:Transgenic varieties expressing Bacillus thuringiensis proteins deliver bollworm resistance without external pesticide applications. Adoption clusters in water-stressed districts where reduced spray schedules lower labor costs and fuel expenditures for growers.
- Pima:Extra-long staple Gossypium barbadense varieties command fiber length premiums in luxury textile spinning.
- Organic:Non-GMO, synthetic-input-free certified seed attracts sustainability-mandated contracting from traceability-focused apparel brands.
- Hybrid:First-generation crosses exploit heterosis for yield step-changes in intensively managed irrigated systems.
- Conventional:Open-pollinated varieties persist in marginal growing zones where seed saving reduces input costs for resource-constrained farmers.
Upland dominates installed base. Bt Cotton is where expansion concentrates.
Application:
Margin structures diverge sharply between fiber-first textile flows and seed-first oil extraction channels, with biofuel and research applications commanding premium pricing through specialized contracting.
- Textile Manufacturing:Gin-separated lint feeds spinning mills producing yarn for apparel and home textile end-uses. Demand from South Asian manufacturers accelerates as ginning infrastructure modernizes and contamination control standards tighten.
- Oil Extraction:Cottonseed crushing yields edible oil and meal for protein recovery. Oil expellers in India and Brazil scale processing capacity to capture byproduct value from expanding seed cotton volumes.
- Animal Feed:Delinted cake and hull fractions enter ruminant ration formulations after gossypol detoxification.
- Biofuel Production:Cottonseed oil transesterification supplies biodiesel blendstock for transport fuel mandates.
- Seed Production:Foundation and certified seed multiplication serves breeder-to-farmer distribution pipelines.
- Research:Germplasm accessions support trait discovery and variety development programs.
Textile Manufacturing captures the largest value share. Oil Extraction is climbing the fastest as crush capacity expands.
End User:
Procurement sophistication varies from spot-market commodity purchasing by feed manufacturers to multi-year contracting by integrated textile groups seeking origin traceability.
- Spinning Mills:Fiber buyers specify micronaire, length, and strength parameters in gin-direct procurement contracts.
- Oil Expellers:Crush operators optimize seed acquisition around oil content and free fatty acid profiles.
- Feed Manufacturers:Protein purchasers source delinted cake through commodity brokers and cooperative aggregators.
- Bioenergy Firms:Renewable fuel producers contract for oilseed feedstock under compliance credit frameworks.
- Agricultural Seed Companies:Breeder and distributor networks manage germplasm multiplication and certified seed distribution.
- Research Institutes:Public and private breeding programs access genetic diversity for trait introgression.
Spinning Mills anchor volume demand. Agricultural Seed Companies are gaining share fastest through direct-to-farm digital platforms.
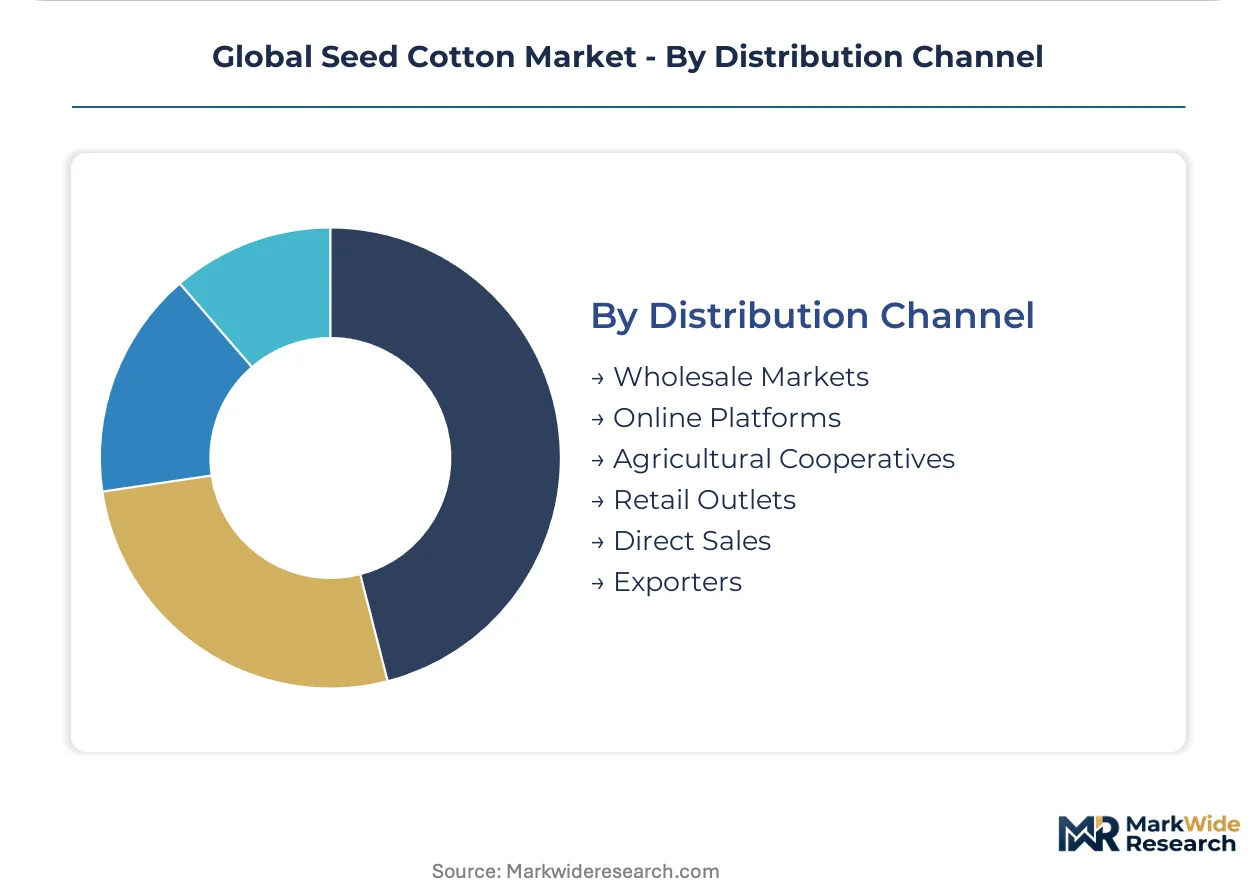
Distribution Channel:
Channel economics reflect working capital intensity and service requirements, with digital platforms compressing margins for traditional wholesale and retail intermediaries.
- Wholesale Markets:Aggregators and commission agents match bulk seed cotton supply with mill and expeller demand.
- Online Platforms:Digital procurement interfaces enable price discovery and logistics coordination between breeders and growers.
- Agricultural Cooperatives:Member-owned entities pool farmer purchasing power for certified seed and input acquisition.
- Retail Outlets:Rural dealer networks provide last-mile distribution and agronomic advisory services.
- Direct Sales:Breeder-to-farm contracts eliminate intermediary tiers for large commercial operations.
- Exporters:International traders manage phytosanitary certification and cross-border logistics for germplasm and lint shipments.
Wholesale Markets retain the deepest penetration. Online Platforms are expanding most quickly as TraitShield-type infrastructure scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian growers capture pricing premiums through the PLI scheme's quality-assured procurement channels, while Brazilian producers in Mato Grosso face compressed export margins from currency volatility and distant port logistics.
United States
Texas High Plains growers drive upland cotton volume through center-pivot irrigation and mechanized harvesting systems. The EPA regulates plant-incorporated protectants in transgenic varieties through its biopesticide registration framework. Lubbock anchors the domestic ginning and merchant infrastructure, with modernized facilities reducing contamination rates for export-oriented lint.
India
Gujarat and Maharashtra concentrate Bt Cotton adoption where bollworm resistance cuts pesticide expenditures for smallholder operations. CDSCO and BIS frameworks govern seed quality standards and germplasm import protocols, with recent updates accelerating certification timelines. The PLI scheme redirects textile value chain procurement toward certified planting stock, tightening gin-to-mill traceability requirements in Surat and Ichalkaranji spinning clusters.
Brazil
Mato Grosso and Bahia expand cotton frontiers into Cerrado savanna zones with double-cropping soy-cotton rotations. ANVISA oversees agricultural biotechnology approvals through its biosafety commission, aligning with Mercosur harmonization efforts. Rondonópolis hosts expanding ginning capacity serving Asian export markets, with TraitShield-type platforms enabling direct breeder-to-farm distribution.
China
Xinjiang Uygur Autonomous Region dominates domestic lint production through state-directed irrigation and mechanized strip harvesting. NMPA and MIIT coordinate seed variety registration with national food security priorities, while GB standards specify fiber quality parameters. The dual carbon goals pressure water-intensive cultivation, accelerating investment in drought-tolerant germplasm development for Yellow River and Yangtze River alternative belts.
Australia
New South Wales and Queensland irrigated valleys sustain high-yielding upland production for premium export segments. The TGA and national biosecurity framework regulate genetically modified organism releases, with state-level protocols governing seed movement across quarantine zones. The Namoi and Gwydir valleys concentrate ginning infrastructure serving Asian spinning mills demanding contamination-free lint.
Global Seed Cotton Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in germplasm and trait development. The market structures around three tiers: multinational breeding platforms with stacked trait pipelines, regional seed specialists with distribution density, and commodity merchants with ginning and origination assets. Consolidation pressures concentrate among mid-scale breeders lacking gene-editing capabilities or direct-to-farm digital infrastructure. Dominant competitive moves include trait licensing alliances and backward integration into captive seed multiplication networks.
Within the multinational platform tier, Bayer Crop Science and Corteva Agriscience exemplify integrated breeding-to-distribution models spanning temperate and subtropical cotton belts. Nuziveedu Seeds occupies a position among regional specialists with extensive rural dealer networks across India's open-pollinated and hybrid segments. These three anchors represent divergent scale logics: global trait stewardship, continental germplasm adaptation, and national distribution density.
| Leading Market Players |
|---|
| Bayer Crop Science |
| Corteva Agriscience |
| BASF SE |
| Syngenta AG |
| Cargill, Inc. |
| Nuziveedu Seeds Ltd. |
| Kaveri Seed Company |
| Mahyco |
| Olam International |
| Others |
Supply & Pricing Matrix
Underutilized ginning capacity across Maharashtra and Gujarat compresses seed cotton procurement premiums while forcing breeders toward volume-based contract structures that sacrifice margin for throughput security.
Pricing Analysis
Certified-to-commodity spread pricing dominates seed cotton procurement, with PLI-linked quality premiums widening against spot-market bulk rates as textile manufacturers enforce traceability mandates. Price differentiation hinges on certification tier and gin proximity to spinning clusters. Cost compression in standard-grade segments intensifies because fertilizer and fuel input volatility squeezes non-integrated grower margins. Smallholder cooperatives exhibit highest price sensitivity, while integrated textile groups with captive ginning assets demonstrate lowest sensitivity due to backward control over origination.
Supply Chain Analysis
Extended payment terms from Indian textile processors to ginning cooperatives strain breeder working capital, accelerating adoption of supply-chain finance facilities backed by commodity traders. Geographic supply concentration centers on India, Brazil, and the United States as the three dominant origination points. The supply chain draws from hybrid seed multiplication networks, agrochemical inputs, and mechanical harvesting equipment pools. Single-source vulnerability around Bt trait licensing creates structural risk for growers locked into proprietary germplasm platforms. Distribution runs through direct-to-farm digital platforms and rural dealer networks in parallel channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Seed cotton markets are recovering from input-cost cyclical troughs, with fertilizer price normalization and ginning infrastructure modernization driving margin restoration across the value chain.
For Market Incumbents: Harden trait licensing control through exclusive germplasm stewardship agreements that lock out CRISPR-enabled mid-size competitors. Deepen upstream control over foundation seed multiplication networks in Gujarat and Maharashtra to secure supply pipeline dominance against digital platform disintermediation.
For New Entrants and Emerging Players: Pursue drought-tolerant germplasm white space in Brazil's Cerrado expansion zones where TraitShield-type infrastructure remains underpenetrated. Target organic certification contracting channels in South Asian textile supply chains as the most penetrable premium segment, leveraging blockchain traceability integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among gene-editing breeding platforms with multi-year trait licensing pipelines and captive seed distribution infrastructure. Long-term viability favors consolidators of mid-scale Indian and Brazilian germplasm specialists lacking CRISPR capabilities. Watch CRISPR regulatory classification clarity across EPA, CDSCO, and EFSA jurisdictions as the critical inflection signal for intellectual property valuation repricing.
| Strategic Initiative | Industry Significance |
|---|---|
| Trait Licensing Alliance | Stacked Bt and drought-tolerance germplasm accelerates variety development timelines for water-stressed belts. |
| Backward Integration into Seed Multiplication | Captive foundation seed networks insulate breeders from CDSCO certification bottlenecks and quality retesting delays. |
| Blockchain Traceability Integration | Digital seed-to-textile tracking attracts premium contracting from sustainability-mandated apparel brands in Surat clusters. |
| Direct-to-Farm Platform Expansion | TraitShield-type infrastructure compresses distribution tiers and displaces rural dealer margins in Brazil's Cerrado zones. |
| Gene-Editing R&D Partnership | CRISPR-Cas9 collaboration accelerates drought-tolerance development without transgenic regulatory burdens across jurisdictions. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of breeder R&D disclosures, CDSCO and EPA regulatory filings, and textile manufacturer sustainability reports. Primary inputs derive from interviews with germplasm licensing directors, ginning cooperative procurement managers, agricultural seed company distribution heads, and spinning mill fiber buyers. Secondary validation draws from BIS quality standard updates, PLI scheme implementation documents, customs trade data, and SEC filings of listed seed and agrochemical firms. Bottom-up variety adoption modeling triangulates against top-down value chain flow analysis.
Forecast inputs incorporate seed type penetration trajectories, ginning capacity utilization curves, and textile manufacturer certification mandates across the projection horizon. Segmentation dimensions span seed type, application flow, end-user procurement sophistication, and distribution channel digital adoption intensity. CAGRs derive from regression-based trend extrapolation against historical variety replacement cycles and regulatory approval timelines. Industry-specific inputs include CRISPR regulatory classification probability weights and PLI scheme disbursement velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by CRISPR-enabled mid-size breeders or accelerated EFSA biocide restrictions would shift outcomes. Macroeconomic input cost volatility, gene-editing regulatory reclassification, or sustainability mandate acceleration would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Commodities
Sugar Beet Pulp Pellets Market
Agricultural Commodities
South America Feed Premix Market
Agricultural Commodities
Gorse Market
Agricultural Commodities
Vietnam Feed Concentrate and Basemix Market
Agricultural Commodities
UK Bird Feeder Market
Agricultural Commodities
Soy Hulls Market
Agricultural Commodities
Asia-Pacific Feed Amino Acids Market
Agricultural Commodities
Africa Feed Amino Acids Market
Agricultural Commodities
Global Ruminant Feed Premix Market
Agricultural Commodities
North America Feed Lutein and Zeaxanthin Market
Agricultural Commodities
Artificial Fishing Baits Market
Agricultural Commodities
Citrus Pulp Pellets Market
Agricultural Commodities
Copra Meal Market
Agricultural Commodities
India Feed Amino Acids Market
Agricultural Commodities
Asia-Pacific Ruminant Feed Premix Market
Agricultural Commodities
Cottonseed Hulls Market