
 Abrasive Rolls Market | 2026-2036
Abrasive Rolls Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasive Rolls Market Insights
ISO 9001 certification is rotating as a baseline gate for Tier-1 abrasive roll suppliers bidding on automotive and aerospace contracts. Saint-Gobain leverages its European manufacturing footprint to sustain long-term supply agreements with German OEMs. 3M anchors North American demand through deep distribution networks serving metalworking job shops. Robert Bosch GmbH competes on integrated power-tool and consumable bundling across European retail channels.
Abrasive rolls consist of flexible backing materials—paper, cloth, or polyester—bonded with mineral grains through resin or electrostatic deposition, engineered for controlled material removal and surface finishing in industrial environments. Aluminum oxide formulations dominate volume shipments for general-purpose metalworking, while ceramic grain rolls command premium positioning in high-pressure aerospace grinding applications where extended cut life justifies elevated pricing. Coated abrasive rolls retain the largest share of manufacturing demand, though non-woven variants are gaining traction in automotive finishing lines requiring reduced substrate damage.
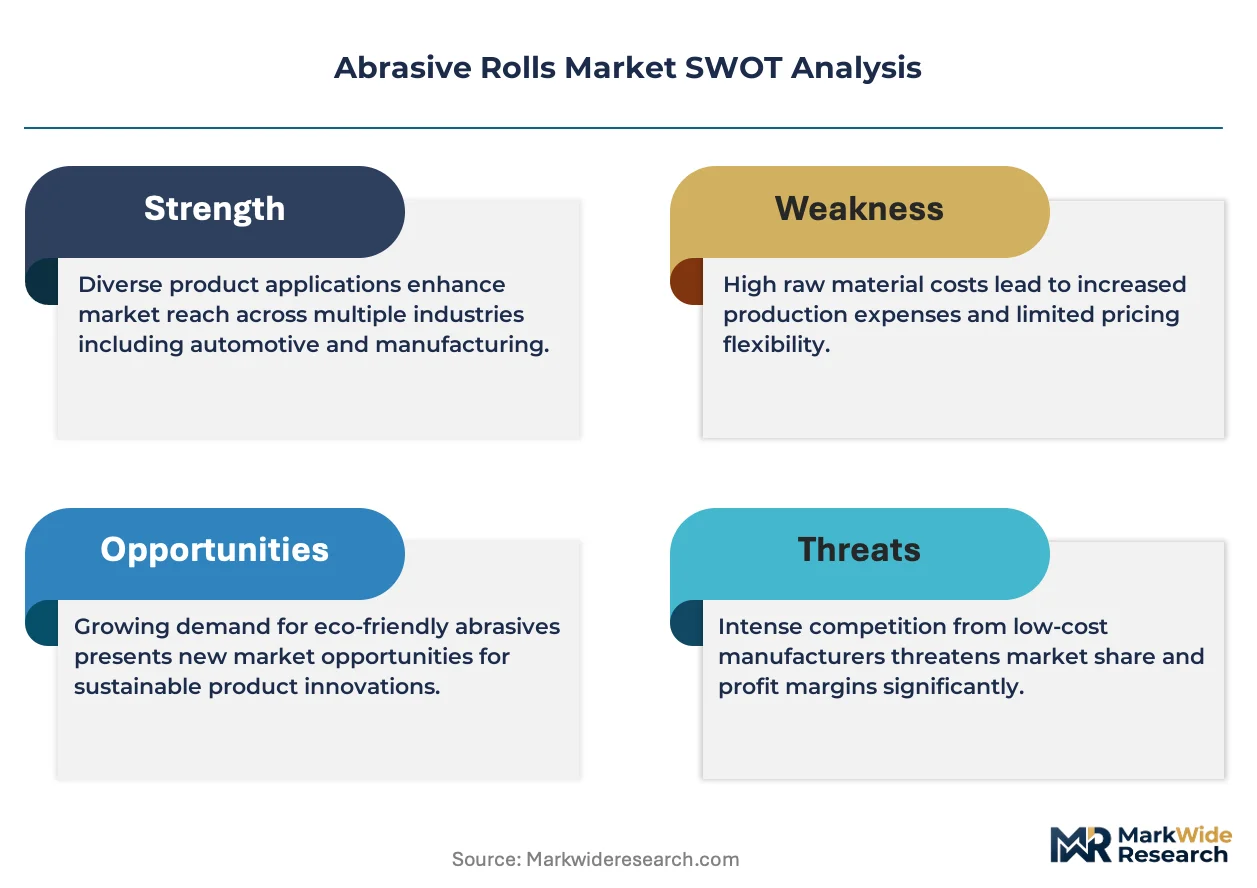
OSHA enforces permissible exposure limits on respirable crystalline silica in the United States, compelling manufacturers to reformulate bonding systems and improve dust extraction compatibility. REACH and the EU Green Deal restrict hazardous substance content in European-sold abrasives, pushing suppliers toward water-based resin alternatives. ECHA substance evaluations are accelerating disclosure requirements for synthetic mineral fibers used in specialty roll backings. Stakeholders must monitor evolving MEE enforcement in China and assess whether regional formulation divergence will fragment global product platforms or consolidate toward unified compliance standards.
Market Dynamics
Precision surface-finishing requirements for EV battery trays and aerospace turbine blades are compressing tolerance windows and forcing abrasive roll suppliers to engineer tighter grain-size distributions and advanced resin bonding systems.
Growth Catalysts
- OSHA silica exposure limits:United States manufacturers are retrofitting dust extraction systems and specifying low-dust abrasive formulations, expanding replacement demand for compliant consumables across metalworking job shops.
- EV battery tray preparation:Automotive OEMs in Germany and the United States are standardizing precision-finish abrasive rolls for aluminum substrate conditioning prior to thermal interface material application.
- Ceramic grain technology:High-pressure aerospace grinding operations are migrating toward engineered ceramic mineral structures that extend cut life and reduce changeout frequency in turbine blade finishing.
Market Restraints
- Alumina price volatility:Bauxite refining capacity concentration in specific geographies exposes abrasive roll manufacturers to input cost swings that compress margin predictability on aluminum oxide formulations.
- Specialty backing supply concentration:Polyester and woven cloth substrates rely on a narrow supplier base in China's eastern manufacturing corridor, creating single-source vulnerability for high-performance roll production.
- Solvent-based resin regulatory friction:REACH and EU Green Deal restrictions on volatile organic compound content are forcing accelerated R&D timelines to reformulate bonding systems without performance degradation.
Strategic Opportunities
- Water-based resin convergence:Formulation chemistry advances are enabling performance parity between water-based and solvent-based bonding systems, opening compliance pathways for European market access without product platform fragmentation.
- Non-woven automotive finishing:Reduced substrate damage requirements in EV body-in-white operations are creating specification windows for surface conditioning rolls that minimize metal removal while improving paint adhesion.
- MEE enforcement tailwinds:China's Ministry of Ecology and Environment is tightening industrial emissions standards, accelerating facility upgrades in provincial manufacturing clusters and expanding demand for dust-compatible abrasive systems.
Industry Challenges
- ISO 9001 certification timelines:Tier-1 automotive and aerospace contract qualification cycles extend 18-24 months, delaying revenue recognition for suppliers seeking to displace incumbent abrasive roll providers.
- Grain-bonding IP complexity:Proprietary ceramic grain structures and electrostatic deposition processes are subject to cross-licensing disputes that complicate technology transfer and geographic market entry strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abrasive Rolls Market |
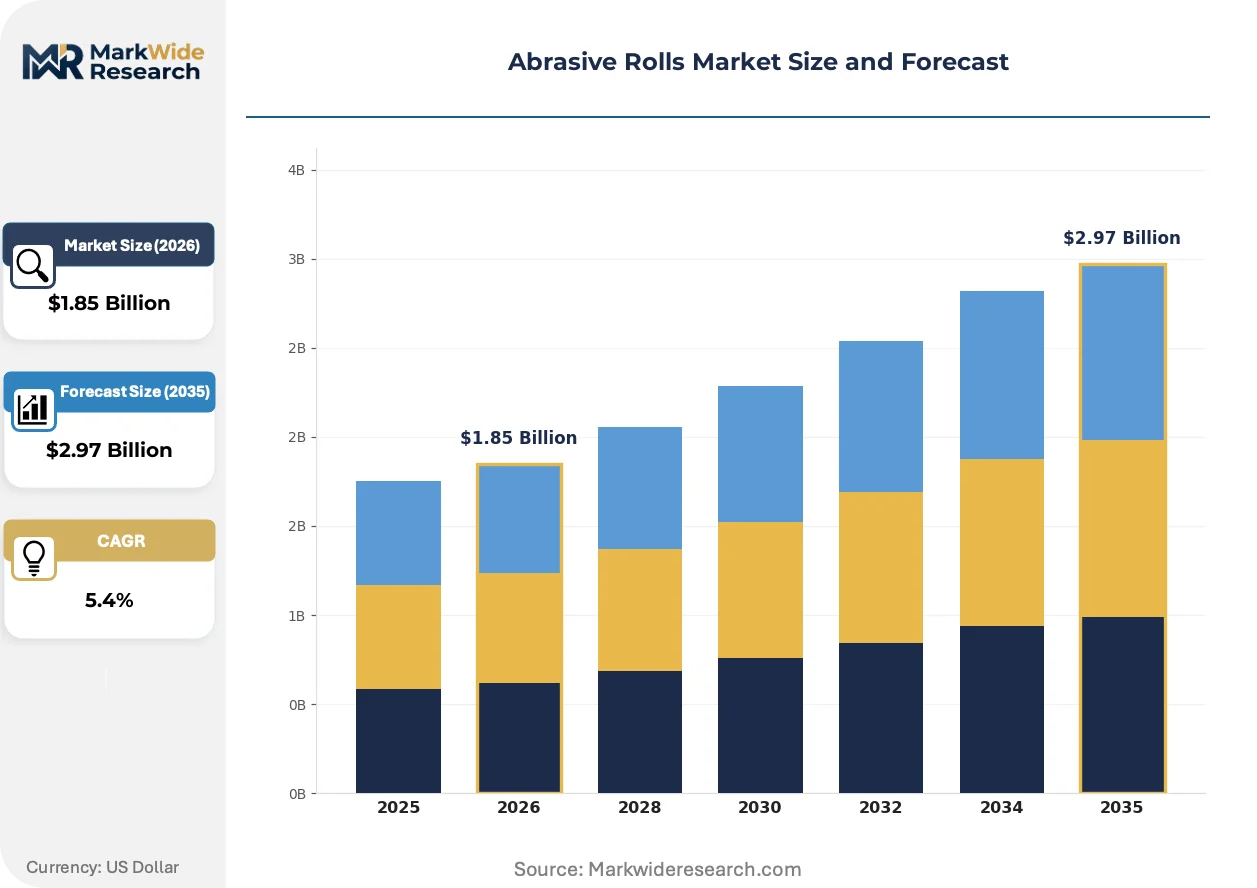
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Oxide, Silicon Carbide, Zirconia, Ceramic Application: Metalworking, Woodworking, Automotive, Aerospace Form: Coated, Non-woven, Specialty, Convolute End User: Manufacturing, Construction, Maintenance, Repair |
| Companies Covered | 3M, Saint-Gobain, Robert Bosch GmbH, Tyrolit Group, Fujimi Corporation, Henkel AG & Co. KGaA, Carborundum Universal Limited, Mirka Ltd., Asahi Diamond Industrial Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasive Rolls Market Trends and Innovations
Surface-finishing operations are converging toward digitized process control and predictive consumable management, reshaping how abrasive rolls are specified, monitored, and replenished across industrial environments.
Ceramic abrasive grain with engineered microfracture properties is supplanting conventional aluminum oxide in high-pressure grinding applications. Aerospace turbine blade manufacturers are specifying these formulations to extend cut life and reduce machine downtime. The technology is compressing total cost-per-part calculations and repositioning premium-grade rolls as operational efficiency investments rather than commodity consumables.
REACH substance evaluations are accelerating disclosure requirements for synthetic mineral fibers used in specialty roll backings. European suppliers must reformulate or relocate production to maintain market access. Coated abrasive variants with alternative fiber compositions are gaining specification share in German and French metalworking operations ahead of full enforcement deadlines.
Metalworking job shops are consolidating vendor relationships and specifying multi-year abrasive roll supply agreements with embedded technical service support. Distributor networks serving North American manufacturing are unbundling pure product sales and attaching application engineering consultations. The shift is most visible in United States automotive supply chain clusters where OEMs are pushing consumable standardization down to Tier-2 and Tier-3 suppliers.
Abrasive Rolls Market Segmentation
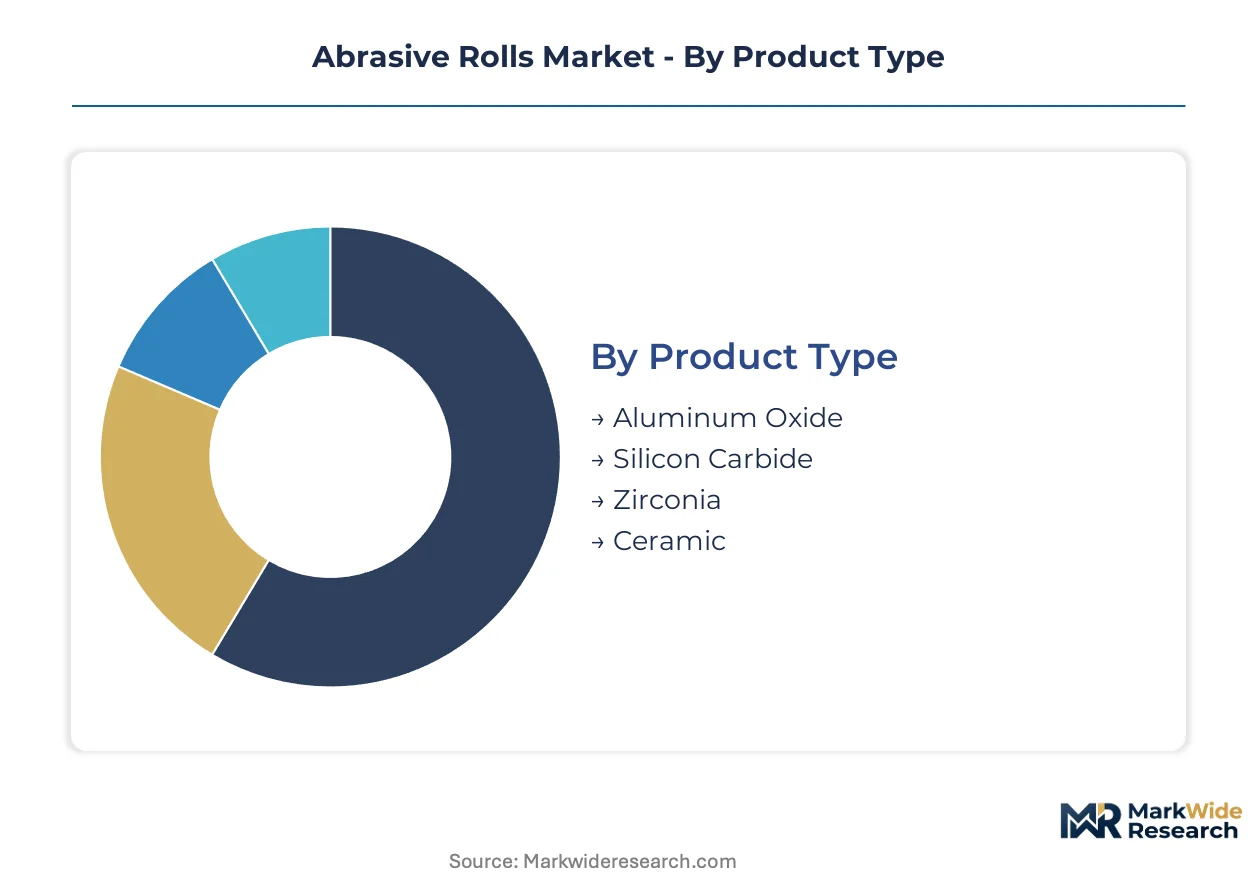
Abrasive roll segmentation reflects divergent compliance burdens and performance thresholds across mineral chemistries and backing constructions. Suppliers must align product platforms with OSHA silica limits, REACH substance restrictions, and MEE emissions enforcement to maintain specification access.
Product Type:
OSHA and REACH thresholds on airborne particulates and hazardous substance content are fragmenting formulation strategies across mineral grain categories.
- Aluminum Oxide:Resin-bonded bauxite-derived grains dominate general-purpose metalworking with cost-efficient material removal. German and United States automotive OEMs specify these formulations for EV battery tray preparation where moderate cut rates suffice.
- Ceramic:Engineered microfracture structures extend cut life in high-pressure aerospace grinding. United States turbine blade manufacturers are migrating specification share toward these premium formulations to compress total cost-per-part calculations.
- Silicon Carbide:Harder-than-alumina grains serve glass and stone finishing applications with sharp fracture properties.
- Zirconia:Self-sharpening grain structures target heavy stock removal in stainless steel processing.
Aluminum oxide handles the majority of throughput; ceramic is expanding most quickly on specification share.
Application:
Customer procurement patterns cluster around ISO 9001 certification requirements and multi-year technical service agreements.
- Metalworking:Precision surface-finishing for aluminum and steel substrates drives volume demand across job shops and OEM captive operations. China's eastern manufacturing corridor is upgrading capabilities for export-grade component finishing.
- Automotive:EV battery tray preparation and body-in-white conditioning require reduced substrate damage and controlled metal removal. German OEMs are standardizing precision-finish rolls for thermal interface material application.
- Aerospace:Turbine blade finishing demands tight grain-size distributions and advanced resin bonding systems.
- Woodworking:Furniture and millwork operations specify coated rolls for intermediate sanding stages.
Metalworking commands the largest installed base; automotive is climbing the fastest on volume growth.
Form:
Backing construction determines dust extraction compatibility and regulatory compliance pathways.
- Coated:Paper, cloth, or polyester backings bonded with mineral grains through resin or electrostatic deposition retain the largest manufacturing demand share. REACH evaluations on synthetic mineral fibers are forcing reformulation of specialty roll backings in European markets.
- Non-woven:Open nylon web structures impregnated with abrasive grain reduce substrate damage in automotive finishing lines. United States EV manufacturers are specifying these for paint adhesion preparation.
- Specialty:Custom-engineered constructions for semiconductor and medical device polishing.
- Convolute:Wound non-woven rolls for deburring and edge radiusing operations.
Coated abrasive rolls maintain the dominant position; non-woven variants are gaining share fastest on automotive specification.
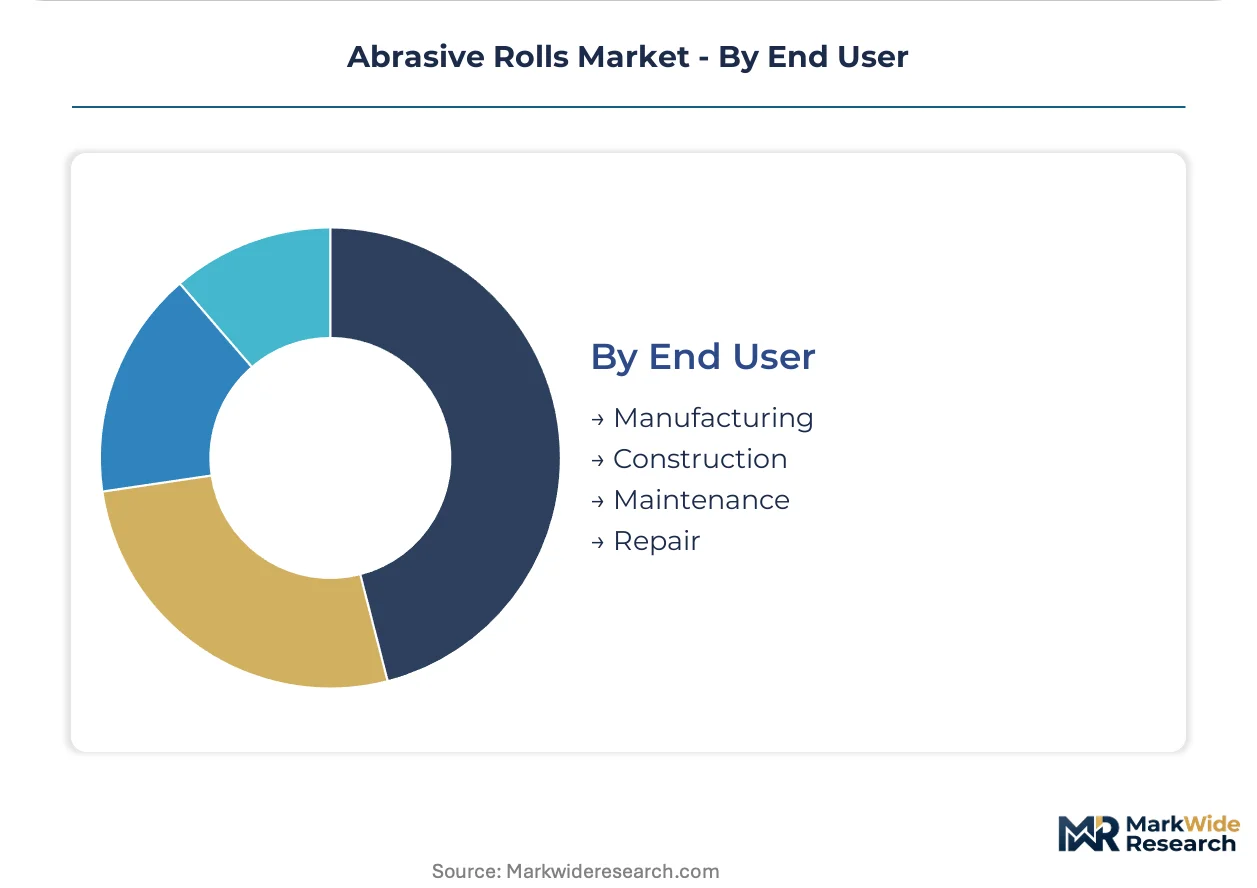
End User:
Facility scale and compliance maturity determine specification tier and supplier relationship structure.
- Manufacturing:Tier-1 automotive and aerospace contracts require 18-24 month ISO 9001 qualification cycles. German and United States OEMs are pushing consumable standardization down through supply chain tiers.
- Maintenance:Industrial facility upkeep drives replacement demand for compliant low-dust formulations as OSHA enforcement tightens.
- Construction:On-site metal fabrication and surface preparation for infrastructure projects.
- Repair:Job shop and field service operations with fragmented procurement patterns.
Manufacturing absorbs the greatest volume; maintenance is expanding fastest on regulatory retrofit demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEMs and metalworking job shops cluster demand in manufacturing corridors where EV battery tray preparation and precision surface-finishing specifications are tightening. Procurement concentrates among Tier-1 suppliers with ISO 9001 certification and multi-year technical service agreements.
United States
EV battery tray preparation for aluminum substrate conditioning drives specification demand from Detroit-area and Southern automotive clusters. OSHA enforces permissible exposure limits on respirable crystalline silica, compelling metalworking job shops to retrofit dust extraction systems and specify low-dust abrasive formulations. Michigan and Ohio manufacturing corridors are upgrading surface-finishing capabilities for electric vehicle supply chain integration.
Germany
Precision-finish abrasive rolls for thermal interface material application on EV battery trays command premium positioning from Stuttgart and Munich OEMs. REACH compliance and the EU Green Deal restrict hazardous substance content in bonding systems, pushing suppliers toward water-based resin alternatives. Bavarian and Baden-Württemberg industrial clusters are standardizing ceramic grain formulations for aerospace turbine blade finishing operations.
China
Provincial manufacturing clusters in the eastern manufacturing corridor are upgrading surface-finishing capabilities for export-grade metal components. MEE enforcement is tightening industrial emissions standards, accelerating facility upgrades and expanding demand for dust-compatible abrasive systems. Yangtze River Delta cities including Shanghai and Suzhou are consolidating abrasive roll procurement through Tier-1 automotive supplier networks.
Japan
High-pressure aerospace grinding operations in Nagoya and Tokyo industrial zones specify engineered ceramic mineral structures for turbine blade finishing. METI industrial standards guide bonding system formulations for precision manufacturing applications. Chubu region automotive suppliers are migrating specification share toward extended cut-life formulations to reduce machine downtime.
India
Metalworking job shops in Maharashtra and Gujarat are expanding consumption of aluminum oxide formulations for general-purpose steel and stainless steel processing. BIS certification requirements are emerging as baseline gates for automotive and industrial machinery contract qualification. Pune and Ahmedabad manufacturing corridors are upgrading dust extraction infrastructure to align with tightening workplace safety enforcement.
Abrasive Rolls Market Competitive Landscape
Player mix skews toward diversified materials conglomerates with captive abrasive divisions and specialized coated abrasives manufacturers with regional manufacturing footprints. The structure concentrates specification power among Tier-1 suppliers with multi-year automotive and aerospace contracts. Three archetypes dominate: European integrated materials groups with long-term OEM supply agreements, North American diversified industrials with deep distribution networks, and Asian specialized manufacturers with cost-optimized production platforms. Competitive moves center on water-based resin formulation R&D and non-woven backing technology licensing.
Within the integrated materials tier, Saint-Gobain anchors European specification share through manufacturing proximity to German automotive clusters, while 3M occupies a position in North American metalworking distribution. Robert Bosch GmbH exemplifies the power-tool and consumable bundling archetype across European retail channels. These three entities represent divergent competitive vectors: geographic manufacturing concentration, distribution network depth, and integrated system bundling.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Robert Bosch GmbH |
| Tyrolit Group |
| Fujimi Corporation |
| Henkel AG & Co. KGaA |
| Carborundum Universal Limited |
| Mirka Ltd. |
| Asahi Diamond Industrial Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
ISO 9001 certification gates both supplier qualification and price differentiation simultaneously, compressing margin structures for uncertified producers while enabling Tier-1 incumbents to command sustained premiums through multi-year technical service agreements.
Pricing Analysis
Cost-plus contracts with alumina price indexation dominate long-term supply agreements between abrasive roll manufacturers and German automotive OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ceramic grain aerospace formulations from aluminum oxide general-purpose grades and commodity job shop offerings. Cost compression in standard-grade aluminum oxide rolls is intensifying because bauxite refining capacity concentration exposes producers to input volatility. Tier-2 metalworking job shops exhibit highest price sensitivity, while aerospace turbine blade manufacturers prioritize total cost-per-part over unit pricing.
Supply Chain Analysis
Inventory buffers and extended lead times for polyester woven cloth backings are forcing abrasive roll producers to pre-position raw material stocks ahead of seasonal demand surges. Manufacturing concentrates in China, Germany, and the United States, with bauxite-derived alumina, synthetic resin bonding systems, and precision-woven polyester substrates as critical inputs. Single-source vulnerability in China's eastern manufacturing corridor for specialty backing materials threatens production continuity. Distribution runs through industrial distributor networks and direct OEM supply agreements with embedded technical service support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against engineered superabrasive alternatives and fixed abrasive machining centers that threaten precision grinding applications.
For Market Incumbents: Fortify specification lock-in through accelerated water-based resin R&D to preempt REACH compliance deadlines, and deepen captive supply of ceramic grain formulations to offset alumina price volatility. Incumbents must defend against integrated power-tool bundlers by attaching application engineering consultations to multi-year contracts.
For New Entrants and Emerging Players: Anchor in China's provincial manufacturing clusters where MEE enforcement is accelerating facility upgrades and Tier-2 suppliers lack ISO 9001 certification. Target dust-compatible abrasive system retrofits in metalworking job shops with compliant low-dust formulations and rapid technical service response.
For Investors and Strategic Acquirers: REACH substance evaluation deadlines reshape the acquisition landscape toward European suppliers with reformulated water-based resin platforms already validated. Long-term viability centers on water-based bonding chemistry and non-woven backing technology. Signal to monitor: ECHA disclosure requirement enforcement timelines for synthetic mineral fiber backings.
| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Resin Platform Migration | REACH compliance unlocks sustained European market access without product fragmentation. |
| Ceramic Grain Capacity Expansion | Engineered microfracture structures capture aerospace turbine blade specification share. |
| Non-Woven Backing Technology Licensing | Reduced substrate damage requirements penetrate EV body-in-white finishing lines. |
| ISO 9001 Certification Acceleration | Tier-1 automotive contract qualification gates displace incumbent supplier relationships. |
| Dust Extraction System Integration | OSHA silica limits compel metalworking job shop retrofit demand for compliant consumables. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers, procurement leads at automotive OEMs, distribution channel partners, and technical R&D directors; and secondary validation through customs/trade data, SEC 10-K filings, ACC industry reports, and OSHA enforcement records. Bottom-up and top-down triangulation cross-checked mineral grain shipment volumes against end-use application demand.
Across the projection horizon, the analytical framework modeled segmentation dimensions including mineral chemistry tier, backing construction type, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from trend extrapolation of specification share migration and facility upgrade cycles. Forecast inputs incorporated EV battery tray preparation volume trajectories and MEE enforcement intensity assumptions.
Decision-makers should treat outputs as directional under sustained alumina price volatility and REACH implementation timelines; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Grinding Wheel Market
Abrasives
Tungsten Carbide Market
Abrasives
Chemical Mechanical Polishing Market
Abrasives
Metal Abrasives Market
Abrasives
North America Abrasives Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Vitrified Bonded Grinding Wheels Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Abrasive Base Paper Market
Abrasives
Tungsten Carbide Powder Market
Abrasives
Abrasive Cloth Market
Abrasives
Carbide Tools Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Concrete Densification and Polishing Material Market