
 Abrasive Tools Market | 2026-2036
Abrasive Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Abrasive Tools Market Analysis
A shift from single-source procurement to multi-source qualification is repositioning supply strategies across the abrasive tools value chain. Robert Bosch GmbH leverages its captive manufacturing network to secure raw material throughput for bonded abrasives. Saint-Gobain Abrasives anchors its position through vertical integration into synthetic mineral production. 3M Company differentiates via proprietary precision-shaped grain technology that commands premium positioning in industrial channels.
Abrasive tools are mechanical implements that employ hard mineral grains—typically aluminum oxide, silicon carbide, diamond, or cubic boron nitride—bonded to substrates via vitrified, resin, or metal matrices to remove material through friction, with grit sizes ranging from coarse 24-grit to ultra-fine 1200-grit for controlled surface modification. Their primary purpose spans material removal, dimensioning, surface finishing, and edge preparation across metalworking, woodworking, and composite fabrication workflows. Grinding wheels occupy the largest share of product-type revenue due to entrenched deployment in heavy metal removal, while diamond abrasives represent the fastest-expanding material-composition category as ceramic matrix composites and hardened alloys proliferate in aerospace and automotive powertrain applications. Surface preparation commands the broadest application footprint across industrial and construction usage environments, though polishing applications are gaining share in electric vehicle battery cell manufacturing where burr-free terminal surfaces reduce electrical resistance.
OSHA enforces permissible exposure limits for respirable crystalline silica that compel manufacturers to engineer lower-dust bonded abrasives and improve vacuum-integrated tool compatibility. REACH restricts specific resin binders and heavy-metal additives used in conventional abrasive formulations, accelerating reformulation cycles among EU-distributed suppliers. The EU F-Gas Regulation indirectly shapes demand for precision finishing tools used in heat-pump compressor manufacturing, a sector whose expansion relies on hermetic sealing surfaces. Stakeholders must monitor evolving MEE air-quality standards in China and dual carbon compliance timelines, as these will determine where captive abrasive production capacity gets allocated and which mineral synthesis routes achieve regulatory clearance.
Market Dynamics
Multi-source procurement mandates from automotive OEMs are fragmenting supplier relationships and compressing qualification timelines for bonded abrasive manufacturers serving precision metalworking applications.
Growth Catalysts
- OSHA Silica Rulemaking:Stricter respirable crystalline silica exposure limits in the United States are compelling manufacturers to engineer lower-dust bonded abrasives and vacuum-integrated tool systems, expanding the addressable market for compliant product lines.
- Electric Vehicle Battery Manufacturing:Burr-free terminal surface requirements in lithium-ion cell assembly are accelerating consumption of ultra-fine polishing abrasives in gigafactory environments across Germany, China, and the United States.
- Ceramic Matrix Composite Proliferation:Aerospace powertrain applications utilizing hardened alloys and CMCs are displacing conventional grinding media with diamond abrasive solutions engineered for thermal stability.
Market Restraints
- Fused Alumina Supply Concentration:Chinese dominance in brown fused alumina synthesis creates input cost volatility and geopolitical exposure for European and North American bonded abrasive producers.
- REACH Registration Burden:ECHA compliance costs for novel resin binders and heavy-metal-free formulations are extending product development cycles by 18-24 months for EU-distributed suppliers.
- Superabrasive Substitution Economics:Polycrystalline diamond tooling in hardened steel applications is capturing finishing workflows previously served by conventional silicon carbide grinding wheels.
Strategic Opportunities
- Heat Pump Manufacturing Expansion:EU F-Gas Regulation-driven compressor production is creating demand for precision lapping tools that achieve hermetic sealing surface specifications in Stuttgart and Solingen industrial clusters.
- Direct-to-Shop Distribution Platforms:Automotive refinishing shops in Bavaria and Baden-Württemberg are bypassing traditional industrial distributors through specialized e-procurement channels for precision abrasive consumables.
- Dual Carbon Compliance in China:MEE air-quality standards and provincial carbon intensity targets are reallocating captive abrasive production capacity toward synthetic mineral synthesis routes with lower embodied emissions.
Industry Challenges
- Precision Grinding Technician Scarcity:Metalworking vocational programs in Germany and the United States are failing to replenish specialized workforce capable of optimizing superabrasive tool parameters for CMC machining.
- ISO 9001:2015 Transition Complexity:Abrasive tool manufacturers serving aerospace tier-1 suppliers face compressed recertification timelines while simultaneously implementing IATF 16949 automotive quality management overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Abrasive Tools Market |
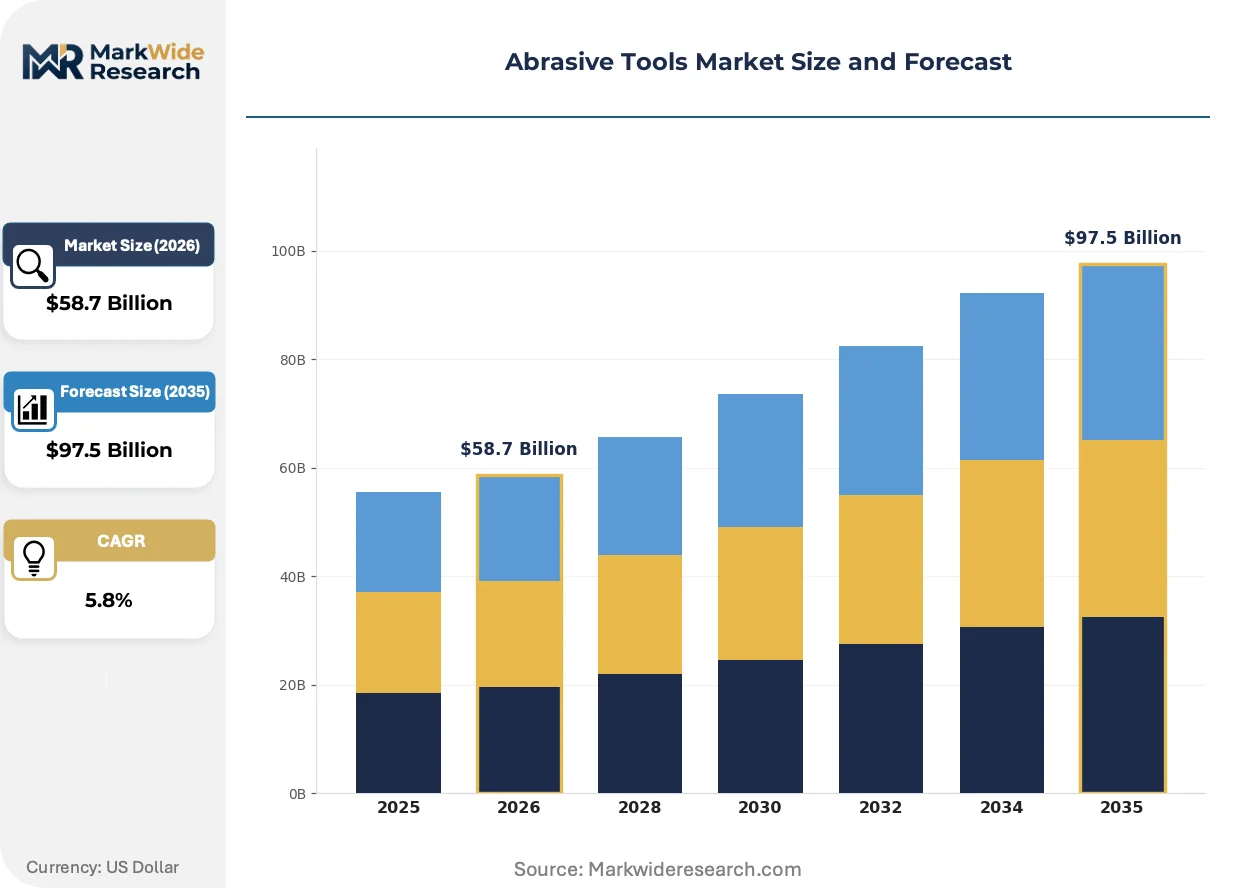
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $97.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grinding Wheels, Sanding Discs, Abrasive Belts, Flap Wheels Usage Environment: Industrial, Automotive, Construction, Metalworking Material Composition: Aluminum Oxide, Silicon Carbide, Diamond, Cubic Boron Nitride Application: Surface Preparation, Polishing, Cutting, Deburring |
| Companies Covered | Robert Bosch GmbH, Henkel AG & Co. KGaA, Saint-Gobain Abrasives, Klingspor AG, Mirka Ltd., 3M Company, Fujimi Incorporated, Carborundum Universal Limited, Tyrolit Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Abrasive Tools Market Emerging Trajectories
Intelligent abrasive systems and connected manufacturing workflows are redefining how removal rates, surface integrity, and tool life get optimized across precision metalworking environments.
Precision-shaped grain technology is automating the transition from manual grinding parameter adjustment to closed-loop process control in automotive powertrain machining cells. Tier-1 suppliers in Stuttgart and Detroit are deploying sensor-integrated grinding wheels that feed real-time wear data into adaptive feed-rate controllers. This convergence is automating the elimination of dimensional variation that previously required post-process inspection and rework.
REACH Annex XVII restrictions on specific resin binders and heavy-metal additives are forcing reformulation of conventional vitrified and resin-bonded abrasive matrices distributed in the European Union. ECHA substance evaluation workflows are extending registration timelines for novel bonding chemistries, compressing competitive windows for compliant product introductions. German abrasive manufacturers with captive synthetic mineral production are responding by accelerating in-house development of bio-based phenolic alternatives.
Automotive refinishing shops are consolidating purchase authority through multi-source qualification platforms that displace single-supplier relationships historically dominant in body shop supply chains. Digital procurement interfaces in Bavaria and North Rhine-Westphalia are enabling real-time price benchmarking across bonded abrasive and coated abrasive categories. This behavioral shift is most visible in Germany's industrial belt, where independent repair facilities now maintain qualified supplier rosters of four to six abrasive tool vendors versus legacy sole-source arrangements.
Abrasive Tools Market Segmentation
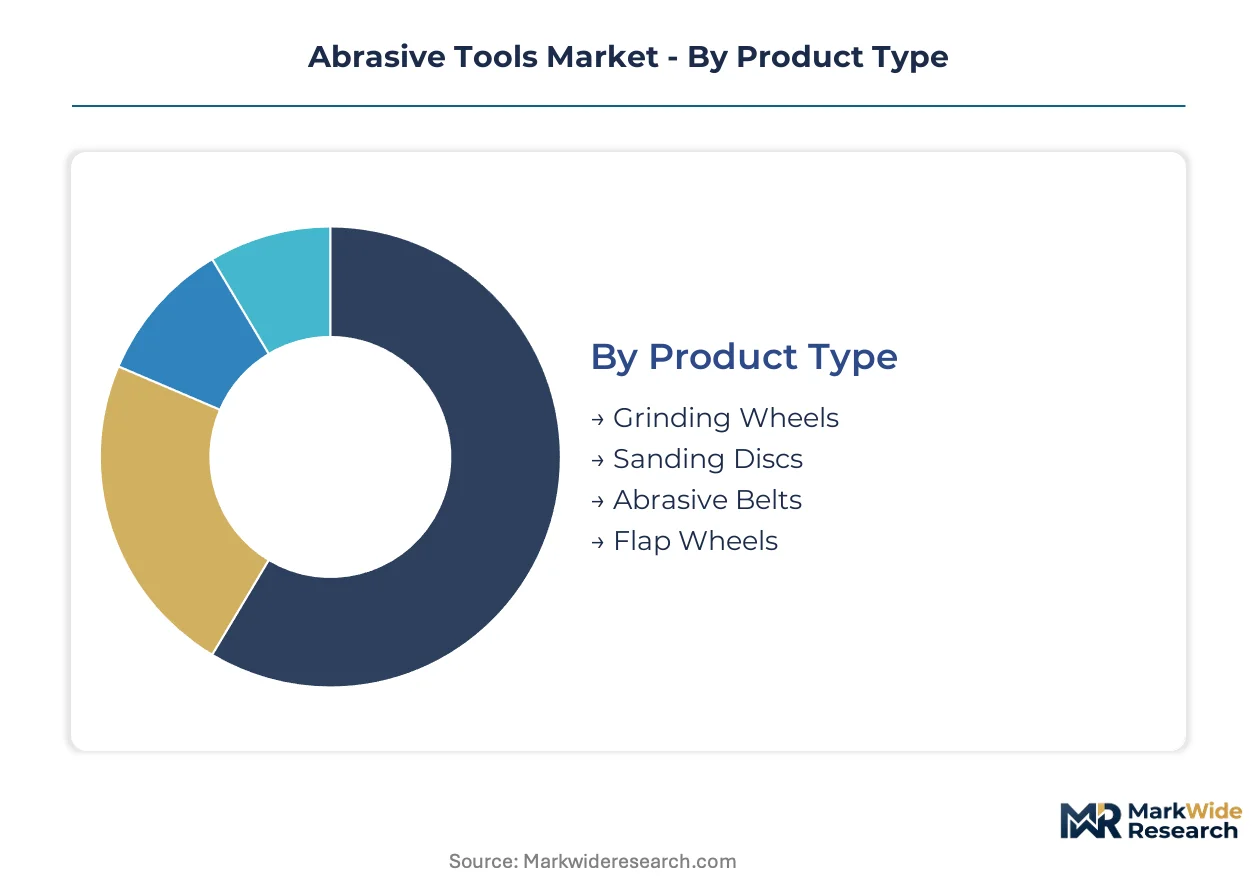
Abrasive tool selection hinges on matching mineral hardness, bond matrix, and grit topology to specific material removal rates and surface integrity requirements. Segmentation reveals where technical differentiation commands premium positioning versus where commoditization pressures dominate procurement decisions.
Product Type:
Supply concentration among bonded abrasive manufacturers in Germany and China determines which product formats achieve consistent raw material throughput and quality certification.
- Grinding Wheels:Vitrified or resin-bonded mineral aggregates formed into rigid rotating discs for heavy stock removal and precision dimensioning. Demand concentrates in Stuttgart's automotive powertrain machining clusters where captive supplier relationships with Robert Bosch GmbH secure brown fused alumina allocations.
- Sanding Discs:Coated abrasives comprising mineral grains adhered to flexible paper or cloth backings for surface finishing operations. German refinishing shops in Bavaria are expanding multi-source procurement of these consumables through digital platforms that bypass traditional industrial distributors.
- Abrasive Belts:Continuous-loop coated abrasive strips engineered for automated material removal in wide-belt sanding and centerless grinding configurations. Metalworking facilities in Solingen utilize these for knife and blade finishing workflows.
- Flap Wheels:Radially arranged abrasive flaps bonded to a central hub, combining aggressive cutting action with conformability to contoured surfaces. Aerospace maintenance operations in Toulouse and Hamburg specify these for turbine blade restoration.
Today's leader: Grinding Wheels. Tomorrow's challenger: Sanding Discs.
Usage Environment:
End-use concentration shapes abrasive specification requirements, with automotive and aerospace applications driving the steepest demand for precision-grade superabrasives.
- Industrial:Heavy manufacturing environments including foundries, forges, and primary metal processing where bulk material removal dominates. OSHA silica exposure limits are compelling these facilities to adopt vacuum-integrated grinding systems.
- Automotive:OEM assembly plants and tier-1 supplier machining cells where dimensional tolerances and surface finish specifications are tightest. EV battery gigafactories in Nevada and Thuringia are accelerating consumption of ultra-fine polishing abrasives for terminal preparation.
- Construction:Field-based surface preparation and concrete finishing where portable abrasive tools face dust exposure and durability challenges. REACH compliance is restricting resin binder formulations available to EU construction contractors.
- Metalworking:Job shops and specialized fabricators serving diverse material classes from mild steel to nickel superalloys. Stuttgart's precision grinding sector is experiencing technician scarcity that limits superabrasive parameter optimization.
Industrial volume anchors current revenue. Automotive applications are climbing the fastest as powertrain electrification reshapes component geometries.
Material Composition:
Mineral synthesis route and thermal stability characteristics determine which compositions capture premium pricing in hardened alloy and ceramic matrix composite applications.
- Aluminum Oxide:Synthetic corundum produced via bauxite reduction in electric arc furnaces, offering cost-effective hardness for ferrous metal grinding. Chinese dominance in brown fused alumina synthesis creates input cost volatility for European bonded abrasive producers.
- Silicon Carbide:Carborundum synthesized from silica sand and petroleum coke, delivering superior friability for non-ferrous metals and stone. Polycrystalline diamond tooling is displacing silicon carbide in some hardened steel finishing workflows.
- Diamond:Natural or synthetic crystalline carbon offering extreme hardness for ceramic, glass, and composite machining. Aerospace CMC proliferation is expanding diamond abrasive consumption fastest among all mineral classes.
- Cubic Boron Nitride:Synthetic superabrasive second only to diamond in hardness, engineered specifically for ferrous alloy grinding where diamond's carbon solubility causes rapid wear. German manufacturers with captive CBN synthesis capacity are securing aerospace tier-1 qualifications.
Diamond claims the steepest expansion trajectory. Aluminum Oxide retains volume leadership through cost-positioned general industrial applications.
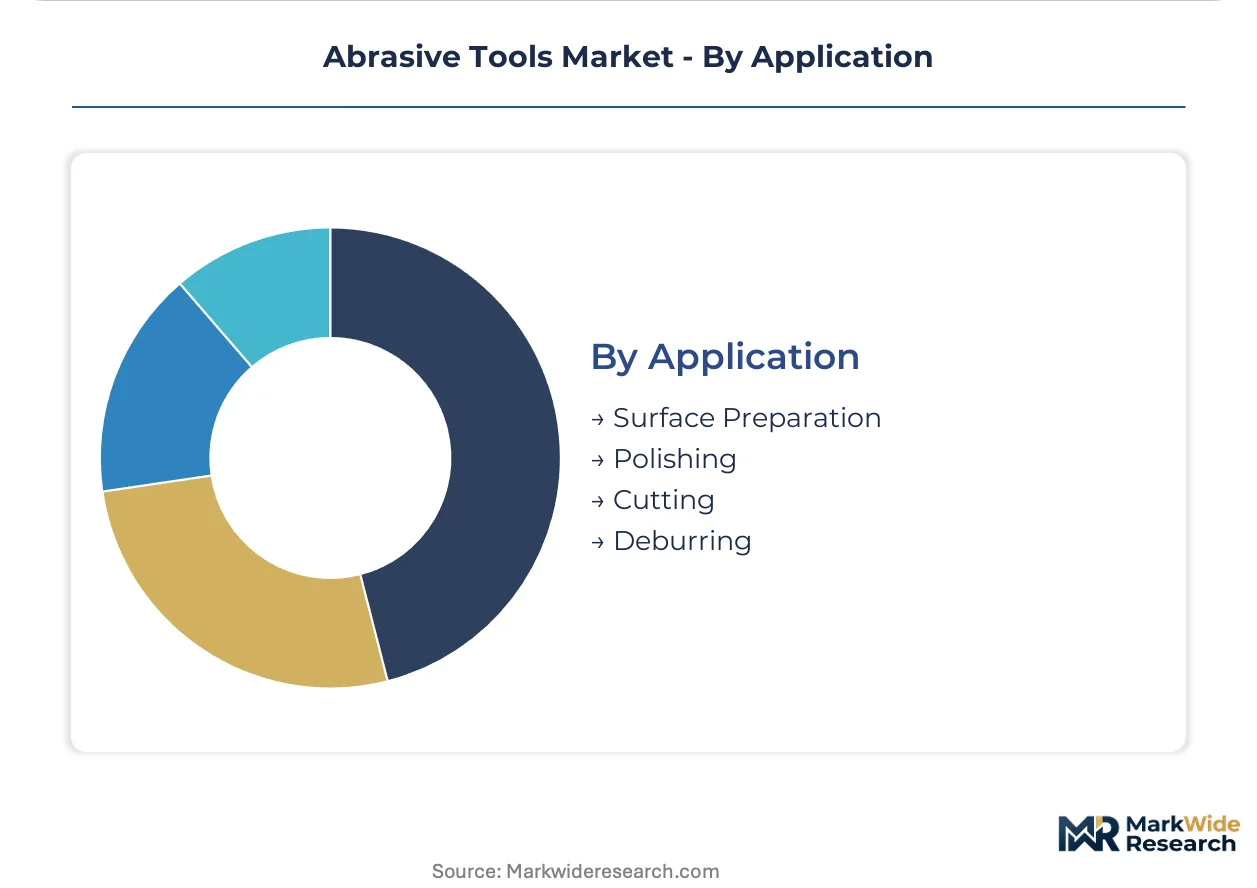
Application:
Process stage and surface specification stringency determine abrasive grade selection, with finishing operations commanding higher mineral purity and tighter grain size distributions.
- Surface Preparation:Initial material conditioning including rust removal, scale stripping, and weld cleaning to establish substrate integrity for subsequent operations. Construction and shipbuilding sectors in South Korea and Poland drive bulk consumption.
- Polishing:Ultra-fine abrasive action producing mirror finishes and sub-micron surface roughness for optical, medical, and electrical contact applications. EV battery cell manufacturing is accelerating demand for burr-free terminal surfaces.
- Cutting:Abrasive action severing workpiece material through thin-wheel fracture or continuous rim grinding. Metal fabrication job shops represent the primary consumption node.
- Deburring:Edge-breaking and flash removal operations critical to aerospace component fatigue life and assembly fit. Automated deburring cells in Toulouse and Wichita are integrating sensor-feedback abrasive systems.
Surface Preparation dominates current volume. Polishing is gaining share fastest as electronics and electrification applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors abrasive tool demand through its dense automotive powertrain machining clusters, where tier-1 suppliers consume precision grinding wheels for crankshaft and camshaft finishing. Regulatory pressure from OSHA silica limits and REACH resin restrictions is fragmenting procurement patterns across major industrial economies. Production capacity allocation increasingly tracks dual carbon compliance timelines and regional air-quality enforcement intensity.
United States
OSHA's respirable crystalline silica rulemaking is compelling manufacturers to engineer lower-dust bonded abrasives and vacuum-integrated tool systems. The EPA coordinates with state-level occupational safety agencies to enforce exposure limits in foundries and metal fabrication facilities. EV battery gigafactories in Nevada and Michigan are accelerating consumption of ultra-fine polishing abrasives for lithium-ion cell terminal preparation.
Germany
REACH Annex XVII restrictions on resin binders and heavy-metal additives are extending product development cycles for EU-distributed abrasive suppliers. ECHA substance evaluation workflows compress competitive windows for compliant product introductions. Stuttgart's automotive powertrain machining clusters and Solingen's precision grinding sector represent the densest consumption nodes for vitrified and superabrasive tooling.
China
MEE air-quality standards and provincial carbon intensity targets are reallocating captive abrasive production capacity toward synthetic mineral synthesis routes with lower embodied emissions. MIIT oversees industrial mineral processing permits that constrain brown fused alumina expansion. Yangtze River Delta manufacturing hubs are prioritizing diamond abrasive consumption for ceramic matrix composite machining in aerospace supply chains.
Japan
METI's industrial technology roadmaps prioritize precision finishing capabilities for semiconductor and automotive component manufacturing. JIS standards govern abrasive grain size distributions and bond matrix specifications for domestic precision tool producers. Nagoya's automotive supplier ecosystem and Osaka's machinery manufacturing belt sustain concentrated demand for cubic boron nitride grinding solutions.
India
BIS certification requirements for bonded abrasives used in critical infrastructure projects are elevating quality thresholds for domestic and imported products. The PLI scheme for specialty steel and automotive components indirectly stimulates precision abrasive consumption in component machining workflows. Gujarat's industrial corridor and Tamil Nadu's automotive manufacturing clusters are expanding coated abrasive procurement for surface preparation operations.
Abrasive Tools Market Vendor Landscape
Global majors compete with regional champions across raw material access, captive synthetic mineral production, and precision-shaped grain technology. Market structure tilts toward consolidation at the superabrasive tier while bonded abrasive segments retain fragmentation among national champions and specialized job shops. Three archetypes dominate: diversified industrial conglomerates with captive mineral synthesis, precision technology specialists commanding premium positioning in automotive and aerospace channels, and regional volume players serving construction and metalworking job shops. Capacity expansion and strategic partnerships represent the dominant competitive moves, with players securing brown fused alumina allocations and qualifying multi-source supplier rosters.
Among diversified industrial conglomerates, Robert Bosch GmbH exemplifies the captive manufacturing archetype through its integrated supply network securing raw material throughput. Saint-Gobain Abrasives occupies a position representing backward integration into synthetic mineral production, while 3M Company anchors the precision technology tier through proprietary grain architectures. These three entities collectively illustrate how competitive positioning stratifies across mineral access, formulation expertise, and distribution reach.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Henkel AG & Co. KGaA |
| Saint-Gobain Abrasives |
| Klingspor AG |
| Mirka Ltd. |
| 3M Company |
| Fujimi Incorporated |
| Carborundum Universal Limited |
| Tyrolit Group |
| Others |
Supply Flow & Price Mechanics
Captive synthetic mineral production anchors competitive positioning across the abrasive tools value chain, with Saint-Gobain Abrasives and Robert Bosch GmbH leveraging in-house brown fused alumina and cubic boron nitride synthesis to buffer input cost volatility and command premium pricing in automotive powertrain channels. This integration choice insulates margin structures from Chinese supply concentration while enabling compliant product lines for REACH-regulated European markets.
Pricing Analysis
Input-cost pass-through from brown fused alumina and synthetic diamond feedstocks shapes contract structures across bonded and superabrasive tiers. Three-tier pricing structure across premium, standard, and economy levels separates precision-shaped grain solutions for aerospace tier-1 suppliers from commodity vitrified wheels serving construction job shops. Cost compression in standard-grade resin-bonded abrasives is intensifying because of Chinese import competition and REACH-driven reformulation expenses. Automotive refinishing shops in Bavaria exhibit highest price sensitivity through multi-source digital procurement, while EV battery gigafactories prioritize performance over unit cost for terminal polishing applications.
Supply Chain Analysis
India's BIS certification requirements and China's MIIT mineral processing permits are reshaping sourcing footprints for EU and North American bonded abrasive distributors. Raw material dependencies center on Chinese brown fused alumina, South Korean synthetic diamond feedstocks, and German-engineered cubic boron nitride crystals. Single-source vulnerability concentrates in Yangtze River Delta alumina synthesis, where provincial carbon intensity targets constrain expansion. Distribution runs through specialized industrial distributors in Stuttgart and Solingen, with direct-to-shop e-procurement platforms gaining share in automotive refinishing channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The abrasive tools market functions as a regulatory compounder, with OSHA silica rulemaking and REACH Annex XVII restrictions accelerating demand for compliant lower-dust and heavy-metal-free formulations across industrial and automotive end-uses.
For Market Incumbents: To counter polycrystalline diamond substitution in hardened steel finishing workflows, secure captive brown fused alumina allocations through long-term offtake agreements with Yangtze River Delta producers. Deepen backward integration into synthetic mineral synthesis to buffer REACH-driven reformulation costs and maintain aerospace tier-1 qualification timelines. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany opens a window for precision lapping tool specialists serving Stuttgart and Solingen heat-pump compressor manufacturing clusters. Target automotive refinishing shops in Baden-Württemberg through specialized e-procurement platforms that bypass legacy distributor relationships. Lead with REACH-compliant bio-based phenolic bond formulations to accelerate ECHA substance evaluation timelines. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap bonded abrasive specialists with captive synthetic mineral production because Chinese supply concentration and REACH compliance burdens favor scaled domestic manufacturers. Focus on 5-10 year viability windows for German and Japanese precision grinding technology platforms. Watch MEE air-quality enforcement intensity in China as the signal for where captive abrasive production capacity reallocates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Mineral Production | Captive cubic boron nitride synthesis secures aerospace tier-1 qualifications for Stuttgart machining clusters. |
| REACH-Compliant Bond Formulation Development | Bio-based phenolic alternatives accelerate ECHA registration timelines for EU-distributed product lines. |
| Direct-to-Shop Digital Distribution Platform | Multi-source procurement interfaces displace traditional industrial distributors in Bavarian refinishing markets. |
| Vacuum-Integrated Tool System Engineering | OSHA silica compliance expands addressable market for lower-dust bonded abrasive product lines. |
| Precision-Shaped Grain Technology Investment | Proprietary grain architectures command premium positioning in automotive powertrain machining cells. |
Methodological Framework
Direct dialogue with abrasive tool plant managers, automotive tier-1 procurement leads, distribution channel partners, and technical R&D directors grounded qualitative findings in operational reality. Secondary validation drew from SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and ECHA substance evaluation databases. Bottom-up demand modeling across grinding wheel, sanding disc, and superabrasive product tiers triangulated with top-down mineral consumption forecasts.
Segment-level projections across product type, material composition, usage environment, and application incorporated mineral hardness specifications, bond matrix thermal stability, and grit topology requirements. CAGRs were derived from regression analysis of historical consumption patterns and forward-looking regulatory enforcement timelines. Key inputs included OSHA silica exposure limit implementation schedules, REACH Annex XVII restriction expansion pathways, and MIIT mineral processing permit allocations.
Revisions become necessary when MEE air-quality standards tighten beyond modeled scenarios, when ECHA accelerates substance evaluation timelines, or when automotive OEM multi-source procurement mandates fragment supplier relationships faster than projected. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Carbide Grinding Wheel Market
Abrasives
Abrasive Base Paper Market
Abrasives
Sandblaster Market
Abrasives
Boron Carbide Bulletproof Plate Market
Abrasives
North America Abrasives Market
Abrasives
Grinding Wheels Market
Abrasives
Europe Abrasives Market
Abrasives
Abrasive Cloth Market
Abrasives
Abrasive Grains Market
Abrasives
Tile Abrasion Testing Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Liquid Sandpaper Market
Abrasives
Global Rubber Bonded Abrasive Market
Abrasives
Glass Abrasives Market
Abrasives
Non-Woven Abrasives Market
Abrasives
Artificial Abrasives Market