
 Synthetic Rubber Market | 2026-2036
Synthetic Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Synthetic Rubber Market Analysis
ISO 16396 certification for polybutadiene rubber is reorganizing supplier qualification protocols across the automotive value chain. Arlanxeo leverages its integrated butadiene feedstock position to sustain cost leadership in European BR supply. Kumho Petrochemical anchors high-cis polybutadiene output for premium tire clients across Northeast Asian manufacturing clusters.
Synthetic rubber comprises elastomeric polymers synthesized from petrochemical feedstocks, primarily styrene-butadiene, polybutadiene, and ethylene-propylene-diene monomer formulations, produced through solution or emulsion polymerization processes to deliver specified tensile strength, abrasion resistance, and glass transition temperatures for load-bearing applications. SBR and BR product categories dominate volume flows into tire manufacturing, where performance-grade specifications command margin premiums over general-purpose grades. Application segmentation shows tires absorbing the majority of offtake, while adhesives and sealants represent faster-growing specialty outlets driven by construction and electronics assembly demand.
EPA emission standards and REACH chemical registration frameworks constrain formulation choices and processing methods in the United States and European supply corridors. China's GB standards and MIIT industrial guidelines shape domestic production quotas and import substitution targets for synthetic rubber grades. Stakeholders must monitor regulatory divergence between jurisdictions to align product certification strategies with regional compliance thresholds.
Market Dynamics
Electric vehicle range optimization mandates are restructuring tire compound specifications, forcing compounders to source solution-polymerized SBR with lower rolling resistance coefficients than conventional emulsion grades.
Growth Catalysts
- REACH VOC limits:European tire manufacturers accelerate reformulation to meet ECHA volatile organic compound thresholds in rubber processing, creating specification premiums for low-emission SBR grades.
- Solution polymerization:This production method delivers superior molecular weight distribution control, enabling compounders to meet OEM traction and durability targets for high-performance tires.
- China domestic automakers:Local EV producers are consolidating supply chain requirements around specialty elastomers, concentrating demand for high-cis polybutadiene within domestic manufacturing clusters.
Market Restraints
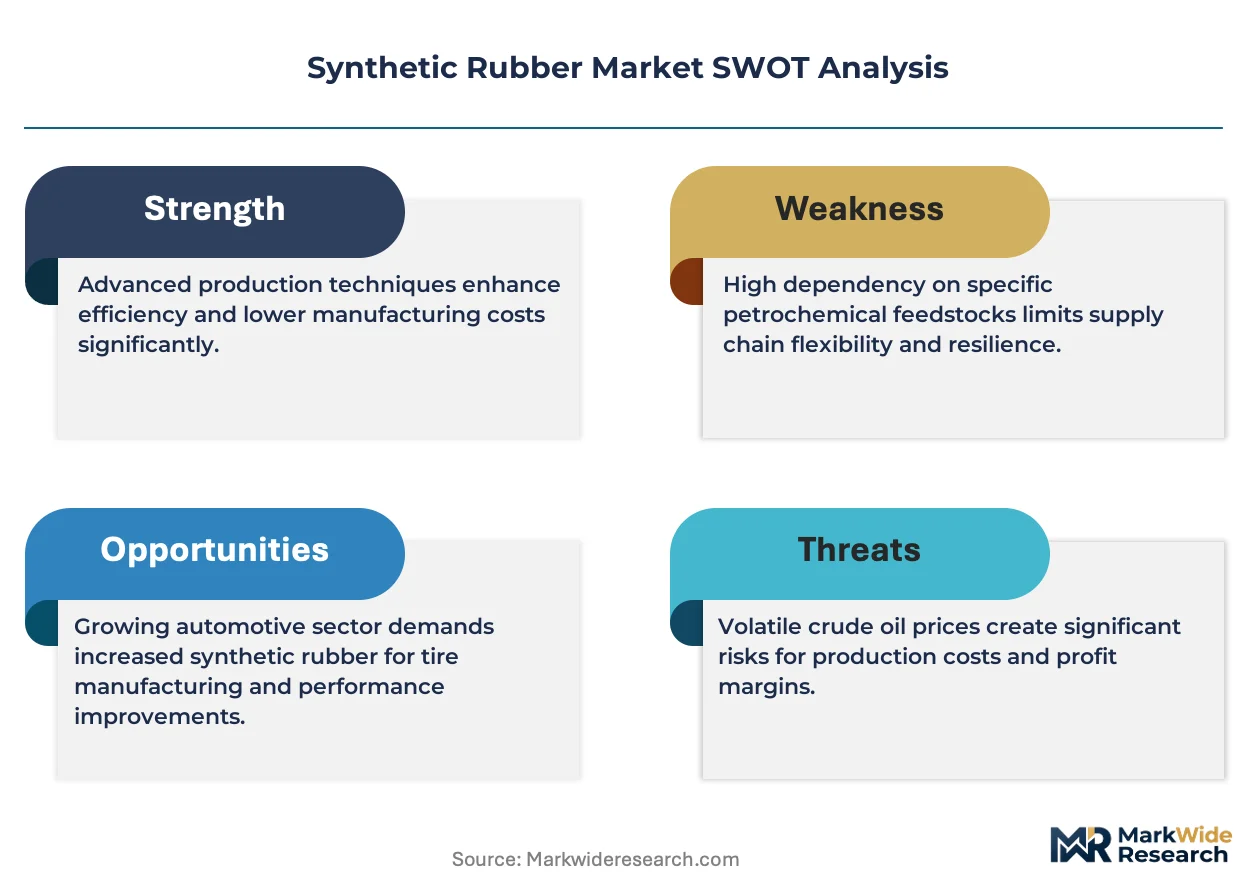
- Butadiene feedstock volatility:Crude oil price swings transmit directly to synthetic rubber production economics, compressing margin visibility for non-integrated compounders.
- Natural rubber substitution ceiling:Hevea brasiliensis latex retains cost advantages in heavy-duty truck tire applications, capping synthetic penetration in load-bearing segments.
- European supply concentration:Integrated petrochemical complexes in Germany and the Netherlands control majority BR capacity, creating geographic vulnerability to energy cost shocks.
Strategic Opportunities
- India tire manufacturing:Domestic production capacity expansions by Apollo Tyres and MRF create localized demand for emulsion SBR that currently relies on imports.
- Adhesives and sealants:Construction and electronics assembly applications are absorbing specialty EPDM grades at faster rates than tire offtake, opening margin-rich outlets.
- EPA Tier 3 standards:Tightening particulate matter limits for heavy-duty vehicles are mandating advanced tread compounds that favor high-performance synthetic formulations.
Industry Challenges
- ISO 16396 certification timelines:Automotive OEM qualification protocols for polybutadiene rubber require 18-24 month validation cycles, delaying supplier switching decisions.
- Polymerization process reconfiguration:Transitioning from emulsion to solution SBR requires capital-intensive reactor modifications that strain mid-tier compounder balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Synthetic Rubber Market |
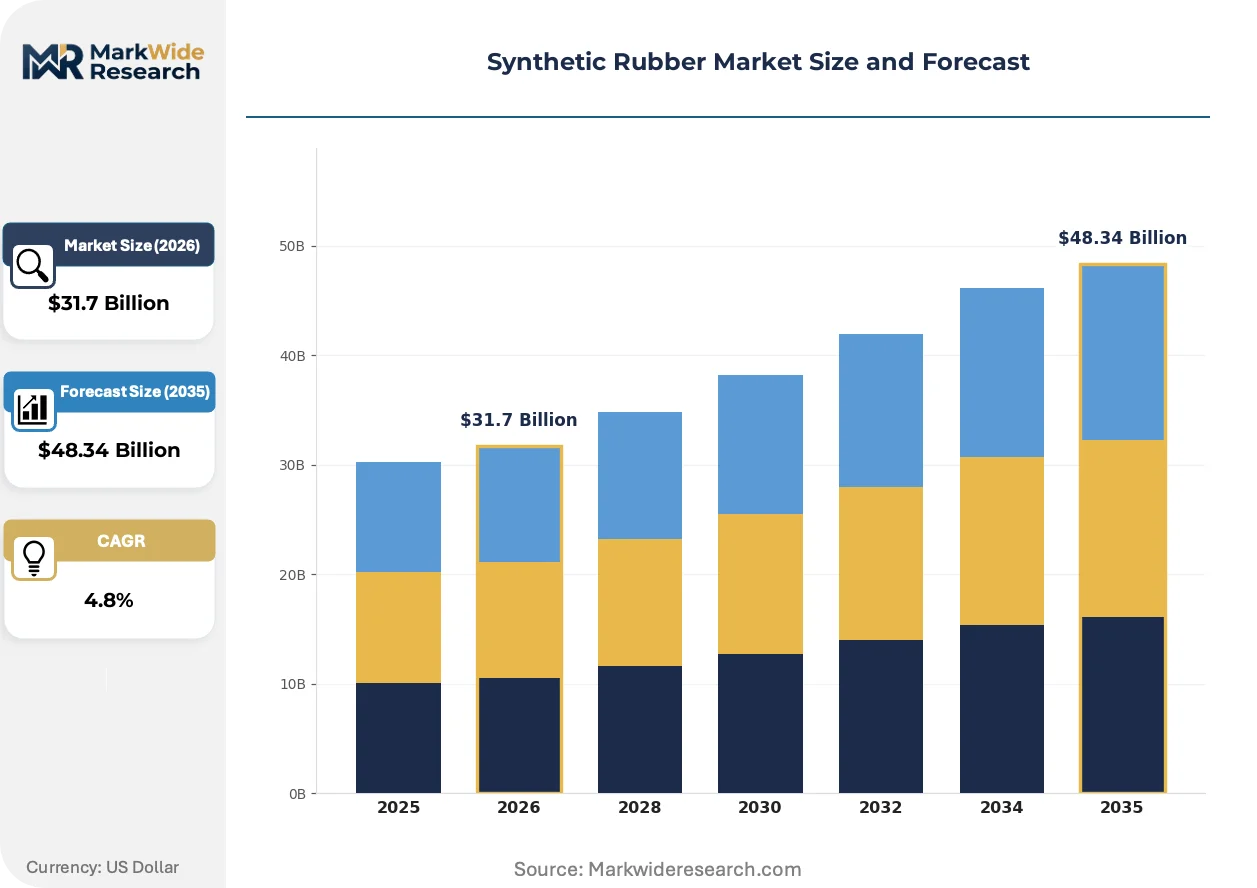
| Market Size in 2026 | $31.7 Billion |
| Market Size in 2035 | $48.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBR, BR, EPDM, NBR Application: Tires, Footwear, Adhesives, Sealants End User: Automotive, Consumer Goods, Construction, Electronics Form: Solid, Liquid, Powder, Granules |
| Companies Covered | JSR Corporation, Lanxess, Sinopec, Synthos, ExxonMobil Chemical, Arlanxeo, LG Chem, Zeon Corporation, Kumho Petrochemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Synthetic Rubber Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are simultaneously expanding performance specifications and narrowing formulation freedom for compounders serving mobility and industrial applications.
Functionalized solution SBR with silane coupling agents is bifurcating the tire compound market. Premium OEMs specify these grades for EV-optimized rolling resistance, while value-tier manufacturers retain conventional emulsion SBR for internal combustion vehicle replacement tires. This split is compressing mid-market compounder margins as specification tiers polarize.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber extender oils are forcing reformulation across European tire production. Compounders must source treated distillate aromatic extract alternatives or migrate to naphthenic bases, raising raw material costs by mid-single-digit percentages. The passenger tire segment bears the highest compliance burden due to volume exposure.
Automotive OEMs are consolidating qualified supplier lists around integrated polymer producers with captive feedstock positions. Long-term offtake agreements with Arlanxeo and Kumho Petrochemical are displacing spot-market procurement for high-volume tire programs. This concentration is most visible in Northeast Asian manufacturing clusters where domestic EV producers prioritize supply security over unit cost optimization.
Synthetic Rubber Market Segmentation
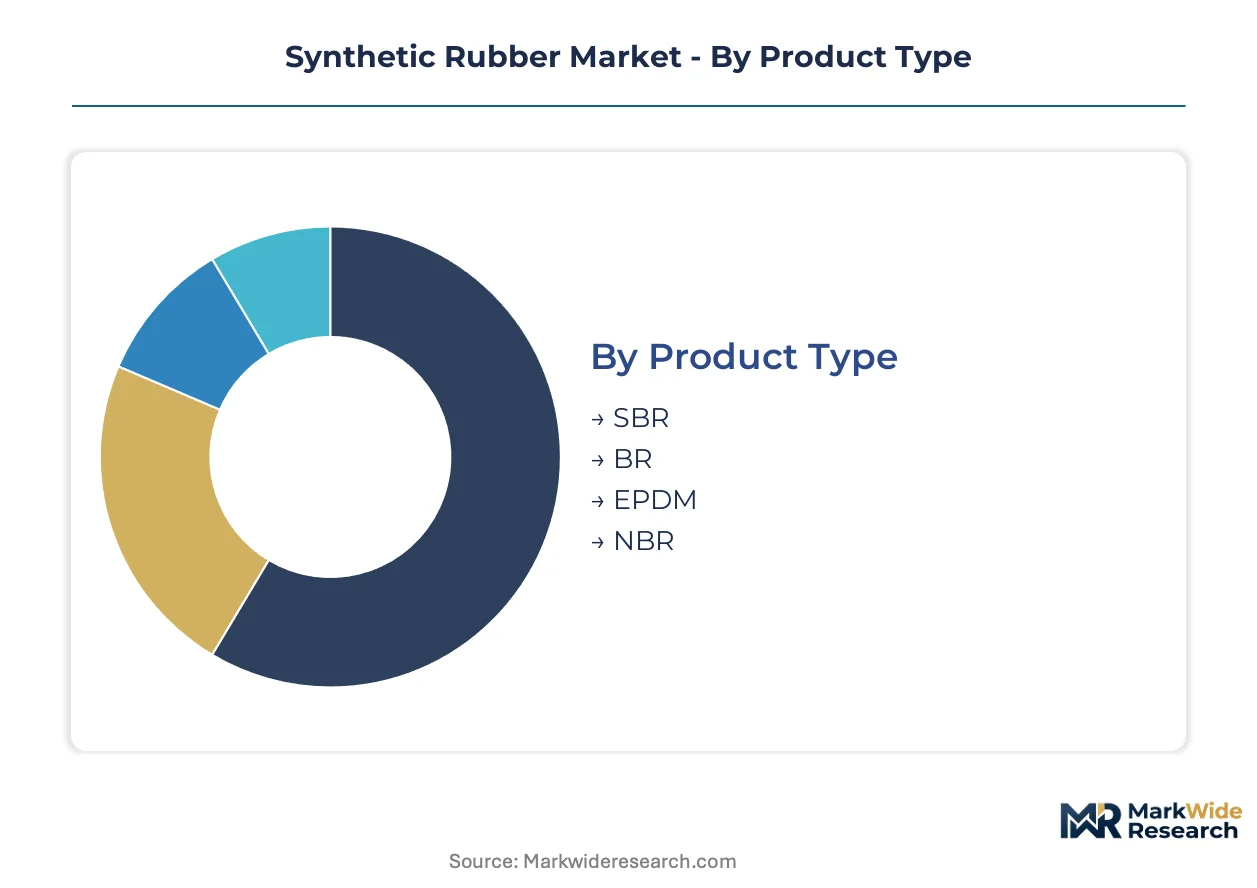
Synthetic rubber flows through distinct specification channels where polymer chemistry determines tire OEM qualification, while specialty grades penetrate adhesives and sealants through distributor networks. Understanding these segment boundaries exposes where margin concentrates versus where volume accumulates.
Product Type:
Solution-polymerized grades command premium positions through direct mill supply agreements, while emulsion variants move through commodity distributors serving replacement tire compounders.
- SBR:Styrene-butadiene rubber dominates tire tread formulations through two distinct supply channels—solution grades for OEM electric vehicle programs, emulsion grades for aftermarket replacement demand. European tire manufacturers are consolidating procurement around low-VOC solution SBR to meet ECHA thresholds.
- BR:Polybutadiene rubber delivers the high-cis microstructure specifications required for sidewall durability and tread wear resistance in premium tire architectures. Northeast Asian manufacturing clusters concentrate demand as domestic automakers localize EV supply chains around specialty elastomers.
- EPDM:Ethylene-propylene-diene monomer rubber serves construction membrane and automotive weatherseal applications through formulated compound distributors.
- NBR:Nitrile butadiene rubber penetrates industrial hose and seal applications where oil resistance specifications govern procurement decisions.
By volume, SBR leads. By growth pace, BR is ahead.
Application:
Cost tier stratification separates specification-grade compounders serving OEM tire programs from general-purpose processors supplying construction adhesives.
- Tires:Original equipment manufacturers enforce ISO 16396 certification protocols that lock compounders into 18-24 month qualification cycles with approved polymer suppliers. Rolling resistance optimization for electric vehicle range extension is restructuring SBR procurement toward solution-polymerized grades.
- Adhesives:Construction and electronics assembly applications absorb specialty EPDM and SBR grades at expansion rates exceeding tire offtake, with formulated products commanding margin premiums over base polymer sales.
- Footwear:Soling compounds utilize emulsion SBR for cost-sensitive mass market production, with limited specification barriers to supplier switching.
- Sealants:Building envelope and automotive seam sealing applications specify EPDM and silicone-modified grades through regional building material distributors.
Tire applications anchor volume throughput. Adhesives deliver the steepest expansion trajectory.
End User:
Customer type determines whether procurement flows through long-term offtake agreements or spot market purchasing, with automotive OEMs consolidating supplier lists around integrated producers.
- Automotive:Tier-1 tire manufacturers negotiate multi-year supply agreements with Arlanxeo and Kumho Petrochemical for high-cis BR and solution SBR, displacing spot-market procurement as supply security priorities override unit cost optimization.
- Construction:Regional building material formulators source EPDM and standard SBR through distributor networks with limited vertical integration requirements.
- Consumer Goods:Footwear manufacturers and household product molders purchase emulsion SBR through trading companies with flexible volume commitments.
- Electronics:Precision sealant and adhesive formulators specify ultra-low volatile content grades to meet EPA Tier 3 and REACH Annex XVII compliance thresholds.
Automotive end users dominate contract value. Electronics represents the fastest-climbing specification tier.
Form:
Processing economics and downstream handling requirements segment supply chains between bulk railcar deliveries and packaged specialty shipments.
- Solid:Bales constitute the standard delivery format for tire mill consumption, with rail and bulk truck logistics optimized for high-volume compounder intake.
- Liquid:Low-molecular-weight grades serve adhesive and sealant formulators requiring pumpable delivery systems and reduced mixing energy.
- Powder:Free-flowing particulate forms enable automated dosing in dry-blend rubber compounding for specialty industrial applications.
- Granules:Controlled particle size distributions support consistent dispersion in masterbatch production for color-critical consumer goods.
Solid bales move the greatest tonnage. Liquid forms are expanding most quickly in adhesives and sealants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tire compounders cluster procurement decisions around integrated petrochemical corridors where butadiene feedstock security determines supplier selection. Automotive OEM qualification protocols lock manufacturing locations into multi-year supply agreements.
China
Domestic EV producers are consolidating specialty elastomer requirements within Yangtze River Delta manufacturing clusters. MIIT industrial guidelines shape production quotas for high-cis polybutadiene grades. Qingdao and Shanghai anchor tire mill demand as local automakers localize supply chains.
Germany
Arlanxeo's integrated butadiene position sustains cost leadership for European BR supply. REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons force reformulation across tire production. The Rhine-Ruhr petrochemical corridor concentrates qualified supplier capacity.
United States
EPA Tier 3 particulate matter limits mandate advanced tread compounds for heavy-duty vehicle applications. Gulf Coast petrochemical complexes provide feedstock integration for SBR producers. Texas and Louisiana host the majority of domestic solution polymerization capacity.
South Korea
Kumho Petrochemical anchors high-cis polybutadiene output for premium tire clients. Domestic automakers prioritize supply security over unit cost in long-term offtake negotiations. Ulsan and Yeosu manufacturing clusters concentrate specialty elastomer demand.
Japan
JSR Corporation and Zeon Corporation occupy positions within the solution SBR tier serving OEM electric vehicle programs. METI standards influence rubber processing emission thresholds. Chubu and Kanto industrial zones concentrate tire mill compounder activity.
Synthetic Rubber Market Vendor Landscape
Player mix skews toward integrated petrochemical conglomerates with captive butadiene positions. The supplier base concentrates around producers with solution polymerization capabilities and ISO 16396 certification status. Two strategic archetypes dominate: integrated feedstock owners and specialty polymerization specialists. Capacity expansion and long-term offtake agreements with automotive OEMs represent the dominant competitive moves.
Within the integrated feedstock tier, Arlanxeo and Kumho Petrochemical exemplify producers leveraging captive butadiene supply to secure tire mill contracts. JSR Corporation occupies a position among Japanese specialists emphasizing solution polymerization for electric vehicle-optimized grades. These three companies represent the concentration of qualified supply for premium OEM programs.
| Leading Market Players |
|---|
| JSR Corporation |
| Lanxess |
| Sinopec |
| Synthos |
| ExxonMobil Chemical |
| Arlanxeo |
| LG Chem |
| Zeon Corporation |
| Kumho Petrochemical |
| Others |
Supply Flow & Price Mechanics
Integrated butadiene capacity utilization above 85 percent in the Rhine-Ruhr and Ulsan corridors locks in cost advantages that compounders without captive feedstock cannot match. This scale concentration compresses margin recovery for spot-market buyers while elevating price floors for solution-polymerized grades serving ISO 16396-certified OEM programs.
Pricing Analysis
Cost-plus contracts with butadiene indexation dominate procurement between integrated producers and Tier 1 tire manufacturers. Price differentiation rests on certification tier—ISO 16396-qualified BR commands premiums over general-purpose emulsion grades—and volume scale through multi-year offtake agreements. Cost compression in mid-tier emulsion SBR is intensifying because Chinese domestic automakers are consolidating procurement around specialty elastomers. Aftermarket replacement tire compounders exhibit the highest price sensitivity, while automotive OEMs prioritize supply security over unit cost optimization.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes have elevated inbound logistics costs for non-integrated compounders sourcing spot butadiene. Supply concentrates in Germany, South Korea, and China, with the Rhine-Ruhr, Ulsan, and Yangtze River Delta corridors anchoring qualified capacity. Raw material dependencies center on butadiene monomer, styrene feedstock, and specialized extender oils subject to REACH Annex XVII restrictions. Single-source vulnerability to energy cost shocks in European petrochemical clusters represents the dominant structural risk. Distribution runs through direct mill supply agreements for premium grades and commodity distributors for standard-tier products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electric vehicle range optimization mandates are restructuring tire compound specifications at a pace that favors producers with solution polymerization capabilities and captive feedstock positions. REACH and EPA regulatory convergence on volatile organic compound limits is accelerating qualification protocol complexity.
For Market Incumbents: Fortify ISO 16396 certification coverage across high-cis polybutadiene grades to defend against Korean and Chinese producers consolidating domestic EV supply chains. Prioritize backward integration into butadiene feedstock where capacity utilization supports scale economics, and lock in multi-year offtake agreements with automotive OEMs before qualification cycles extend further. For New Entrants and Emerging Players: Technical service gaps in adhesives and sealants formulation support—where incumbent polymer producers under-serve regional building material distributors—offer the most penetrable white space. Target construction-grade EPDM through formulated compound partnerships rather than direct mill supply, and pursue distributor-led go-to-market models that bypass 18-24 month OEM qualification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive butadiene positions and established automotive OEM qualification status. Long-term viability over a multi-year horizon favors acquisition targets with solution polymerization assets and ISO 16396 certification in place. Watch for inflection signals in India tire manufacturing capacity expansion announcements by Apollo Tyres and MRF as indicators of localized emulsion SBR demand formation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Butadiene Feedstock | Arlanxeo's integrated position sustains cost leadership against spot-market dependent competitors. |
| Solution Polymerization Capacity Expansion | JSR Corporation and Zeon Corporation anchor premium OEM electric vehicle program supply. |
| ISO 16396 Certification Investment | Automotive qualification protocols lock compounders into 18-24 month validation cycles with approved suppliers. |
| Long-term Supply Agreement with Domestic Automakers | Kumho Petrochemical secures Northeast Asian manufacturing cluster demand through supply security prioritization. |
| Specialty EPDM Formulation Partnership | Construction and electronics assembly applications absorb grades at expansion rates exceeding tire offtake. |
Methodological Framework
A spread of perspectives from tire compounder procurement directors, automotive OEM platform engineers, petrochemical plant managers, and specialty elastomer R&D leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with downstream formulation specialists and upstream polymerization operators. Secondary validation drew from customs and trade flow databases, SEC 10-K filings of integrated chemical producers, and industry association reports published by ACC and Cefic. Bottom-up demand modeling across tire, adhesives, and sealants applications was triangulated against top-down capacity assessments from major production corridors.
Segmentation dimensions modeled include polymer chemistry grade, end-use industry vertical, geographic production hub, and certification tier across the projection horizon. Volume and value outputs reflect analytical framework integration of historical trade data, announced capacity additions, and regulatory compliance cost overlays. CAGRs were derived from elasticity-adjusted demand projections and supply-side constraint modeling. Forecast inputs incorporated electric vehicle penetration assumptions for tire compound specifications and REACH Annex XVII reformulation cost pass-through estimates.
Material uncertainties—feedstock price volatility, regulatory timeline acceleration, and automotive OEM supplier consolidation decisions—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding qualification cycle durations and capacity utilization thresholds. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Global Rubber Process Oil Market
Rubber
Isoprene Rubber Market
Rubber
Rubber Compound Market
Rubber
Corrosion Protection Rubber Linings and Coatings Market
Rubber
Oil Saver Rubber Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Tire Recycling Downstream Products Market
Rubber
Polyacrylate Rubber Market
Rubber
Performance Elastomers Market
Rubber
Acrylic Based Elastomers Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Rubber Color Masterbatch Market
Rubber
Global Rubber Additives Market
Rubber
Europe Neoprene Market
Rubber
Rubber Block Market