
 Concrete Densification and Polishing Material Market | 2026-2036
Concrete Densification and Polishing Material Market Size, Share, and Industry Trends Forecast 2026-2036
Concrete Densification and Polishing Material Market Analysis
REACH compliance in Europe is repositioning the cost-of-entry calculus for imported densifier formulations, forcing reformulation of sodium silicate and lithium silicate chemistries. Sika AG leverages its European manufacturing footprint to sustain compliant supply chains without cross-border formulation bottlenecks. BASF SE anchors its position through R&D intensity in nano-silica dispersions that meet both REACH and evolving German DIBt standards for indoor air quality.
Concrete densification and polishing materials comprise reactive silicate-based solutions, typically lithium, sodium, or potassium silicates with 10-25% solids content, that penetrate concrete capillaries to form calcium silicate hydrate gels and increase surface hardness from 4-6 to 7-9 on the Mohs scale. These materials serve the primary industrial purpose of eliminating dusting, reducing permeability, and creating a polished, light-reflective finish suitable for high-traffic commercial and industrial floors. Densifiers dominate product type revenue due to their position as the mandatory first treatment in multi-step polishing systems, while sealers capture expanding margin pools as end users specify extended warranty protection in warehouse and data center applications. The contractor end-user segment leads volume absorption, though facility managers represent the fastest-growing specification authority as asset life-cycle cost analysis replaces first-cost bidding in commercial procurement.
The EPA regulates VOC emissions from architectural coatings in the United States, directly constraining solvent-based sealer formulations and accelerating waterborne product development. OSHA silica exposure limits during concrete grinding operations shape contractor equipment choices and drive demand for wet-polishing systems that integrate with densifier application workflows. Germany's DIBt and France's ANSM indoor air quality protocols add parallel compliance layers for products specified in European commercial buildings. Stakeholders must monitor how evolving state-level low-carbon procurement rules in California, New York, and Washington integrate embodied carbon criteria into material selection beyond traditional performance metrics.
Market Dynamics
LEED v4 and comparable green building codes are compressing specification windows for high-VOC floor coatings, forcing facility managers toward lithium silicate densifiers that satisfy both performance and emissions criteria. This regulatory tightening intersects with rapid industrial construction in the American Sun Belt, where warehouse and logistics center buildouts are outpacing national averages.
Growth Catalysts
- LEED v4 VOC limits:Facility managers in the United States are specifying low-emission lithium silicate densifiers to meet green building certification requirements, eliminating solvent-based alternatives from bid pools.
- Warehouse construction clusters:Texas, Arizona, and Florida are seeing industrial floor square footage expand faster than national benchmarks, concentrating densifier demand in the American Sun Belt.
- Silica exposure protocols:OSHA wet-grinding mandates are accelerating contractor adoption of integrated densifier application workflows that reduce airborne crystalline silica during polishing operations.
Market Restraints
- Alkali metal price volatility:Lithium carbonate and sodium hydroxide input costs fluctuate with battery sector demand, squeezing densifier formulation margins without immediate pass-through mechanisms.
- REACH formulation barriers:European chemical registration requirements are raising cost-of-entry for imported sodium silicate and lithium silicate products, advantaging regional manufacturers with compliant supply chains.
- Epoxy coating substitution:High-build epoxy systems retain specification share in pharmaceutical and food processing facilities where seamless, coved flooring is mandatory.
Strategic Opportunities
- Data center floor specifications:Hyperscale computing facilities are adopting polished concrete with extended warranty sealers to manage static electricity and thermal cycling in server halls.
- California low-carbon procurement:State-level embodied carbon criteria are creating preference windows for densifiers with verified lifecycle assessments against higher-carbon coating alternatives.
- Wet-polishing system integration:Equipment manufacturers are bundling densifier application stages into automated grinding platforms, creating captive chemical demand through machine-software-chemistry convergence.
Industry Challenges
- Polishing technician certification gaps:The Concrete Polishing Association of America and comparable bodies face backlogs in certifying contractors on multi-step densifier-sealer-burnishing sequences, constraining quality installation capacity.
- Cross-border formulation complexity:Manufacturers maintaining separate REACH-compliant and EPA-registered product lines face inventory fragmentation and working capital duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Concrete Densification and Polishing Material Market |
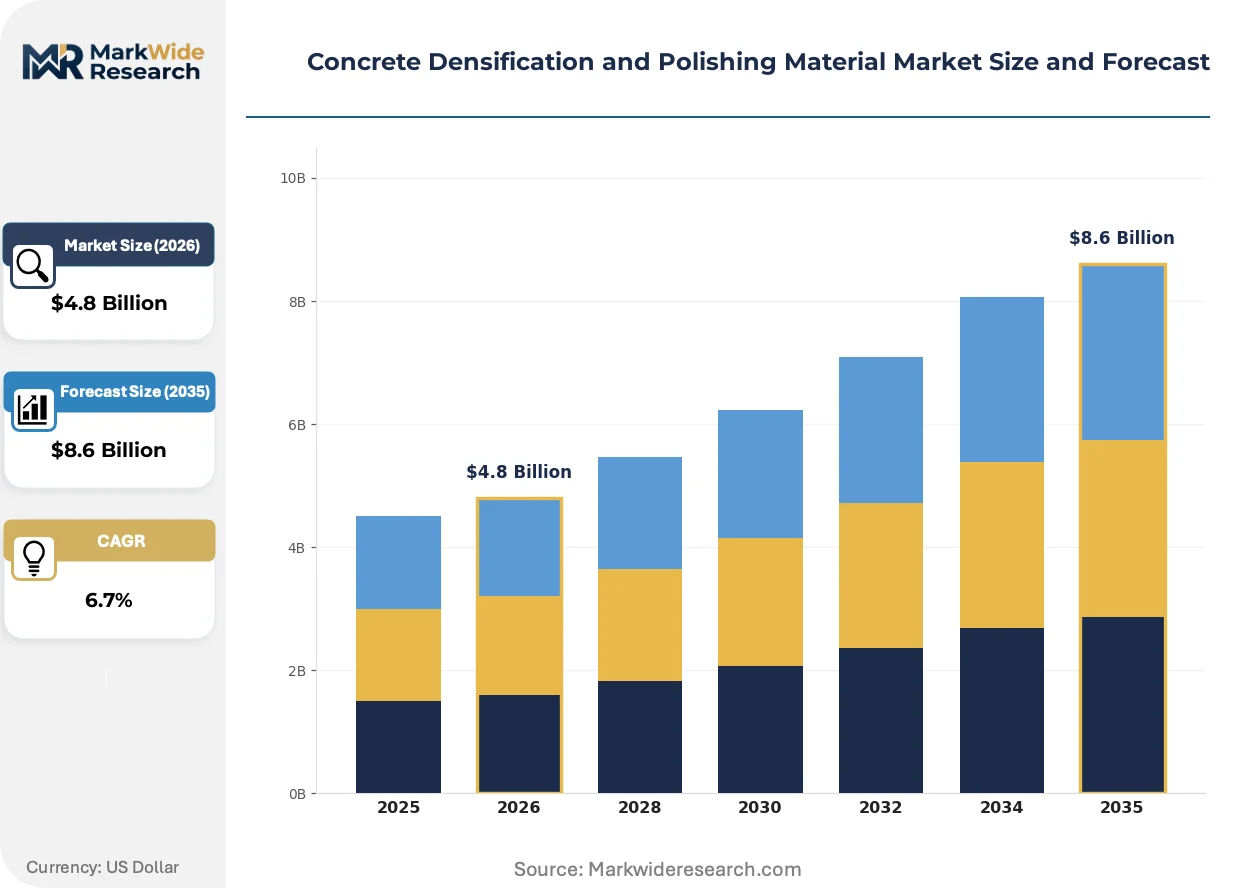
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Densifiers, Sealers, Hardeners, Polishing Compounds Application: Flooring, Industrial Spaces, Commercial Facilities, Residential Areas End User: Contractors, Facility Managers, Homeowners, Architects Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | LATICRETE International, Inc., Husqvarna AB, The Euclid Chemical Company, Sika AG, BASF SE, Flowcrete Group Ltd., Markham Global Ltd., Hilti, W.R. Meadows Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Concrete Densification and Polishing Material Market Emerging Trajectories
Nano-silica dispersion technologies are compressing the performance gap between mid-tier and premium densifier formulations, while regulatory layering across jurisdictions forces product architecture decisions earlier in development cycles. These shifts are rewiring how manufacturers prioritize R&D spend and geographic registration sequencing.
Nano-silica colloidal suspensions with particle sizes below 50 nanometers are penetrating concrete capillaries more deeply than conventional lithium silicates, producing harder, more abrasion-resistant surfaces with reduced application volumes. Data center operators and high-throughput distribution centers are specifying these formulations for 20-year wear warranties. This penetration depth advantage is rewriting the unit economics of multi-step polishing systems by reducing reapplication frequency.
REACH authorization requirements for sodium silicate classifications are forcing reformulation of legacy densifier chemistries ahead of 2026 sunset dates for certain hazard categories. German DIBt indoor air quality protocols are adding parallel compliance layers that exceed baseline EU requirements. Manufacturers with European manufacturing footprints are capturing specification share from importers facing cross-border registration bottlenecks.
Facility managers in warehousing and logistics are displacing first-cost bidding with lifecycle cost analysis that weights slab longevity, maintenance intervals, and downtime costs. General contractors are responding by bundling densifier specifications into design-build contracts with extended performance guarantees. This analytical shift is most visible in Texas and Florida industrial corridors where rapid facility turnover makes asset depreciation schedules decisive in material selection.
Concrete Densification and Polishing Material Market Segmentation
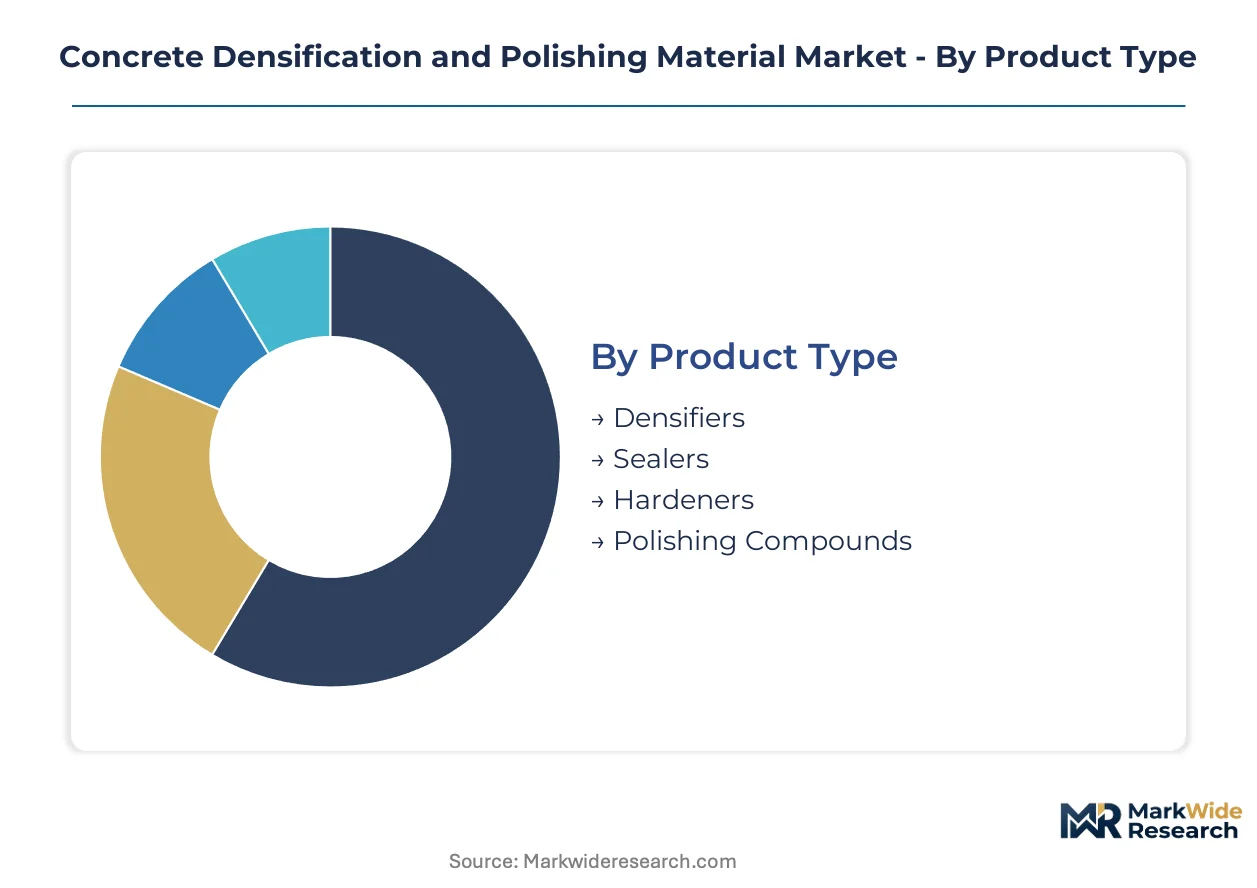
Concrete densification materials operate across distinct specification layers—some function as mandatory base treatments in multi-step systems, others as optional performance enhancers. Understanding where each segment sits in the installation sequence reveals margin concentration and contractor purchasing patterns.
Product Type:
Densifiers anchor standalone application workflows as the non-negotiable first step, while sealers and hardeners embed into extended warranty systems that compound labor and chemistry costs.
- Densifiers:Reactive lithium, sodium, or potassium silicate solutions with 10-25% solids content penetrate concrete capillaries to form calcium silicate hydrate gels. Demand clusters in Texas and Arizona warehouse construction where slab longevity requirements exceed 20 years. LEED v4 VOC limits are eliminating solvent-based alternatives from bid pools.
- Sealers:Topical or penetrating formulations provide stain resistance and warranty protection for polished concrete finishes. Data center operators in Northern Virginia and Dallas-Fort Worth specify extended-coverage sealers to manage static electricity and thermal cycling in server halls.
- Hardeners:Surface-modifying treatments that accelerate abrasion resistance development.
- Polishing Compounds:Abrasive suspensions for burnishing stages that refine light reflectivity.
Volume placements concentrate in densifiers; the faster expansion belongs to sealers as warranty specifications lengthen.
Application:
Cost tier stratification separates high-square-footage industrial specifications from discretionary residential spending, with commercial facilities occupying the contested middle ground where lifecycle analysis displaces first-cost bidding.
- Flooring:Polished concrete surfaces in warehouses, logistics centers, and retail environments. OSHA wet-grinding mandates are accelerating contractor adoption of integrated densifier-sealer workflows that reduce airborne crystalline silica exposure.
- Industrial Spaces:Manufacturing floors, distribution centers, and cold storage facilities requiring chemical resistance and thermal shock tolerance. The American Sun Belt—specifically Florida, Texas, and Arizona—is outpacing national construction averages.
- Commercial Facilities:Office buildings, educational institutions, and healthcare environments where aesthetic performance intersects with maintenance cost control.
- Residential Areas:High-end custom homes and renovation projects where decorative concrete finishes command premium positioning.
Industrial spaces absorb the highest absolute volumes; commercial facilities are climbing the fastest as asset life-cycle cost analysis penetrates procurement.
End User:
Customer type determines specification authority—contractors execute purchases but facility managers increasingly control material selection through performance guarantees and warranty terms.
- Contractors:Polishing specialists and general flooring contractors who apply densifiers as part of multi-step grinding sequences. Certification backlogs from the Concrete Polishing Association of America are constraining quality installation capacity.
- Facility Managers:Asset stewards in warehousing, logistics, and data center operations who specify materials based on total cost of ownership. Procurement is shifting from first-cost bidding to lifecycle analysis that weights slab longevity against maintenance intervals.
- Homeowners:Individual consumers in residential renovation and new construction markets.
- Architects:Design professionals who embed densifier specifications into construction documents.
Contractors dominate current volume; facility managers are gaining share fastest as extended performance guarantees become standard in industrial procurement.
Distribution Channel:
Supply concentration varies by urgency and specification complexity—wholesale and direct channels capture project-scale volume while online retail serves spot purchasing and geographic expansion.
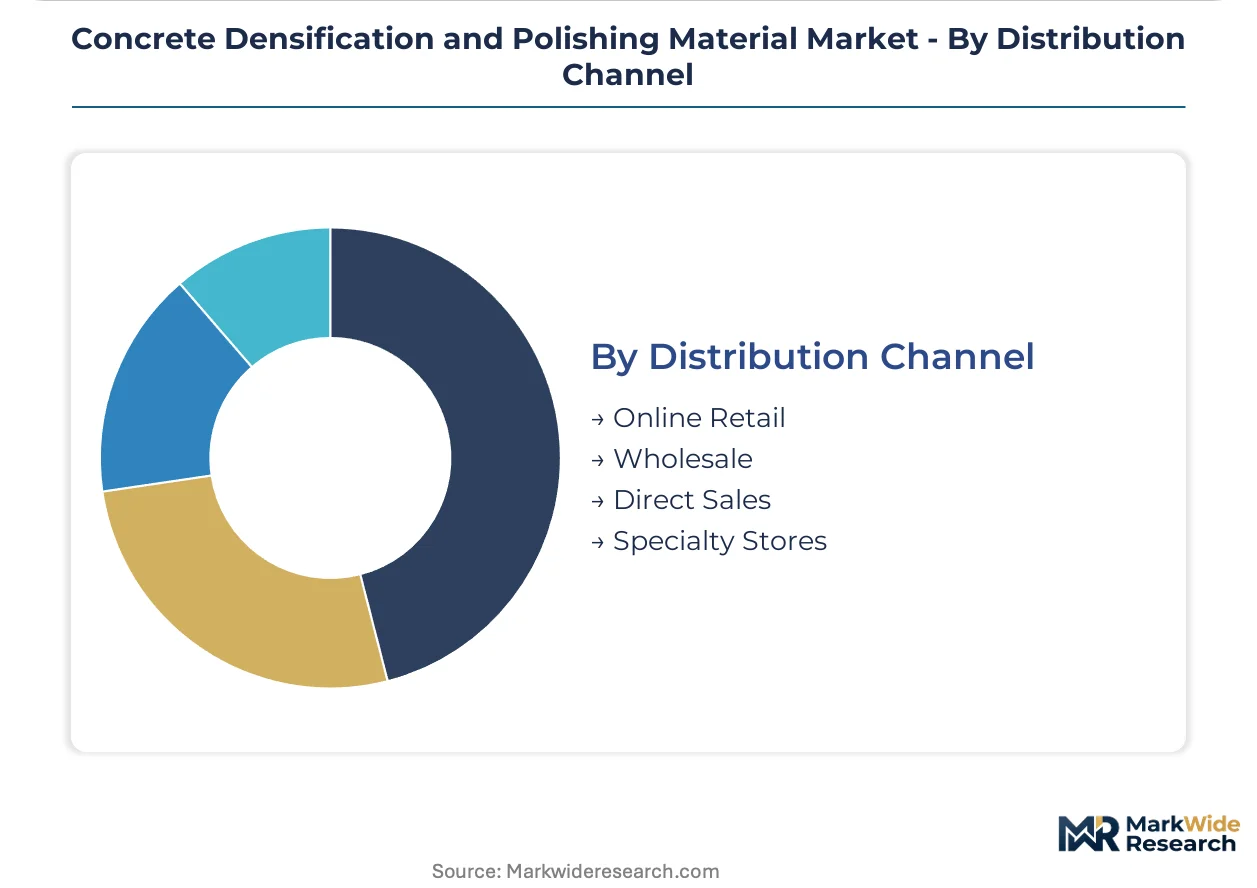
- Online Retail:E-commerce platforms serving small contractors and maintenance departments with standard formulations. REACH-compliant product lines face cross-border registration bottlenecks that fragment inventory availability.
- Wholesale:Distributor networks supplying project-scale densifier and sealer volumes to certified polishing contractors. Texas and Florida industrial corridors concentrate wholesale demand as warehouse construction accelerates.
- Direct Sales:Manufacturer-to-contractor relationships for specification-grade nano-silica formulations and extended-warranty systems.
- Specialty Stores:Regional suppliers serving local contractor bases with application support and technical service.
Wholesale channels capture the greatest volume; direct sales are expanding most quickly as equipment-chemistry bundling creates captive supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foreign Trade Zones in Texas and Florida are accelerating warehouse construction, concentrating densifier demand in Sun Belt logistics corridors. EPA VOC regulations and OSHA silica protocols shape material specification authority across industrial flooring markets. LEED v4 compliance requirements are displacing solvent-based alternatives in commercial procurement nationwide.
United States
Texas and Arizona warehouse construction is outpacing national benchmarks, driven by Foreign Trade Zone incentives and nearshoring logistics demand. EPA architectural coating regulations constrain solvent-based sealer formulations, accelerating waterborne lithium silicate adoption. Dallas-Fort Worth and Phoenix industrial corridors concentrate specification-grade densifier procurement for 20-year slab warranties.
Germany
REACH authorization timelines are forcing sodium silicate reformulation ahead of 2026 hazard category sunsets. DIBt indoor air quality protocols exceed baseline EU requirements, advantaging regional manufacturers with compliant supply chains. Bavaria and North Rhine-Westphalia industrial zones anchor specification demand for nano-silica formulations in manufacturing floors.
China
Dual carbon goals are compressing embodied carbon thresholds for commercial building materials in Yangtze River Delta logistics hubs. MIIT industrial standards for construction chemicals are tightening quality certification requirements. Shanghai and Shenzhen data center clusters are specifying polished concrete with extended-warranty sealers for thermal cycling management.
India
PLI scheme incentives for electronics manufacturing are expanding cleanroom-grade flooring specifications in Karnataka and Tamil Nadu. BIS construction chemical standards are formalizing densifier performance testing protocols for industrial applications. Mumbai-Pune and Chennai automotive corridors concentrate demand for abrasion-resistant polished concrete in component assembly facilities.
United Arab Emirates
MOHAP building material regulations are aligning with Gulf green building codes to restrict high-VOC floor coatings in commercial developments. Dubai South and Khalifa Industrial Zone logistics buildouts are specifying low-emission densifiers for warehouse longevity in harsh climate conditions. Abu Dhabi sustainable construction mandates are embedding lifecycle cost analysis into material procurement frameworks.
Concrete Densification and Polishing Material Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation and application equipment segments. Market structure shows moderate concentration, with chemical majors leveraging R&D scale against regional manufacturers with compliant supply chains. Two strategic archetypes dominate: integrated construction chemical suppliers with global registration capabilities, and equipment-chemistry bundlers capturing captive demand through automated polishing platforms. Competitive moves center on REACH-compliant formulation portfolios and wet-polishing system integration.
Within the diversified chemical tier, Sika AG and BASF SE exemplify manufacturers with European manufacturing footprints that sustain compliant supply chains without cross-border bottlenecks. LATICRETE International, Inc. occupies a position among specialized construction material suppliers with project-scale distribution networks. These three anchors represent distinct strategic postures: global registration scale, nano-silica R&D intensity, and contractor-channel specialization respectively.
| Leading Market Players |
|---|
| LATICRETE International, Inc. |
| Husqvarna AB |
| The Euclid Chemical Company |
| Sika AG |
| BASF SE |
| Flowcrete Group Ltd. |
| Markham Global Ltd. |
| Hilti |
| W.R. Meadows Inc. |
| Others |
Supply Flow & Price Mechanics
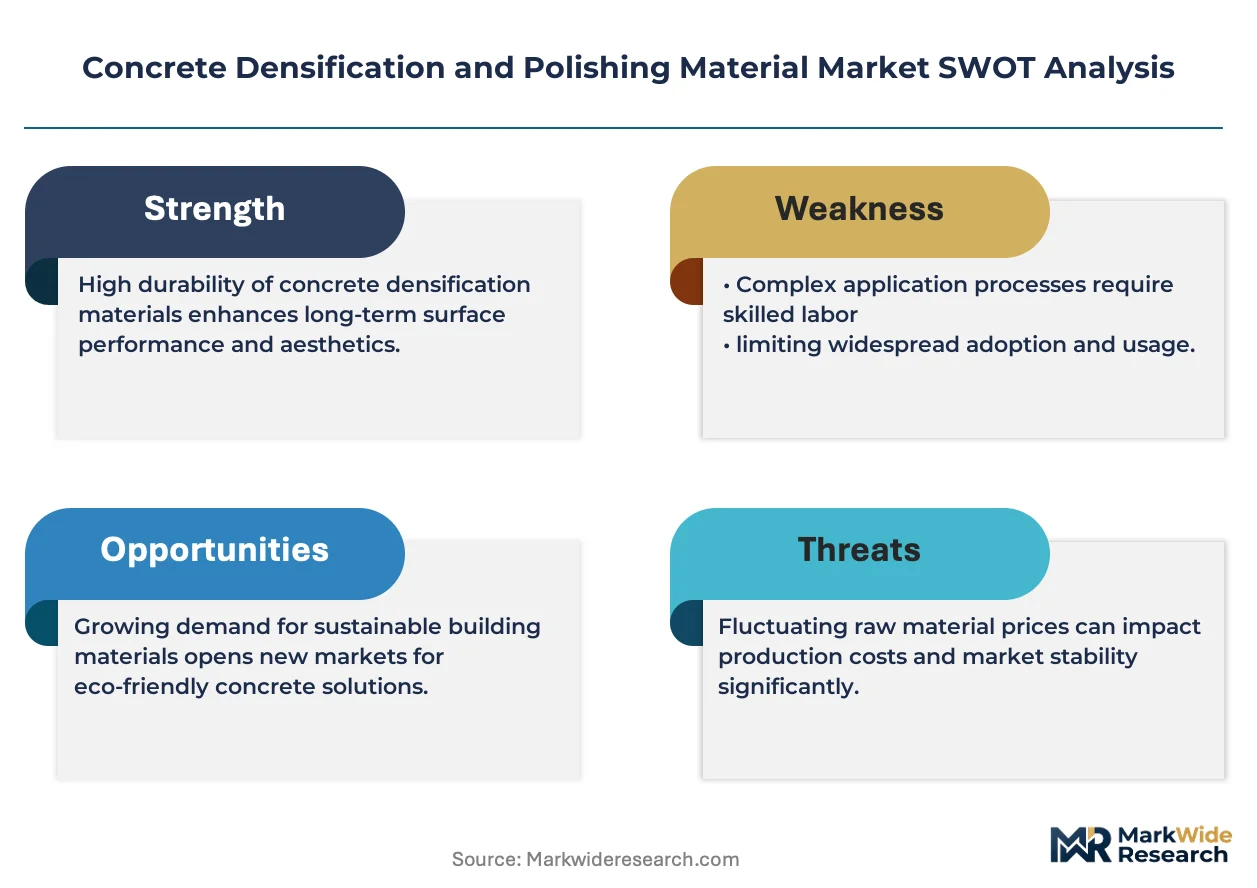
Facility managers in Texas and Arizona warehouse operations anchor specification-grade densifier procurement, driving a project-based pricing model where extended warranty terms command premium positioning against spot-market alternatives. This buyer concentration compresses margin pools for standard formulations while concentrating pricing power with manufacturers offering REACH-compliant nano-silica portfolios.
Pricing Analysis
Short lead-time premiums separate emergency replenishment orders from scheduled project deliveries, with Texas industrial corridors absorbing expedited freight costs to maintain construction timelines. Three-tier pricing structure across specification-grade, commercial-standard, and economy formulations reflects certification tier and solids content concentration. Cost compression in sodium silicate formulations is intensifying because battery-sector lithium carbonate demand is squeezing alkali metal input availability. Small polishing contractors exhibit highest price sensitivity, while data center operators prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China anchor hub-and-spoke patterns that position REACH-compliant inventory within 48-hour delivery windows of major industrial corridors. Lithium carbonate, sodium hydroxide, and colloidal silica nanoparticles constitute critical input dependencies tethered to battery and electronics manufacturing demand cycles. Single-source vulnerability concentrates in German DIBt-certified formulation facilities serving European specification markets. Distribution runs through wholesale contractor networks in Sun Belt logistics zones, with direct manufacturer relationships capturing hyperscale data center accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-compliant formulation capabilities, with registration cost barriers forcing non-specialist coating manufacturers toward exit or acquisition. Regulatory layering advantages players with European manufacturing footprints and multi-jurisdiction registration scale.
For Market Incumbents: Deepen backward integration into lithium silicate precursor production to insulate margins from battery-sector commodity cycles. Capture specification authority by embedding certified technicians within contractor certification programs, countering the Concrete Polishing Association of America's capacity constraints. Prioritize wet-polishing equipment bundling to create captive chemical demand through automated platform integration. For New Entrants and Emerging Players: Capture white-space in California low-carbon procurement channels where embodied carbon verification creates preference windows against incumbent epoxy coating suppliers. Target data center sealer specifications in Northern Virginia and Dallas-Fort Worth, where static electricity management requirements outpace established coating relationships. Lead with lifecycle cost analysis tools that displace first-cost bidding in facility manager procurement workflows. For Investors and Strategic Acquirers: The window for entry favors regional manufacturers with compliant European supply chains and nano-silica R&D pipelines. Five-to-ten year viability rests on capturing specification-grade densifier share before REACH sunset dates eliminate import-competitive formulations. Watch for lithium carbonate price stabilization as the inflection signal for margin recovery in silicate-based chemistry portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Expansion | Secures specification access in German DIBt and broader EU indoor air quality protocols. |
| Wet-Polishing Equipment Integration | Creates captive densifier demand through OSHA silica compliance bundling with automated grinding platforms. |
| Nano-Silica R&D Intensification | Compresses reapplication frequency for data center 20-year warranty specifications. |
| Contractor Certification Program Investment | Addresses Concrete Polishing Association of America backlogs constraining quality installation capacity. |
| Extended-Warranty Sealer Portfolio Buildout | Captures margin pools in hyperscale computing facilities managing thermal cycling and static electricity. |
Methodological Framework
Multi-period observation of warehouse construction permits, LEED certification filings, and OSHA enforcement patterns anchored the trend analysis, supplemented by interviews with polishing contractors, facility managers at logistics operators, densifier formulation chemists, and wholesale distribution channel managers. Secondary validation drew from EPA architectural coating regulations, ECHA REACH authorization timelines, customs trade data for silicate chemical imports, and SEC filings of diversified construction chemical suppliers. Bottom-up project pipeline tracking across Texas, Arizona, and Florida industrial corridors triangulated against top-down manufacturer revenue segmentation.
Segment-weighting approaches modeled product type, application, end user, and distribution channel dimensions across the projection horizon, with regional construction forecasts and regulatory compliance cost curves informing trajectory assumptions. CAGRs derived from installed base erosion rates and new specification penetration in data center and logistics verticals. Input variables included lithium carbonate price volatility indices, contractor certification backlog estimates, and state-level low-carbon procurement rule adoption timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH authorization scope expansions and battery-sector lithium demand shocks. Outputs reflect documented assumptions regarding construction cycle duration and regulatory implementation schedules. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Global Chemical Mechanical Polishing Slurry Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Tungsten Carbide Balls Market
Abrasives
Super Abrasives Market
Abrasives
Asia-Pacific Abrasives Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Abrasive Grains Market
Abrasives
Chemical Deflasher Market
Abrasives
Grinding Wheels Market
Abrasives
North America Abrasives Market
Abrasives
Artificial Abrasives Market
Abrasives
Superabrasive Electroplated Grinding Wheel Market
Abrasives
Tungsten Carbide Market
Abrasives
Glass Abrasives Market
Abrasives
Global Rubber Bonded Abrasive Market