

Superabrasive Electroplated Grinding Wheel Market Size, Share, and Industry Trends Forecast 2026-2036
Superabrasive Electroplated Grinding Wheel Market Insights
ISO 9001 certification is collapsing as a sufficient qualification for superabrasive wheel suppliers serving aerospace and medical device channels. Saint-Gobain Abrasives leverages its vertically integrated synthetic diamond production to sustain premium positioning in European precision grinding. Tyrolit Group anchors Central European supply through dedicated mold and die service centers. Asahi Diamond Industrial dominates Asian electronics assembly applications with specialized wafer dicing wheel geometries.
A superabrasive electroplated grinding wheel consists of a single layer of diamond or cubic boron nitride (CBN) crystals bonded to a steel or aluminum core through an electrodeposited nickel matrix, typically achieving grain protrusion heights of 30-50% of particle diameter for aggressive material removal with minimal thermal damage. Diamond electroplated wheels lead overall volume due to their hardness superiority in grinding tungsten carbide and advanced ceramics, while CBN electroplated wheels command margin premiums in ferrous alloy precision grinding where diamond suffers chemical degradation. Bonding technology differentiation separates electroplated products from resin and vitrified alternatives through superior form retention and the absence of truing requirements between dressing cycles.
REACH in Europe and OSHA permissible exposure limits in the United States constrain nickel electroplating chemistries, forcing wheel manufacturers to validate alternative bonding matrices or invest in closed-loop plating recovery systems. China's GB standards for abrasive product safety and Japan's JIS B 4130 for grinding wheel specifications create additional compliance layers for cross-border suppliers. Stakeholders must monitor evolving cobalt-free bonding formulations and regional carbon border adjustments that could restructure cost competitiveness between Asian and Western manufacturing bases.
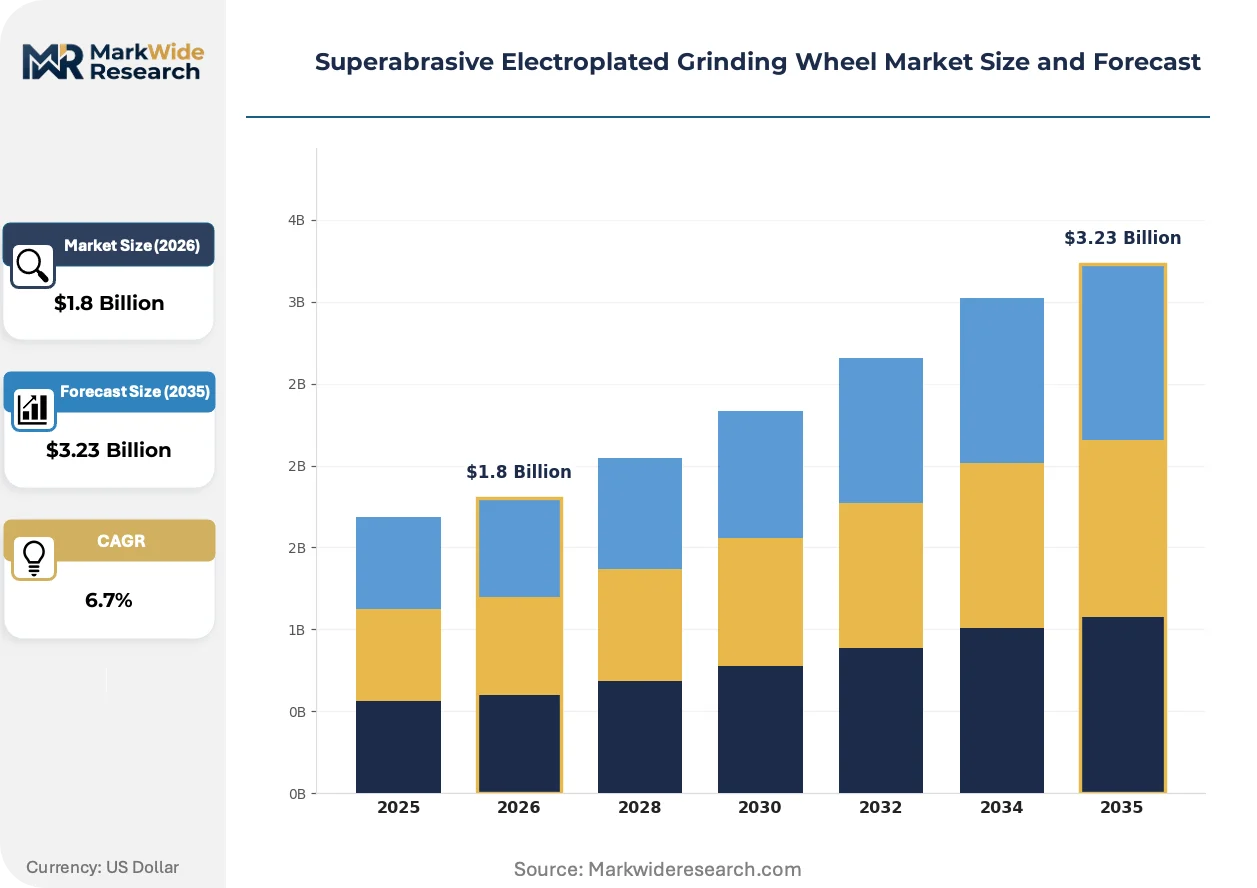
Market Dynamics
REACH restrictions on nickel electroplating chemistries are forcing wheel manufacturers to revalidate bonding matrices, while aerospace procurement teams in Germany and Japan tighten supplier qualification protocols beyond ISO 9001 certification.
Growth Catalysts
- REACH-driven chemistry transition:European hazardous substance regulations accelerate nickel-free electroplating adoption, compelling suppliers to develop compliant bonding alternatives.
- Yangtze River Delta machining clusters:China's mold and die shops demand tighter dimensional tolerances for automotive injection tooling, concentrating precision grinding wheel procurement.
- Wafer dicing geometries:Specialized wheel designs for electronics assembly applications expand addressable market in semiconductor manufacturing channels.
Market Restraints
- Nickel price volatility:Electrodeposited nickel matrix costs fluctuate with London Metal Exchange pricing, compressing margins for standard-grade wheel producers.
- Central European supply concentration:Dedicated mold and die service centers in Austria and Germany create geographic dependency risk for precision grinding tool distribution.
- Diamond chemical degradation:Diamond crystals suffer accelerated wear in ferrous alloy grinding, limiting penetration in high-volume steel precision applications.
Strategic Opportunities
- Carbon border adjustment alignment:EU Green Deal mechanisms reward low-carbon electroplating processes, creating competitive advantage for closed-loop plating recovery adopters.
- Closed-loop plating systems:Investment in wastewater recovery infrastructure enables compliance cost recovery through metal reclamation and reduced environmental liability.
- Medical device channel expansion:Orthopedic implant manufacturers require superabrasive wheels for cobalt-chrome alloy finishing, a specification-intensive segment with premium pricing tolerance.
Industry Challenges
- Multi-jurisdiction certification timelines:Simultaneous pursuit of JIS B 4130, GB standards, and REACH compliance extends product launch cycles by 8-14 months.
- Electroplating technician scarcity:Specialized nickel bath chemistry expertise concentrates among aging workforce cohorts in traditional manufacturing regions.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Superabrasive Electroplated Grinding Wheel Market Trends and Innovations
Alternative bonding matrices and precision geometry customization are displacing standardized product catalogs, while regulatory chemistry constraints reshape manufacturing economics.
Cobalt-free bonding formulations are fragmenting the supplier landscape as wheel manufacturers develop proprietary electrodeposition chemistries to circumvent REACH nickel restrictions. Medical device and aerospace buyers in Switzerland and the Netherlands pilot these alternatives for biocompatibility-critical applications. The technology is fragmenting procurement standards, as end-users establish application-specific qualification protocols rather than accepting industry-wide certifications.
OSHA permissible exposure limits for nickel compounds tighten workplace monitoring requirements in US electroplating facilities. Wheel producers must install real-time atmospheric sensing and automated ventilation controls to maintain operational licenses. Ferrous alloy grinding operations in Michigan and Ohio face the steepest compliance cost escalation, accelerating interest in CBN alternatives that reduce nickel matrix dependency.
Performance-based wheel specification contracts replace catalog-based purchasing in high-precision automotive channels. Tier-1 suppliers now demand documented grit retention rates and thermal damage thresholds rather than nominal abrasive grades. This behavioral shift concentrates procurement authority among German and Japanese OEM technical teams with direct grinding process expertise.
Superabrasive Electroplated Grinding Wheel Market Segmentation
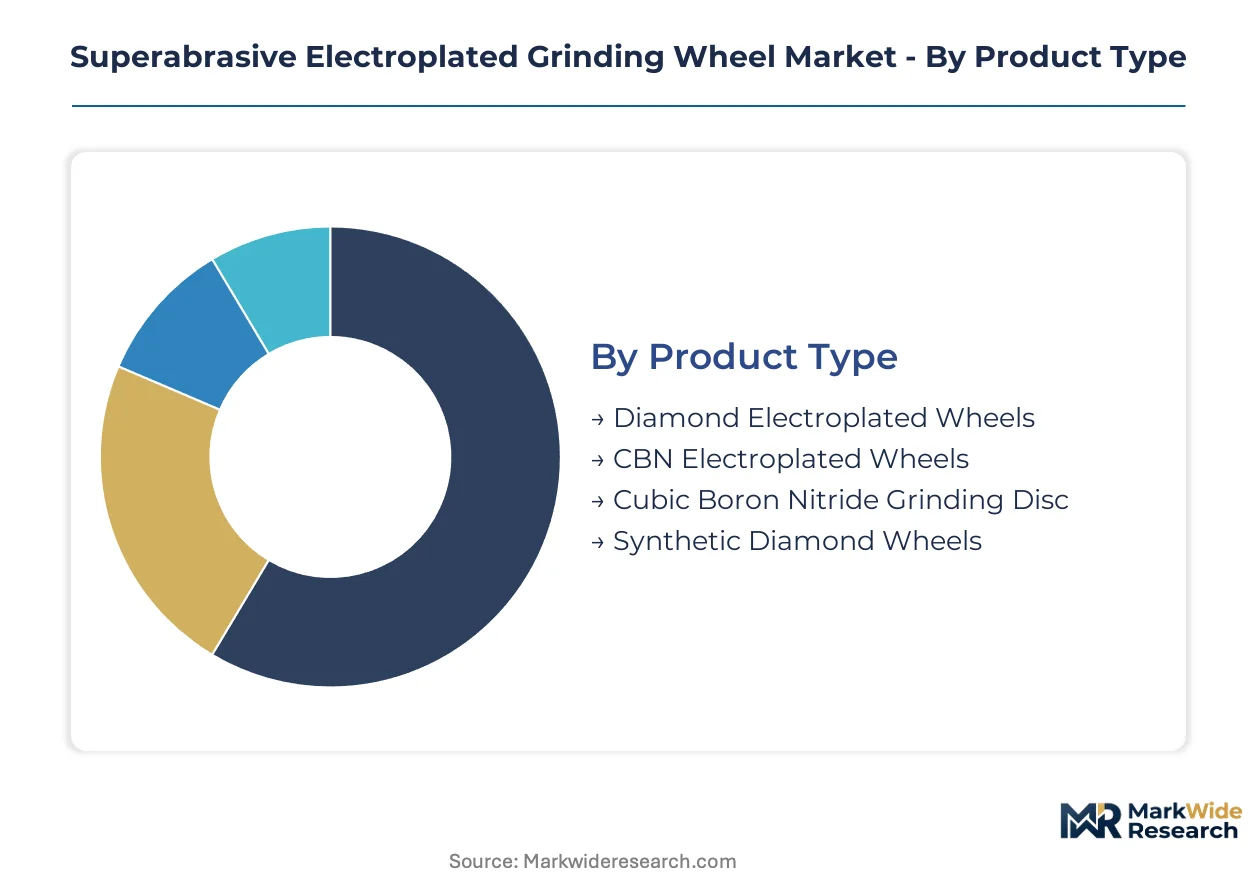
Segmentation in superabrasive electroplated grinding wheels separates commodity-grade consumables from specification-critical precision tools. Channel strategy diverges sharply: standard-grade wheels flow through industrial distributors while aerospace and medical applications require direct technical sales engagement with documented qualification protocols.
Product Type:
Diamond and CBN variants split channel economics, with diamond wheels dominating tungsten carbide grinding through distributor networks while CBN commands premium direct sales in ferrous precision applications.
- Diamond Electroplated Wheels:A single-layer diamond crystal matrix electrodeposited onto steel or aluminum cores achieves 30-50% grain protrusion for aggressive material removal. Demand concentrates in China's Yangtze River Delta mold and die clusters, where automotive injection tooling requires tight dimensional tolerances that diamond hardness delivers.
- CBN Electroplated Wheels:Cubic boron nitride crystals bonded through nickel electrodeposition resist chemical degradation in ferrous alloy grinding where diamond fails. German aerospace component manufacturers specify CBN for nickel-based superalloy turbine blade finishing, paying margin premiums for thermal damage thresholds that protect critical part integrity.
- Cubic Boron Nitride Grinding Disc:Flat-disc geometries optimized for surface grinding operations in toolroom environments.
- Synthetic Diamond Wheels:Manufactured diamond grit from high-pressure high-temperature synthesis serves cost-sensitive ceramic and glass processing channels.
By volume, Diamond Electroplated Wheels lead. By growth pace, CBN Electroplated Wheels are climbing the fastest as ferrous precision applications expand.
Application:
Application segmentation tracks manufacturing process intensity, with precision grinding and tool sharpening commanding technical sales support while glass polishing runs through volume distributors.
- Metal Cutting:High-speed slotting and grooving operations in machinery fabrication.
- Tool Sharpening:Resharpening of carbide cutting tools in job shop environments.
- Precision Grinding:Tolerance-critical finishing where form retention and thermal damage thresholds determine part acceptance. Japanese electronics assembly lines specify documented grit retention rates rather than nominal abrasive grades, concentrating procurement authority among OEM technical teams with direct grinding process expertise.
- Glass Polishing:Optical component finishing with standardized wheel geometries.
- Ceramic Finishing:Advanced ceramic component processing for aerospace and medical implants.
Precision Grinding generates the highest revenue per wheel. Metal Cutting moves the largest unit volumes through distributor channels.
Industry Vertical:
Vertical segmentation exposes qualification protocol divergence: aerospace and medical channels enforce REACH-compliant bonding matrices while mold and die shops prioritize unit economics.
- Aerospace Component Manufacturing:Nickel-based superalloy and titanium grinding with biocompatibility-critical specifications. Swiss and Dutch buyers pilot cobalt-free bonding formulations, establishing application-specific qualification protocols rather than accepting industry-wide certifications.
- Mold & Die:Automotive injection tooling production in China's machining clusters demands tight tolerances.
- Machinery Fabrication:General industrial grinding with standardized product requirements.
- Electronics Assembly:Wafer dicing and semiconductor processing with specialized wheel geometries. Asahi Diamond Industrial dominates this channel with proprietary designs for silicon substrate singulation.
- Jewelry Production:Precision finishing of precious metals and gemstones.
Aerospace Component Manufacturing commands the steepest pricing premiums. Electronics Assembly is gaining share fastest as semiconductor capacity expands.
Bonding Technology:
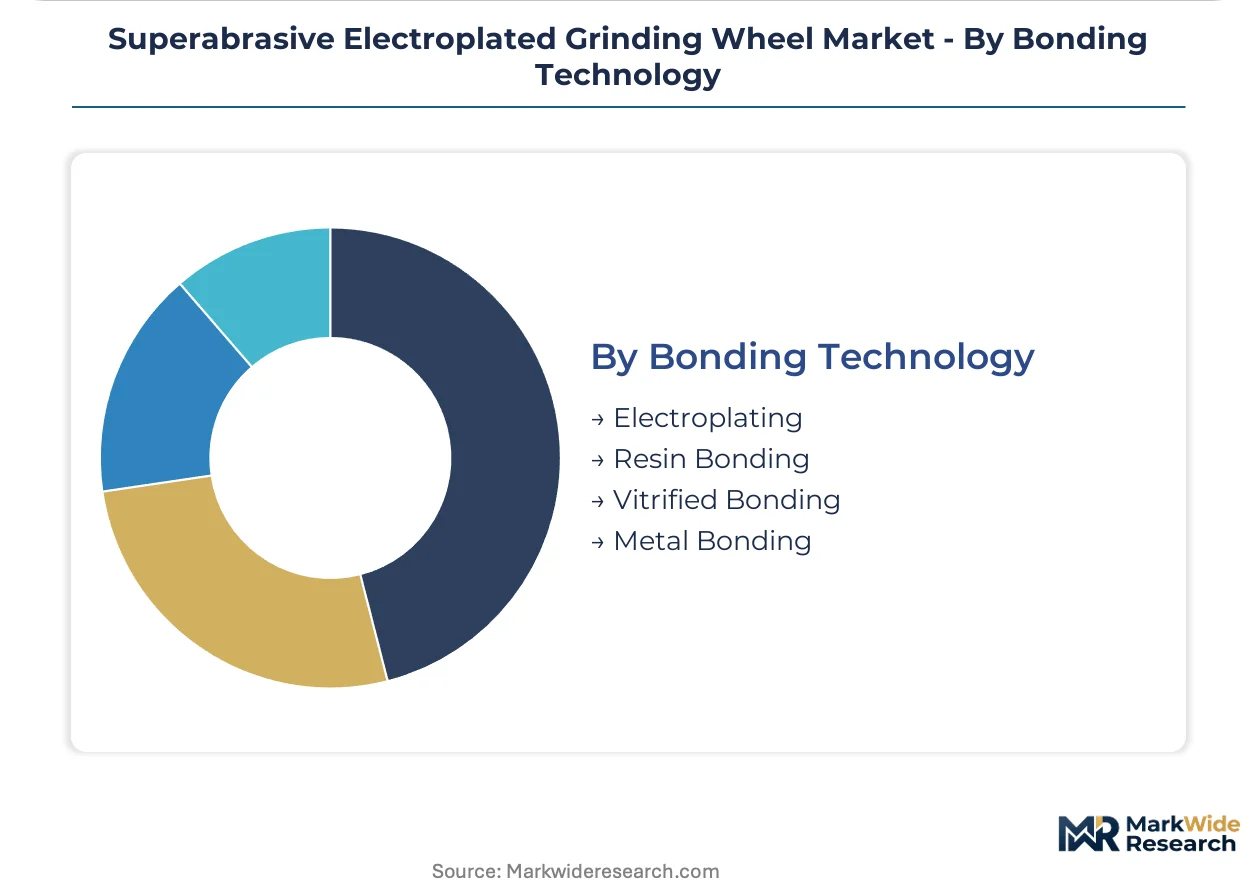
Technology segmentation separates electroplated single-layer products from multi-layer alternatives, with bonding choice determining truing requirements and form retention characteristics.
- Electroplating:Single-layer diamond or CBN crystals in electrodeposited nickel matrix deliver superior form retention without truing between dressing cycles. REACH restrictions on nickel chemistries force manufacturers to validate alternative bonding matrices or invest in closed-loop plating recovery systems, restructuring cost competitiveness between Asian and Western manufacturing bases.
- Resin Bonding:Polymer matrix systems offering self-sharpening characteristics for general-purpose grinding.
- Vitrified Bonding:Ceramic bond systems for high-temperature stability in creep-feed applications.
- Metal Bonding:Bronze or cobalt matrices for extended wheel life in heavy-stock removal.
Electroplating leads in precision applications. Metal Bonding holds the largest installed base in heavy manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal carbon border adjustments reward low-carbon electroplating processes, reshaping cost competitiveness between Asian and Western manufacturing bases. REACH nickel restrictions and OSHA exposure limits create divergent compliance cost structures across major production centers.
Germany
Aerospace turbine blade finishing drives CBN wheel demand from nickel-based superalloy grinders. KBA vehicle component regulations indirectly shape precision tool specifications for automotive suppliers. Baden-Württemberg's Stuttgart industrial corridor hosts dedicated mold and die service centers requiring ISO 9001-plus qualification protocols.
China
Yangtze River Delta machining clusters concentrate procurement for automotive injection tooling with tight dimensional tolerances. GB standards for abrasive product safety create compliance layers for cross-border suppliers. Shanghai and Suzhou mold shops drive volume demand for diamond electroplated wheels in tungsten carbide processing.
Japan
Electronics assembly lines specify documented grit retention rates for wafer dicing applications. METI industrial policy supports precision manufacturing tool development through targeted incentives. Chubu region Nagoya-based aerospace component manufacturers tighten supplier qualification beyond baseline certifications.
United States
OSHA permissible exposure limits for nickel compounds tighten workplace monitoring in Michigan and Ohio electroplating facilities. Ferrous alloy grinding operations face compliance cost escalation accelerating CBN alternative interest. Midwest machinery fabrication clusters distribute standard-grade wheels through industrial distributor networks.
Switzerland
Orthopedic implant manufacturers require superabrasive wheels for cobalt-chrome alloy finishing with biocompatibility-critical specifications. Swissmedic medical device regulations pilot cobalt-free bonding formulations for qualification protocols. Basel pharmaceutical tooling shops demand premium thermal damage thresholds.
Superabrasive Electroplated Grinding Wheel Market Competitive Landscape
Player mix skews toward vertically integrated material producers and specialized precision grinding tool fabricators. Consolidation concentrates among European and Asian manufacturers with captive synthetic diamond or CBN supply. Three archetypes dominate: integrated abrasive material producers, dedicated electroplated wheel specialists, and diversified industrial tool conglomerates. Strategic moves center on closed-loop plating recovery infrastructure investment and cobalt-free bonding formulation development.
Among diversified industrial conglomerates, 3M and Saint-Gobain Abrasives exemplify scale-driven positioning through backward integration into synthetic abrasive production. Tyrolit Group anchors Central European supply architecture through Austrian-based mold and die service center networks. Asahi Diamond Industrial occupies a specialist position in Asian electronics assembly channels with proprietary wafer dicing geometries.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain Abrasives |
| Tyrolit Group |
| Norton Abrasives |
| Asahi Diamond Industrial |
| Noritake |
| Engis Corporation |
| Abrasive Technology |
| Continental Diamond Tool Corporation |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Central European electroplating facilities shapes both supply concentration and price floors for precision-grade wheels, as REACH-compliant bonding chemistry investments create fixed-cost barriers that commodity producers cannot cross. Yangtze River Delta mold shops and German aerospace turbine finishers occupy opposite ends of this bifurcated structure, with certification intensity determining margin capture rather than volume scale.
Pricing Analysis
Certification level creates the primary spread between aerospace-grade CBN wheels and standard diamond products for mold and die applications. Three-tier pricing structure separates REACH-compliant cobalt-free formulations from nickel-matrix legacy products and economy-grade distributor catalog items. Cost compression in standard-grade channels intensifies as Chinese producers expand Yangtze River Delta capacity, while orthopedic implant manufacturers in Switzerland exhibit minimal price sensitivity for biocompatibility-critical specifications.
Supply Chain Analysis
Strait of Malacca transit routes anchor synthetic diamond grit flows from Chinese HPHT synthesis facilities to European electroplating plants. The supply chain draws from concentrated nickel refining in Indonesia and Russia, electrodeposited matrix chemicals from German specialty chemical producers, and precision-machined steel cores from Japanese forging operations. Single-source vulnerability concentrates in nickel sulfate supply for plating baths. Distribution runs through dedicated mold and die service centers in Austria and Germany for precision applications, with volume-grade wheels flowing through industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized nickel bath chemistry expertise concentrates among aging workforce cohorts in Baden-Württemberg and Nagoya, creating capability scarcity that will intensify as REACH-driven formulation transitions demand fresh technical training pipelines.
For Market Incumbents: Shield proprietary cobalt-free bonding formulations through patent thickets in European jurisdictions, while embedding electroplating technicians within customer technical service teams to lock in switching costs. Nickel price volatility threatens margin stability for standard-grade producers lacking closed-loop recovery infrastructure. For New Entrants and Emerging Players: Lead with medical device channel qualification in Switzerland and the Netherlands, where biocompatibility-critical specifications command premium pricing tolerance and procurement authority concentrates among technical teams with limited vendor lists. Target wafer dicing geometries for Asian electronics assembly expansion, offering documented grit retention rates rather than nominal abrasive grades to differentiate from catalog competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electroplated wheel specialists with captive synthetic abrasive supply and embedded service contracts in aerospace component manufacturing. Long-term viability hinges on carbon border adjustment alignment and closed-loop plating recovery adoption. The acquisition target archetype combines proprietary bonding chemistry with established JIS B 4130 and REACH qualification protocols. Monitor EU Green Deal implementation pace as the inflection signal for cost competitiveness restructuring between Asian and Western manufacturing bases.| Strategic Initiative | Industry Significance |
|---|---|
| Cobalt-Free Bonding Formulation Development | REACH compliance enables continued European market access for aerospace and medical channels. |
| Closed-Loop Plating Recovery Infrastructure | EU Green Deal carbon border adjustments reward low-carbon electroplating process adopters. |
| Medical Device Channel Qualification | Swissmedic regulations in Switzerland pilot biocompatibility-critical specification protocols. |
| Wafer Dicing Geometry Specialization | Japanese electronics assembly lines demand documented grit retention rates for silicon substrate singulation. |
| Electroplating Technician Apprenticeship Programs | OSHA exposure limits tighten as aging workforce expertise concentrates in Michigan and Ohio facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from diversified industrial conglomerates, and JIS B 4130 specification databases. Conversations with electroplating plant managers, aerospace component procurement leads, mold and die shop owners in the Yangtze River Delta, orthopedic implant manufacturing engineers, and industrial distributor category buyers informed demand-side validation. Bottom-up wheel shipment estimates triangulate against top-down abrasive materials consumption data from regional manufacturing surveys.
Segmentation dimensions modeled include abrasive type, bonding technology, application intensity, and industry vertical qualification protocol tier across the projection horizon. CAGRs derive from growth rate convergence analysis applied to historical shipment patterns and forward capacity expansion announcements. Forecast inputs incorporate REACH compliance timeline assumptions and semiconductor capital equipment spending trajectories for wafer dicing demand.
Underlying assumptions cover nickel price stabilization, REACH enforcement consistency, and carbon border adjustment implementation pace, with deviation risk concentrated in electroplating chemistry substitution timelines and Chinese GB standards harmonization. Practitioners should keep alternative scenarios live as EU Green Deal mechanism details and OSHA permissible exposure limit revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.