
 Non-Woven Abrasives Market | 2026-2036
Non-Woven Abrasives Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Woven Abrasives Market Intelligence
The adoption of vendor-managed inventory models by large industrial consumers is reshaping competitive positioning among suppliers. This shift favors large-scale manufacturers with sophisticated logistics and forecasting capabilities. Global giant 3M leverages its vast distribution network to service these contracts effectively. In contrast, Saint-Gobain differentiates through its portfolio of specialized materials for high-performance applications, while PFERD specializes in precision tools for the metalworking industry.
Non-woven abrasives are engineered materials comprising a web of synthetic fibers, like nylon, bonded with resins and impregnated with abrasive grains. Their primary purpose is surface conditioning, including finishing and deburring, without altering the geometry of the workpiece. Within applications, metal finishing remains the largest segment due to its widespread use in heavy industry and general manufacturing. The aerospace end-user segment commands premium pricing for applications requiring high-precision surface preparation on advanced alloys and composites.
Product formulation and use are governed by a complex web of international regulations. The European Union's REACH framework controls the chemical constituents of binders and resins, while in the United States, OSHA standards dictate permissible worker exposure to abrasive dust. Future material development will center on creating biodegradable fiber and resin systems that meet stringent performance criteria for automated industrial processes.
Market Dynamics
The market's evolution is primarily driven by the integration of automated finishing systems in manufacturing. This trend demands non-woven abrasives with exceptional consistency and predictable performance to meet the rigorous requirements of robotic applications in high-volume industries.
Growth Catalysts
- Robotic Finishing Adoption:The automotive sector's expanding use of robotic cells for surface preparation and finishing requires abrasives with uniform wear rates and consistent cut, directly stimulating demand for high-performance non-woven products.
- Aerospace Material Advancement:Demand for precision finishing on advanced alloys and composites in aerospace manufacturing creates a significant catalyst, as these applications require specialized abrasives and support premium pricing structures.
- China's Industrial Scale:The sheer volume of metalworking and general manufacturing within China's industrial economy provides a foundational demand base, particularly for deburring and finishing applications in fabricated metal production.
Market Restraints
- Raw Material Volatility:Price fluctuations in key inputs, including nylon fibers, synthetic resins, and abrasive grains like aluminum oxide, create margin pressure and complicate long-term cost planning for manufacturers.
- Regulatory Compliance Burden:Adherence to chemical safety regulations, such as the European Union's REACH framework, imposes significant R&D and administrative costs for the development and qualification of binder and resin systems.
- Substitution from Alternative Processes:In specific niche applications, alternative technologies like laser deburring and electrochemical polishing present a substitution threat, potentially capping market penetration for certain finishing tasks.
Strategic Opportunities
- Biodegradable Materials:Developing biodegradable fiber and resin systems that meet industrial performance standards presents a major opportunity, aligning with corporate sustainability goals and circular economy initiatives across end-user markets.
- Medical Device Finishing:The growing medical device industry offers a high-value application for finishing orthopedic implants and surgical instruments, where precision, surface integrity, and material compatibility are critical requirements.
- Southeast Asian Manufacturing Growth:Expanding into the burgeoning manufacturing hubs of Southeast Asian nations provides an opportunity to capture new demand as industrial production diversifies geographically beyond established centers.
Industry Challenges
- Navigating Global Standards:Manufacturers face the operational challenge of designing and marketing products that comply with a patchwork of international worker safety standards, such as OSHA dust exposure limits in the US.
- Automation Skill Gaps:A shortage of technicians skilled in programming and maintaining the automated robotic systems that utilize non-woven abrasives can slow the adoption rate of these advanced finishing technologies.
- Performance Standardization Deficit:The absence of universally accepted standards for grading abrasive performance leads to customer uncertainty and makes direct product comparisons between competing suppliers difficult.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Woven Abrasives Market |
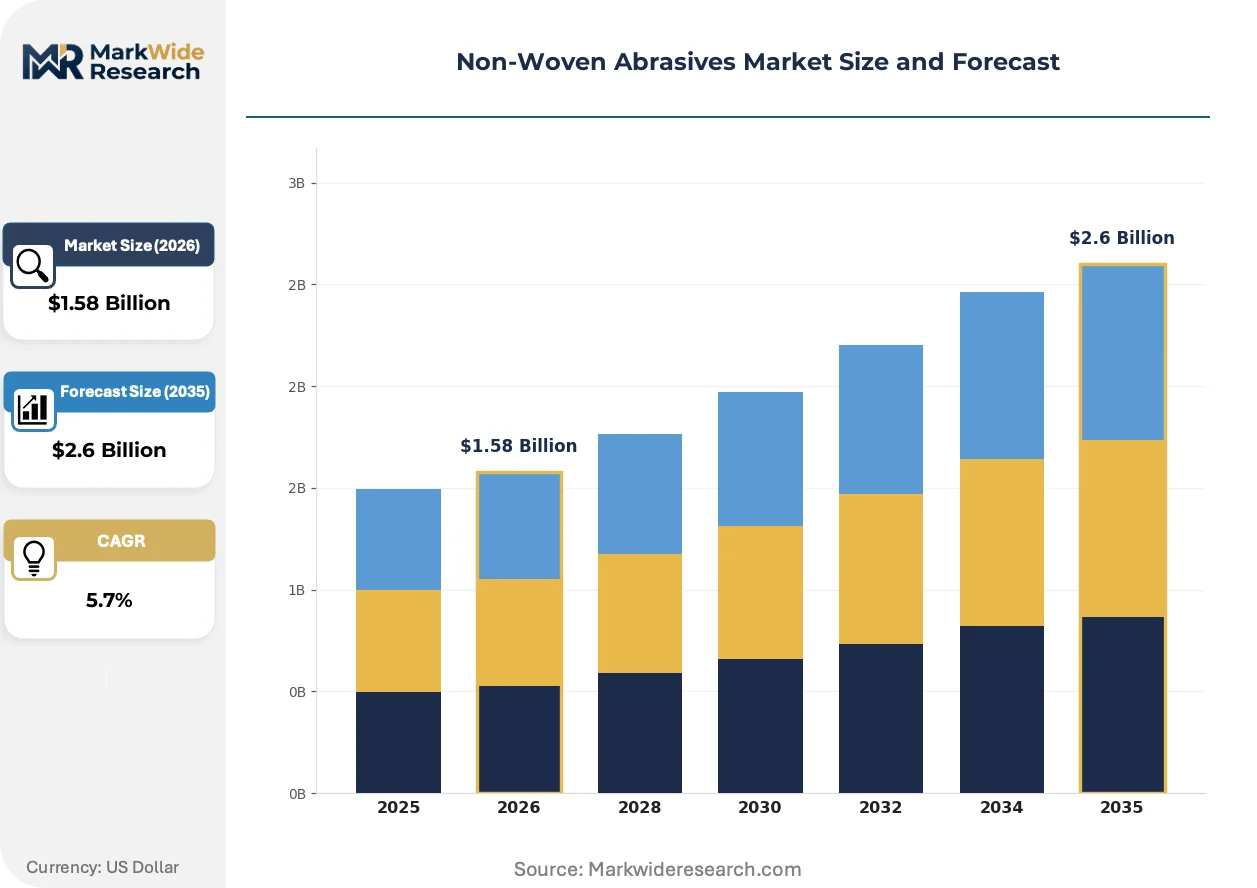
| Market Size in 2026 | $1.58 Billion |
| Market Size in 2035 | $2.6 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheets, Rolls, Discs, Wheels Application: Metal Finishing, Woodworking, Surface Preparation, Cleaning End User: Manufacturing, Automotive, Construction, Aerospace Form: Loose, Rolled, Flat, Custom |
| Companies Covered | 3M, Saint-Gobain, DEWALT, Carborundum Universal Limited (CUMI), Sia Abrasives, PFERD, Mirka Ltd., TGA Abrasives, Osborn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Woven Abrasives Market Strategic Shifts & Innovations
Innovation in the non-woven abrasives market is being steered by the convergence of material science and digital manufacturing. Sustainability mandates and the need for greater process control in automated environments are forcing fundamental changes in product design and application.
Smart abrasives incorporating embedded sensors or RFID tags represent a significant technological evolution. Aerospace and automotive manufacturers are the primary adopters, using this technology to gain precise control over their automated finishing processes. This development is digitizing the entire consumable lifecycle, enabling predictive maintenance schedules and real-time process optimization within smart factories.
Heightened regulatory focus on worker health, exemplified by OSHA standards for permissible dust exposure, is a powerful innovation driver. This pressure compels manufacturers to engineer products with advanced binder technologies that minimize airborne particulates during operation. The metalworking sector is most impacted, creating strong demand for cleaner, safer abrasive solutions for manual and automated tasks.
A distinct behavioral shift is occurring as large end-users transition from simple transactional purchasing to more integrated supply models. This trend favors suppliers capable of managing vendor-managed inventory programs, displacing traditional distribution channels that lack sophisticated logistical capabilities. This pattern is especially visible within the North American heavy equipment manufacturing sector, where minimizing production downtime is paramount.
Non-Woven Abrasives Market Segmentation
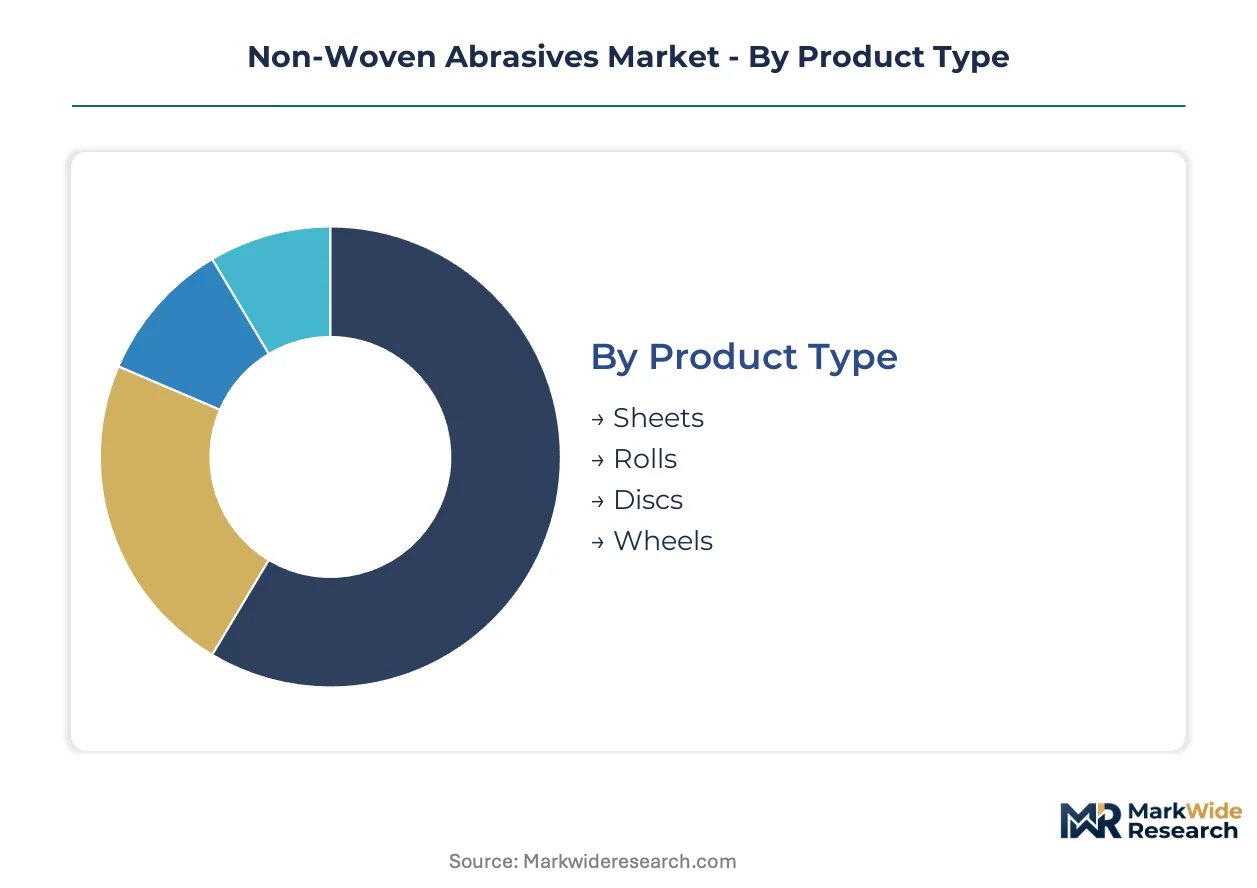
Understanding the non-woven abrasives market through segmentation clarifies how different product attributes, applications, and end-user demands shape competitive dynamics. This granular analysis reveals where innovation is most impactful and where specific market needs are underserved by current offerings.
Product Type:
The intensity of after-sales service and technical support often correlates with the complexity and precision required for specific product forms, influencing supplier relationships and market entry barriers.
- Discs:These circular abrasives are widely used in automated and manual finishing processes, particularly for deburring, blending, and polishing metal surfaces in the automotive and general manufacturing sectors. Their consistent performance is essential for robotic applications in Germany's advanced industrial base.
- Rolls:Continuous abrasive rolls are integral to high-volume, automated production lines for consistent material removal and surface finishing across large workpieces in heavy equipment manufacturing. Demand for these products is concentrating in China's expansive metalworking industry.
- Sheets:Non-woven abrasive sheets offer versatility for manual finishing tasks and light deburring, finding broad use in smaller workshops and repair operations.
- Wheels:Abrasive wheels are designed for aggressive material removal and heavy-duty grinding applications, common in foundries and fabrication plants.
Rolls holds the largest share; momentum sits with Discs.
Application:
The specific application dictates the required abrasive properties, influencing material composition, grain size, and binder systems to achieve desired surface finishes and material removal rates.
- Metal Finishing:This segment represents the largest application for non-woven abrasives, encompassing deburring, blending, and polishing of various metals in industries from automotive to heavy machinery. Precise surface conditioning is critical for component performance.
- Surface Preparation:Non-woven abrasives are vital for preparing surfaces before coating, painting, or bonding, ensuring optimal adhesion and longevity across diverse materials including plastics and composites. The aerospace industry in the United States utilizes these extensively for advanced materials.
- Woodworking:In woodworking, these abrasives are used for sanding, denibbing, and achieving smooth finishes on timber and wood-based panels in furniture manufacturing.
- Cleaning:Lighter-duty non-woven abrasives are employed for general cleaning, rust removal, and conditioning tasks where minimal material removal is desired.
Demand is strongest in Metal Finishing, with Surface Preparation showing significant expansion.
End User:
Customer type segmentation highlights distinct procurement patterns, technical requirements, and regulatory compliance needs across various industrial sectors utilizing non-woven abrasive products.
- Automotive:The automotive sector relies heavily on non-woven abrasives for surface conditioning of vehicle components, bodywork preparation, and robotic deburring operations, particularly in high-volume production facilities in Japan. This industry prioritizes consistent performance and high throughput.
- Aerospace:Aerospace manufacturing demands specialized non-woven abrasives for precise finishing of advanced alloys and composite materials, crucial for structural integrity and aerodynamic performance. These applications command premium pricing for specialized products.
- Manufacturing:This broad category includes general industrial manufacturing, covering a wide array of applications from tool and die finishing to general metal fabrication.
- Construction:Non-woven abrasives find use in construction for tasks such as surface preparation of structural components and finishing architectural elements.
The Manufacturing sector drives substantial volume, while Aerospace commands premium pricing.
Form:
Supply concentration for different abrasive forms reflects the scale of production, specialized manufacturing processes, and the distribution channels required to serve diverse end-user needs efficiently.
- Rolled:Rolled non-woven abrasives cater to automated and continuous finishing processes, providing consistent material for high-volume industrial applications such as coil finishing. These forms are commonly used in large-scale metalworking operations.
- Custom:Custom-formed abrasives are engineered for highly specialized applications requiring unique shapes, sizes, or performance characteristics, often for niche industries like medical device manufacturing in Switzerland. These bespoke solutions offer tailored precision.
- Loose:Loose non-woven abrasive materials are flexible and adaptable for manual applications or as components within other abrasive systems, offering versatility.
- Flat:Flat non-woven abrasives encompass sheets and pads, suitable for general-purpose surface conditioning and manual finishing across various materials.
Rolled forms are foundational, with specialized Custom solutions gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Global trade in non-woven abrasives exhibits a nuanced balance, with significant production centers driving exports while key industrial nations represent substantial import markets. This dynamic shapes regional supply chains and influences pricing strategies across diverse manufacturing sectors. Localized demand for specialized finishing solutions also creates distinct market concentrations.
China
China's expansive industrial base drives immense demand for non-woven abrasives, particularly in metalworking and general manufacturing applications. The country's dual carbon goals influence material development towards more sustainable abrasive formulations. Industrial clusters in the Yangtze River Delta and Pearl River Delta utilize these products for high-volume deburring and surface preparation in fabricated metal production.
Germany
The German automotive and advanced manufacturing sectors require high-performance non-woven abrasives for robotic finishing and precision surface preparation. European Union's REACH framework heavily regulates chemical constituents in binders and resins, impacting product innovation. Bavaria and Baden-Württemberg's industrial regions are centers for automated finishing systems demanding consistent abrasive performance.
United States
Aerospace manufacturing and heavy equipment production in the United States generate significant demand for specialized non-woven abrasives for advanced alloys and composites. OSHA standards dictate permissible worker exposure to abrasive dust, influencing product design for cleaner operations. The Pacific Northwest and Midwest regions, with their strong aerospace and automotive presence, emphasize high-precision surface conditioning.
Japan
Japan's automotive industry relies on non-woven abrasives for consistent surface conditioning and robotic deburring in high-volume production facilities. The Ministry of Economy, Trade and Industry (METI) supports advanced manufacturing initiatives that integrate automated finishing technologies. Kanto and Chubu regions, home to major automotive manufacturers, prioritize uniform wear rates and predictable abrasive performance.
Non-Woven Abrasives Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying essential materials for finishing processes. The non-woven abrasives market exhibits a tiered structure, with a few global conglomerates alongside numerous specialized manufacturers. Strategic archetypes include diversified industrial giants, specialized material providers, and precision tool manufacturers catering to specific end-user needs. Portfolio diversification through material science advancements and strategic partnerships for automated system integration are dominant competitive moves among market participants.
Within the diversified industrial giants, 3M exemplifies extensive distribution networks and broad product portfolios across multiple industrial segments. Saint-Gobain occupies a position as a specialized material provider, leveraging its expertise in advanced ceramics and composites for high-performance applications. PFERD anchors the precision tool manufacturing archetype, specializing in solutions for the metalworking industry where application-specific products are critical. These companies represent distinct approaches to serving the varied demands of the non-woven abrasives market.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| DEWALT |
| Carborundum Universal Limited (CUMI) |
| Sia Abrasives |
| PFERD |
| Mirka Ltd. |
| TGA Abrasives |
| Osborn |
| Others |
Cost & Logistics Intelligence
Raw material volatility in key inputs like synthetic resins and abrasive grains directly determines pricing tier spreads and shapes the non-woven abrasives supply chain. These cost fluctuations compel manufacturers to optimize sourcing strategies and manage inventory carefully across product lines.
Pricing Analysis
Industrial OEM buyers anchor a tiered pricing structure that differentiates based on performance consistency and specialized application support. Pricing stratifies across premium, standard, and economy tiers, reflecting product formulation complexity and after-sales technical service. Pricing softness stems from intense competition and the availability of alternative finishing processes for certain applications. Aerospace and medical device manufacturers exhibit the least price sensitivity due to critical performance requirements, while general manufacturing consumers are highly sensitive.
Supply Chain Analysis
Export control regimes on advanced chemical precursors for specialized resins could limit flows, impacting the non-woven abrasives supply chain. Supply concentrations for critical inputs like aluminum oxide and synthetic resins are observed in China and parts of Europe. Single-source vulnerability for specialized binder systems presents a structural risk for manufacturers. Distribution runs through a dual model, with direct contracts for large industrial consumers and specialized distributors serving smaller workshops and regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a high-growth disruption opportunity, driven by the integration of smart abrasives into automated finishing systems. This technological inflection point demands new material science and process control solutions from suppliers.
For Market Incumbents: Insulate core market share by deepening vendor-managed inventory relationships with large automotive and aerospace OEMs. Invest significantly in R&D for biodegradable fiber and resin systems to counter the threat of environmental regulations and alternative material solutions. Pursue strategic partnerships with robotic automation providers to integrate abrasive performance data directly into smart factory ecosystems. Enhance product consistency and standardization to meet the rigorous demands of automated finishing systems.
For New Entrants and Emerging Players: Build out specialized product lines targeting the high-value medical device finishing segment, emphasizing precision and material compatibility. Focus on expanding into burgeoning Southeast Asian manufacturing hubs, where industrial growth is creating foundational demand for general-purpose abrasives. Differentiate through sustainable product formulations, such as biodegradable fiber systems, to capture early adopter demand. Offer bundled solutions that combine abrasives with technical support for automated finishing processes.
For Investors and Strategic Acquirers: The EU's REACH framework reshapes the acquisition landscape, favoring companies with compliant and sustainable material portfolios. Long-term viability for this market hinges on continuous innovation in automated process compatibility and environmental performance over the next decade. Target specialized material science firms with patented biodegradable resin technologies or companies offering integrated sensor solutions for smart abrasives. The signal to watch is the accelerated investment by major automotive and aerospace OEMs in fully automated finishing lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Expanding manufacturing capacity in Southeast Asian nations captures new demand from diversifying industrial production bases. |
| R&D in Biodegradable Materials | Developing biodegradable fiber and resin systems aligns with corporate sustainability goals and future EU regulatory mandates. |
| Strategic Partnership with Automation Providers | Collaborating with robotic system integrators optimizes abrasive performance for high-volume automotive and aerospace applications. |
| Certification Investment for Smart Abrasives | Obtaining specific certifications for smart abrasives validates their consistent performance in automated industrial processes. |
| Backward Integration into Resin Production | Controlling specialized resin supply mitigates raw material volatility and enhances product customization capabilities for manufacturers. |
Research Approach
Desk research of industry association reports, patent databases, and trade publications preceded structured interviews with procurement leads at automotive OEMs, R&D directors in abrasives manufacturing, and plant managers. This primary and secondary data combination enabled a comprehensive market understanding. A bottom-up approach estimated market size from granular data, while a top-down approach validated these figures.
The forecast framework assumed stable geopolitical conditions and consistent technological advancement across the analysis window. Segmentation dimensions modeled included product type, application, end-user, and form, capturing granular market dynamics. Compound Annual Growth Rates were derived from historical trends and projected growth drivers like robotic finishing adoption. This approach provided a detailed outlook for the non-woven abrasives market.
Practitioners should monitor raw material price spikes and significant regulatory shifts, such as EU's REACH framework updates, for early signals. Forecasts reflect current assumptions about technological adoption and industrial growth. Material shifts in automated finishing system integration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Abrasives
Global Abrasives Market
Abrasives
Abrasive Blasting Nozzle Market
Abrasives
Europe Abrasives Market
Abrasives
Surface Conditioning Wheels Market
Abrasives
Coated Abrasives Market
Abrasives
Tungsten Carbide Band Saw Blade Market
Abrasives
Lapping and Polishing Films Market
Abrasives
Anthracite Fines Market
Abrasives
North America Abrasives Market
Abrasives
Abrasive Rolls Market
Abrasives
Metal Abrasives Market
Abrasives
Rare Earth Polishing Materials Market
Abrasives
Super Abrasives Market
Abrasives
Fine Sandpaper Market
Abrasives
Polishing Chemicals Market
Abrasives
Carbide Grinding Wheel Market