
 Global Rock Climbing Equipment Market | 2026-2036
Global Rock Climbing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rock Climbing Equipment Market Outlook
Advanced polymer weaving and 3D-molded structural components is reconfiguring how climbing harnesses distribute load and reduce weight across performance tiers. Black Diamond Equipment leverages its vertically integrated Utah manufacturing base to control quality from fiber extrusion to finished goods. Petzl anchors its competitive position through intensive R&D on energy-absorbing lanyard systems for via ferrata and alpine applications. Arc'teryx differentiates via laminated construction techniques originally developed for its technical outerwear division.
Rock climbing equipment encompasses specialized personal protective apparatus designed to arrest falls, secure belay systems, and facilitate vertical movement on natural and artificial surfaces; load-bearing components typically utilize kernmantle rope construction with nylon or polyester sheaths rated to UIAA fall-test standards exceeding twelve kilonewtons. The primary commercial purpose centers on reducing injury risk while enabling controlled exposure to gravity-dependent recreation and professional access work. Climbing harnesses and ropes capture the largest revenue share due to mandatory replacement cycles and liability-driven purchasing behavior among commercial operators. Carabiners and quickdraws represent the fastest-growing product category as sport climbing participation expands and climbers build personal rack collections. Aluminum and steel hardware segments command premium margins where hot-forged construction and anodized finishes signal performance differentiation.
The EU's Personal Protective Equipment Regulation and CE marking requirements enforce third-party testing for all climbing gear sold within member states, creating compliance barriers for uncertified Asian imports. The United States operates under OSHA fall-protection standards for workplace applications and voluntary UIAA safety protocols for recreational equipment, producing a dual-track regulatory environment. Japan's Consumer Product Safety Law mandates S-mark certification for climbing hardware, adding a distinct approval layer for brands targeting that market. Stakeholders must monitor how divergent national testing protocols affect component standardization and inventory segmentation across regional distribution networks.
Market Dynamics
Indoor climbing gym expansion in Germany and the United States is reconfiguring procurement patterns, with facility operators negotiating volume contracts that bypass traditional retail channels and compress distributor margins. This facility-led demand concentration is forcing manufacturers to restructure sales organizations around direct institutional accounts.
Growth Catalysts
- Sport climbing's Olympic inclusion:Youth program enrollment in the United States has surged, creating sustained replacement demand for entry-level harnesses and shoes as participants advance through skill tiers.
- EU CE marking mandate:The Personal Protective Equipment Regulation is filtering uncertified Asian imports from European distribution, protecting compliant manufacturers' price positioning.
- Advanced polymer weaving:Kernmantle rope construction with high-tenacity nylon sheaths is extending product lifecycles while reducing weight-to-strength ratios for alpine applications.
Market Restraints
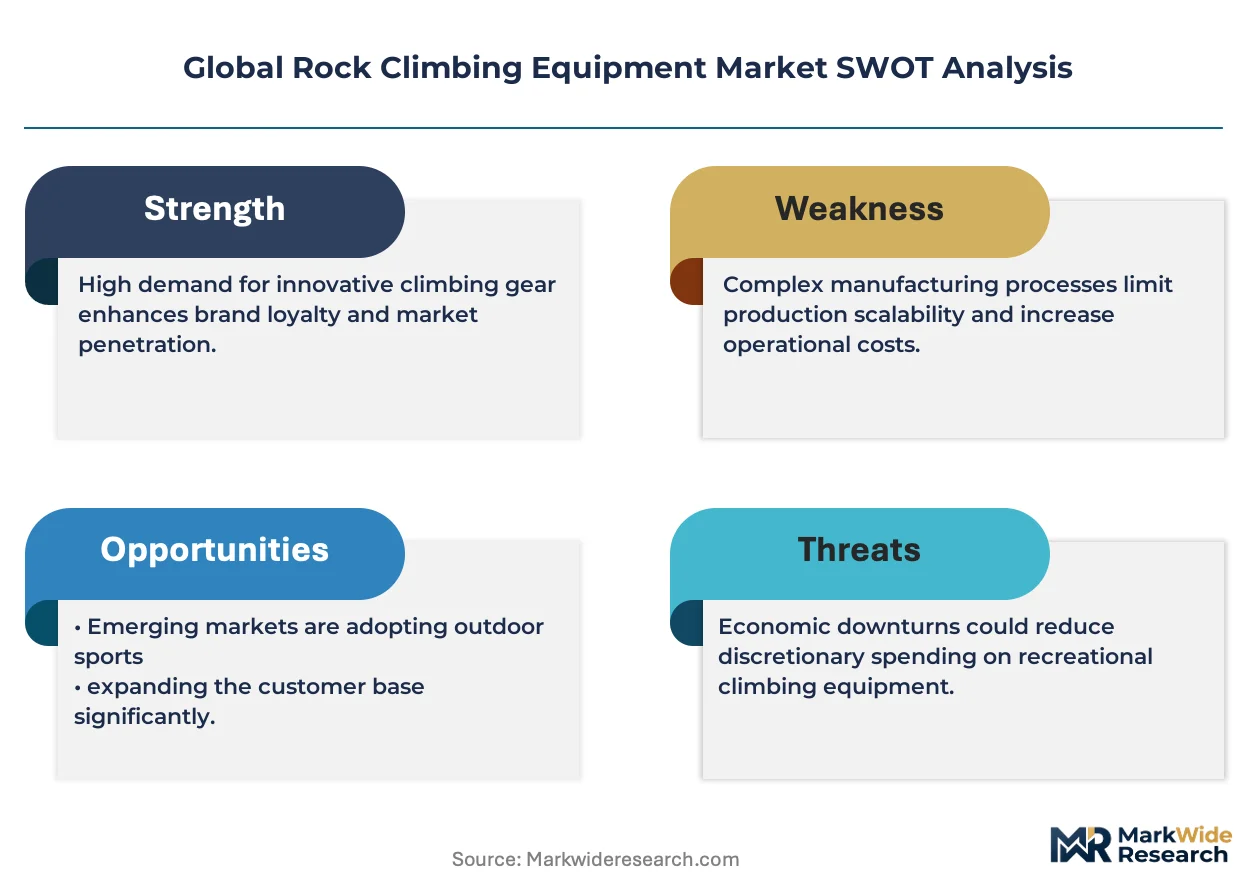
- Petrochemical input volatility:Nylon and polyester fiber costs fluctuate with crude oil derivatives, squeezing margin predictability for rope and webbing producers.
- Chinese hardware oversupply:Unbranded aluminum carabiner manufacturing in Zhejiang province is flooding discount channels, eroding price discipline in entry-tier segments.
- UIAA fall-test limitations:Current twelve-kilonewton certification thresholds do not address dynamic loading scenarios in highball bouldering, creating liability exposure.
Strategic Opportunities
- Indian metropolitan expansion:Mumbai and Bangalore climbing gym openings are creating first-mover advantage for brands establishing local distribution before market maturation.
- Work-at-height regulatory convergence:OSHA fall-protection standards for industrial rope access are creating crossover demand for recreational-derived harness systems.
- Biomechanical sensor integration:Wearable force-measurement devices combined with mobile applications are enabling data-driven training programs and equipment replacement alerts.
Industry Challenges
- Certification timeline compression:CE marking and Japan's S-mark approval processes require twelve-to-eighteen-month lead times, delaying product launches behind design completion.
- Specialized textile engineering scarcity:Kernmantle braiding technicians and UIAA-accredited test engineers command premium compensation, constraining production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rock Climbing Equipment Market |
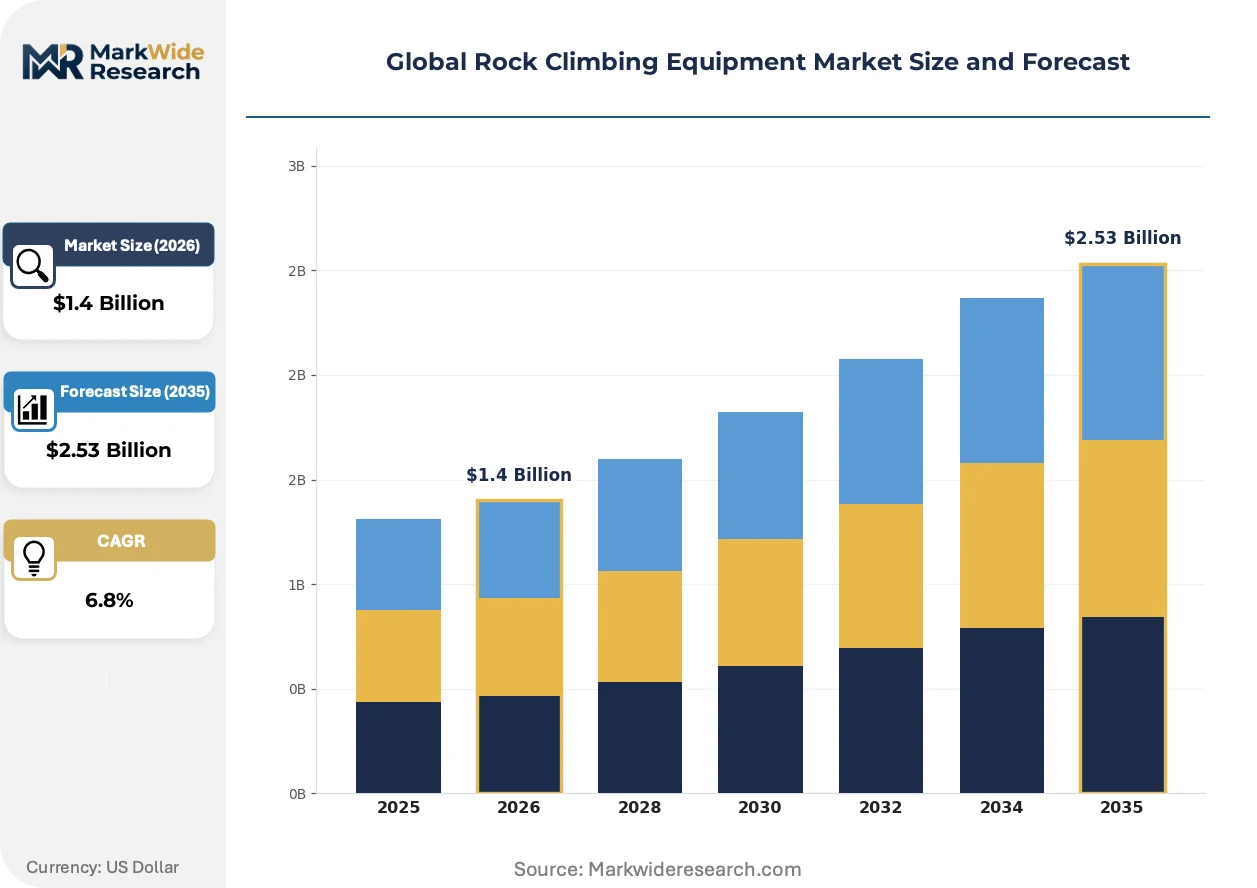
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Climbing Harnesses, Carabiners, Ropes, Chalk Bags End User: Outdoor Enthusiasts, Professional Climbers, Recreational Users, Training Facilities Distribution Channel: Online Retailers, Specialty Stores, Outdoor Gear Shops, Sporting Goods Chains Material: Nylon, Polyester, Aluminum, Steel |
| Companies Covered | La Sportiva, Arc'teryx, Black Diamond Equipment, Edelrid, CAMP USA, Petzl, Scarpa, Metolius Climbing, Mammut Sports Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rock Climbing Equipment Market Strategic Shifts
Material science advances and regulatory harmonization pressures are converging to redefine performance benchmarks across harness, rope, and hardware categories. Manufacturers must now balance weight reduction imperatives against escalating safety testing protocols.
Recycled nylon yarn derived from post-industrial fishing net recovery is hybridizing rope construction, with European alpine guides and expedition operators adopting these lines for glacier travel and crevasse rescue. The material maintains UIAA fall ratings while addressing sustainability procurement criteria from institutional buyers. This fiber transition is compressing virgin polymer demand among premium-tier suppliers.
The EU's Corporate Sustainability Reporting Directive is mandating supply chain disclosure for protective equipment importers, with German distributors now requiring batch-level polymer sourcing documentation from Asian contract manufacturers. Compliance costs are falling disproportionately on mid-tier brands lacking captive fiber production. Alpine harness and rope categories face the steepest documentation burdens due to their higher polymer mass per unit.
Climbing gym operators in the United States are consolidating purchasing through group procurement organizations, replacing individual facility buying with negotiated multi-year equipment supply agreements. This channel concentration is disintermediating traditional outdoor retail and forcing manufacturers to maintain dedicated institutional sales teams. The shift is most advanced in Texas and Colorado, where gym chain density supports volume-based contracting.
Global Rock Climbing Equipment Market Segmentation
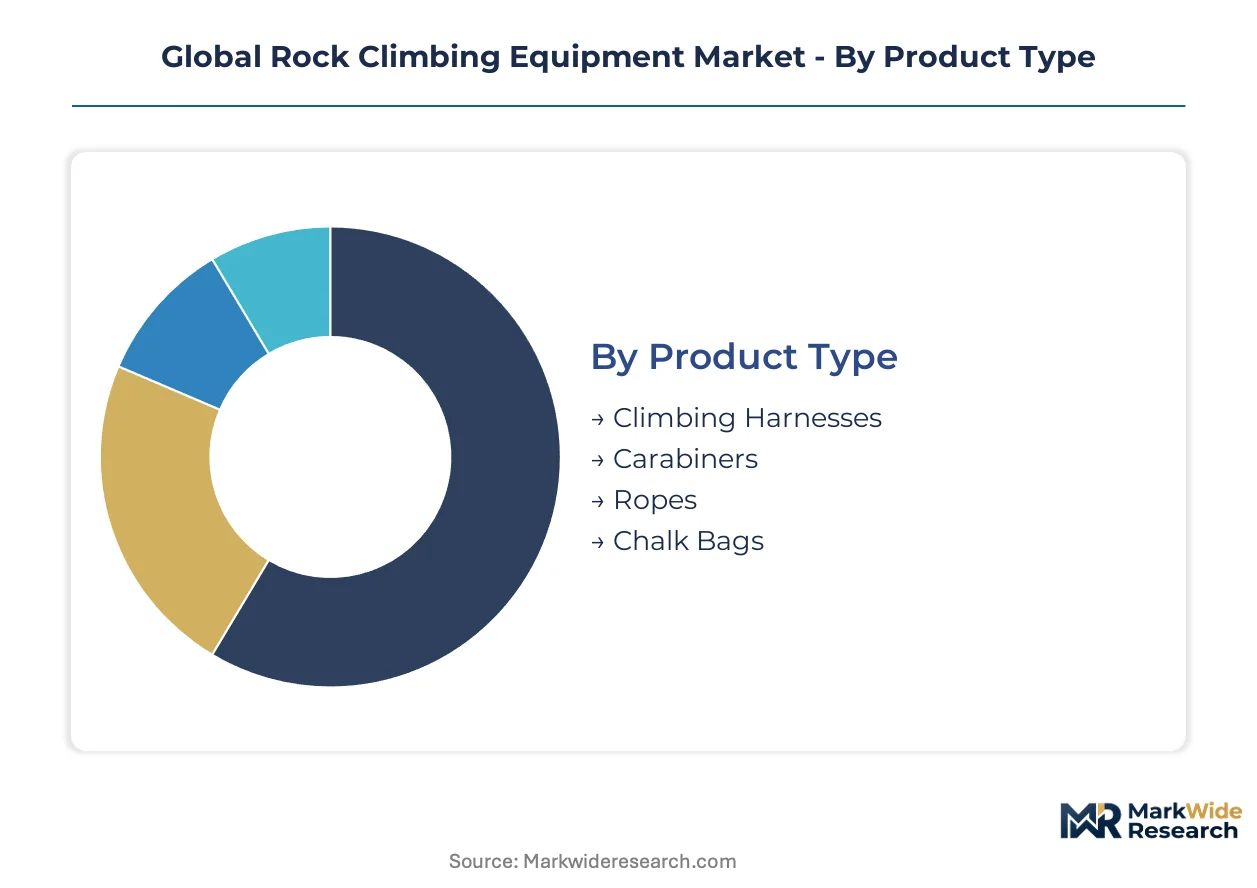
Equipment categorization in rock climbing reflects divergent safety mandates, replacement cycles, and channel economics. Manufacturers optimize production lines around material handling properties and certification batch requirements rather than uniform scaling.
Product Type:
Mature harness and rope categories anchor procurement budgets, while hardware segments exhibit faster innovation turnover.
- Climbing Harnesses:Load-bearing waist and leg loops constructed from high-tenacity nylon webbing with thermoformed padding distribute fall forces across the pelvis and upper thighs. Demand concentrates in United States indoor gym chains negotiating institutional replacement schedules tied to liability insurance renewals.
- Carabiners:Hot-forged aluminum or steel gate mechanisms rated to UIAA 22-kilonewton major-axis standards connect protection points to rope systems. German via ferrata tourism operators drive specialized auto-locking variants with energy-absorbing lanyard compatibility.
- Ropes:Kernmantle braiding with nylon core and polyester sheath delivers dynamic elongation properties for lead climbing fall absorption.
- Chalk Bags:Fleece-lined nylon cylinders with drawstring closures manage magnesium carbonate application for friction-dependent bouldering and sport routes.
Harnesses handle the majority of throughput; carabiners are expanding most quickly on share as sport climbers assemble personal rack collections.
End User:
Volume concentrates in institutional training environments, while professional segments command premium pricing tiers.
- Outdoor Enthusiasts:Self-directed climbers purchasing multi-pitch trad racks and alpine rope systems for independent mountain objectives. Colorado and Utah desert tower specialists drive cam and nut protection demand outside gym-oriented categories.
- Professional Climbers:Sponsored athletes and certified guides requiring CE-marked expedition kits for commercial liability coverage. UIAA-accredited test protocols govern their equipment selection for instructional liability.
- Recreational Users:Occasional gym visitors and single-pitch crag climbers prioritizing rental-grade harnesses and entry shoes.
- Training Facilities:Franchised climbing gyms in Texas and Colorado sourcing volume harness and auto-belay contracts through group purchasing organizations.
Training facilities dominate procurement tonnage; professional climbers generate the steepest margin contribution per unit.
Distribution Channel:
Channel selection correlates with equipment complexity and post-sale service requirements.
- Online Retailers:Direct-to-consumer platforms capturing replacement rope and quickdraw sales from experienced climbers with precise specification knowledge. Return rate compression depends on detailed UIAA rating disclosure and sizing guidance.
- Specialty Stores:Technical climbing shops in Chamonix and Boulder providing harness fitting services and crevasse rescue equipment demonstrations. Staff certification requirements elevate operating costs above general sporting goods competitors.
- Outdoor Gear Shops:Multi-sport retailers stocking climbing alongside skiing and backpacking categories with seasonal inventory rotation.
- Sporting Goods Chains:Mass-market outlets moving entry-level shoes and chalk bags through seasonal promotional cycles.
Specialty stores command the highest service premium; online retailers are gaining share fastest in replacement hardware categories.
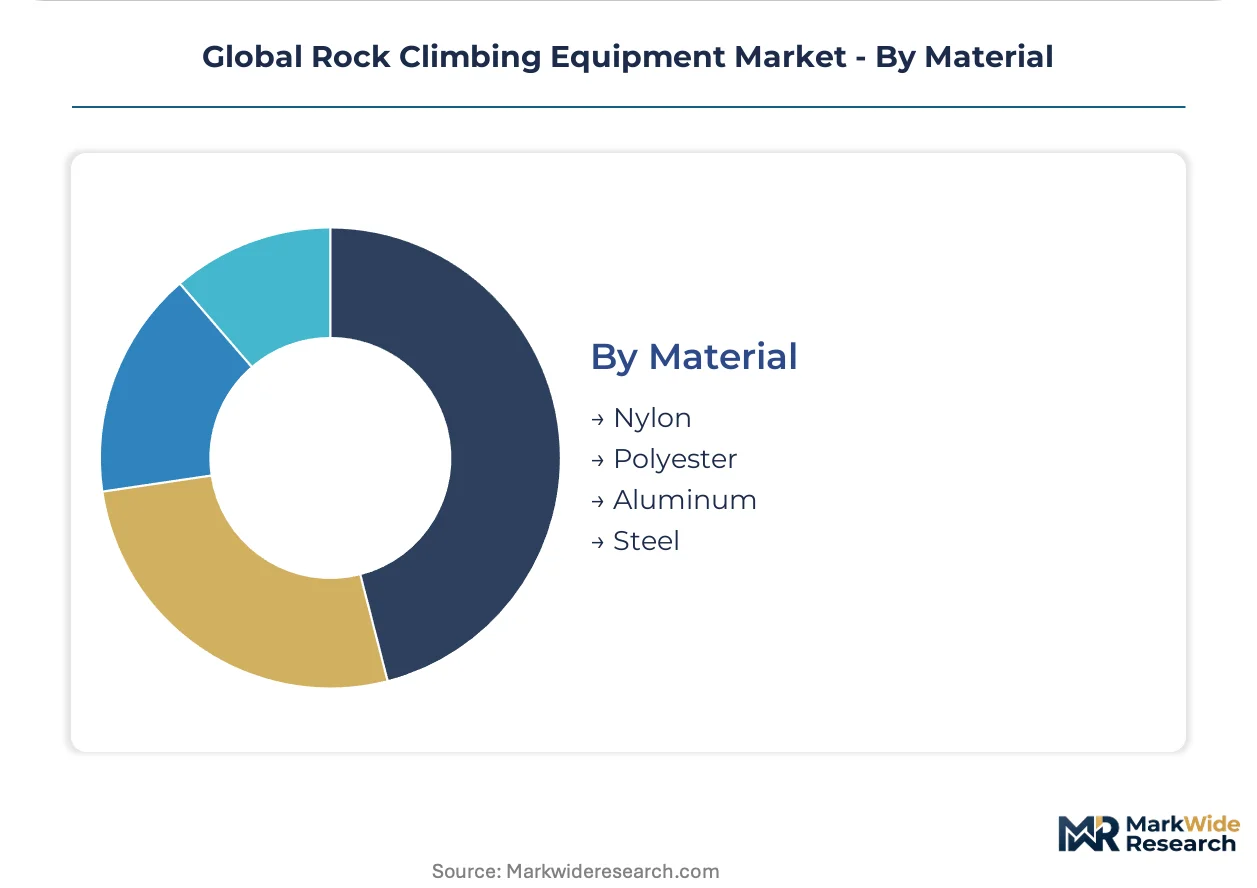
Material:
Material selection traces load-bearing requirements against weight and corrosion constraints.
- Nylon:High-elongation polymer dominating dynamic rope cores and harness webbing for energy absorption during factor-two falls. Petrochemical input volatility from crude derivative pricing squeezes margin predictability for European rope manufacturers.
- Polyester:Lower-stretch fiber preferred for static rope sheaths and via ferrata lanyards where minimal elongation preserves positioning accuracy. German alpine clubs specify polyester-dominant construction for glacier travel kits.
- Aluminum:7000-series alloys in hot-forged carabiners balancing strength-to-weight ratios for redpoint climbing applications.
- Steel:Corrosion-resistant hardware for coastal crags and industrial rope access where durability overrides gram counting.
Nylon handles the majority of polymer throughput; aluminum is climbing the fastest on unit volume as sport participation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export CE-certified harness systems to climbing gym operators across the United States and United Kingdom, establishing a transatlantic trade corridor in institutional safety equipment.
United States
Texas and Colorado gym chains consolidate procurement through group purchasing organizations, bypassing traditional retail channels. OSHA fall-protection standards govern workplace rope access applications, creating crossover demand with recreational gear. Salt Lake City anchors domestic manufacturing with vertically integrated fiber-to-finished-goods operations.
Germany
Bavarian via ferrata tourism operators drive specialized auto-locking carabiner demand for energy-absorbing lanyard systems. The EU's Personal Protective Equipment Regulation enforces CE marking through third-party testing protocols. Munich and Stuttgart host alpine equipment R&D clusters focused on polymer weaving innovation.
Japan
Tokyo metropolitan climbing gyms source S-mark certified hardware for liability coverage under the Consumer Product Safety Law. METI oversees industrial standards harmonization with international UIAA protocols. Osaka-based distributors manage inventory segmentation for domestic certification requirements.
India
Mumbai and Bangalore gym openings create first-mover distribution opportunities before market maturation. BIS standards for personal protective equipment remain under development, producing regulatory uncertainty for importers. Maharashtra climbing facilities currently rely on CE-marked imports for liability insurance compliance.
Australia
New South Wales and Victoria outdoor retailers stock UIAA-rated ropes for Blue Mountains and Grampians climbing destinations. The TGA does not regulate recreational climbing gear, leaving voluntary safety standards to industry self-governance. Sydney specialty shops provide harness fitting services for limestone sport climbing sectors.
Global Rock Climbing Equipment Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base organizes around three archetypes: vertically integrated manufacturers with captive fiber production, design-focused brands leveraging technical outerwear heritage, and hardware specialists concentrating on forged aluminum components. Consolidation pressures emerge as gym operators negotiate multi-year institutional contracts. Geographic expansion into Indian metropolitan markets and capacity investments in recycled polymer processing represent dominant competitive vectors.
Within the vertically integrated tier, Black Diamond Equipment and Petzl exemplify contrasting strategic positions. Arc'teryx occupies a design-premium position derived from laminated construction techniques. These three anchors illustrate how competitive differentiation traces material control, energy-absorbing system R&D, and technical apparel heritage respectively.
| Leading Market Players |
|---|
| La Sportiva |
| Arc'teryx |
| Black Diamond Equipment |
| Edelrid |
| CAMP USA |
| Petzl |
| Scarpa |
| Metolius Climbing |
| Mammut Sports Group |
| Others |
Value Chain & Pricing Dynamics
Zhejiang province's unbranded aluminum forging capacity feeds directly into discount channel price erosion, compressing margin pools for branded carabiner manufacturers who must defend positioning through CE-marked certification premiums and hot-forged construction differentiation.
Pricing Analysis
Current-generation hot-forged aluminum carabiners command substantial premiums over prior-generation cast variants, while next-generation titanium alloys remain pre-commercial. Three-tier pricing structure across premium, standard, and economy levels separates UIAA-certified expedition-grade hardware from gym-rental tier and unbranded Asian imports. Price differentiation traces certification level and volume scale, with institutional gym contracts extracting 40% discounts below retail. Cost compression in entry-tier segments intensifies because Chinese oversupply floods discount channels. Recreational users exhibit highest price sensitivity; professional climbers and industrial rope access operators demonstrate lowest sensitivity due to liability-driven procurement.
Supply Chain Analysis
Petrochemical derivatives from Saudi Arabia, South Korea, and the United States constitute the upstream feedstock for high-tenacity nylon and polyester fiber production. Kernmantle rope construction draws from virgin polymer supply chains anchored in European and Asian petrochemical complexes, with recycled fishing net recovery emerging as alternative fiber sourcing. Single-source vulnerability concentrates in specialized textile engineering labor, where UIAA-accredited braiding technicians command premium compensation. Distribution runs through direct institutional accounts for gym chains, specialty retailers for technical alpine equipment, and online platforms for replacement hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indoor climbing gym networks are consolidating procurement through group purchasing organizations, creating platform-economics dynamics where equipment interoperability and multi-year service bundling determine vendor selection rather than discrete product specifications.
For Market Incumbents: Harden institutional sales organizations against disintermediation by embedding replacement scheduling software and liability insurance alignment into gym contracts. Defend margin position through captive fiber production or exclusive recycled polymer partnerships that satisfy EU Corporate Sustainability Reporting Directive documentation burdens. Certification timeline compression from CE marking and Japan S-mark protocols represents the primary regulatory threat requiring dedicated compliance infrastructure. For New Entrants and Emerging Players: Mumbai and Bangalore metropolitan gym openings represent the most penetrable entry point before market maturation locks in incumbent relationships. Indian climbing facilities currently rely on CE-marked imports, creating first-mover advantage for brands establishing local distribution and BIS standards pre-positioning. Target group procurement organization participation as the essential go-to-market angle, bypassing traditional retail channel development entirely. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed outdoor conglomerates holding portfolio brands with overlapping distribution but divergent manufacturing footprints. Long-term viability centers on recycled polymer processing capabilities and Indian market positioning within a 5-10 year window. Acquisition target archetype: mid-tier harness and rope manufacturers lacking vertical fiber integration but holding CE-marking infrastructure. The signal to watch is BIS standards finalization triggering forced import substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polymer Processing Investment | EU Corporate Sustainability Reporting Directive mandates batch-level sourcing documentation from German distributors. |
| Indian Distribution Infrastructure Buildout | Mumbai and Bangalore gym openings create first-mover positioning before BIS standards crystallize. |
| Institutional Sales Team Expansion | Texas and Colorado gym chains consolidate procurement through group purchasing organizations bypassing retail. |
| UIAA-Accredited Testing Laboratory Acquisition | CE marking and S-mark approval timelines compress product launch windows behind design completion. |
| Biomechanical Sensor Platform Development | Wearable force-measurement devices enable data-driven training programs and predictive equipment replacement alerts. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with climbing gym procurement directors, UIAA-accredited test engineers, alpine guide association equipment officers, and polymer sourcing managers at rope manufacturers. Secondary validation drew from EU CE marking databases, OSHA fall-protection standard filings, Japanese S-mark certification registries, and trade customs records for aluminum hardware imports. Bottom-up equipment shipment analysis triangulated against top-down gym membership and participation rate estimates.
Calibration anchored volume and value outputs to facility expansion pipelines, replacement cycle documentation from institutional insurance renewals, and polymer cost pass-through elasticity observed across the analysis window. Segmentation dimensions modeled include product type, end-user category, distribution channel, material composition, and regional regulatory cluster. CAGRs derived from slope-log regression on normalized participation indices and equipment penetration rates. Industry-specific forecast inputs encompass youth program enrollment trajectories post-Olympic inclusion and via ferrata tourism operator procurement patterns.
Macroeconomic conditions sit as an overlay; deviation in crude oil derivative pricing, euro-yen exchange rates, or Indian rupee volatility would shift the trajectory. Forecasts reflect documented assumptions regarding certification timeline stability and gym chain consolidation pace. Material shifts in BIS standards promulgation, EU polymer disclosure enforcement intensity, or Chinese environmental regulation tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Baseball Equipment Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Curling Equipment Market
Sports Equipment
Surfboard Market
Sports Equipment
Europe Kickboxing Equipment Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Starting Blocks Market
Sports Equipment
North America Kickboxing Equipment Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Squash Equipment Market
Sports Equipment
Hunting Equipment and Accessories Market
Sports Equipment
Mini Balance Beam Market