
 Squash Equipment Market | 2026-2036
Squash Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Squash Equipment Market Intelligence
Aftermarket service revenue for racket restringing and grip replacement is fragmenting across independent pro shops and direct-to-consumer mail-in programs. Wilson Sporting Goods leverages its authorized dealer network to sustain premium pricing on certified restring services. Prince anchors its aftermarket presence through proprietary string tension diagnostics offered at select retail partners. Dunlop Sport competes with flat-rate refurbishment bundles that appeal to club-level players seeking predictable maintenance costs.
Squash equipment comprises rackets, balls, footwear, and protective eyewear engineered for indoor court play, with graphite and carbon fiber composite rackets typically weighing 110-170 grams strung and featuring teardrop or throat-bridge geometries optimized for power or control. The equipment serves competitive athletes, recreational players, and institutional programs requiring durability standards for high-frequency use. Rackets constructed from carbon fiber dominate margin pools due to material cost premiums and player willingness to pay for stiffness-to-weight ratios, while the amateur and club end-user segment represents the volume foundation as school and municipal program enrollment expands. Online retail channels are capturing share from specialty stores by offering custom string configurations and trial-period policies that reduce purchase friction for new entrants.
ISO 9001 quality management standards govern manufacturing consistency for export-oriented producers, while the World Squash Federation equipment specifications dictate ball bounce characteristics and court dimension compliance that shape product development cycles. National sports federations in key markets enforce eye protection mandates that drive recurring eyewear replacement demand. Stakeholders must monitor raw material tariff schedules and court construction permitting trends to anticipate regional demand inflection points.
Market Dynamics
Carbon fiber composite manufacturing is compressing racket weight thresholds below 110 grams, forcing incumbent producers to retool filament winding lines while Egyptian professional academies accelerate equipment turnover through subsidized player development pipelines.
Growth Catalysts
- Community sports infrastructure:Municipal squash programs in England and Australia are expanding court construction through national lottery funding mechanisms, creating captive equipment demand from institutional procurement officers.
- ISO 9001 export certification:Pakistani and Chinese manufacturers achieving quality management standardization are penetrating European specialty retail channels previously blocked by compliance barriers.
- Protective eyewear mandates:National federation enforcement of court-side eye protection rules in Canada and the United States is generating recurring replacement cycles for polycarbonate lens inventory.
Market Restraints
- Raw material tariff volatility:Carbon fiber prepreg imports face unpredictable duty schedules between major manufacturing hubs and key consumer markets, compressing margin predictability for mid-tier racket assemblers.
- Technical performance ceiling:Stiffness-to-weight ratios in graphite-composite frames are approaching theoretical material limits, constraining product differentiation through specification escalation alone.
- Substitution from padel:Latin American and Southern European markets are experiencing facility conversion to padel courts, diverting recreational player budgets and reducing squash-specific equipment addressable spend.
Strategic Opportunities
- Direct-to-consumer string customization:Online configurators allowing tension and gauge selection are capturing first-time buyers previously dependent on pro shop expertise, with trial-period return policies reducing purchase friction.
- Mail-in refurbishment programs:Independent operators and manufacturer-direct services are unbundling restringing and grip replacement from retail markup structures, building recurring revenue attachment to initial racket sales.
- School enrollment expansion:Physical education curriculum adoption in Egypt and Malaysia is creating institutional volume demand for durable aluminum alloy rackets at price points below competitive carbon fiber offerings.
Industry Challenges
- Stringing technician scarcity:Certified racket service professionals are concentrating in metropolitan club clusters, leaving secondary markets with extended turnaround times for maintenance services.
- Inventory obsolescence risk:Rapid geometry preference shifts between teardrop and throat-bridge designs are forcing distributors to carry broader SKU portfolios, tying up working capital in slow-moving frame configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Squash Equipment Market |
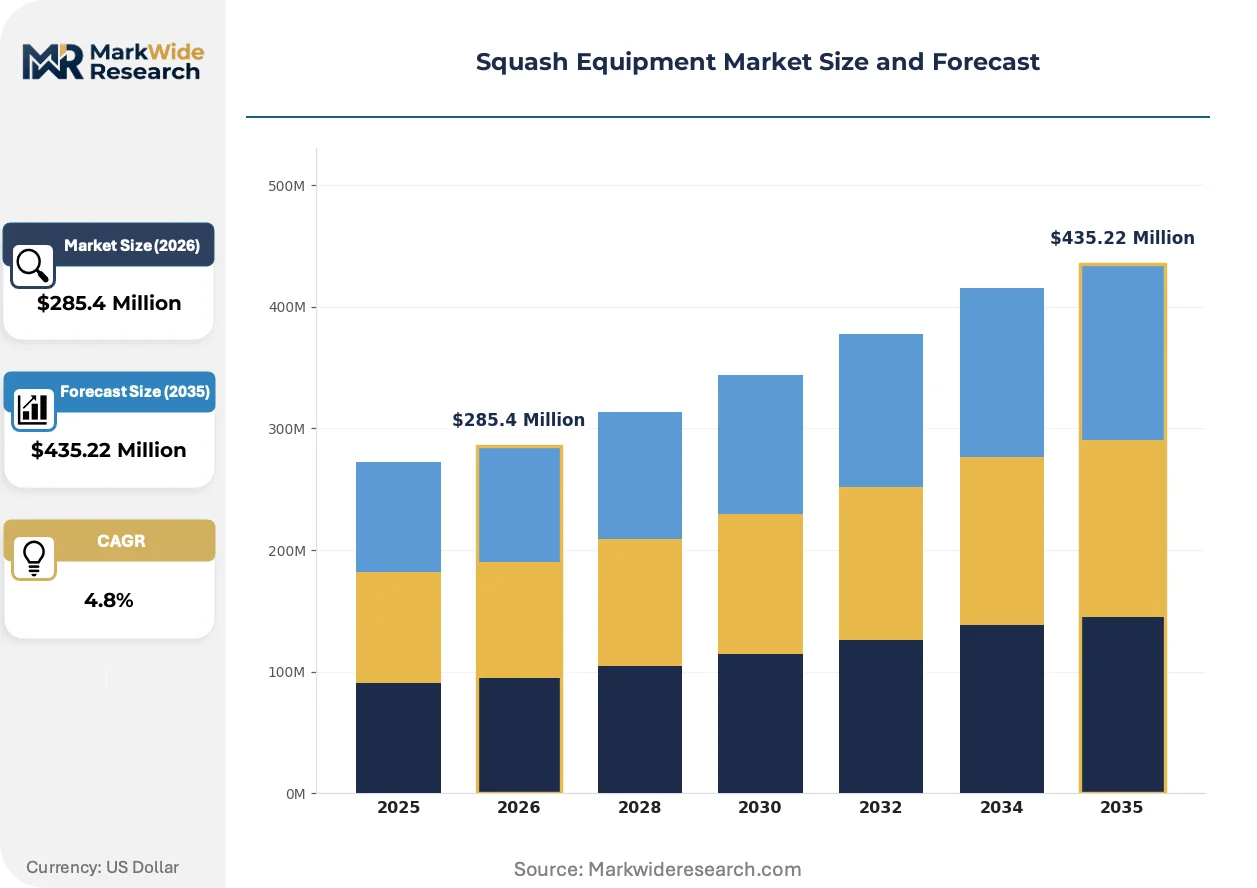
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rackets, Balls, Shoes, Eyewear Material: Carbon Fiber, Aluminum, Plastic, Rubber End User: Amateurs, Professionals, Clubs, Schools Distribution Channel: Online Retail, Specialty Store, Supermarket, Others |
| Companies Covered | Wilson Sporting Goods, Prince, Dunlop Sport, Eye Rackets International, Harrow Sports, Head, Karakal Worldwide Ltd., UNSQUASHABLE, Tecnifibre, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Squash Equipment Market Strategic Shifts & Innovations
Digital tools are penetrating equipment selection and maintenance workflows, compressing the traditional pro shop advisory role while enabling data-driven player optimization previously accessible only to elite coaching environments.
Sensor-embedded racket handles are virtualizing swing analysis by capturing impact location, ball velocity, and stroke frequency during live play. Amateur players in Germany and the Netherlands are adopting these devices at accelerating rates through subscription-enabled mobile applications. The technology is virtualizing coaching relationships by replacing in-person biomechanical assessment with algorithm-generated technique recommendations.
REACH chemical substance restrictions in the European Union are compelling manufacturers to reformulate epoxy resin systems and surface coatings used in composite frame production. Industrial laboratories in Belgium and Italy are validating alternative hardener compounds that maintain structural integrity while eliminating SVHC-classified additives. Small-batch producers serving club-level segments are experiencing compliance timeline compression as certification documentation requirements expand.
After-sales service unbundling is fragmenting equipment ownership economics across player segments. Recreational participants in Australia and England are shifting from bundled retail packages toward à la carte string replacement schedules managed through manufacturer-direct portals. Specialty stores are responding by anchoring foot traffic through court booking systems and tournament organization rather than transactional equipment margins alone.
Squash Equipment Market Segmentation
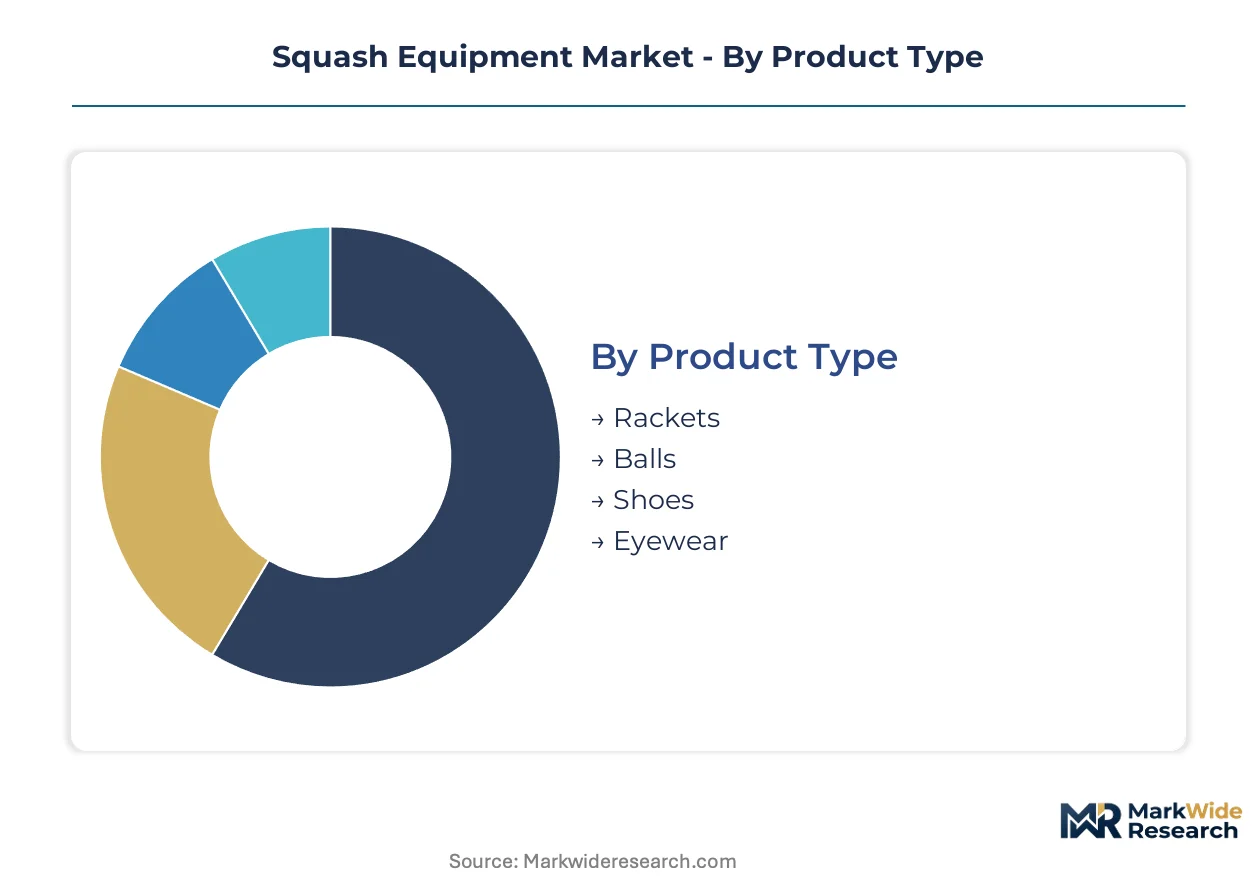
Equipment segmentation in squash reveals divergent margin structures across material grades and procurement contexts. Carbon fiber rackets command premium positioning through stiffness-to-weight engineering, while institutional channels drive volume through aluminum alternatives. Understanding these divides shapes inventory strategy and pricing architecture.
Product Type:
Cost tier differentiation separates recreational consumables from capital-intensive racket purchases that anchor player lifetime value.
- Rackets:Graphite and carbon fiber composite frames weighing 110-170 grams strung, with teardrop or throat-bridge geometries optimized for power or control. Egyptian professional academies accelerate turnover through subsidized player development pipelines, compressing replacement cycles for high-performance models.
- Balls:Rubber compound spheres with varying bounce characteristics governed by World Squash Federation specifications. Blue dot and double yellow dot variants concentrate demand in competitive circuits, while single dot configurations serve entry-level instructional programs.
- Shoes:Non-marking gum rubber soles engineered for lateral court movement and rapid directional changes. Club-level procurement in England and Australia drives institutional volume through municipal program expansion.
- Eyewear:Polycarbonate protective lenses meeting national federation mandates in Canada and the United States. Recurring replacement cycles generate steady aftermarket revenue as lens scratching and strap degradation force refresh purchases.
Rackets command the established base. The steepest expansion runs through eyewear as protective mandate enforcement spreads.
Material:
Application requirements dictate material selection, with performance thresholds separating elite competition from mass participation contexts.
- Carbon Fiber:Prepreg filament-wound composites delivering superior stiffness-to-weight ratios below 110 grams in emerging configurations. Manufacturing retooling pressures incumbent producers as Egyptian and Malaysian academies specify elite-grade equipment.
- Aluminum:Alloy extrusions offering durability and cost accessibility for high-frequency institutional use. Physical education curriculum adoption in Egypt and Malaysia drives volume procurement for school inventory.
- Plastic:Injection-molded components for entry-level racket throats and protective eyewear frames. REACH chemical restrictions in the European Union compel reformulation of epoxy resin systems and surface coatings.
- Rubber:Natural and synthetic compounds for ball construction and shoe sole applications. Bounce consistency standards enforced by national federations constrain supplier flexibility in compound formulation.
Carbon fiber dominates margin capture. Aluminum is climbing the fastest as institutional enrollment scales.
End User:
Customer type segmentation reveals divergent service expectations, with professionals demanding customization and amateurs prioritizing accessibility.
- Amateurs:Recreational participants purchasing through online configurators with trial-period return policies. Direct-to-consumer string customization is capturing first-time buyers previously dependent on pro shop expertise.
- Professionals:Elite athletes requiring certified restring services and proprietary string tension diagnostics. Wilson Sporting Goods leverages authorized dealer networks to sustain premium pricing on aftermarket maintenance.
- Clubs:Facility operators managing fleet inventory for member access and rental programs. Court booking systems and tournament organization now anchor specialty store foot traffic beyond transactional equipment margins.
- Schools:Municipal and institutional procurement officers sourcing durable equipment for physical education curricula. National lottery funding mechanisms in England and Australia are expanding court construction and captive equipment demand.
Amateurs represent the volume foundation. Professionals concentrate margin extraction through service attachment.
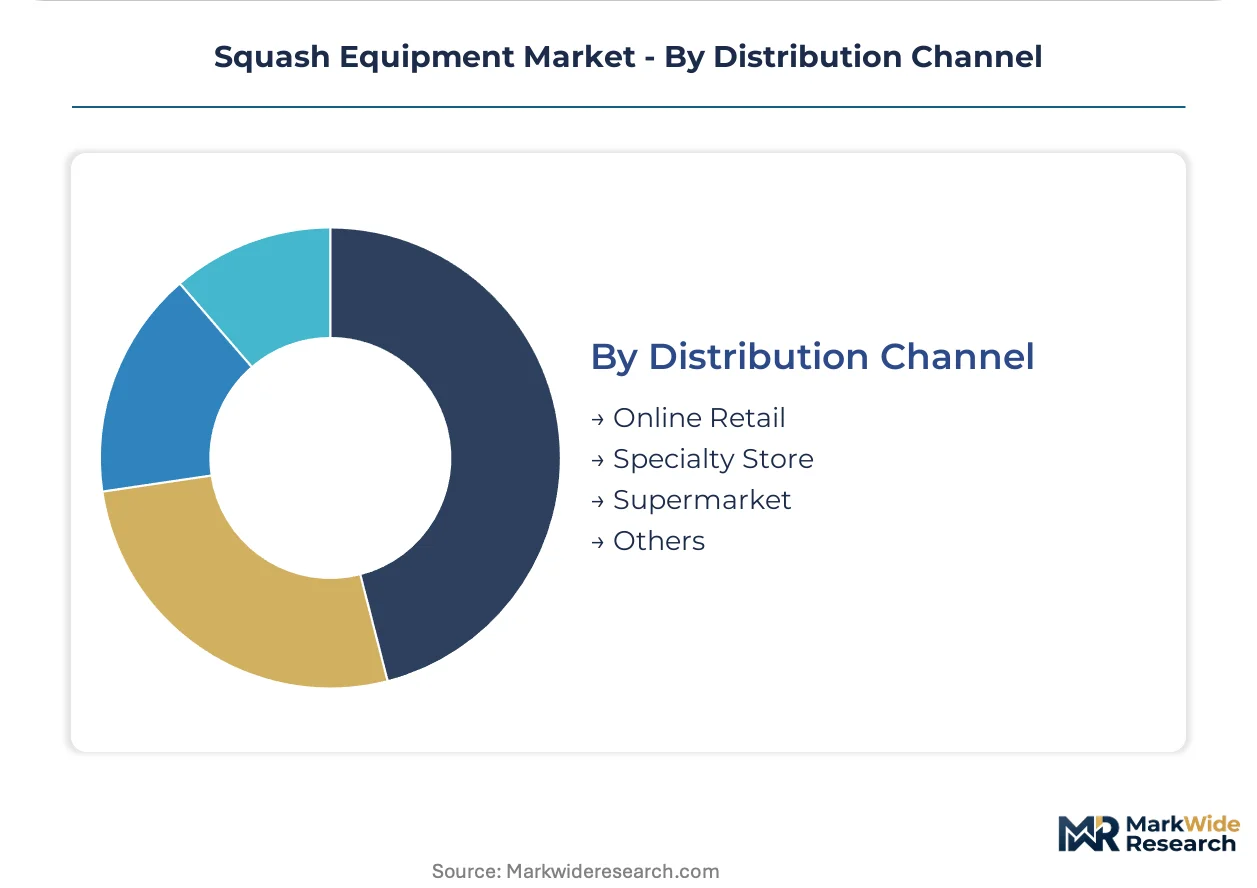
Distribution Channel:
Supply concentration shapes competitive access, with digital channels unbundling traditional retail advisory functions.
- Online Retail:E-commerce platforms offering custom string configurations and manufacturer-direct refurbishment programs. Mail-in restringing services are fragmenting aftermarket revenue across independent operators.
- Specialty Store:Authorized dealers providing certified restring services and biomechanical assessment. Prince anchors presence through proprietary diagnostics at select retail partners.
- Supermarket:Mass-market outlets stocking entry-level aluminum rackets and basic protective eyewear. Price-focused positioning serves occasional participants with minimal service expectations.
- Others:Direct institutional procurement and academy subsidized pipelines. Egyptian professional development infrastructure drives equipment turnover through non-retail channels.
Specialty stores retain service-intensive transactions. Online retail is gaining share fastest through customization and trial policies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Egyptian players favor ultra-light carbon fiber frames subsidized by academy pipelines, while English and Australian markets prioritize institutional aluminum procurement through municipal funding mechanisms. This consumption-mix differential separates professional development infrastructure from recreational program expansion.
Egypt
Professional player development academies in Cairo and Alexandria drive accelerated equipment turnover through subsidized carbon fiber racket distribution. The Egyptian Ministry of Youth and Sports channels public investment toward squash infrastructure as a national prestige priority. Manufacturing partnerships with European composite specialists concentrate in the Greater Cairo zone, feeding elite-grade supply chains.
United Kingdom
England Squash leverages National Lottery funding to expand municipal court construction across Birmingham, Manchester, and London boroughs. Sport England facility grants mandate ISO 9001-certified equipment procurement for publicly funded programs. Specialty retail clusters in London's West End sustain premium restringing services for club-level competitive players.
Australia
Squash Australia coordinates state-level program enrollment through Victoria and New South Wales physical education curricula. The Australian Sports Commission distributes equipment subsidies to regional schools, prioritizing durable aluminum alloy inventory. Court construction permits in Melbourne and Sydney metropolitan areas are accelerating through streamlined municipal planning frameworks.
United States
US Squash enforces protective eyewear mandates through tournament sanctioning requirements, generating recurring replacement demand in Boston, Philadelphia, and New York metro corridors. NCAA emerging sport status for women's squash is expanding collegiate procurement channels. Club facility operators in the Northeast corridor are converting underutilized racquetball courts to squash configuration.
Germany
REACH chemical substance restrictions are compelling racket manufacturers to reformulate epoxy resin systems for EU market access. The German Squash Association certifies coaching programs in Hamburg and Munich that specify sensor-embedded equipment for technique analysis. Industrial laboratories in Belgium and Italy supply compliant hardener alternatives to German distributors.
Squash Equipment Market Key Industry Players
Capability concentration sits with specialized composite manufacturers; scale advantage sits with diversified sporting goods conglomerates. The market structures around three tiers: premium carbon fiber specialists, mid-market aluminum assemblers, and mass-market entry-level distributors. Strategic archetypes include academy-integrated equipment pipelines, direct-to-consumer customization platforms, and authorized dealer service networks. Dominant competitive moves encompass filament winding line retooling for sub-110 gram thresholds and mail-in refurbishment program launches.
Within the premium-tier vector, Wilson Sporting Goods and Prince exemplify divergent aftermarket strategies—one leveraging authorized dealer certification, the other deploying proprietary diagnostics at retail partners. Dunlop Sport occupies a position in flat-rate service bundling. Tecnifibre and Head represent European composite engineering concentration, while Eye Rackets International and Harrow Sports anchor North American specialty distribution. Karakal Worldwide Ltd. and UNSQUASHABLE sit within the accessibility-focused tier serving institutional volume channels.
| Leading Market Players |
|---|
| Wilson Sporting Goods |
| Prince |
| Dunlop Sport |
| Eye Rackets International |
| Harrow Sports |
| Head |
| Karakal Worldwide Ltd. |
| UNSQUASHABLE |
| Tecnifibre |
| Others |
Cost & Logistics Intelligence
Shanghai-Rotterdam container freight corridors transmit carbon fiber prepreg cost volatility directly into Egyptian academy procurement budgets and European specialty retail markups, compressing margin predictability for mid-tier assemblers while amplifying price differentiation between certified dealer networks and direct-to-consumer channels.
Pricing Analysis
Long-term offtake contracts between European composite specialists and Egyptian professional academies anchor volume pricing for sub-110 gram carbon fiber frames, while spot-market aluminum alloy purchases by Australian municipal programs introduce cost variability at the institutional tier. Price differentiation hinges on ISO 9001 certification status and after-sales service bundling, with certified restringing packages commanding sustained premiums. Pricing pressure stems from raw material tariff unpredictability between major manufacturing hubs. Amateur online buyers exhibit highest price sensitivity, while professional players prioritize performance specifications over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Pakistani and Chinese filament winding specialists serving European brand specifications, while Belgian and Italian industrial laboratories dominate REACH-compliant hardener formulation. Geographic supply concentration centers on China for carbon fiber prepreg, Pakistan for aluminum alloy extrusions, and Egypt for academy-integrated distribution pipelines. Raw material dependencies encompass Japanese Toray carbon fiber, Chinese epoxy resin systems, and Malaysian natural rubber compounds. Supply chain risk manifests as single-source vulnerability in certified stringing technician labor pools. Distribution runs through authorized dealer networks for premium tiers and manufacturer-direct portals for refurbishment services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service layers—mail-in restringing, sensor-embedded subscription analytics, and protective eyewear replacement cycles—are expanding faster than hardware unit sales, repositioning equipment vendors as recurring revenue platforms rather than transactional manufacturers.
For Market Incumbents: Pre-empt padel facility conversion in Southern European and Latin American markets by anchoring club relationships through court booking systems and tournament infrastructure rather than equipment margins alone. Deepen backward integration into carbon fiber prepreg sourcing to defend against tariff volatility. Accelerate proprietary string tension diagnostic certification to differentiate authorized dealer networks from independent pro shops. For New Entrants and Emerging Players: Malaysian school procurement channels represent the most penetrable white-space target, with physical education curriculum expansion driving institutional aluminum racket volume at price points below incumbent carbon fiber positioning. Direct-to-consumer string configurators with trial-period policies offer the lowest-friction go-to-market angle for first-time amateur buyers previously dependent on pro shop expertise. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors sensor-embedded equipment platforms with subscription-enabled mobile applications over pure hardware manufacturers. Long-term viability across the projection horizon rests on recurring revenue attachment rates rather than unit shipment growth. Acquisition targets should demonstrate academy-integrated distribution pipelines or proprietary refurbishment program infrastructure. The signal to watch is municipal court construction permitting velocity in England and Australia as a demand inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Filament Winding Line Retooling | Sub-110 gram threshold achievement captures Egyptian academy specification mandates. |
| Mail-in Refurbishment Program Launch | Manufacturer-direct restringing unbundles aftermarket revenue from retail markup structures. |
| REACH-Compliant Resin Reformulation | Belgian and Italian laboratory partnerships secure EU market access against chemical restrictions. |
| Sensor-Embedded Subscription Platform | German and Dutch amateur adoption of swing analytics virtualizes traditional coaching relationships. |
| Academy-Integrated Distribution Pipeline | Egyptian Ministry of Youth and Sports partnerships accelerate equipment turnover through subsidized player development. |
Research Approach
Findings reconcile primary fieldwork against secondary review of World Squash Federation equipment specifications, national federation procurement databases, and carbon fiber composite trade flow records. Primary interviews encompassed racket manufacturing plant managers, specialty retail pro shop operators, municipal sports program procurement officers, and professional academy equipment coordinators. Secondary validation drew from ISO 9001 certification registries, REACH compliance documentation, and customs import data for prepreg materials. Bottom-up segmentation modeling triangulated against top-down market sizing from institutional enrollment trends and court construction permits.
Forecast inputs incorporate material grade segmentation, end-user procurement context, and distribution channel dynamics across the analysis window. Modeled dimensions span product type, material composition, customer tier, and geographic regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections tied to municipal funding mechanisms and academy pipeline expansion rates. Industry-specific inputs include stringing technician labor pool concentration and geometry preference shift velocity between teardrop and throat-bridge configurations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by padel facility operators or carbon fiber tariff coalition formations would shift outcomes. Quarterly review of municipal court construction permitting trends and academy subsidized procurement volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Baseball Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Skydiving Equipment Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Turbo Trainer Market
Sports Equipment
One-Piece Carbon Fiber Badminton Racket Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Football Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Golf Club Grips Market
Sports Equipment
High-End Bicycle Market
Sports Equipment
UK Horse Riding Equipment Market