
 Europe Climbing Gym Market | 2026-2036
Europe Climbing Gym Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Climbing Gym Market Foresight
The EU Green Deal is broadening the sustainability requirements for indoor sports facility construction across member states. DAV Kletterhallen leverages its German Alpine Club heritage to anchor premium membership loyalty in Central Europe. Climb Up competes through aggressive geographic expansion into secondary French and Belgian cities. Boulders specializes in compact urban bouldering formats that occupy limited real estate footprints profitably.
Europe climbing gyms comprise indoor artificial climbing structures featuring engineered wall surfaces with resin or fiberglass holds, typically constructed with steel-framed plywood or concrete substrates rated for dynamic load factors. These facilities serve commercial fitness, competitive training, and social recreation purposes through controlled vertical movement environments. Bouldering gyms capture disproportionate new-build investment due to lower ceiling height requirements and reduced liability infrastructure compared with roped climbing walls. Monthly membership models sustain the dominant revenue share across the customer segment dimension, while single-pass ticketing retains importance in tourist-heavy Southern European markets.
CE marking governs structural safety of climbing wall installations under the EU Construction Products Regulation, while national building codes in France, Germany, and Spain impose additional fire resistance and accessibility standards. The EU AI Act introduces emerging compliance considerations for automated route-setting systems and visitor analytics platforms. Facility operators must monitor evolving insurance liability frameworks and decide whether to self-certify climbing equipment or delegate to third-party accredited bodies.
Market Dynamics
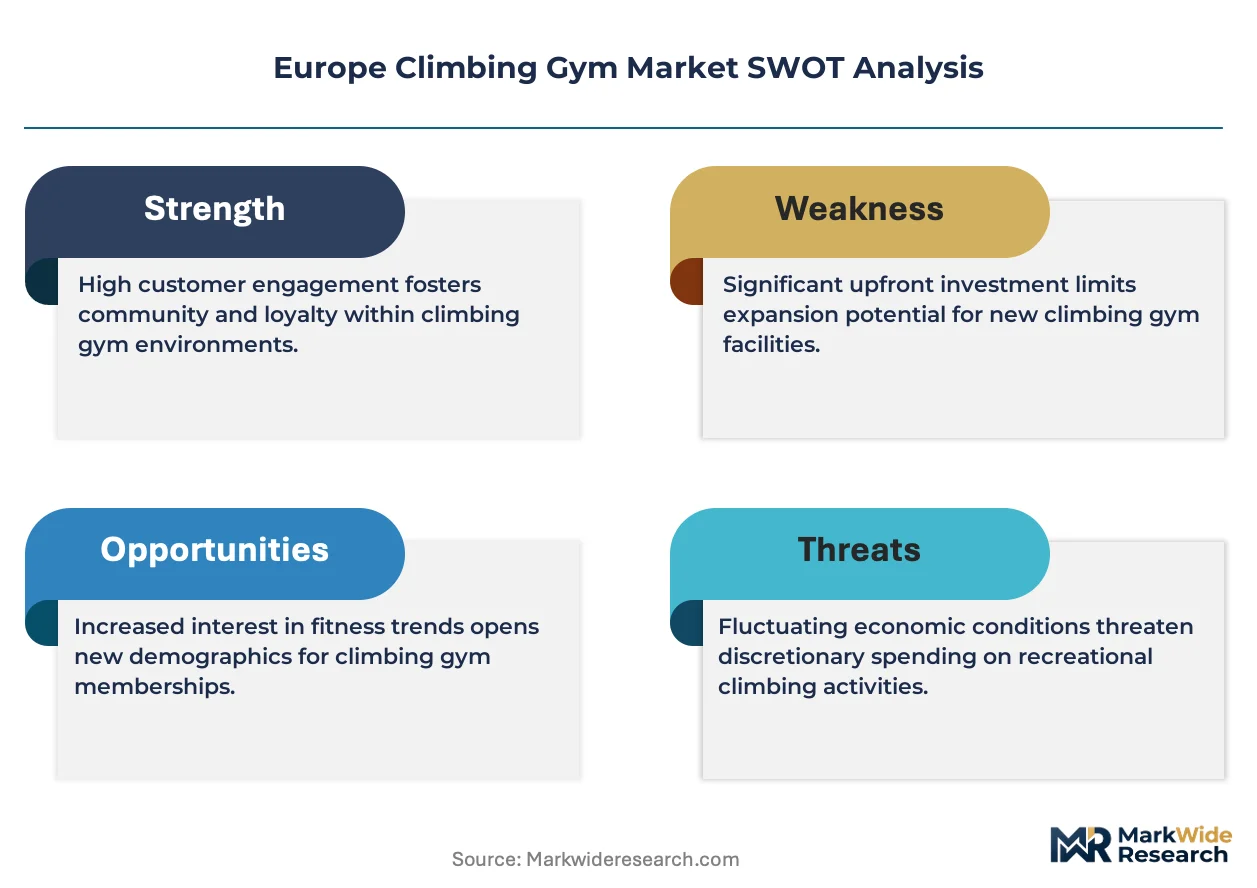
The EU Green Deal's building retrofit mandates are compressing facility development timelines across member states, forcing operators to integrate sustainable construction methods into new climbing gym projects from the ground up rather than retrofitting later.
Growth Catalysts
- Recreational climber expansion:Social fitness seekers now dominate new membership acquisition across French and German facilities, broadening the customer base beyond traditional mountaineering communities.
- EU Green Deal mandates:Building retrofit requirements for indoor sports infrastructure are accelerating demand for energy-efficient HVAC and lighting systems in new gym construction.
- Bouldering format economics:Lower ceiling height requirements reduce structural steel and concrete costs, enabling profitable operations in converted urban warehouses.
Market Restraints
- Real estate concentration in urban cores:Prime locations in Berlin, Paris, and Barcelona command premium lease rates that constrain expansion into secondary districts.
- Steel and engineered timber volatility:Wall substrate materials face input cost swings tied to construction sector demand cycles across Central Europe.
- CE marking compliance burden:The EU Construction Products Regulation imposes third-party testing costs on wall manufacturers that smaller operators struggle to absorb.
Strategic Opportunities
- Portuguese and Eastern European whitespace:Spain and Poland show climbing gym density gaps relative to GDP per capita, offering first-mover positioning for franchise concepts.
- EU AI Act route-setting automation:Automated hold placement systems reduce labor costs while enabling dynamic difficulty calibration for personalized training programs.
- Tourism-integrated day-pass channels:Southern European coastal cities can capture seasonal visitor flows through partnerships with hospitality booking platforms.
Industry Challenges
- Route-setting talent pipeline:Certified setters capable of commercial-grade creativity remain scarce relative to facility expansion rates.
- Legacy wall upgrade cycles:Early 2000s plywood-steel installations face obsolescence against modern fiberglass-resin surfaces with superior texture durability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Climbing Gym Market |
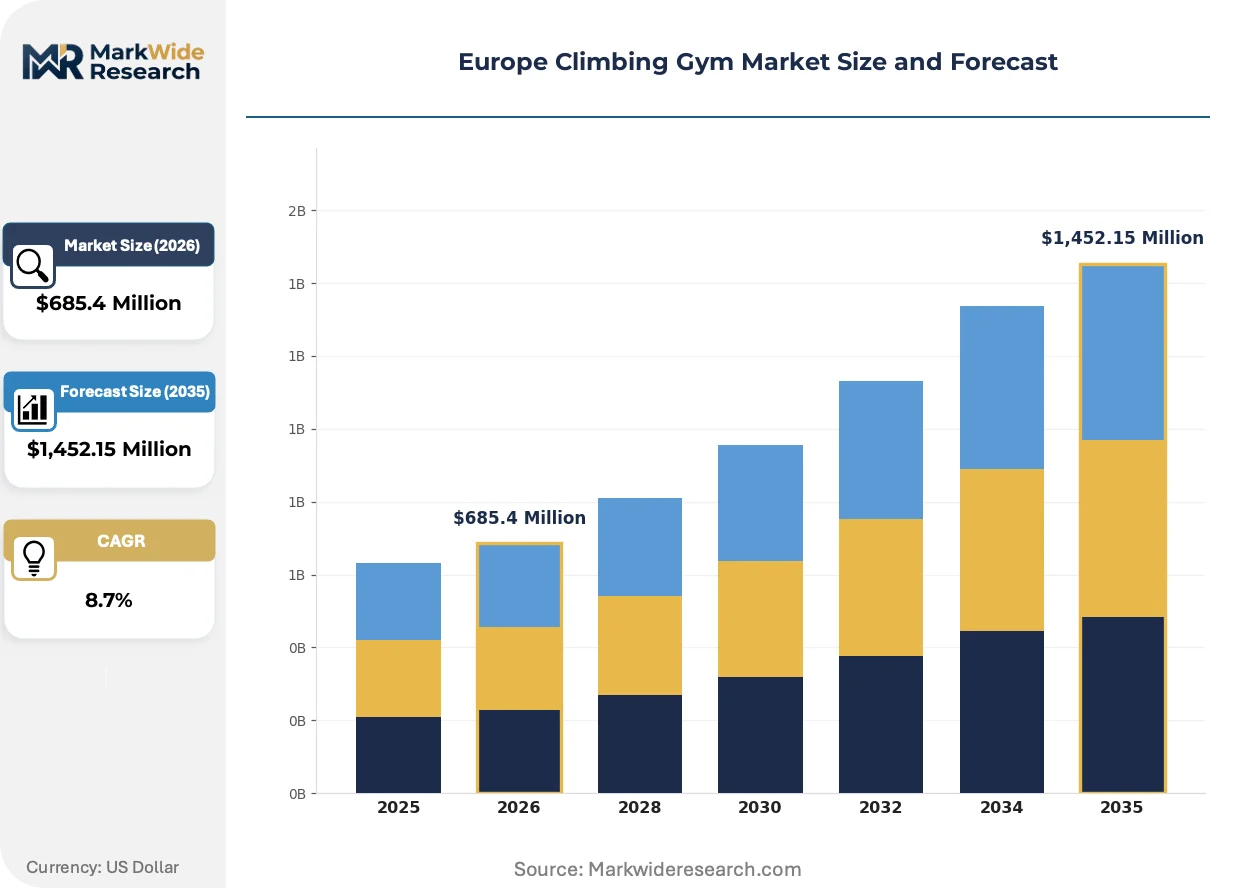
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Climbing Walls, Bouldering Gyms, Training Centers, Multi-Sport Facilities Customer Segment: Recreational Climbers, Professional Athletes, Schools, Fitness Enthusiasts Climbing Type: Sport Climbing, Bouldering, Traditional Climbing, Competition Climbing Membership Model: Single Pass, Monthly Membership, Annual Membership, Family Packages |
| Companies Covered | The Font, DAV Kletterhallen, Climb Up, Falkors Climbing, Element, Indoorwall Centers, Boulders, Vertigo, Climbing Network, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Climbing Gym Market Shifts & Advancements
Facility design philosophy is pivoting from pure athletic performance toward hybrid social-entertainment spaces, with operators investing in adjacent amenities that extend dwell time and per-visit spend.
Adjustable LED-integrated wall surfaces are absorbing the role of static painted routes in premium facilities. Operators in Germany and the Netherlands are retrofitting existing structures with programmable light projections that indicate problems without physical tape or markers. This technology is absorbing route-setting labor hours while enabling instant difficulty modifications that respond to real-time occupancy patterns.
The EU AI Act is introducing compliance frameworks for automated visitor analytics and route recommendation engines. Facility operators deploying computer vision for crowd management must now document algorithmic transparency and data governance protocols. German and Austrian gyms with integrated training apps are most affected, restructuring vendor contracts to include audit rights and explainability requirements.
Corporate wellness procurement is displacing individual membership as the dominant B2B channel. Large employers in Denmark and Sweden now subsidize climbing gym access as part of mental health and team-building benefits. This shift is most visible in Copenhagen and Stockholm, where facilities dedicate weekday morning slots to contracted corporate groups at rates 40% below peak retail pricing.
Europe Climbing Gym Market Segmentation
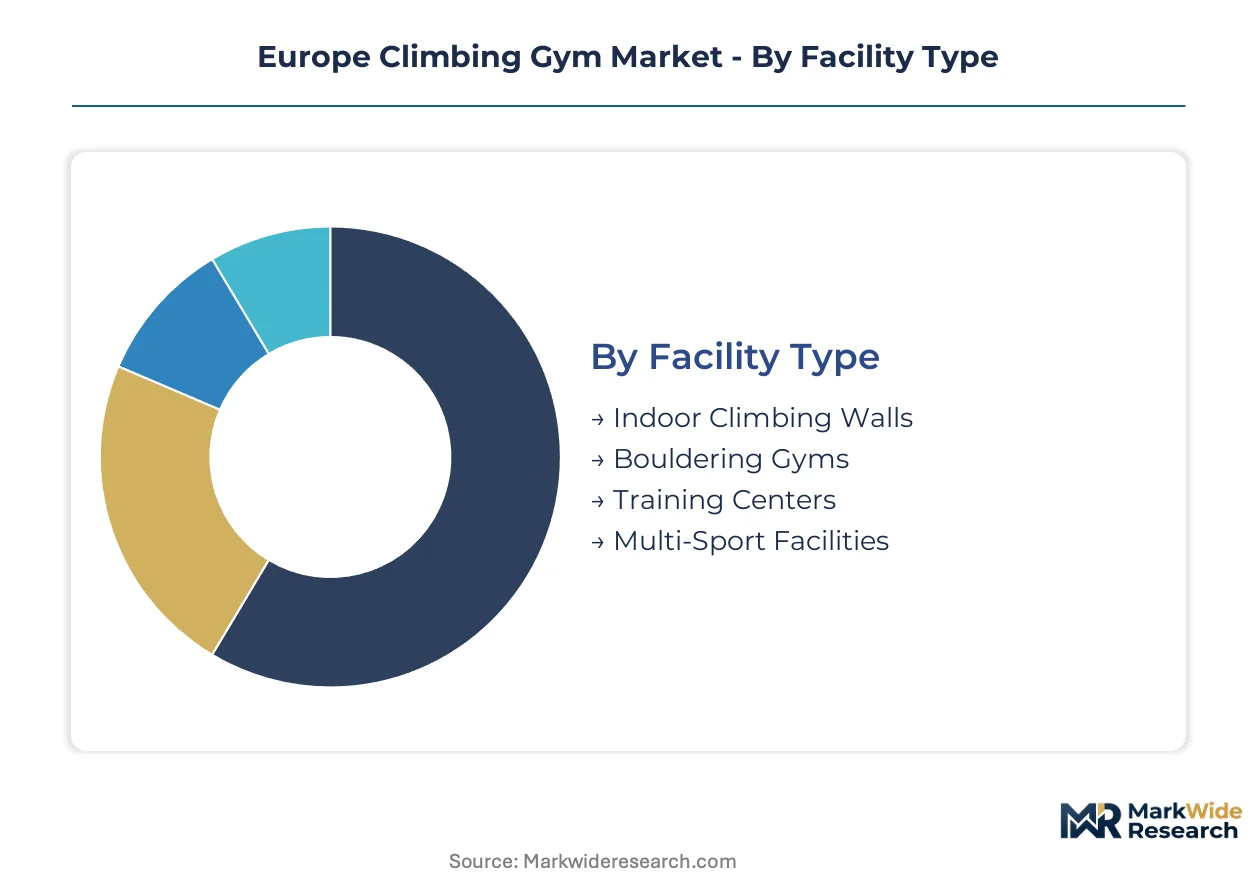
Facility operators across Europe configure their service mix around distinct usage patterns and spending behaviors. Segment boundaries increasingly blur as hybrid formats combine bouldering terrain with roped climbing walls to capture broader customer bases.
Facility Type:
Wall substrate suppliers concentrate manufacturing capacity in Germany and the Netherlands, creating supply bottlenecks for operators in Southern and Eastern Europe.
- Indoor Climbing Walls:Steel-framed plywood or concrete structures with resin-coated surfaces rated for dynamic load factors. German and French operators dominate installed capacity, driven by DAV Kletterhallen and Climb Up expansion programs.
- Bouldering Gyms:Compact formats with 4-5 meter ceiling heights and dense mat coverage. Lower structural steel requirements enable profitable warehouse conversions in Berlin, Paris, and Barcelona urban cores.
- Training Centers:Specialized facilities integrating campus boards, system walls, and adjustable angle terrain. Concentrated in Austria and Switzerland where alpine preparation drives year-round demand.
- Multi-Sport Facilities:Hybrid configurations combining climbing with yoga studios, fitness equipment, and co-working spaces. Emerging in Copenhagen and Stockholm corporate wellness corridors.
Bouldering gyms absorb the bulk of installed capacity; multi-sport facilities are expanding most quickly.
Customer Segment:
Spending concentration varies sharply by customer lifetime value and visit frequency, with corporate channels now commanding weekday morning blocks at discounted rates.
- Recreational Climbers:Social fitness seekers prioritizing community and accessibility over technical progression. This segment now drives membership growth across French and Belgian facilities, displacing traditional mountaineering club members.
- Professional Athletes:Elite competitors requiring standardized competition terrain and video analysis infrastructure. Concentrated in Innsbruck, Munich, and Grenoble where national training centers cluster.
- Schools:Institutional procurement through physical education curricula and extracurricular programs. Growing in Denmark and Sweden where climbing integrates into national sports education frameworks.
- Fitness Enthusiasts:Cross-training athletes from running, cycling, and swimming backgrounds seeking full-body conditioning. Captured through day-pass channels in tourist-heavy Portuguese and Spanish coastal markets.
Recreational climbers anchor revenue stability; fitness enthusiasts are climbing the fastest as crossover marketing penetrates traditional gym networks.
Climbing Type:
Route-setting labor allocation and hold inventory requirements diverge significantly across climbing disciplines, shaping operational cost structures.
- Sport Climbing:Roped ascents on 15-25 meter walls requiring belay infrastructure and certified supervision. Dominates German and Austrian facilities with strong alpine club heritage.
- Bouldering:Unroped movement on shorter walls with crash pad protection. Captures disproportionate new-build investment due to reduced liability infrastructure and lower staffing ratios.
- Traditional Climbing:Crack and corner terrain simulating outdoor rock features with removable protection practice. Niche presence in UK and Irish facilities serving outdoor transition preparation.
- Competition Climbing:Standardized IFSC-format walls with official hold specifications and timing systems. Concentrated in dedicated training centers and periodic event rentals across France, Slovenia, and Italy.
Bouldering claims the greatest share of new route-setting hours; competition climbing is gaining share fastest through Olympic exposure and youth academy pipelines.
Membership Model:
Revenue predictability and customer acquisition cost economics vary dramatically across pricing structures, with annual commitments preferred by established operators.
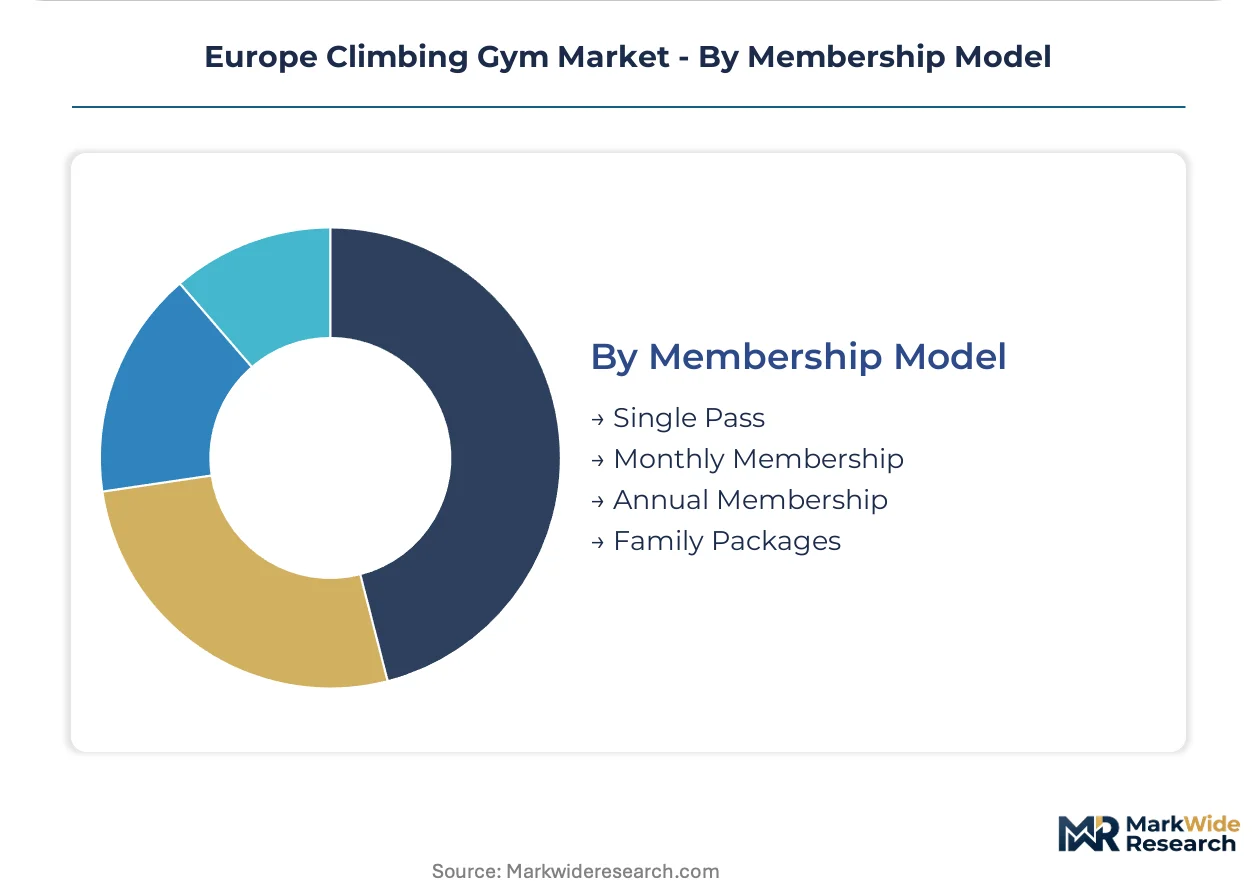
- Single Pass:Per-visit ticketing for tourists, trial users, and occasional visitors. Retains importance in Barcelona, Lisbon, and Nice where seasonal visitor flows sustain premium day-rate pricing.
- Monthly Membership:Recurring subscriptions with cancellation flexibility. Sustains dominant revenue share across the customer segment dimension, particularly in German and Dutch markets with high urban population density.
- Annual Membership:Prepaid twelve-month commitments with 15-25% discounts versus monthly rates. Preferred by committed climbers in Scandinavian markets with strong winter indoor training cultures.
- Family Packages:Multi-user accounts with guardian-minor pricing structures. Expanding in suburban Warsaw and Prague locations where family-oriented facility design differentiates from urban core competitors.
Monthly memberships absorb the bulk of contracted revenue; family packages are expanding most quickly as operators target underpenetrated suburban demographics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European climbing gym density with the highest per-capita facility concentration on the continent, driven by Bavaria's alpine heritage and the German Alpine Club's institutional presence.
Germany
Recreational climber expansion and corporate wellness procurement now dominate membership acquisition in Berlin and Hamburg facilities. CE marking under the EU Construction Products Regulation imposes third-party testing costs on wall manufacturers that smaller operators absorb with difficulty. The Rhine-Ruhr corridor hosts the densest cluster of bouldering conversions, where warehouse retrofits exploit lower ceiling height economics.
France
Social fitness seekers now drive growth across Lyon and Toulouse, displacing traditional mountaineering club members. National building codes impose additional fire resistance standards beyond EU baseline requirements. Climb Up anchors aggressive expansion into secondary French and Belgian cities, capturing whitespace before competitor entry.
Spain
Fitness enthusiasts from running and cycling backgrounds generate day-pass revenue in Barcelona and Valencia coastal markets. The EU Green Deal accelerates energy-efficient HVAC integration in new Madrid facilities. Andalusian cities show climbing gym density gaps relative to GDP per capita, offering first-mover positioning for franchise concepts.
Poland
Family-oriented facility design differentiates suburban Warsaw and Prague locations from urban core competitors. National accessibility standards layer onto CE marking requirements for wall installations. The Silesian metropolitan area concentrates training center development where alpine preparation culture meets disposable income growth.
Netherlands
Adjustable LED-integrated wall surfaces absorb route-setting labor hours in Amsterdam and Rotterdam premium facilities. The EU AI Act introduces compliance frameworks for automated visitor analytics platforms now deployed in Dutch corporate wellness corridors. Randstad urban cores command premium lease rates that constrain expansion into secondary districts.
Europe Climbing Gym Market Competitive Landscape
The competitive structure tilts toward heritage-backed membership loyalty and aggressive geographic expansion. Facility operators divide between alpine club-affiliated networks, private equity-backed roll-ups, and compact urban bouldering specialists. Consolidation pressure concentrates in Germany and France where scale economies matter most. Dominant competitive moves include strategic partnerships with hospitality booking platforms and portfolio diversification into adjacent yoga and co-working amenities.
Among heritage-anchored operators, DAV Kletterhallen exemplifies premium membership loyalty derived from German Alpine Club affiliation. Climb Up occupies a position representing aggressive geographic expansion into secondary French and Belgian markets. Boulders sits within the compact urban specialist tier, converting limited real estate footprints into profitable bouldering formats through reduced ceiling height requirements.
| Leading Market Players |
|---|
| The Font |
| DAV Kletterhallen |
| Climb Up |
| Falkors Climbing |
| Element |
| Indoorwall Centers |
| Boulders |
| Vertigo |
| Climbing Network |
| Others |
Supply & Pricing Matrix
Captive in-house route-setting capabilities anchor pricing power for established European operators, while outsourced wall manufacturing constrains margin flexibility for newer entrants. This integration choice separates facilities with proprietary setter teams and hold inventories from competitors dependent on third-party wall suppliers and freelance setting labor.
Pricing Analysis
Throughput-based membership anchoring governs facility economics across German and Dutch markets, with monthly recurring revenue models sustaining premium pricing against day-pass alternatives. Price differentiation rests on certification tier and geographic density, with DAV-affiliated facilities commanding brand premiums in Bavaria while urban bouldering specialists compete on accessibility. Cost compression in secondary French and Belgian markets is intensifying because Climb Up's expansion program floods whitespace with standardized formats. Corporate wellness buyers exhibit lowest price sensitivity through contracted morning blocks, while fitness enthusiast day-pass visitors in Southern European coastal cities drive highest price elasticity.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands concentrate wall substrate manufacturing, creating hub-and-spoke patterns that extend delivery timelines to Southern and Eastern European operators. Steel-framed plywood and fiberglass-resin surfaces draw from engineered timber suppliers in Central Europe and resin compound specialists in the Benelux region. Single-source vulnerability concentrates in German wall manufacturers serving DAV Kletterhallen's expansion program. Distribution runs through specialized sports infrastructure contractors rather than general construction channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where route-setting talent and hold inventory control represent the decisive upstream levers. Operators securing captive setter pipelines and proprietary hold libraries gain sustainable differentiation against asset-light competitors.
For Market Incumbents: Cement route-setting talent retention through equity participation structures and accredited training academy investments. Lock in multi-year hold supply agreements with German and Dutch substrate manufacturers before capacity constraints tighten. The scarcity of IFSC-certified setters relative to facility expansion rates threatens service quality consistency. Backward integration into proprietary LED wall surface technology separates premium Amsterdam and Rotterdam facilities from commodity competitors. For New Entrants and Emerging Players: Enter via Portuguese and Eastern European whitespace where climbing gym density lags GDP per capita indicators. Warsaw suburban family packages and Andalusian franchise-ready markets offer lowest competitive saturation. Exploit bouldering format economics to reduce capital requirements versus roped wall infrastructure. Partnership with hospitality booking platforms captures seasonal tourist flows in Barcelona and Lisbon coastal corridors. For Investors and Strategic Acquirers: Exit pathways concentrate in private equity roll-up platforms targeting fragmented German and French regional operators. Long-term viability hinges on corporate wellness channel penetration and AI-enabled route-setting automation adoption. Target acquisition archetypes include compact urban bouldering specialists with proven warehouse conversion playbooks. The signal to watch is EU AI Act compliance cost absorption capacity among automated analytics deployers.| Strategic Initiative | Industry Significance |
|---|---|
| Route-Setting Talent Acquisition | IFSC-certified setter pipelines differentiate service quality in Munich and Innsbruck training corridors. |
| LED Wall Surface Integration | Programmable light projections reduce labor hours while enabling dynamic difficulty calibration in premium facilities. |
| Corporate Wellness Channel Development | Contracted morning blocks at Copenhagen and Stockholm facilities secure predictable weekday revenue. |
| Portuguese and Eastern European Expansion | First-mover positioning in Warsaw and Lisbon captures whitespace before competitor saturation. |
| EU AI Act Compliance Investment | Algorithmic transparency documentation protects against audit risk in German and Austrian automated analytics deployments. |
Research Methodology
Independent corroboration across facility operator interviews, wall manufacturer technical assessments, and national sports federation data underwrites the qualitative findings. Primary fieldwork engaged climbing gym managing directors, route-setting team leads, wall substrate procurement managers, and corporate wellness benefits administrators across Germany, France, Spain, Poland, and the Netherlands. Secondary validation drew from EU Construction Products Regulation filings, national building code repositories, German Alpine Club membership statistics, and hospitality platform partnership disclosures. Bottom-up facility count triangulation against top-down addressable market sizing anchors the quantitative framework.
Rate-of-change decomposition across the projection horizon segments facility type, customer archetype, climbing discipline, and membership model dimensions. CAGRs derive from installed capacity expansion trajectories, membership penetration curves, and average revenue per member trends. Industry-specific inputs include CE marking compliance cost absorption rates, steel and engineered timber price indices, and route-setting labor availability metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU Green Deal retrofit timeline acceleration or steel price volatility spikes. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gyms and Fitness Centers
Global Pilates and Yoga Studios Market
Gyms and Fitness Centers
Health and Fitness Club Market
Gyms and Fitness Centers
Southeast Asia Health and Fitness Club Market
Gyms and Fitness Centers
Saudi Arabia Health and Fitness Club Market
Gyms and Fitness Centers
South America Health and Fitness Club Market
Gyms and Fitness Centers
Europe Pilates & Yoga Studios Market
Gyms and Fitness Centers
Global Climbing Gym Market
Gyms and Fitness Centers
South Korea Health and Fitness Club Market
Gyms and Fitness Centers
Boutique Fitness Studio Market
Gyms and Fitness Centers
Fitness and Recreational Sports Centers Market