
 Europe Kickboxing Equipment Market | 2026-2036
Europe Kickboxing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kickboxing Equipment Market Foresight
Smart textile integration with embedded impact sensors is reconfiguring how protective gear monitors athlete biomechanics during training. Hayabusa Fightwear leverages proprietary foam layering systems to differentiate its glove architecture from commodity alternatives. RDX sustains manufacturing scale through vertically integrated production facilities in South Asia that supply European distribution hubs. Venum anchors brand strength through exclusive partnerships with premier mixed martial arts promotions that cross-promote kickboxing equipment lines.
Kickboxing equipment encompasses purpose-built protective and training apparatus engineered to absorb repetitive high-impact strikes while permitting full range of motion. Gloves typically integrate multi-density foam cores with leather or synthetic outer shells rated for force dissipation exceeding standard boxing specifications, serving both competitive fighters and conditioning-focused fitness participants. Gloves and shin guards capture the dominant margin pools due to mandatory replacement cycles driven by foam degradation from repeated impacts. Punch bags represent the fastest-growing product category as boutique fitness studios expand heavy bag programming for non-competitive members. Specialty stores and online retailers split channel control, with the former offering custom fitting services that reduce return rates for headgear and gloves.
REACH chemical compliance and CE marking requirements under the EU's Personal Protective Equipment Regulation shape material selection and testing protocols for all equipment sold within member states. ECHA substance restrictions on certain phthalates and flame retardants directly impact synthetic leather formulations used by manufacturers targeting European consumers. National sports federations in Germany, France, and the Netherlands impose additional equipment certification standards for sanctioned competition that exceed baseline EU requirements. Stakeholders must monitor evolving biometric data governance under the EU AI Act as sensor-embedded gear generates athlete performance data subject to emerging algorithmic accountability rules.
Market Dynamics
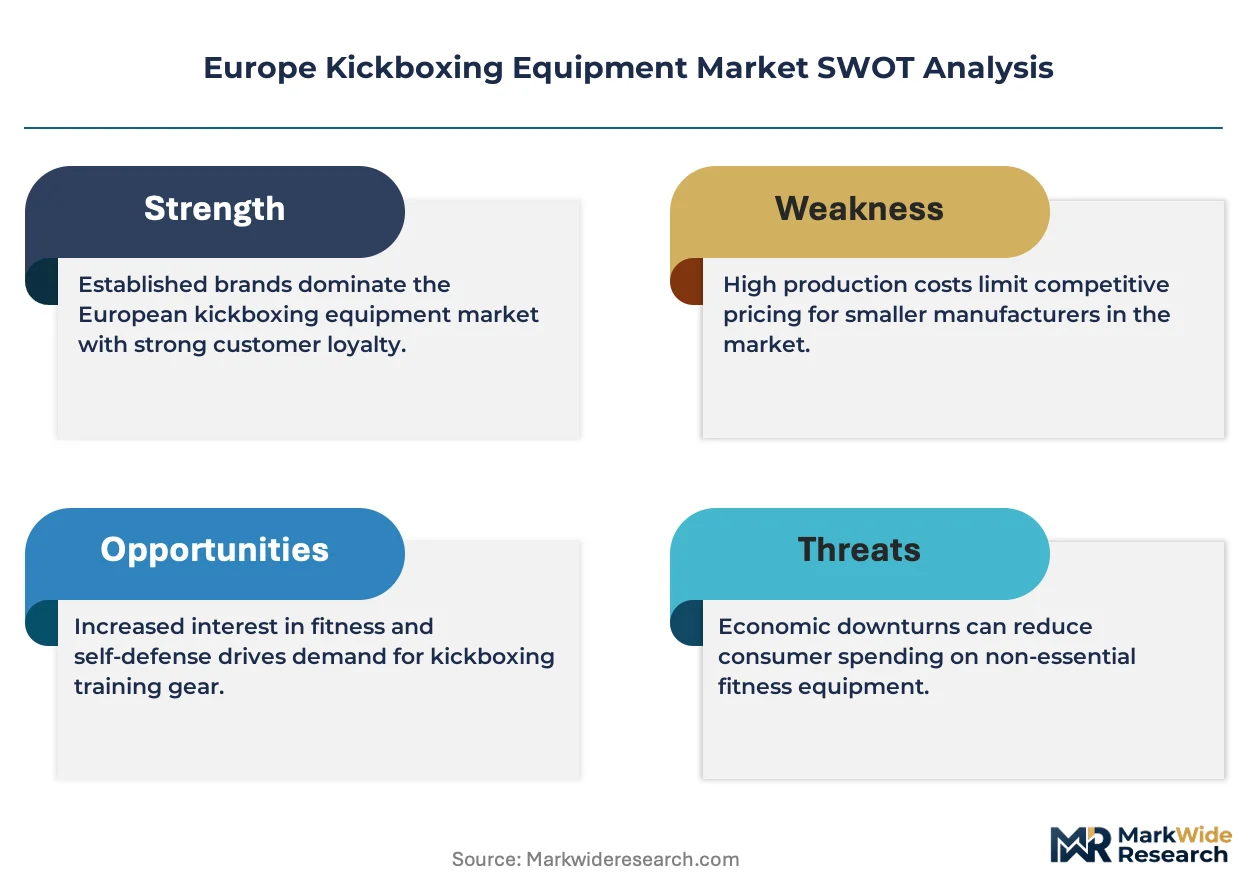
The EU Green Deal's chemical safety protocols are forcing manufacturers to reformulate synthetic leather and adhesive systems, compressing margins for suppliers unable to pivot production lines toward water-based chemistries and recycled polymer feedstocks.
Growth Catalysts
- Fitness Studio Expansion:Boutique gym chains across Germany and France are adding heavy bag programming for non-competitive members, expanding addressable demand beyond traditional combat sports practitioners.
- REACH Compliance Differentiation:Manufacturers achieving ECHA substance restrictions certification command preferential shelf placement at specialty retailers serving liability-conscious institutional buyers.
- Smart Textile Integration:Embedded impact sensors are enabling biomechanical monitoring during training sessions, creating upgrade cycles for protective gear among data-driven athletes.
Market Restraints
- Petrochemical Feedstock Volatility:Synthetic leather production depends on polyurethane precursor supply chains concentrated in Northeast Asia, exposing European manufacturers to input cost swings.
- CE Marking Burden:Personal Protective Equipment Regulation testing protocols add twelve to eighteen months to product development timelines for new entrants.
- Substitution by Bodyweight Training:Calisthenics and functional fitness modalities require no equipment investment, capturing budget-conscious recreational exercisers.
Strategic Opportunities
- Underpenetrated Southern Europe:Spain and Italy exhibit combat sports participation rates below northern European benchmarks, representing expansion terrain for education-focused distribution.
- EU AI Act Tailwind:Algorithmic accountability frameworks for biometric data create first-mover advantage for manufacturers establishing compliant data governance in sensor-embedded gear.
- Direct-to-Consumer Channels:Custom fitting algorithms and virtual try-on technologies are compressing return rates for headgear and gloves previously requiring physical retail presence.
Industry Challenges
- Multi-Jurisdiction Certification Complexity:German, French, and Dutch national sports federations impose equipment standards exceeding baseline EU requirements, fragmenting compliance engineering resources.
- Foam Chemistry Talent Scarcity:Formulation expertise for multi-density impact absorption cores resides with a narrow cohort of polymer scientists, constraining R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kickboxing Equipment Market |
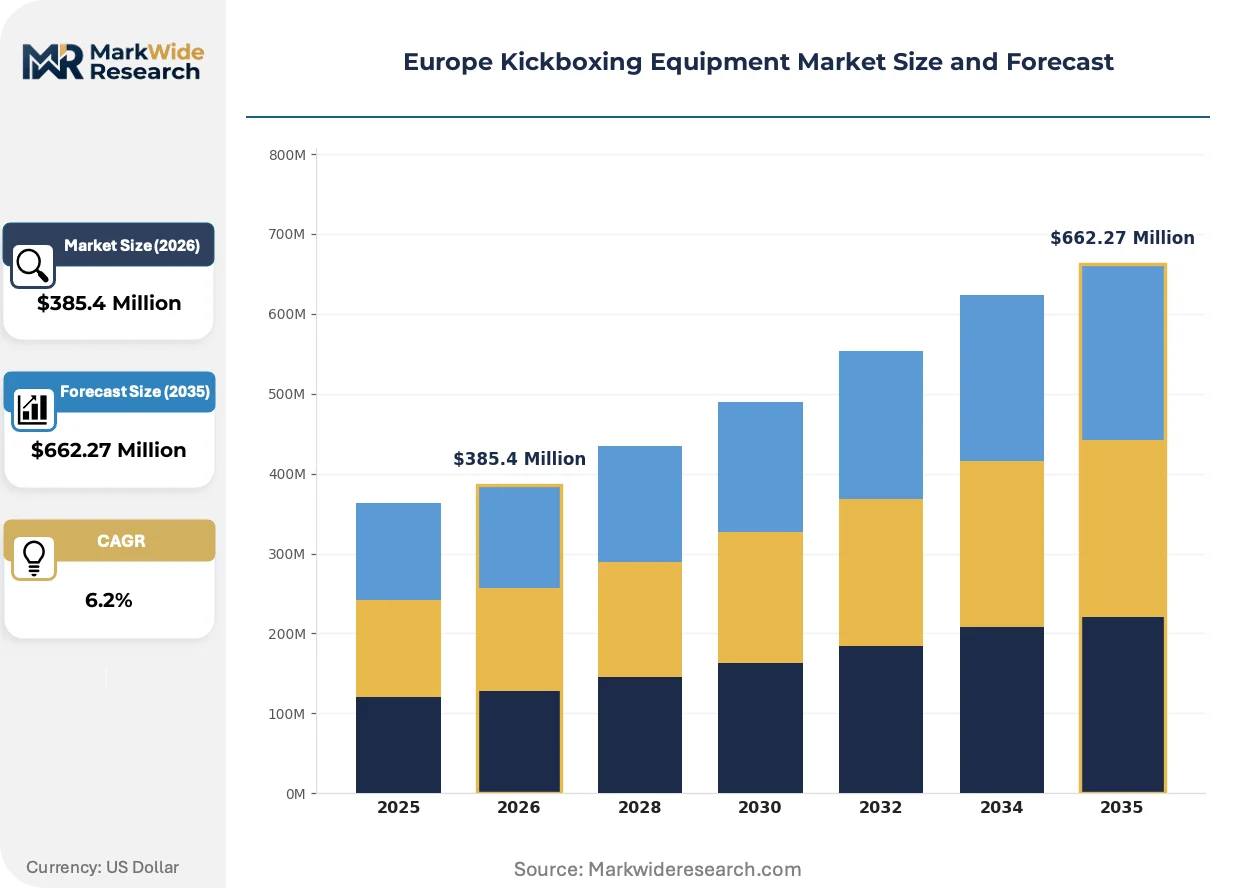
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Shin Guards, Punch Bags, Headgear End User: Fitness Enthusiasts, Professional Fighters, Gyms, Home Users Material: Leather, Synthetic, Cotton, Foam Distribution Channel: Online Retailers, Specialty Stores, Supermarkets, Others |
| Companies Covered | Hayabusa Fightwear, RDX, Everlast Worldwide, Fairtex, Century LLC, Venum, Title Boxing, Twins Special, Adidas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kickboxing Equipment Market Shifts & Advancements
Material science breakthroughs and regulatory compression are simultaneously reconfiguring product architecture and supply chain geography across European kickboxing equipment manufacturing.
Impact-sensing smart textiles embedded in glove and shin guard architectures are rendering obsolete passive protective gear that cannot quantify strike force or track cumulative trauma exposure. Competitive amateur fighters and high-frequency gym members in the United Kingdom are adopting these systems at accelerating rates. The data feedback loop is compressing replacement cycles as athletes upgrade to capture performance metrics.
REACH chemical restrictions on phthalates and specific flame retardants are forcing synthetic leather suppliers to validate alternative plasticizer chemistries through ECHA notification procedures. Reformulation costs are disproportionately burdening mid-tier manufacturers lacking dedicated regulatory affairs capacity. Premium product lines targeting sanctioned competition are absorbing compliance investments fastest.
Specialty retail foot traffic is fragmenting as boutique fitness studios negotiate direct equipment procurement relationships with manufacturers, bypassing traditional distribution markups. Studio owners in France and the Netherlands are consolidating purchase volume across multi-location chains to extract volume pricing previously reserved for national sporting goods retailers. The channel shift is most visible in punch bag and glove categories where fit standardization reduces customization requirements.
Europe Kickboxing Equipment Market Segmentation
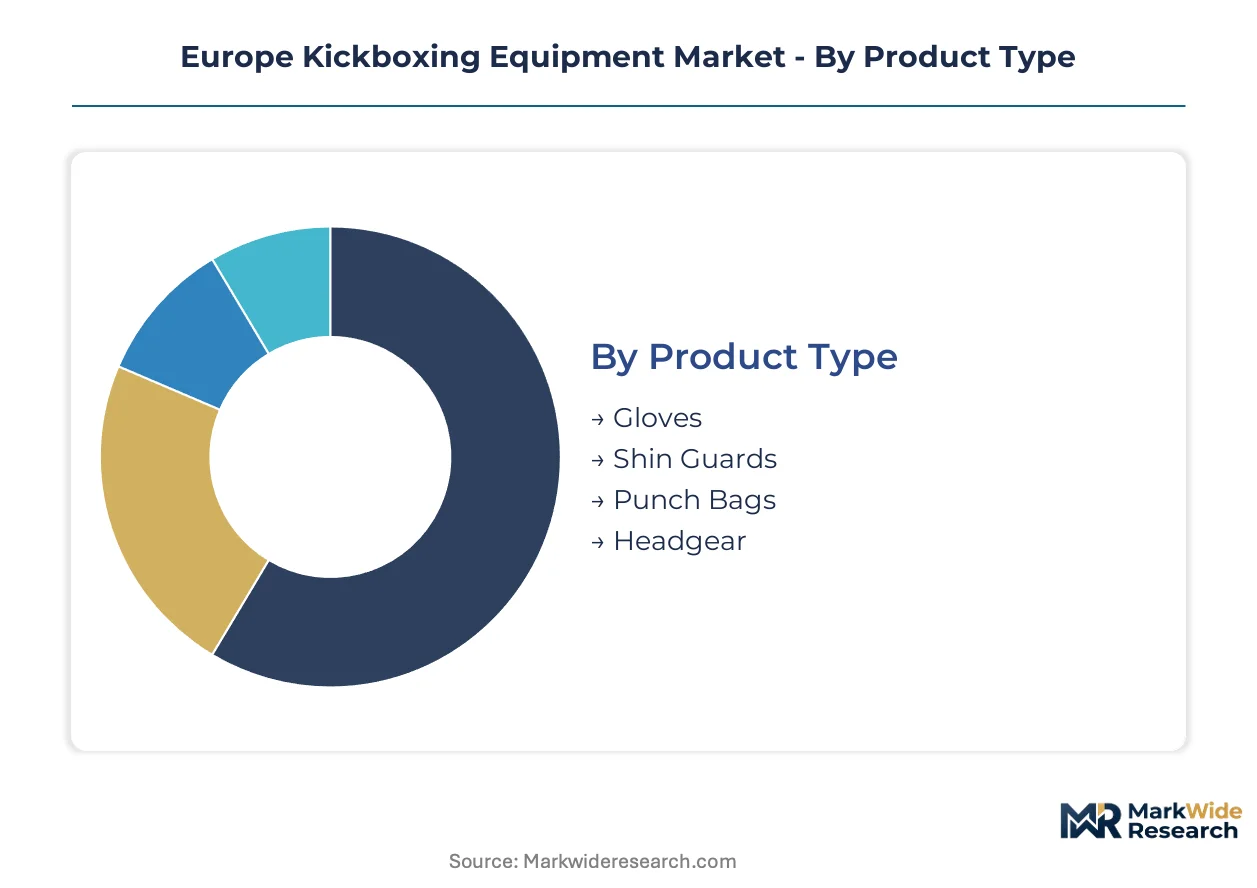
Segmentation in European kickboxing equipment reveals how protective gear specifications diverge across competitive intensity, material chemistry constraints under REACH, and channel economics. Manufacturers must architect distinct product lines for sanctioned competition versus boutique fitness studio programming.
Product Type:
Cost tier stratification separates mandatory protective equipment from discretionary training apparatus, with replacement cycle economics driving margin concentration differently across each tier.
- Gloves:Multi-density foam cores with leather or synthetic shells rated for force dissipation exceeding standard boxing specifications. Demand concentrates among commercial gym chains in Germany and France where heavy bag programming requires institutional volume procurement.
- Shin Guards:Anatomically contoured shells with impact-absorbing padding engineered for repetitive striking without mobility restriction. Professional fighters and high-frequency gym members in the United Kingdom drive premium tier adoption with shorter replacement intervals.
- Punch Bags:Suspended and freestanding striking targets with fill systems calibrated for resistance feedback. Boutique fitness studios across the Netherlands are expanding heavy bag programming for non-competitive members.
- Headgear:Protective cranial padding with face bar or open-face configurations for sparring safety. Specialty retailers in France emphasize custom fitting services that reduce return rates for this category.
Gloves hold installed capacity. Punch bags are rotating up the share rankings.
End User:
Application intensity creates divergent performance requirements, from casual fitness participants prioritizing comfort to competitive athletes demanding certified protective ratings.
- Fitness Enthusiasts:Recreational practitioners engaging kickboxing for cardiovascular conditioning without competitive aspirations. Boutique studio chains in Germany and France drive equipment procurement through direct manufacturer relationships.
- Professional Fighters:Sanctioned competitors requiring gear meeting national federation certification standards. German, French, and Dutch sports federations impose equipment standards exceeding baseline EU requirements for this segment.
- Gyms:Commercial fitness facilities and combat sports academies purchasing institutional volumes with durability specifications. Volume pricing consolidation across multi-location chains is compressing traditional distribution markups.
- Home Users:Individual consumers equipping personal training spaces with space-efficient apparatus. Online retailers capture this segment through virtual fitting technologies and direct-to-consumer logistics.
Professional fighters hold installed capacity. Fitness enthusiasts are rotating up the share rankings.
Material:
Supply concentration in polymer feedstock chemistry is forcing reformulation investments as ECHA substance restrictions reshape synthetic leather and adhesive formulations.
- Leather:Full-grain and split-hide constructions offering durability and breathability for extended training sessions. REACH compliance differentiation commands preferential shelf placement at specialty retailers serving liability-conscious institutional buyers.
- Synthetic:Polyurethane and microfiber alternatives engineered for moisture resistance and consistent performance characteristics. ECHA restrictions on phthalates and specific flame retardants are forcing suppliers to validate alternative plasticizer chemistries.
- Cotton:Natural fiber linings and wraps providing moisture management and skin contact comfort. Home users in southern European markets show preference for breathable natural materials.
- Foam:Multi-density polymer cores delivering calibrated impact absorption across strike zones. Formulation expertise for these cores resides with a narrow cohort of polymer scientists, constraining R&D velocity.
Synthetic materials hold installed capacity. Foam innovations are rotating up the share rankings.
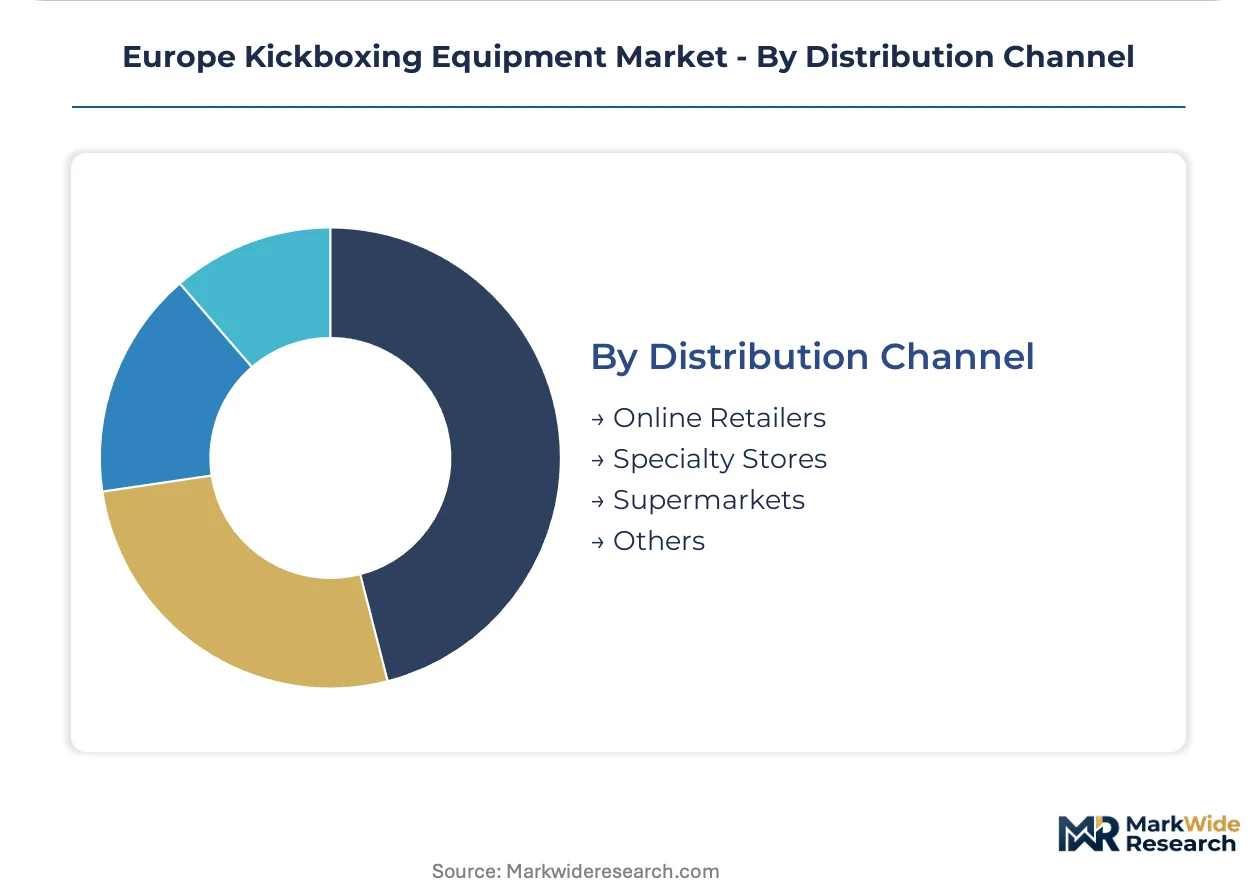
Distribution Channel:
Channel economics fragment as procurement authority shifts from national retailers toward consolidated studio chains and algorithm-driven direct-to-consumer platforms.
- Online Retailers:E-commerce platforms leveraging custom fitting algorithms and virtual try-on technologies. Return rate compression for headgear and gloves previously requiring physical retail presence is accelerating channel migration.
- Specialty Stores:Dedicated combat sports retailers offering expert fitting services and equipment certification guidance. These outlets maintain relevance through liability-conscious institutional buyer relationships.
- Supermarkets:Mass-market retail channels stocking entry-level equipment for casual fitness participants. Limited product depth restricts penetration beyond basic glove and wrap categories.
- Others:Direct procurement relationships, secondhand markets, and promotional distribution through combat sports events. Boutique studio chains in France and the Netherlands consolidate purchase volume to extract manufacturer-direct pricing.
Specialty stores hold installed capacity. Online retailers are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export protective gear to boutique fitness chains across France and the Netherlands, establishing a north-south equipment flow corridor that concentrates procurement authority in Rhine-Ruhr distribution hubs.
Germany
Commercial gym chains in Berlin and Hamburg drive institutional volume procurement of gloves and heavy bags for heavy bag programming. The German Sports Federation imposes equipment certification standards for sanctioned competition that exceed baseline EU Personal Protective Equipment Regulation requirements. Manufacturing clusters in North Rhine-Westphalia host formulation facilities developing REACH-compliant synthetic leather alternatives.
France
Boutique fitness studios in Paris and Lyon negotiate direct manufacturer relationships, consolidating purchase volume across multi-location chains. ANSM chemical safety protocols align with ECHA substance restrictions on phthalates in synthetic leather formulations. Specialty retailers in Marseille maintain relevance through custom fitting services that reduce return rates for headgear and gloves.
United Kingdom
High-frequency gym members in London and Manchester adopt smart textile-embedded protective gear for biomechanical monitoring during training sessions. The UKCA marking framework maintains regulatory continuity with CE marking requirements post-Brexit. Competitive amateur fighters in Birmingham drive premium-tier replacement cycles for sensor-equipped shin guards and gloves.
Netherlands
Boutique fitness studios in Amsterdam and Rotterdam expand heavy bag programming for non-competitive members, accelerating punch bag category growth. Dutch sports federation certification requirements for sanctioned competition create multi-jurisdiction compliance complexity for equipment suppliers. Distribution hubs in Eindhoven channel German-manufactured gear to Benelux studio chains.
Spain
Combat sports participation rates in Madrid and Barcelona trail northern European benchmarks, representing expansion terrain for education-focused distribution strategies. Spanish consumer preference for breathable natural materials sustains cotton-lining demand in entry-level glove segments. Regional distributors in Valencia test direct-to-consumer virtual fitting technologies to compress return rates without physical retail presence.
Europe Kickboxing Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a fragmented vendor base where scale advantages concentrate in vertically integrated supply chains and regulatory compliance capacity. Premium-tier differentiation depends on REACH certification achievement and smart textile integration rather than price positioning alone. Two strategic archetypes dominate: vertically integrated manufacturers with captive South Asian production facilities, and brand-anchored specialists leveraging exclusive combat sports promotion partnerships. Competitive moves center on direct-to-consumer channel expansion and formulation investments for water-based adhesive systems.
Within the brand-anchored specialist tier, Hayabusa Fightwear and Venum exemplify positioning built through proprietary differentiation and promotion partnerships respectively. RDX occupies a position representing vertically integrated manufacturing scale through South Asian production facilities supplying European distribution hubs. Everlast Worldwide and Title Boxing sit within the heritage-brand archetype leveraging decades of institutional recognition across commercial gym procurement channels. These three groupings—specialist innovators, integrated manufacturers, and established heritage labels—capture distinct margin pools based on certification depth, production control, and brand equity durability.
| Leading Market Players |
|---|
| Hayabusa Fightwear |
| RDX |
| Everlast Worldwide |
| Fairtex |
| Century LLC |
| Venum |
| Title Boxing |
| Twins Special |
| Adidas |
| Others |
Supply & Pricing Matrix
North Rhine-Westphalia's manufacturing clusters concentrate REACH-compliant synthetic leather formulation capacity, translating upstream chemical innovation into pricing power for premium-tier equipment suppliers serving liability-conscious institutional buyers across Germany and France.
Pricing Analysis
Cost-plus contracts with polyurethane precursor indexation dominate procurement between European distributors and Northeast Asian feedstock suppliers. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified competition-grade gear from fitness-studio bulk orders and entry-level home-use equipment. Pricing pressure stems from ECHA-mandated reformulation costs disproportionately burdening mid-tier manufacturers lacking dedicated regulatory affairs capacity. Boutique fitness studios exhibit highest price sensitivity through consolidated multi-location volume negotiations, while professional fighters demonstrate lowest sensitivity due to mandatory federation certification requirements.
Supply Chain Analysis
Tariff exposure between South Asian production hubs and European distribution centers dominates supply chain risk assessment for vertically integrated manufacturers. Raw material dependencies center on polyurethane precursors from Northeast Asia, multi-density foam cores requiring specialized polymer chemistry expertise, and REACH-compliant adhesive systems transitioning to water-based formulations. Single-source vulnerability concentrates in foam core formulation capabilities residing with a narrow cohort of polymer scientists. Distribution runs through Rhine-Ruhr logistics hubs channeling German-manufactured gear to Benelux and French boutique studio chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe Kickboxing Equipment Market dynamics reflect cyclical recovery patterns as fitness studio expansion following pandemic disruptions drives equipment replacement and upgrade cycles across Germany and France.
For Market Incumbents: Entrench competitive position through captive control of REACH-compliant synthetic leather formulation capacity in North Rhine-Westphalia clusters and exclusive data governance frameworks for sensor-embedded gear under EU AI Act requirements. Defend against direct-to-consumer channel displacement by embedding custom fitting algorithms into specialty retail partnerships that replicate virtual try-on convenience. For New Entrants and Emerging Players: Pursue white-space expansion in Spain and Italy where combat sports participation rates trail northern European benchmarks and education-focused distribution strategies remain underdeveloped. Target southern European home-user segments through breathable natural material positioning and direct-to-consumer virtual fitting technologies that compress return rates without physical retail presence. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with established REACH certification depth and backward integration into South Asian production facilities. Long-term viability hinges on regulatory compliance capacity rather than brand equity alone. Monitor ECHA substance restriction expansion timelines as the critical inflection signal for reformulation cost acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA notification procedures validate alternative plasticizer chemistries before competitors achieve certification depth. |
| Smart Textile Sensor Integration | Embedded impact sensors enable biomechanical monitoring that compresses replacement cycles among data-driven athletes. |
| Direct-to-Consumer Channel Buildout | Custom fitting algorithms replicate specialty retail expertise while capturing margin previously allocated to distribution intermediaries. |
| Southern European Distribution Expansion | Education-focused strategies penetrate Spain and Italy where combat sports participation trails German benchmarks. |
| Water-Based Adhesive System Transition | EU Green Deal chemical safety protocols force manufacturing pivot that eliminates competitors with petrochemical-dependent production lines. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with boutique fitness studio owners, commercial gym procurement managers, polymer formulation scientists, specialty retail buyers, and national sports federation equipment certification officers. Secondary validation drew from ECHA substance restriction databases, EU Personal Protective Equipment Regulation filings, German Sports Federation certification standards, customs trade data for polyurethane precursor flows, and SEC disclosures from publicly traded sporting goods manufacturers. Bottom-up equipment shipment data triangulated against top-down fitness industry participation surveys.
Calibration against historical replacement cycle patterns and regulatory implementation timelines anchored growth projections across the analysis window. Segmentation modeling incorporated product type tier, end-user intensity, material chemistry compliance grade, and distribution channel migration patterns. CAGRs derived from equipment volume elasticities relative to fitness studio expansion rates and REACH compliance cost pass-through coefficients. Industry-specific inputs included foam degradation replacement intervals and smart textile adoption curves among competitive amateur fighters.
Sensitivities concentrate around ECHA substance restriction expansion scope, boutique fitness studio expansion sustainability, and polyurethane precursor price volatility. Forecasts reflect documented assumptions regarding regulatory implementation timelines and fitness industry cyclical patterns. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Sports Sunglasses Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Cleat Market
Sports Equipment
United States Running Gear Market
Sports Equipment
Wetsuits Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Diving Board Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Global Darts Market
Sports Equipment
Shuttlecock Market
Sports Equipment
Football Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Mixed Martial Arts Equipment Market