
 Mini Balance Beam Market | 2026-2036
Mini Balance Beam Market Size, Share, and Industry Trends Forecast 2026-2036
Mini Balance Beam Market Analytics
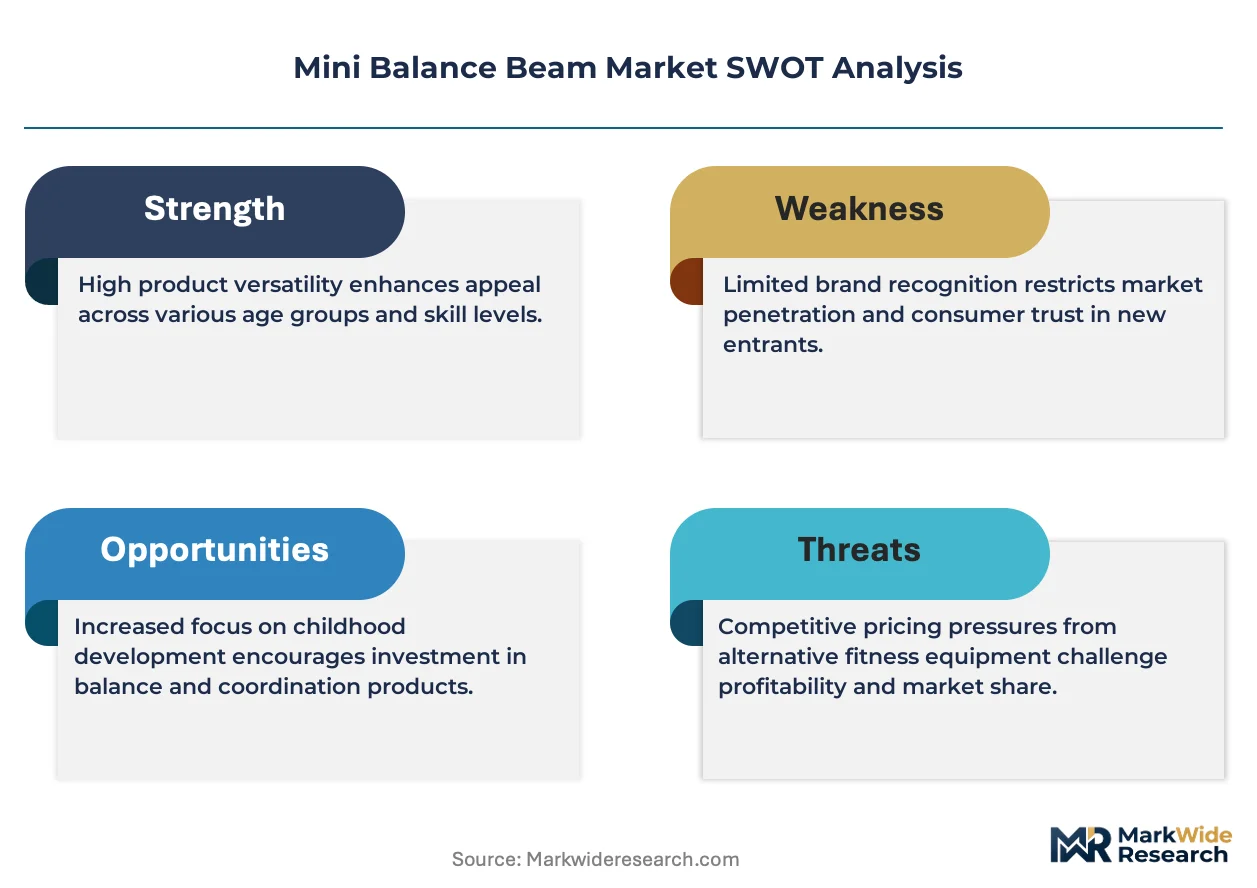
The EU Green Deal is broadening material sourcing requirements for youth athletic equipment across European institutional buyers. Janssen Fritsen leverages its Benelux manufacturing base to supply certified sustainable wood beam lines. Gibson Athletic anchors North American demand through direct relationships with collegiate gymnastics programs. American Athletic (AAI) competes on Olympic-grade specification adherence for elite training centers.
A mini balance beam is a scaled-down apparatus, typically 2.4 to 3.0 meters in length with a working surface width of 10 centimeters, engineered from laminated hardwood cores with suede or synthetic competition wraps to replicate full-size apparatus dynamics for skill acquisition and conditioning. The folding and portable type segments attract the fastest volume growth as home-use and mobile coaching applications expand, while wood material configurations retain the dominant margin pool due to competitive federation approval requirements. Foam-based constructions serve entry-level children and recreational schools where cost thresholds override specification stringency.
ISO 59020 traceability standards, the U.S. Consumer Product Safety Commission guidelines, and Germany's DIN 7909 sports equipment safety framework collectively elevate compliance costs and barrier thresholds for new entrants. China's GB standards for juvenile sports apparatus add a third certification layer for suppliers targeting Asia-Pacific distribution channels. Stakeholders must monitor evolving school district procurement mandates and federation equipment approval cycles to align production timelines with institutional buying windows.
Market Dynamics
Institutional procurement mandates for certified youth athletic equipment are compressing supplier qualification timelines while fragmenting order volumes across multiple compliance frameworks.
Growth Catalysts
- ISO 59020 traceability standards:European institutional buyers now require documented material sourcing for all juvenile sports apparatus, redirecting procurement toward certified manufacturers.
- China's GB standards expansion:Municipal governments in Shanghai and Guangzhou mandate certified equipment for newly constructed youth athletic facilities, creating concentrated demand pull.
- Folding beam portability:Mobile coaching applications and home-use training programs accelerate volume growth in collapsible apparatus configurations.
Market Restraints
- Laminated hardwood supply concentration:Baltic birch core material sourcing clusters in Nordic and Baltic states, exposing producers to regional logistics disruptions.
- Multi-jurisdiction certification stacking:Suppliers targeting transatlantic distribution must simultaneously satisfy U.S. Consumer Product Safety Commission guidelines, Germany's DIN 7909 framework, and China's GB standards.
- Foam-based substitution at entry level:Recreational schools and parent buyers increasingly accept lower-specification foam constructions where competitive federation approval is not required.
Strategic Opportunities
- EU Green Deal material sourcing:Sustainable wood certification creates preference windows for Benelux-based manufacturers with established chain-of-custody documentation.
- Collegiate program direct contracting:North American universities bypass traditional distribution to negotiate specification-compliant bulk orders directly with producers.
- Digital training platform integration:Beam manufacturers embedding sensor technology for remote coaching feedback open subscription revenue streams alongside hardware sales.
Industry Challenges
- Federation equipment approval cycle compression:National gymnastics federations accelerate specification updates, forcing producers to retool production lines mid-contract.
- Skilled laminating technician scarcity:Precision hardwood core fabrication requires specialized craft labor pools concentrated in traditional furniture-producing regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mini Balance Beam Market |
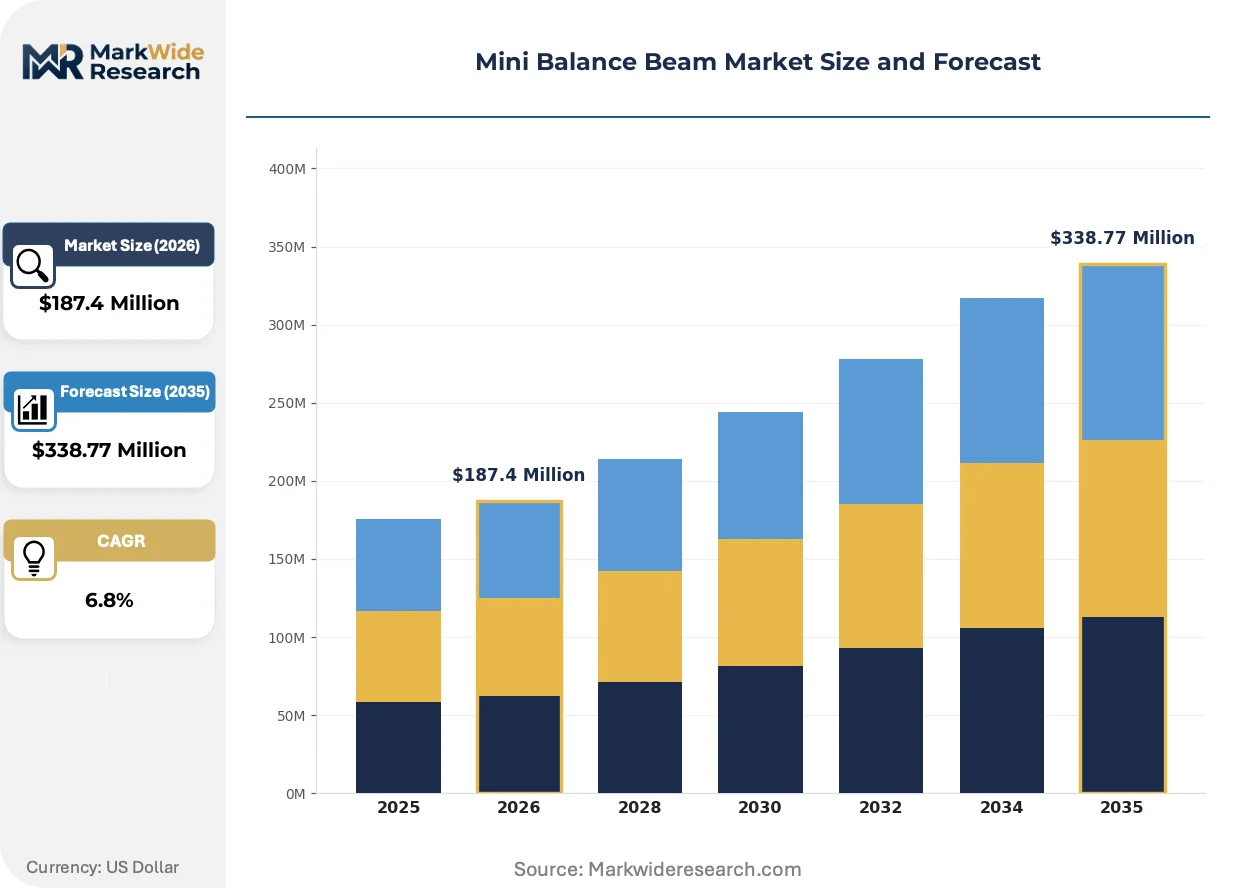
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Standard, Adjustable, Folding, Portable Material: Wood, Foam, PVC, Metal End User: Children, Trainers, Schools, Gyms Feature: Non-Slip, Lightweight, Adjustable Height, Compact |
| Companies Covered | American Athletic (AAI), Janssen Fritsen, Cramer Product, Acromat, Active Wrap, Black Diamond, Champions Sports, DGS, Gibson Athletic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mini Balance Beam Market Evolving Landscape
Material science advances and procurement digitization are restructuring how specification-compliant apparatus reaches end-users, with sustainability documentation becoming a competitive filter rather than a value-add.
Sensor-enabled beam surfaces are converging with cloud-based coaching platforms to capture real-time balance metrics and transmit skill progression data to remote instructors. Collegiate programs and elite training centers in the United States pilot these integrated systems during off-site conditioning periods. This convergence is compressing the traditional separation between hardware procurement and digital service subscriptions.
Germany's DIN 7909 sports equipment safety framework now mandates third-party structural testing for all institutional purchases, elevating documentation burdens for imported apparatus. Domestic producers leverage proximity to accredited testing laboratories to shorten certification timelines. Municipal buyers in Bavaria and North Rhine-Westphalia increasingly specify DIN-compliant sourcing in public tender requirements.
Direct institutional contracting is displacing traditional distributor relationships as school districts and university athletic departments consolidate vendor lists around multi-year framework agreements. Equipment specification committees now negotiate directly with manufacturers, unbundling installation and maintenance services previously bundled through regional dealers. This pattern concentrates most visibly in competitive gymnastics programs across Texas, California, and Florida.
Mini Balance Beam Market Segmentation
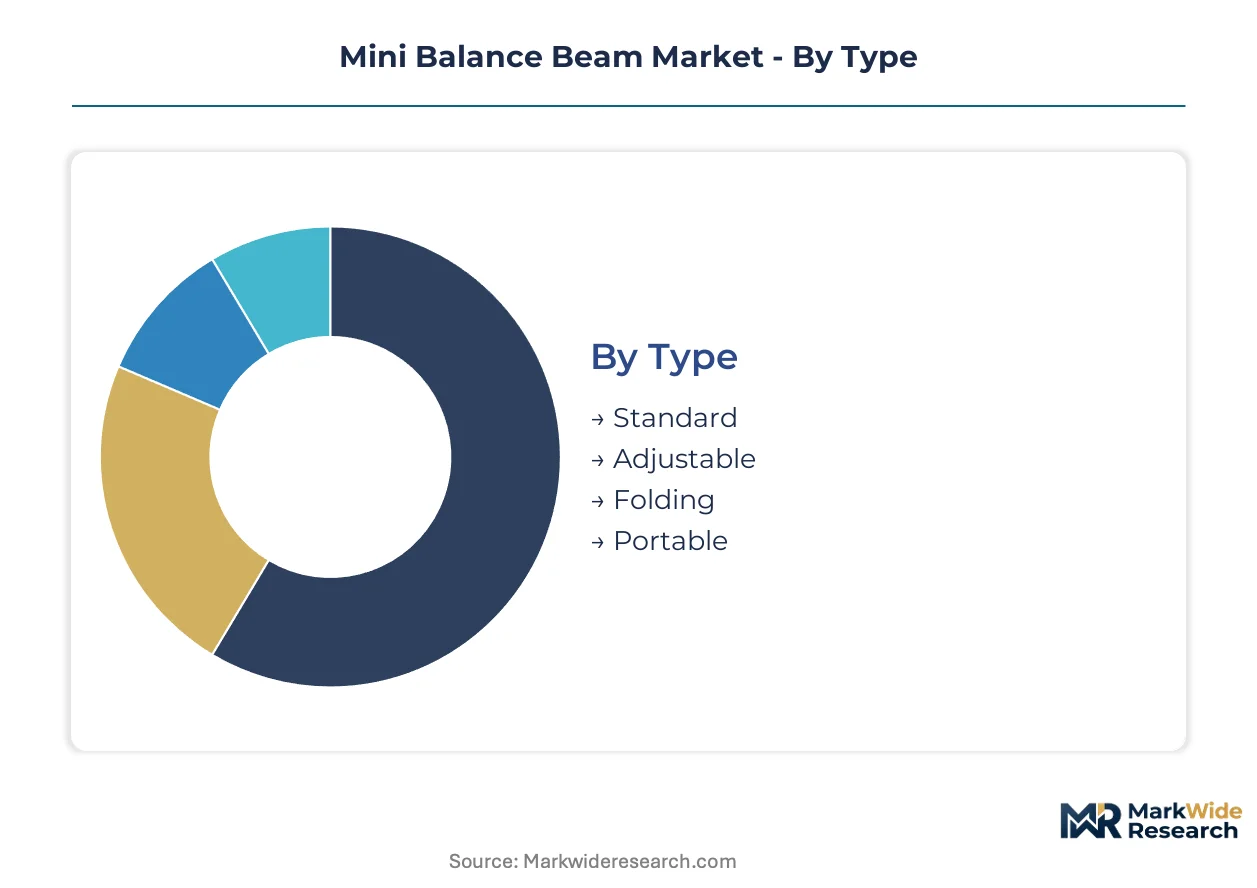
Procurement patterns across the mini balance beam market diverge sharply by institutional versus consumer use cases, with certification requirements and portability needs driving distinct specification tiers. Manufacturers must align production configurations with these segment-specific compliance and performance thresholds to capture volume.
Type:
Capital intensity varies substantially across type configurations, with fixed installations demanding substantial upfront tooling for federation-grade specification adherence while portable variants require lighter manufacturing footprints.
- Standard:Fixed-length laminated hardwood cores with competition-grade suede wraps dominate institutional procurement in competitive gymnastics programs across Texas and California. School districts and university athletic departments specify these configurations for permanent training installations where DIN 7909 or GB standard compliance is mandatory.
- Folding:Collapsible hinge mechanisms with reinforced joint hardware serve mobile coaching applications and home-use training programs. Municipal governments in Shanghai and Guangzhou specify folding configurations for multi-purpose youth athletic facilities where space flexibility is prioritized.
- Adjustable:Telescoping leg assemblies with locking pin mechanisms accommodate progressive skill development across age cohorts.
- Portable:Detachable base systems with carrying cases target parent buyers and recreational schools where rapid deployment overrides specification stringency.
Most installed capacity flows through Standard configurations. Expansion is steepest in Folding.
Material:
Margin concentration tracks raw material certification tiers, with sustainably sourced hardwood commanding premium positioning against synthetic substitutes.
- Wood:Laminated Baltic birch cores with chain-of-custody documentation satisfy EU Green Deal procurement mandates and federation approval requirements. Benelux-based manufacturers leverage proximity to certified forestry operations to supply collegiate programs in the United States and institutional buyers in Bavaria.
- Foam:EVA and polyurethane constructions serve entry-level children and recreational schools where cost thresholds override competitive specification needs. Parent buyers in Florida and parent-funded programs accept these configurations where federation approval is not required.
- PVC:Vinyl-wrapped composite cores offer moisture resistance for humid climate installations.
- Metal:Aluminum frame systems with synthetic surfaces target high-traffic gym environments requiring durability.
Wood captures the dominant margin pool. Foam is gaining share fastest in volume terms.
End User:
Customer-type segmentation reveals divergent purchasing authority structures, with institutional committees negotiating multi-year frameworks against individual consumer transactions.
- Schools:Public district procurement committees in Germany and municipal education bureaus in China mandate certified equipment with third-party testing documentation. These buyers consolidate vendor lists around framework agreements that bundle installation and maintenance services.
- Gyms:Private training centers and collegiate athletic departments specify Olympic-grade apparatus with sensor-enabled surfaces for remote coaching integration. Elite training centers in the United States pilot subscription-integrated hardware configurations.
- Children:Parent-directed purchases prioritize safety labeling and compact storage for residential use.
- Trainers:Independent coaching professionals value portability and rapid setup for mobile lesson delivery.
Schools represent the largest committed order flow. Gyms show the steepest specification upgrade trajectory.
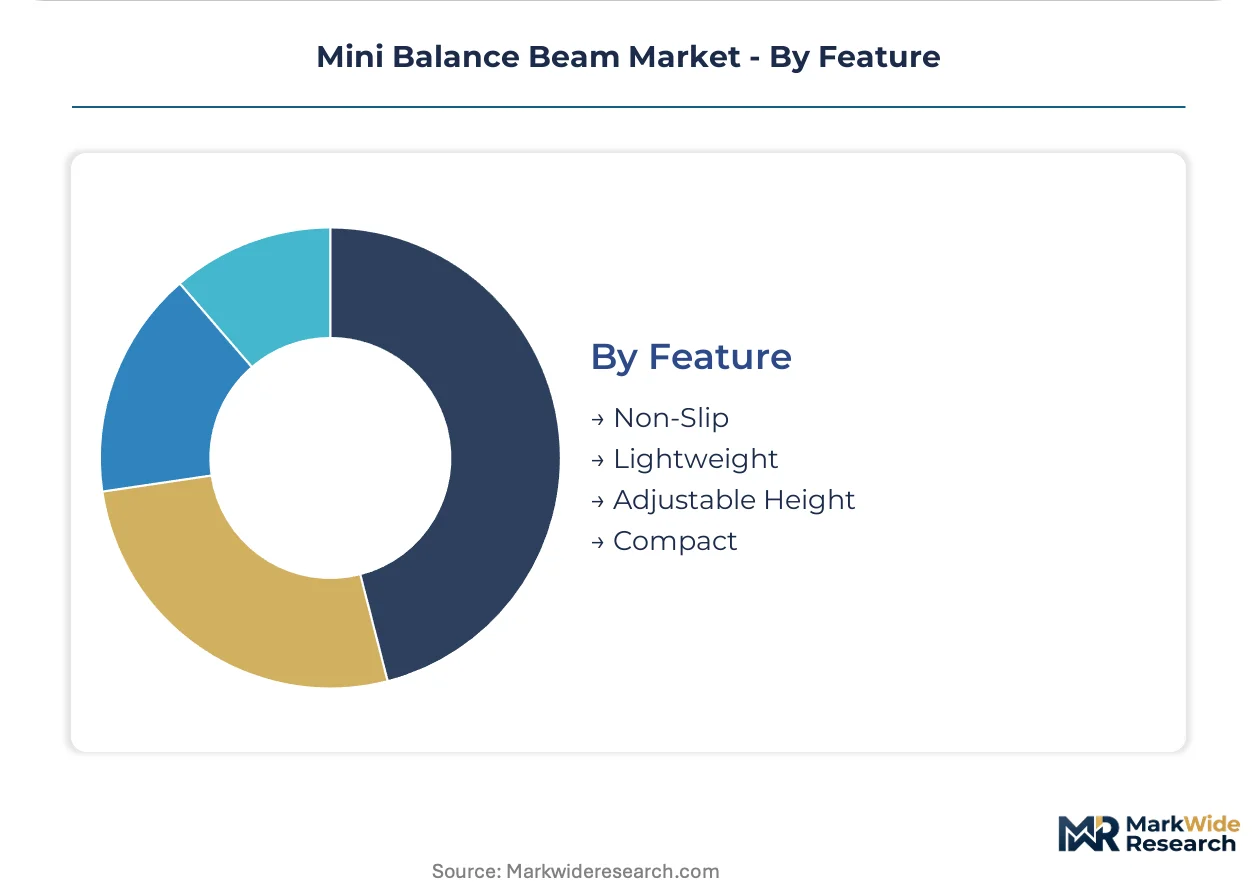
Feature:
Functional differentiation increasingly converges with digital service integration, transforming hardware attributes into subscription-enabling infrastructure.
- Non-Slip:Microfiber or rubberized surface treatments with DIN 7909-certified friction coefficients prevent skill execution failures in competitive training environments. German institutional buyers specify these treatments in public tender requirements.
- Adjustable Height:Telescoping leg systems with calibrated detent positions accommodate gymnasts from early childhood through adolescent development stages. These configurations concentrate in school districts with multi-age program structures.
- Lightweight:Hollow-core construction techniques reduce transport burden for mobile coaching applications.
- Compact:Reduced footprint designs serve residential buyers with space constraints.
Non-Slip treatments dominate federation-approved installations. Adjustable Height configurations are expanding most quickly across institutional segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gymnastics apparatus manufacturing traces its commercial origins to Dutch and Belgian woodcraft traditions in the early twentieth century, with laminated beam construction techniques spreading through Central European trade networks before establishing production footholds in North America and East Asia.
United States
Texas and California school districts drive institutional procurement through consolidated vendor frameworks, while collegiate athletic departments in Florida and the Midwest negotiate direct contracts for Olympic-grade specifications. The U.S. Consumer Product Safety Commission guidelines mandate third-party structural testing for all juvenile sports apparatus entering institutional channels. Dallas-Fort Worth and Los Angeles metropolitan clusters concentrate distributor consolidation activity as multi-year framework agreements displace traditional dealer relationships.
Germany
Bavaria and North Rhine-Westphalia municipal buyers specify DIN 7909-compliant sourcing in public tender requirements for newly constructed youth athletic facilities. The country's sports equipment safety framework mandates third-party structural testing, elevating documentation burdens for imported apparatus. Stuttgart and Munich industrial corridors host accredited testing laboratories that domestic producers leverage to shorten certification timelines against foreign competitors.
China
Shanghai and Guangzhou municipal governments mandate GB-standard certified equipment for youth athletic infrastructure expansion, creating concentrated demand pull from state-funded construction programs. The country's national standards for juvenile sports apparatus add a certification layer distinct from European and North American frameworks. Pearl River Delta manufacturing clusters supply folding and portable configurations for domestic distribution and Southeast Asian export channels.
Netherlands
Benelux-based manufacturers leverage proximity to certified forestry operations and established chain-of-custody documentation to supply sustainable wood beam lines under EU Green Deal procurement mandates. The country's national environmental framework aligns with broader European sustainability documentation requirements for institutional buyers. Eindhoven and Rotterdam logistics hubs facilitate distribution to German institutional buyers and North American collegiate programs seeking certified sustainable sourcing.
Japan
Tokyo and Osaka metropolitan school districts specify JIS-compliant apparatus for competitive gymnastics programs, with national federation approval cycles driving specification adherence among domestic suppliers. The country's Ministry of Economy, Trade and Industry oversees industrial standards coordination for sports equipment safety. Kanto region manufacturing maintains traditional laminated hardwood fabrication techniques for high-specification institutional segments resistant to foam-based substitution.
Mini Balance Beam Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification tier and material sourcing dimensions, with sustainably certified hardwood configurations commanding price premiums against foam-based entry-level alternatives. The vendor base organizes around three strategic archetypes: federation-approved specification specialists, sustainable sourcing credential holders, and portable-configuration volume producers. Capacity expansion and direct institutional contracting represent the dominant competitive moves, with producers bypassing traditional distribution to capture multi-year framework agreements.
Among North American institutional specialists, American Athletic (AAI) occupies a position exemplifying Olympic-grade specification adherence for elite training centers, while Gibson Athletic anchors demand through direct relationships with collegiate gymnastics programs. Janssen Fritsen represents the Benelux-based sustainable sourcing archetype, leveraging regional forestry certification chains to supply European institutional buyers and export markets. These three companies illustrate the geographic and tier-based positioning that structures competitive rivalry across certification, material, and channel dimensions.
| Leading Market Players |
|---|
| American Athletic (AAI) |
| Janssen Fritsen |
| Cramer Product |
| Acromat |
| Active Wrap |
| Black Diamond |
| Champions Sports |
| DGS |
| Gibson Athletic |
| Others |
Value Network & Pricing Analysis
Backward integration into Baltic birch core fabrication anchors supply position and pricing power for federation-grade beam manufacturers, while outsourced foam assembly operations surrender margin control to commodity resin suppliers. Captive laminating capacity in Benelux and Nordic regions insulates certified producers from raw material volatility that compresses margins for specification-dependent competitors.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates federation-approved wood configurations from institutional-grade folding variants and entry-level foam substitutes. Price differentiation rests on certification tier—DIN 7909 and GB standard compliance command substantial premiums against uncertified alternatives. Cost compression in foam-based economy tiers is intensifying because recreational schools prioritize procurement thresholds over specification stringency. Parent buyers in Florida and Texas show highest price sensitivity, while German municipal committees and Chinese education bureaus demonstrate lowest sensitivity due to mandated compliance documentation.
Supply Chain Analysis
Skilled laminating technician scarcity in traditional furniture-producing regions of the Netherlands and Belgium constrains precision hardwood core fabrication capacity. Geographic supply concentration clusters in Nordic and Baltic states for Baltic birch veneer, Pearl River Delta for folding hinge hardware, and Benelux for sustainable certification documentation. Raw material dependencies draw from certified forestry operations, EVA foam resin, and synthetic suede competition wraps. Single-source vulnerability runs through Baltic birch core suppliers exposed to regional logistics disruptions. Distribution runs through direct institutional contracting that displaces traditional regional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory complexity into sustainable competitive advantage, with Germany's DIN 7909 framework and China's GB standards expansion creating durable demand pull for certified manufacturers.
For Market Incumbents: Deploy direct institutional contracting to capture multi-year framework agreements before competitors establish relationships with Texas and California school districts. Fortify position by accelerating sensor-enabled beam development for subscription-integrated revenue streams, countering the threat of digital training platforms that could commoditize hardware specifications. For New Entrants and Emerging Players: Begin with foam-based portable configurations targeting parent buyers in Florida and recreational schools where federation approval is not required. The most penetrable segment sits in home-use training programs with rapid deployment needs, accessed through e-commerce channels and mobile coaching professional networks rather than institutional procurement committees. For Investors and Strategic Acquirers: Consolidation pressure builds where certification documentation burdens exceed the operational capacity of sub-scale regional manufacturers. Long-term viability favors vertically integrated producers with captive Baltic birch sourcing and accredited testing laboratory proximity. The signal to watch is federation equipment approval cycle compression that accelerates retooling requirements and strains working capital reserves.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | DIN 7909 and GB standard compliance unlocks German and Chinese institutional procurement channels. |
| Sensor Technology Integration | Embedded balance metrics transform hardware into subscription-enabling infrastructure for remote coaching platforms. |
| Sustainable Sourcing Documentation | EU Green Deal chain-of-custody certification creates preference windows with European municipal buyers. |
| Direct Institutional Contracting | Bypassing traditional distributors captures multi-year framework agreements with consolidated vendor lists. |
| Portable Configuration Expansion | Folding and collapsible designs serve mobile coaching applications and space-constrained municipal facilities. |
Research Methodology
Direct dialogue with equipment specification committees, gymnastics federation technical directors, school district procurement officers, and laminating facility operators grounded qualitative assessment, validated against customs trade records, federation equipment approval registries, municipal tender documentation, and sports equipment safety framework publications. Bottom-up and top-down triangulation reconciled manufacturer shipment data with institutional purchasing patterns across the analysis window.
Bottom-up volume modeling aggregated segment-level demand curves by type, material, and end-user configuration, while top-down validation cross-checked against national youth athletic infrastructure investment programs. The projection horizon incorporated type-specific adoption trajectories, certification requirement phase-in schedules, and regional procurement mandate enforcement patterns. CAGRs derived from fitted growth curves adjusted for federation equipment replacement cycles and school construction program timing.
Several conditions sit outside the modeled scope, including geopolitical disruption to Baltic birch supply corridors, abrupt federation specification revisions, and sensor technology cost curves that could accelerate digital platform substitution. Forecasts reflect assumptions about regulatory enforcement continuity and institutional budget allocation stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Clay Pigeon Thrower Market
Sports Equipment
Middle East and Africa Stand-Up Paddleboard Market
Sports Equipment
Golf Bags Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Kids Sports Equipment and Accessories Market
Sports Equipment
Racket Sports Equipment Market
Sports Equipment
Mixed Martial Arts Equipment Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Windsurf Masts Market
Sports Equipment
Motocross Gears Market
Sports Equipment
Baseball Equipment Market