
 Global Sports Bicycle Market | 2026-2036
Global Sports Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Bicycle Market Outlook
A shortage of certified carbon fiber layup technicians is unwinding production capacity at several Asian contract manufacturers. Trek Bicycle Corporation leverages in-house composite engineering to sustain North American supply continuity despite labor scarcity. Giant Manufacturing Co. Ltd. anchors Taiwan's export dominance through vertical integration into raw carbon fiber prepreg sourcing. Specialized Bicycle Components differentiates via proprietary shock-tuning technology that commands premium positioning across dealer networks.
Sports bicycles are human-powered, lightweight vehicles engineered for competitive racing, off-road traversal, or structured fitness training, typically featuring frame geometries optimized for aerodynamic efficiency and power transfer with component specifications including carbon fiber monocoque construction, electronic shifting systems, and hydraulic disc brakes. The product type dimension shows road and mountain categories capturing the dominant volume share while BMX maintains niche tournament-driven demand. Carbon fiber material grades concentrate margin pools at the premium and luxury price tiers, where frame weight-to-stiffness ratios justify substantial price premiums over aluminum alternatives.
The EU Green Deal and associated F-Gas Regulation on manufacturing coolants, alongside REACH chemical compliance for frame coatings, shape European market access requirements and production facility siting decisions. The US Consumer Product Safety Commission enforces mechanical safety standards that dictate brake-system minimum performance thresholds for imported complete bicycles. Stakeholders must monitor evolving battery-assist regulatory thresholds in key European cycling markets, as e-bike classification boundaries increasingly influence sports bicycle adjacent product development and channel placement strategies.
Market Dynamics
The EU Green Deal's sustainable transport mandates are compressing replacement cycles as municipal infrastructure investment redirects toward dedicated cycling corridors, while carbon fiber supply scarcity concentrates production among vertically integrated manufacturers.
Growth Catalysts
- EU Green Deal cycling infrastructure mandates:Germany, Denmark, and the Netherlands are expanding dedicated bike-lane networks that accelerate fitness enthusiast replacement demand.
- Carbon fiber monocoque frame technology:Professional cycling teams and competitive amateur leagues are expanding procurement of lightweight, aerodynamic frame geometries optimized for power transfer efficiency.
- F-Gas Regulation compliance manufacturing:REACH chemical standards for frame coatings and manufacturing coolants are redirecting European production facility siting toward certified greenfield sites.
Market Restraints
- Certified carbon fiber layup technician shortage:Asian contract manufacturers face unwinding production capacity due to skilled labor scarcity in composite engineering.
- Raw carbon fiber prepreg supply concentration:Taiwan and select Japanese suppliers control upstream material access, creating input cost volatility for non-integrated frame builders.
- Electronic shifting system technical limitation:Battery-assist regulatory threshold uncertainty across European markets constrains adjacent product development boundaries.
Strategic Opportunities
- Factory-to-consumer direct sales channel expansion:Germany's fitness enthusiast segment demonstrates accelerated replacement cycles through bypassed dealer networks.
- E-bike classification boundary convergence:Evolving battery-assist regulatory thresholds in Belgium, France, and Italy create white space for sports bicycle adjacent positioning.
- REACH chemical compliance certification tailwind:European frame coating standards favor early-adopting manufacturers with certified green production lines.
Industry Challenges
- Composite engineering skill gap:In-house carbon fiber layup capability requires multi-year technician training programs that constrain rapid capacity scaling.
- Hydraulic disc brake certification timeline:US Consumer Product Safety Commission mechanical safety standards dictate extended validation periods for imported complete bicycles.
- Supply chain reconfiguration friction:Raw carbon fiber prepreg sourcing shifts necessitate qualified supplier requalification under ISO composite material standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Bicycle Market |
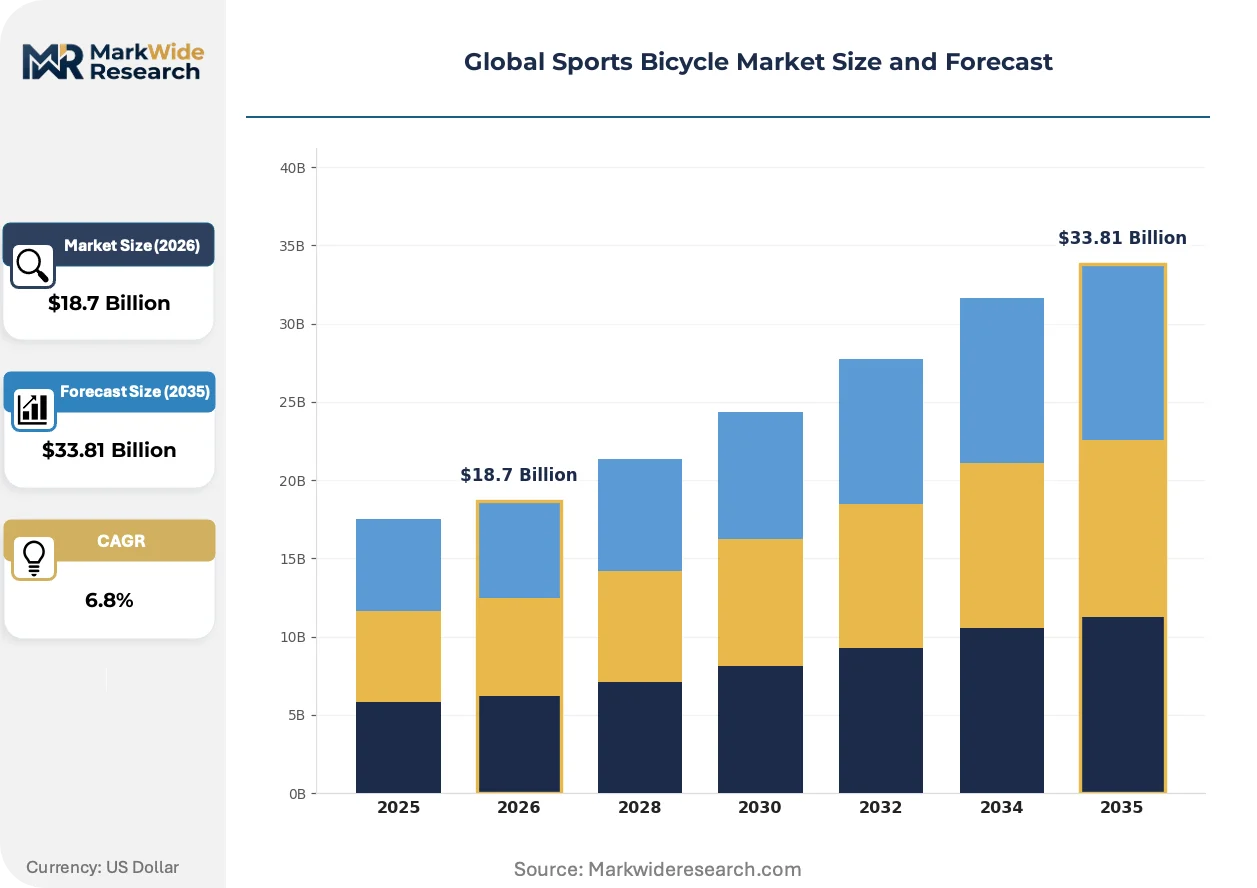
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mountain, Road, Hybrid, BMX End User: Professional Athletes, Recreational Riders, Fitness Enthusiasts, Tourists Material: Aluminum, Carbon Fiber, Steel, Titanium Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Trek Bicycle Corporation, Giant Manufacturing Co. Ltd., Specialized Bicycle Components, Merida Industry Co. Ltd., Accell Group NV, Dorel Industries Inc., Scott Sports SA, Bianchi, Cervelo Cycles, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Bicycle Market Strategic Shifts
Active reshaping of the sports bicycle market centers on material substitution in frame construction, regulatory compression of manufacturing processes, and disintermediation of traditional distribution hierarchies.
Advanced carbon fiber prepreg formulations with tuned resin systems are supplanting aluminum alloy frames in the premium performance tier. Professional cycling teams and competitive amateur leagues in Germany and Belgium are adopting these monocoque constructions at accelerating pace. The shift is compressing margin pools at mid-tier aluminum specialists while concentrating engineering talent among vertically integrated composite houses.
REACH chemical compliance for frame coatings and the EU F-Gas Regulation on manufacturing coolants are mandating production facility re-siting across Europe. Manufacturers must relocate or retrofit to certified greenfield sites to maintain market access. German and Danish production clusters are responding fastest, leveraging proximity to municipal cycling infrastructure investment zones.
Factory-to-consumer direct sales are eroding traditional dealer network dominance in the fitness enthusiast segment. Germany's replacement cycle acceleration demonstrates the model's viability, with online configurators and virtual fit systems replacing brick-and-mortar consultation. Belgian and Dutch markets are exhibiting similar channel migration as digital-native buyers concentrate in urban cycling corridors.
Global Sports Bicycle Market Segmentation
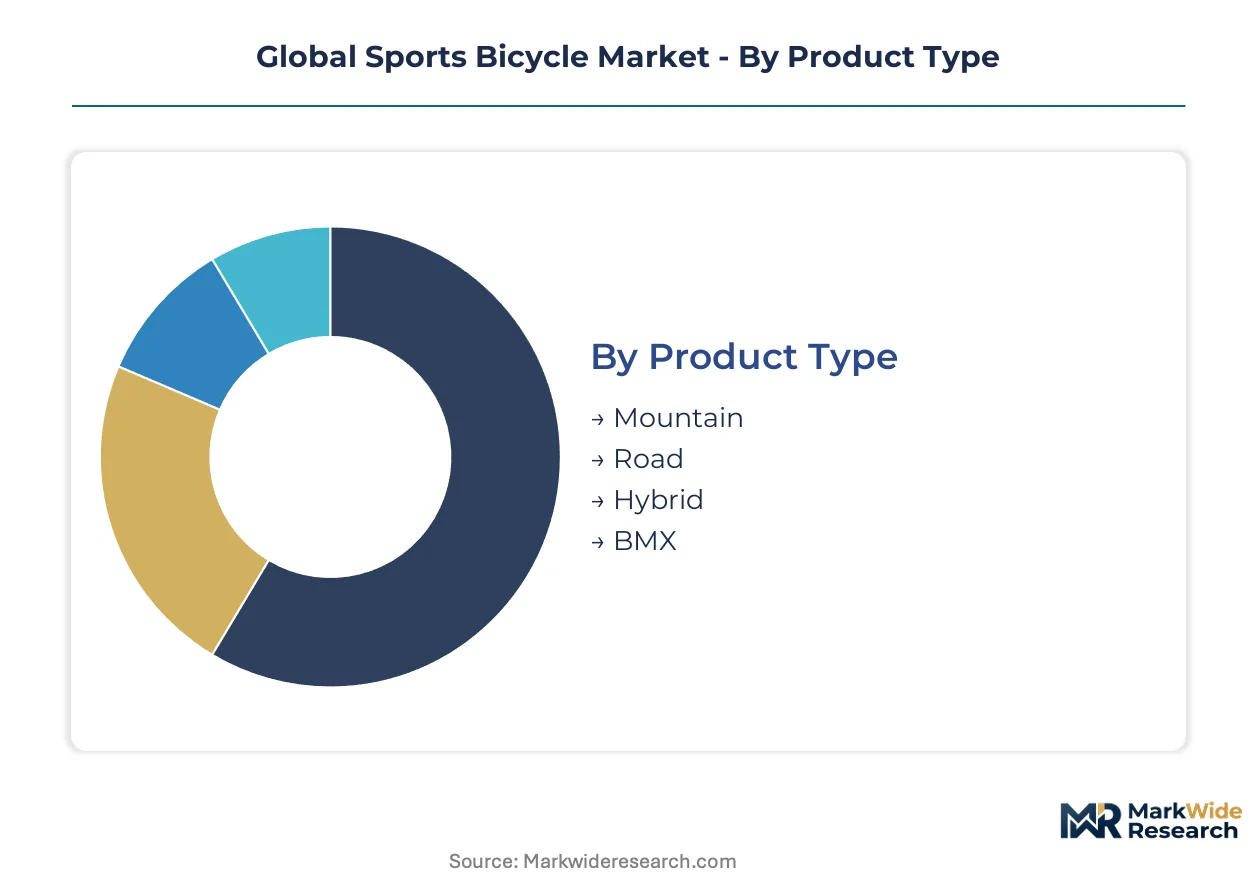
Sports bicycle segmentation tracks how frame materials, riding disciplines, and buyer sophistication stratify across distribution channels. Manufacturers align production capacity and dealer support investments to these segment boundaries.
Product Type:
Channel placement varies sharply by riding discipline, with road and mountain categories commanding dedicated retail footprints while hybrid and BMX segments distribute through alternative pathways.
- Road:Drop-bar geometries optimized for paved-surface speed and aerodynamic efficiency dominate professional team procurement and competitive amateur league sponsorships. German fitness enthusiasts accelerate replacement cycles through factory-direct channels, bypassing traditional dealer consultation.
- Mountain:Suspension-equipped frames with hydraulic disc brakes and electronic shifting systems concentrate demand in Belgium and Dutch cycling corridors where off-road trail networks expand. Trek Bicycle Corporation sustains North American supply continuity through in-house composite engineering despite technician shortages.
- Hybrid:Flat-bar configurations blending road efficiency with urban durability flow through mass retail and municipal fleet procurement channels.
- BMX:Compact frames for tournament-driven trick disciplines maintain niche distribution through specialty action-sport retailers.
Road dominates installed base. Mountain is where expansion concentrates.
End User:
Cost tier alignment separates professional and enthusiast segments from casual participants, with pricing stratification across premium, standard, and economy levels reflecting component specification and service bundling.
- Professional Athletes:UCI-registered teams and national federation programs demand homologated frames with certified stiffness-to-weight ratios and documented wind-tunnel validation.
- Recreational Riders:Weekend cyclists prioritize comfort geometries and dealer service networks over marginal performance gains, concentrating volume in mid-range aluminum configurations.
- Fitness Enthusiasts:Structured training regimens in Germany and Denmark drive carbon fiber monocoque adoption through online configurators and virtual fit systems that disintermediate brick-and-mortar consultation. This segment climbs the fastest as municipal cycling infrastructure investment accelerates replacement cycles.
- Tourists:Rental fleet operators and guided tour companies source durable steel and aluminum frames with standardized component specifications for simplified field maintenance.
Fitness enthusiasts command margin concentration. Recreational riders anchor volume scale.
Material:
Supply concentration at the prepreg level shapes which frame materials manufacturers can source reliably, with backward integration determining competitive positioning in carbon fiber grades.
- Carbon Fiber:T700 and T800 modulus prepregs with tuned resin systems deliver premium weight-to-stiffness ratios. Giant Manufacturing Co. Ltd. anchors Taiwan's export dominance through upstream control over raw carbon fiber sourcing.
- Aluminum:6061-T6 and 7005 alloys maintain mid-tier positioning where hydroformed tube sets balance cost against performance degradation relative to composite alternatives.
- Steel:Chromoly and stainless tubing persists in touring and custom builder niches where repairability and ride quality outweigh mass considerations.
- Titanium:Cold-worked 3Al-2.5V frames occupy ultra-premium positioning for riders prioritizing fatigue resistance and corrosion immunity in all-weather conditions.
Carbon fiber dominates engineering talent concentration. Aluminum retains volume manufacturing scale.
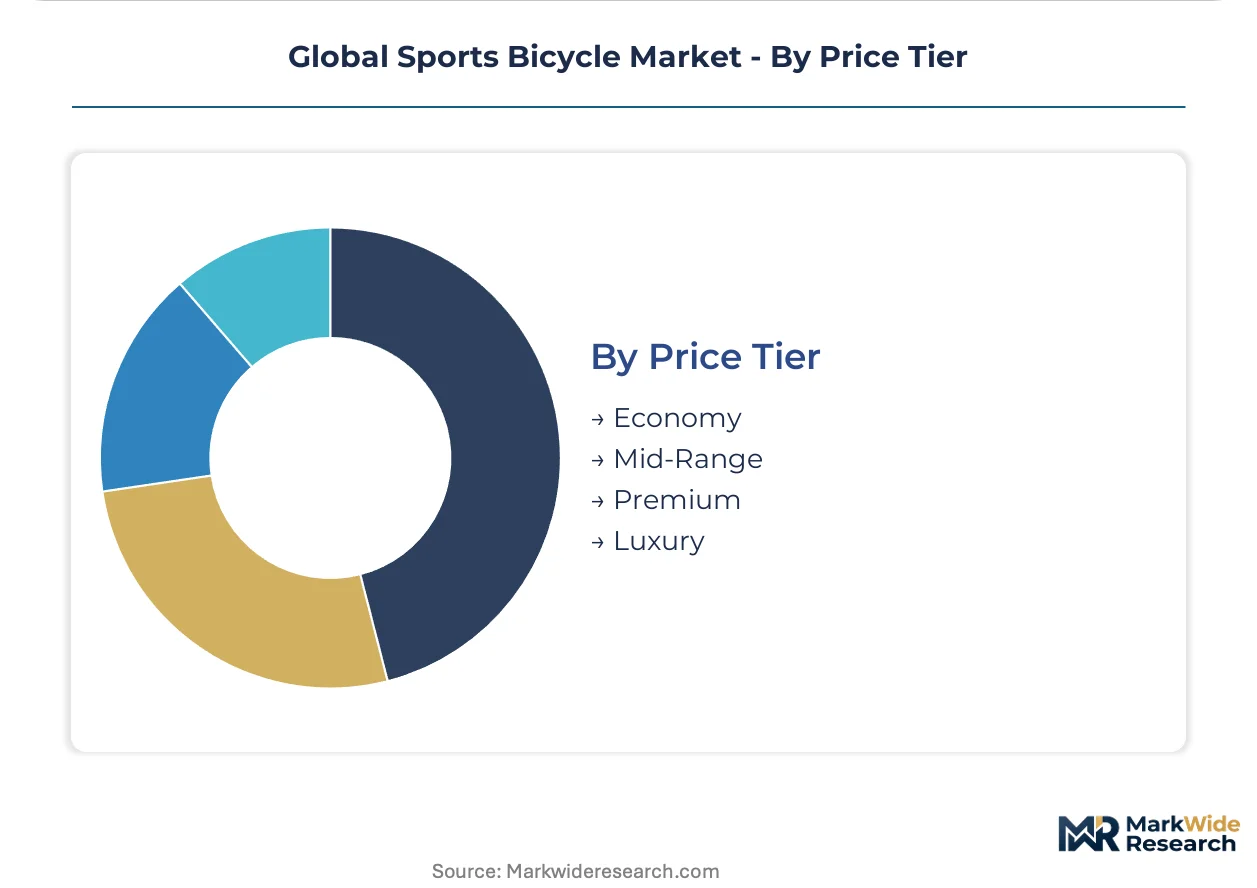
Price Tier:
Margin pools concentrate at the premium and luxury tiers where frame weight-to-stiffness ratios justify substantial price premiums over aluminum alternatives.
- Premium:Electronic shifting systems and carbon fiber monocoque construction with proprietary shock-tuning technology command dealer network positioning. Specialized Bicycle Components differentiates via these specifications.
- Luxury:Custom geometry programs and limited-production frame sets with hand-layup certification target collectors and professional team replica demand.
- Mid-Range:Aluminum frames with mechanical shifting and rim or entry-level disc brakes serve club riders and emerging market expansion.
- Economy:Steel and basic aluminum configurations with standardized components satisfy price-sensitive entry demand and rental fleet procurement.
Premium tier concentrates manufacturer R&D investment. Mid-range is where channel expansion accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers command pricing premiums through EU Green Deal-aligned production certification, while Taiwanese exporters compete on carbon fiber supply chain velocity and scale economies.
Germany
Fitness enthusiasts accelerate replacement cycles through factory-direct channels, bypassing traditional dealer networks. The EU Green Deal mandates dedicated cycling corridor investment across Bavaria and North Rhine-Westphalia. Stuttgart's composite engineering cluster concentrates in-house carbon fiber layup capability despite technician shortages.
Taiwan
Raw carbon fiber prepreg sourcing dominance anchors export volume to North American and European markets. The island's central bank monitors currency exposure for bicycle component exporters. Taichung's manufacturing corridor houses vertically integrated frame builders with captive supply of T700 and T800 modulus materials.
United States
Professional cycling teams and competitive amateur leagues drive procurement of electronic shifting systems and hydraulic disc brake configurations. The Consumer Product Safety Commission enforces mechanical safety standards for imported complete bicycles. Wisconsin and California clusters sustain North American supply continuity through in-house composite engineering programs.
Belgium
Off-road trail network expansion concentrates mountain bicycle demand in Flanders and Wallonia cycling corridors. REACH chemical compliance for frame coatings redirects production facility siting toward certified greenfield sites. Antwerp's logistics hub facilitates rapid distribution to Dutch and French adjacent markets.
Japan
Precision component manufacturing for electronic shifting systems and hydraulic brake assemblies supplies global premium-tier assemblers. METI standards govern carbon fiber material certification for export-bound frames. Osaka's industrial belt maintains specialty steel and titanium tubing capacity for touring and custom builder niches.
Global Sports Bicycle Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where composite engineering capability separates premium positioning from volume manufacturing. The vendor base concentrates among vertically integrated frame builders with backward integration into raw material sourcing, mid-tier aluminum specialists dependent on contract manufacturing, and niche custom builders serving collector demand. Dominant competitive moves include capacity expansion in certified greenfield European sites and strategic partnerships for electronic system integration.
Among Taiwan-based fabricators, Giant Manufacturing Co. Ltd. exemplifies upstream control over carbon fiber prepreg supply chains, while Trek Bicycle Corporation and Specialized Bicycle Components occupy positions within the premium-tier vector where proprietary shock-tuning technology and in-house composite engineering sustain North American supply continuity. These three anchors represent distinct strategic postures: captive raw material access, integrated manufacturing scale, and technology-led brand differentiation.
| Leading Market Players |
|---|
| Trek Bicycle Corporation |
| Giant Manufacturing Co. Ltd. |
| Specialized Bicycle Components |
| Merida Industry Co. Ltd. |
| Accell Group NV |
| Dorel Industries Inc. |
| Scott Sports SA |
| Bianchi |
| Cervelo Cycles |
| Others |
Value Chain & Pricing Dynamics
Carbon fiber prepreg substitution for aluminum alloy frames simultaneously redraws procurement geography toward Taiwan and Japan while compressing mid-tier pricing power. REACH chemical compliance and F-Gas Regulation certification requirements layer cost premiums onto European-sourced frames that factory-direct channels in Germany only partially offset.
Pricing Analysis
The customization-premium spread between configured-to-order carbon fiber monocoque frames and standard aluminum configurations spans three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on frame certification grade and electronic shifting integration, with German fitness enthusiasts showing lowest sensitivity through direct channels while recreational riders in Belgium and the Netherlands anchor volume at mid-range aluminum tiers. Cost compression in economy steel configurations is intensifying because of raw material pass-through volatility. Tourist rental fleet operators exhibit highest price sensitivity, sourcing standardized components through municipal procurement.
Supply Chain Analysis
Taiwan Strait maritime transit underwrites carbon fiber prepreg flow to North American and European assembly plants. Raw material sourcing draws from Taiwan, Japan, and select Chinese suppliers for T700 and T800 modulus prepregs, with hydraulic disc brake assemblies and electronic shifting systems feeding from Japanese precision manufacturers. Single-source vulnerability concentrates in Taichung's vertically integrated corridor where Giant Manufacturing Co. Ltd. controls upstream access. Distribution runs through Antwerp's logistics hub for Benelux cycling corridors, with secondary nodes in Stuttgart and Wisconsin sustaining regional fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sports Bicycle Market sits at a post-pandemic equipment replacement cyclical upswing as EU Green Deal infrastructure investment accelerates municipal cycling corridor development.
For Market Incumbents: Consolidate in-house carbon fiber layup capability through multi-year technician training programs that lock scarce composite engineering talent against Asian contract manufacturer attrition. Defend margin position by securing REACH-certified greenfield production capacity in Germany and Denmark before regulatory deadlines harden. Prioritize backward integration into raw prepreg sourcing or captive supplier relationships to neutralize Taiwan-Japan supply concentration risk. For New Entrants and Emerging Players: Differentiate on virtual fit technology and online configurator platforms that bypass established dealer networks in the German fitness enthusiast segment. Target Belgium's expanding off-road trail network corridor where mountain bicycle demand outpaces incumbent service coverage. Pursue white-label assembly partnerships with Taiwanese frame builders to compress time-to-market while building proprietary shock-tuning competencies. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors vertically integrated manufacturers with certified European production footprints. Long-term viability hinges on carbon fiber material science capabilities and regulatory compliance infrastructure rather than brand equity alone. Monitor F-Gas Regulation enforcement intensity and REACH certification backlog as inflection indicators for European market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Greenfield Facility Expansion | REACH and F-Gas Regulation compliance secures EU market access against relocation costs. |
| Technician Training Program Investment | Multi-year composite engineering pipelines offset Asian contract manufacturer labor scarcity. |
| Factory-to-Consumer Channel Launch | German fitness enthusiast segment demonstrates accelerated replacement cycles through disintermediation. |
| Electronic System Integration Partnership | Proprietary shock-tuning technology commands premium positioning across dealer networks. |
| Raw Material Backward Integration | Upstream control over T700 and T800 modulus prepreg sourcing neutralizes cost volatility. |
Study Parameters
Initial hypotheses were tested against primary input from composite engineering directors, procurement leads at professional cycling teams, dealer network managers, and municipal infrastructure planners and refined through secondary validation. Primary fieldwork combined structured interviews with frame builders in Taiwan and Germany alongside channel assessments in Belgium and the Netherlands. Secondary sources incorporated customs trade data for carbon fiber prepreg flows, EU Green Deal implementation tracking, Consumer Product Safety Commission enforcement records, and ISO composite material standard documentation. Bottom-up demand modeling from end-user segments was cross-checked against top-down production capacity estimates from major manufacturing clusters.
Variance-decomposition across product type, material grade, price tier, and regional regulatory framework shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include riding discipline, frame construction material, buyer sophistication tier, and certification status. CAGRs were derived from replacement cycle velocity analysis and infrastructure investment correlation. Industry-specific forecast inputs encompassed EU cycling corridor completion schedules and carbon fiber technician training program graduation rates.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding commitment or carbon fiber supply continuity would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and skilled labor pipeline development. Practitioners should keep alternative scenarios live as battery-assist classification thresholds and municipal procurement standardization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Air Sports Equipment Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Soccer Gear Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Juggling Clubs Market
Sports Equipment
Football Market
Sports Equipment
Carbon Fiber Badminton Racket Market
Sports Equipment
Sports Eyewear Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Golf Ball Market
Sports Equipment
Backboard Market
Sports Equipment
Padel Balls Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Diving Board Market
Sports Equipment
Licensed Sports Merchandise Market
Sports Equipment
Surfboard Market