
 Hunting Equipment and Accessories Market | 2026-2036
Hunting Equipment and Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Hunting Equipment and Accessories Market Intelligence
The Enthusiasts end-user segment is expanding its influence on product design, shifting demand towards more versatile and user-friendly gear. Vista Outdoor Inc. leverages a diverse portfolio spanning ammunition to outdoor products. Under Armour Inc. differentiates through its technical apparel and footwear designed for specific hunting environments and climates. Beretta Holding SA sustains its premium market position through a legacy of craftsmanship and brand reputation in firearms.
Hunting equipment and accessories encompass the tools and apparel used for tracking, pursuing, and harvesting game animals. This includes firearms with specific barrel rifling for accuracy and advanced bows constructed from lightweight carbon fiber composites. The primary purpose is to enhance hunter efficiency, safety, and success. While rifles constitute a mature product category, high-performance crossbows and digital accessories like laser range finders are high-growth areas.
Regulations from bodies like the US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) govern firearm sales and ownership. Concurrently, wildlife management agencies in countries such as Canada and Germany set strict rules on hunting seasons, weapon types, and caliber restrictions. Manufacturers must therefore navigate a complex web of national firearm laws and regional conservation policies. Future success depends on adapting product lines to these divergent regulatory landscapes while incorporating technological advancements.
Market Dynamics
The central force shaping the market is the convergence of consumer electronics with traditional hunting gear. This fusion embeds digital intelligence, from GPS tracking to ballistic computation, directly into equipment, shifting product value from mechanical craftsmanship alone to integrated system performance and data-driven precision.
Growth Catalysts
- Advanced Materials Science:The adoption of carbon fiber composites and lightweight alloys in bow and firearm construction reduces weight while increasing strength and durability, appealing to hunters who cover long distances in difficult terrain.
- Enthusiast Segment Expansion:A growing base of dedicated enthusiasts demands more sophisticated and versatile equipment, driving innovation in products like modular rifle chassis and high-performance optics that serve multiple hunting disciplines.
- Conservation Funding Models:Wildlife management programs in countries like the United States, funded through excise taxes on hunting equipment and license sales, create a stable regulatory environment that supports habitat preservation and sustained hunter participation.
Market Restraints
- Divergent Firearm Regulations:Manufacturers face significant compliance costs navigating the patchwork of laws governing firearm sales, transport, and features, from ATF regulations in the US to caliber restrictions set by wildlife agencies in Germany.
- Negative Social Perception:Opposition to hunting from animal rights groups and segments of the public can lead to restrictive legislation, reduced access to hunting lands, and a decline in new participant recruitment in certain regions.
- Specialty Material Price Volatility:The cost of key inputs, such as high-grade optical glass for scopes and specialty steels for barrels, is subject to supply chain disruptions and market fluctuations, creating margin pressure for manufacturers.
Strategic Opportunities
- Smart Accessory Ecosystems:There is a significant opportunity to develop interconnected digital accessories, including rangefinders that communicate with smart scopes to automatically adjust aim points for distance and environmental conditions.
- Expansion in Eastern Europe:Markets in countries like Poland and the Czech Republic, with strong hunting traditions and rising disposable incomes, present opportunities for premium equipment manufacturers to establish a foothold.
- Female-Specific Product Lines:Designing apparel and equipment ergonomically tailored for female hunters represents an underserved segment, offering a path to capture a growing demographic with specific fit and performance needs.
Industry Challenges
- Complex Global Logistics:Managing a supply chain for specialized components, such as optical sensors and composite materials, is complicated by varied international trade regulations and export controls on defense-related technologies.
- Counterfeit Product Infiltration:The proliferation of counterfeit high-performance accessories, particularly rifle scopes and laser rangefinders, poses a significant threat to brand integrity and user safety, requiring investment in anti-counterfeiting measures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hunting Equipment and Accessories Market |
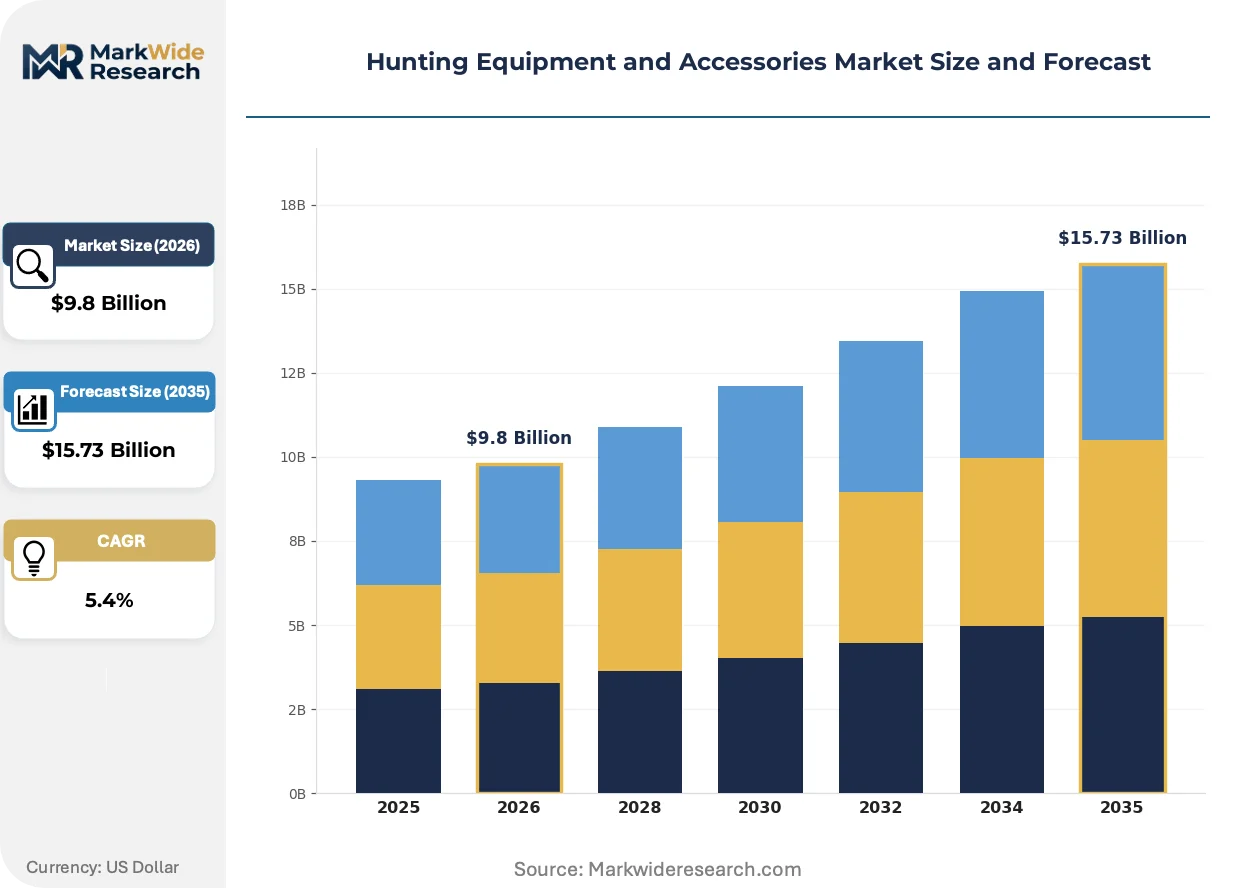
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rifles, Shotguns, Bows, Crossbows Accessory Type: Scopes, Holsters, Knife Sets, Range Finders End User: Professional Hunters, Enthusiasts, Outfitters, Collectors Distribution Channel: Online Retail, Sporting Goods Stores, Specialty Retailers, Trade Shows |
| Companies Covered | Sturm, Ruger and Co Inc, Buck Knives Inc., Beretta Holding SA, Leupold & Stevens Inc., Under Armour Inc., Vista Outdoor Inc., Browning Arms Company, Savage Arms, American Outdoor Brands Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hunting Equipment and Accessories Market Strategic Shifts & Innovations
Technological advancement is transforming formerly passive equipment into active, intelligent systems. This shift is most evident in the integration of digital capabilities into optics and the use of advanced materials to push performance boundaries in both firearms and archery equipment, meeting new user expectations.
Smart optics technology combines high-transmission glass with embedded microprocessors and sensors. Enthusiast hunters and long-range sport shooters are the primary adopters, seeking a decisive technological advantage. This evolution is integrating functions like laser rangefinding, ballistic calculation, and video capture into a single sighting device, compressing the hunter's toolkit and decision-making time.
Regulatory pressures on ammunition composition are intensifying across multiple jurisdictions. The European Chemicals Agency (ECHA), under REACH, is implementing broad restrictions on the use of lead projectiles, citing environmental and health concerns. This action compels a market-wide pivot to alternative, non-toxic materials like copper and bismuth, affecting ballistics and terminal performance for rifle and shotgun ammunition categories.
Buyer behavior increasingly favors modularity and personalization over fixed, off-the-shelf products. This trend disrupts the traditional sales model, as consumers now expect to customize firearms with different stocks, triggers, and barrels, or archery bows with specialized limbs and sights. This is most visible in the United States, where a strong aftermarket ecosystem supports extensive customization for tactical and hunting rifles.
Hunting Equipment and Accessories Market Segmentation
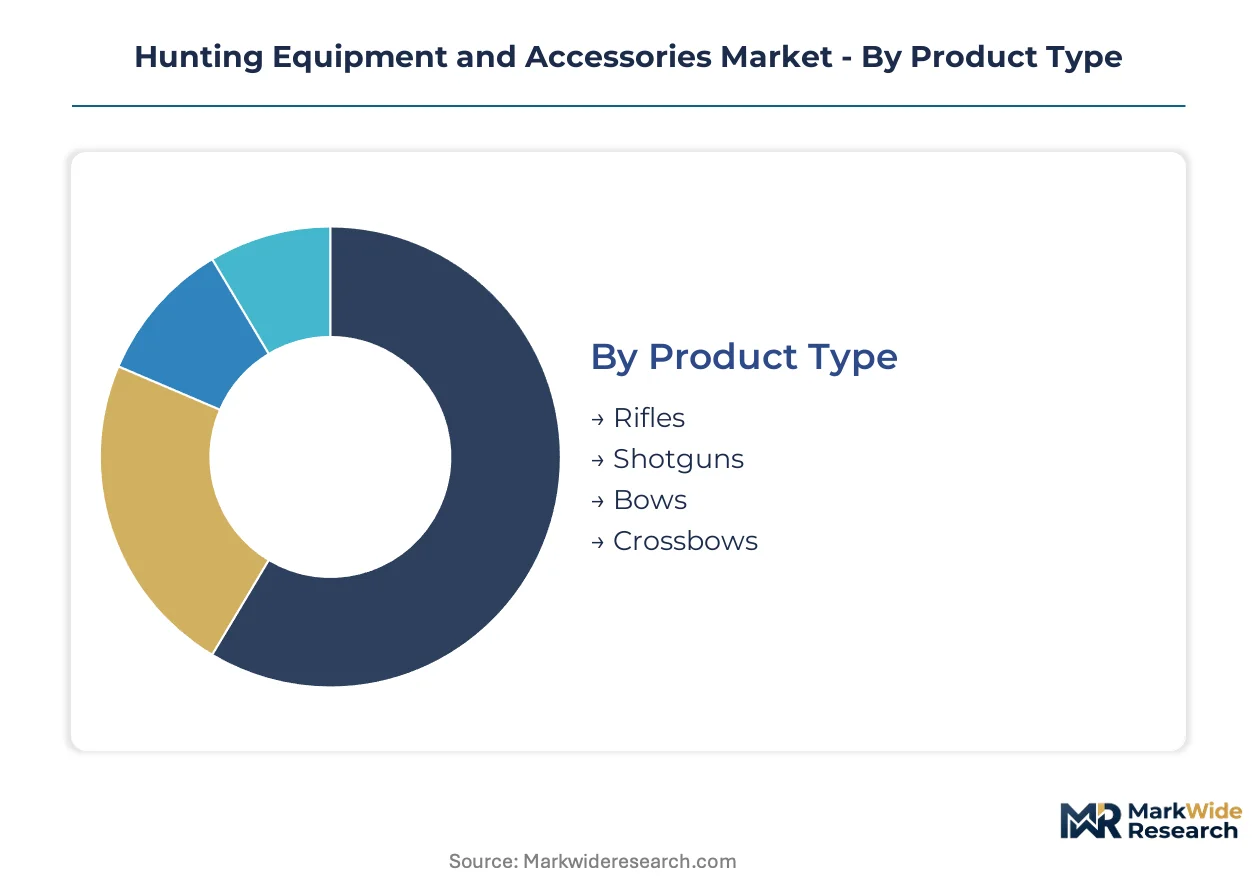
Market segmentation provides a granular view of the hunting equipment and accessories landscape, highlighting distinct product preferences, end-user behaviors, and distribution pathways. Understanding these segments allows manufacturers to tailor product development and marketing strategies effectively, addressing specific demand pockets across the industry.
Product Type:
The upgrade and replacement cycle for hunting equipment often dictates innovation within specific product types, particularly for firearms and advanced archery gear. Hunters frequently seek performance enhancements or compliance with evolving regulations, driving demand for newer models.
- Rifles:These firearms feature rifled barrels for enhanced accuracy over long distances, primarily used for harvesting larger game animals. Demand remains consistent in regions like the United States due to established hunting traditions and a robust aftermarket for customization.
- Shotguns:These smoothbore firearms primarily target birds and smaller game, also serving for self-defense applications. Their versatility across various hunting scenarios maintains a steady market presence.
- Bows:Traditional and compound bows offer a silent, challenging hunting experience, appealing to a dedicated segment of archers. Carbon fiber and advanced limb designs enhance their performance.
- Crossbows:These high-performance archery devices offer greater power and accuracy than traditional bows, attracting both experienced archers and new participants. Their technological advancements are driving significant market expansion.
Rifles sits at the top of the volume ranking, with Crossbows climbing the fastest.
Accessory Type:
Cost tiers for hunting accessories vary significantly, from basic utility items to high-precision digital tools, influencing purchasing decisions across different hunter demographics. Premium accessories often integrate advanced technology, commanding higher price points.
- Scopes:These optical sighting devices magnify targets, providing precision for firearms over varying distances and light conditions. Integrated ballistic calculators and low-light performance drive demand among serious hunters.
- Holsters:Designed for secure and accessible firearm carry, holsters prioritize safety and comfort for hunters in diverse environments. Material science improvements enhance durability and fit.
- Knife Sets:Essential tools for field dressing and processing game, knife sets emphasize sharpness, durability, and ergonomic design. High-carbon steel blades are a common requirement.
- Range Finders:Digital laser range finders accurately measure distance to targets, crucial for precise shot placement with firearms and bows. Their integration with smart optics is a key technological trend.
The application of advanced optics and digital integration heavily influences the market for accessories, with high-performance scopes seeing strong demand.
End User:
The volume of equipment purchased by different end-user segments shapes product development priorities, as manufacturers respond to the specific needs of each group. High-volume segments often drive standardization, while niche segments demand specialization.
- Professional Hunters:This segment requires highly specialized, reliable, and durable equipment capable of performing in extreme conditions. Their purchasing decisions prioritize function and proven performance.
- Enthusiasts:Dedicated enthusiasts seek versatile, high-performance gear that offers customization and technological integration. This group actively drives innovation and demand for premium products.
- Outfitters:Outfitters equip clients for guided hunts, requiring robust and dependable gear that can withstand frequent use. Their focus is on durability and ease of maintenance.
- Collectors:This segment values rare, antique, or custom-built firearms and accessories, often prioritizing craftsmanship and historical significance over practical hunting utility.
Enthusiasts represent the largest purchasing volume, while Professional Hunters demand the most specialized equipment.
Distribution Channel:
Customer type significantly impacts the preferred distribution channel, as hunters choose outlets based on convenience, product availability, and the need for expert advice. Online platforms cater to a broad base, while specialty stores serve specific needs.
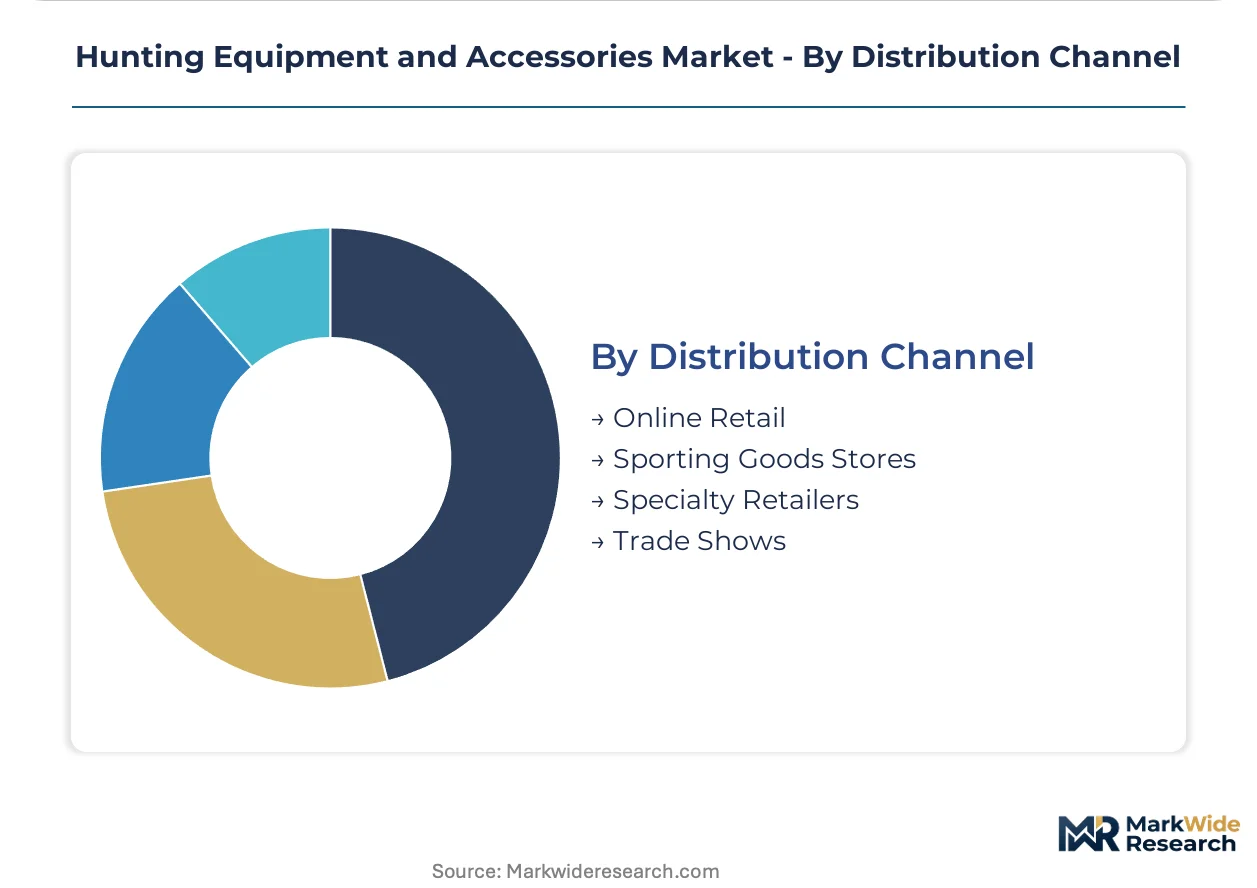
- Online Retail:This channel offers extensive product catalogs, competitive pricing, and convenience, appealing to a wide customer base across various geographies. Direct-to-consumer models are gaining traction.
- Sporting Goods Stores:These large format retailers provide a broad selection of hunting gear, allowing customers to physically inspect products and receive general advice. They serve a mainstream market.
- Specialty Retailers:Focused on specific product categories or premium brands, these stores offer expert knowledge and personalized service. They cater to experienced hunters seeking specialized equipment.
- Trade Shows:Industry trade shows allow manufacturers to showcase new products, engage directly with consumers, and facilitate wholesale orders. They serve as important platforms for brand building and product launches.
Online Retail provides extensive reach and convenience, whereas Sporting Goods Stores offer a tangible shopping experience for many consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global hunting equipment market sees regulatory frameworks influencing manufacturing decisions, creating arbitrage opportunities where production migrates due to varying compliance costs. Manufacturers balance strict firearm regulations in established markets with opportunities in regions offering more favorable operational environments. This dynamic shapes investment and supply chain strategies across continents.
United States
Demand for advanced firearms and high-performance archery gear drives innovation in the United States. Federal regulations from the US Bureau of Alcohol, Tobacco, Firearms and Explosives (ATF) govern firearm sales and features. The Midwest states, like Wisconsin, exhibit robust aftermarket customization for tactical and hunting rifles.
Germany
European demand for premium hunting optics and precision firearms remains strong in Germany. ECHA regulations under REACH compel manufacturers towards lead-free ammunition alternatives. The region around Suhl maintains a legacy of specialized firearm manufacturing and craftsmanship.
Poland
Rising disposable incomes in Poland fuel demand for modern hunting equipment and accessories. National wildlife management agencies set specific hunting seasons and weapon type restrictions. Krakow's growing outdoor retail sector supports the distribution of premium gear to enthusiasts.
Canada
Robust hunting traditions across Canada create steady demand for durable and weather-resistant equipment. Health Canada and provincial wildlife agencies enforce strict regulations on hunting seasons and weapon types. Vancouver's outdoor retail sector serves as a hub for specialized gear catering to diverse terrains.
China
Domestic manufacturing capabilities in China support global supply chains for hunting accessories. Strict national firearm control policies limit civilian ownership but allow for export-oriented production. Industrial clusters in Guangdong province specialize in producing composite materials for archery equipment.
Hunting Equipment and Accessories Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the hunting equipment market. The market exhibits a tiered structure, with premium brands focusing on technological innovation and mid-market players emphasizing versatility. Specialist manufacturers often integrate advanced materials science into their product lines. Companies pursue strategic partnerships for technology co-development and portfolio diversification to maintain competitive positioning.
Companies focusing on diversified portfolios and heritage brands shape the competitive landscape. Beretta Holding SA, an Italian-based company, exemplifies the premium market segment through its legacy of craftsmanship. Vista Outdoor Inc., a US-based corporation, occupies a position as a broad outdoor product supplier with a diverse portfolio. Under Armour Inc., another US-based entity, anchors the technical apparel segment, offering specialized gear for specific hunting environments.
| Leading Market Players |
|---|
| Sturm, Ruger and Co Inc |
| Buck Knives Inc. |
| Beretta Holding SA |
| Leupold & Stevens Inc. |
| Under Armour Inc. |
| Vista Outdoor Inc. |
| Browning Arms Company |
| Savage Arms |
| American Outdoor Brands Corp. |
| Others |
Cost & Logistics Intelligence
The European Chemicals Agency (ECHA) lead-free ammunition mandate gates qualified supply channels and restricts access to premium-tier pricing for non-compliant manufacturers. This regulatory pressure directly impacts both component sourcing and final product cost structures across the hunting equipment market.
Pricing Analysis
Retailer markups significantly influence the per-unit transactional pricing model for hunting equipment. Price differentiation stems from the brand premium associated with established firearms manufacturers and the customization level offered for modular components. Cost compression in specialty materials is intensifying due to supply chain disruptions, leading to pricing softness across mid-tier accessories. Enthusiasts are least price-sensitive, valuing performance and technology, while mainstream sporting goods store buyers exhibit higher sensitivity to price points.
Supply Chain Analysis
Specialty retailers and online platforms constitute the dominant downstream distribution model for hunting equipment. China and Germany concentrate specialized component manufacturing, particularly for optical glass and advanced composite materials, while the United States provides a robust aftermarket ecosystem. High-grade optical glass for scopes and carbon fiber composites for bows are critical raw material dependencies. Commodity price volatility for specialty steels creates margin pressure for manufacturers, representing a structural supply chain risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hunting equipment market functions as a stable compounder, driven by sustained participation in wildlife management programs and technological integration.
For Market Incumbents: To counter the proliferation of counterfeit products, incumbent manufacturers should invest in advanced anti-counterfeiting technologies. Pursue strategic partnerships for technology co-development, leveraging existing distribution channels to maintain market share. Diversify product lines into high-growth areas like digital accessories and high-performance crossbows. Focus R&D on advanced materials science to enhance product durability and reduce weight.
For New Entrants and Emerging Players: Smart optics technology offers a technology-first wedge for new entrants targeting the enthusiast segment. Focus on developing interconnected digital accessory ecosystems that enhance hunter efficiency. Female-specific product lines represent an underserved segment with specific fit and performance needs. Direct-to-consumer online sales with strong community engagement can provide an effective go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for specialized accessory manufacturers because market fragmentation presents clear synergy opportunities. Long-term viability rests on adapting to regulatory shifts and technological advancements in non-lead ammunition and smart equipment. Target mid-sized firms with strong intellectual property in digital integration or advanced materials. Adoption rates of lead-free ammunition across new jurisdictions represent a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Lead-Free Ammunition Lines | Addresses ECHA regulations, securing market access in European regions. |
| Integrate Smart Optics with Ballistic Calculators | Enhances hunter efficiency and precision, appealing to technology-driven enthusiasts. |
| Expand into Eastern European Markets | Capitalizes on rising disposable incomes and established hunting traditions in Poland. |
| Launch Female-Specific Apparel and Gear | Captures an underserved demographic with ergonomically tailored products. |
| Strengthen Anti-Counterfeiting Measures | Protects brand integrity and user safety against fraudulent high-performance accessories. |
Research Approach
Multiple input streams — industry association reports, manufacturer financial statements, and regulatory body publications — were reconciled for comprehensive data collection. Primary interviews were conducted with hunting equipment R&D directors, retail channel managers, wildlife conservation officials, and end-user enthusiasts. Secondary validation utilized ATF firearm sales data, ECHA chemical regulations, national wildlife agency reports, and customs data for trade flows. Bottom-up market sizing was validated against top-down industry revenue figures.
Historical market performance was cross-referenced with expert panel input to establish a robust forecast framework. The analytical framework integrates supply-side capacity and demand-side adoption rates across the analysis window. Segmentation dimensions included product type, accessory type, end-user, and distribution channel, alongside regional regulatory compliance. Compound Annual Growth Rates were derived from projected shifts in technology integration and consumer preferences, informed by hunting license sales data and advanced materials cost trends.
The model holds under current regulatory stability and projected technological adoption rates; deviation in firearm legislation or material science breakthroughs would shift market trajectories. Geopolitical events affecting supply chains or significant changes in wildlife conservation policies represent key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Mountain Bicycles Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Gym Shoes Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Wave Windsurf Boards Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Quad Skate Market
Sports Equipment
Sponge Wrestling Mat Market
Sports Equipment
Baseball Sliding Mitts Market
Sports Equipment
Fishing Rods Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Licensed Sports Merchandise Market