
 Baseball Equipment Market | 2026-2036
Baseball Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Baseball Equipment Market Intelligence
The baseball equipment sector is restructuring around a widening gap between premium composite bats and commodity aluminum models. Louisville Slugger leverages its heritage wood bat craftsmanship to anchor the high-performance segment. Mizuno Corp. sustains its position through specialized glove leather tanning and Japanese manufacturing precision. Franklin Sports Inc. competes aggressively in the entry-level protective gear tier through mass retail channel control.
Baseball equipment encompasses bats, gloves, balls, and protective gear engineered to specific performance standards such as BBCOR certification for collegiate bats and USA Baseball stamp requirements for youth leagues. Aluminum and composite materials dominate bat construction, while full-grain steerhide remains the standard for professional-grade gloves due to its break-in characteristics and durability. The bats segment leads in absolute revenue contribution, though protective gear registers the fastest structural expansion as concussion awareness elevates helmet and face guard replacement cycles. Online retailers are capturing disproportionate growth within distribution channels, eroding the historical dominance of sporting goods stores.
The Consumer Product Safety Commission enforces youth baseball bat performance standards, while the National Federation of State High School Associations governs equipment eligibility rules that directly shape manufacturer design priorities. ASTM International maintains impact testing protocols for helmets and chest protectors that determine market access for protective gear suppliers. Stakeholders must monitor evolving material regulations and channel migration patterns to calibrate production allocation and certification investments.
Market Dynamics
The baseball equipment sector is restructuring around material transitions mandated by USA Baseball standards, which are compressing wood bat volumes while elevating composite and aluminum specifications across youth leagues.
Growth Catalysts
- USA Baseball Youth Standards:The stamp requirement for youth league bats is forcing equipment upgrades across American amateur leagues, accelerating replacement cycles for non-compliant inventory.
- Concussion Protocol Expansion:High school athletic associations in Texas and California are mandating enhanced helmet and face guard specifications, elevating protective gear procurement volumes.
- Composite Material Advancement:Carbon fiber layering techniques are improving bat sweet spot consistency, drawing performance-oriented buyers away from traditional aluminum construction.
Market Restraints
- Tariff Exposure on Taiwan Sourcing:Finished bat and glove imports face elevated duty uncertainty, pressuring margin structures for brands dependent on Taiwanese OEM partnerships.
- Steerhide Supply Concentration:Professional-grade glove leather sourcing clusters in Midwestern American tanneries, creating bottleneck risk during peak preseason procurement windows.
- BBCOR Performance Ceiling:The NCAA-mandated batted-ball speed limit caps innovation potential in collegiate aluminum bats, compressing premium pricing power.
Strategic Opportunities
- Direct-to-Consumer Channel Buildout:Custom bat configuration platforms are capturing margin previously ceded to sporting goods retailers, with Marucci Sports and Warstic demonstrating viable models.
- Mexico Manufacturing Migration:Labor cost differentials and USMCA tariff advantages are drawing glove stitching and assembly operations away from Chinese facilities.
- Sensor-Enabled Training Integration:Swing analytics hardware is converging with bat purchases, creating bundled equipment-software offerings for academy and travel ball segments.
Industry Challenges
- Multi-Sport Athlete Retention:Youth specialization pressure and lacrosse-soccer crossover competition are compressing baseball participation rates in suburban Midwestern districts.
- Certification Timeline Compression:The gap between USA Baseball standard updates and laboratory testing capacity is delaying new product launches through peak retail seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baseball Equipment Market |
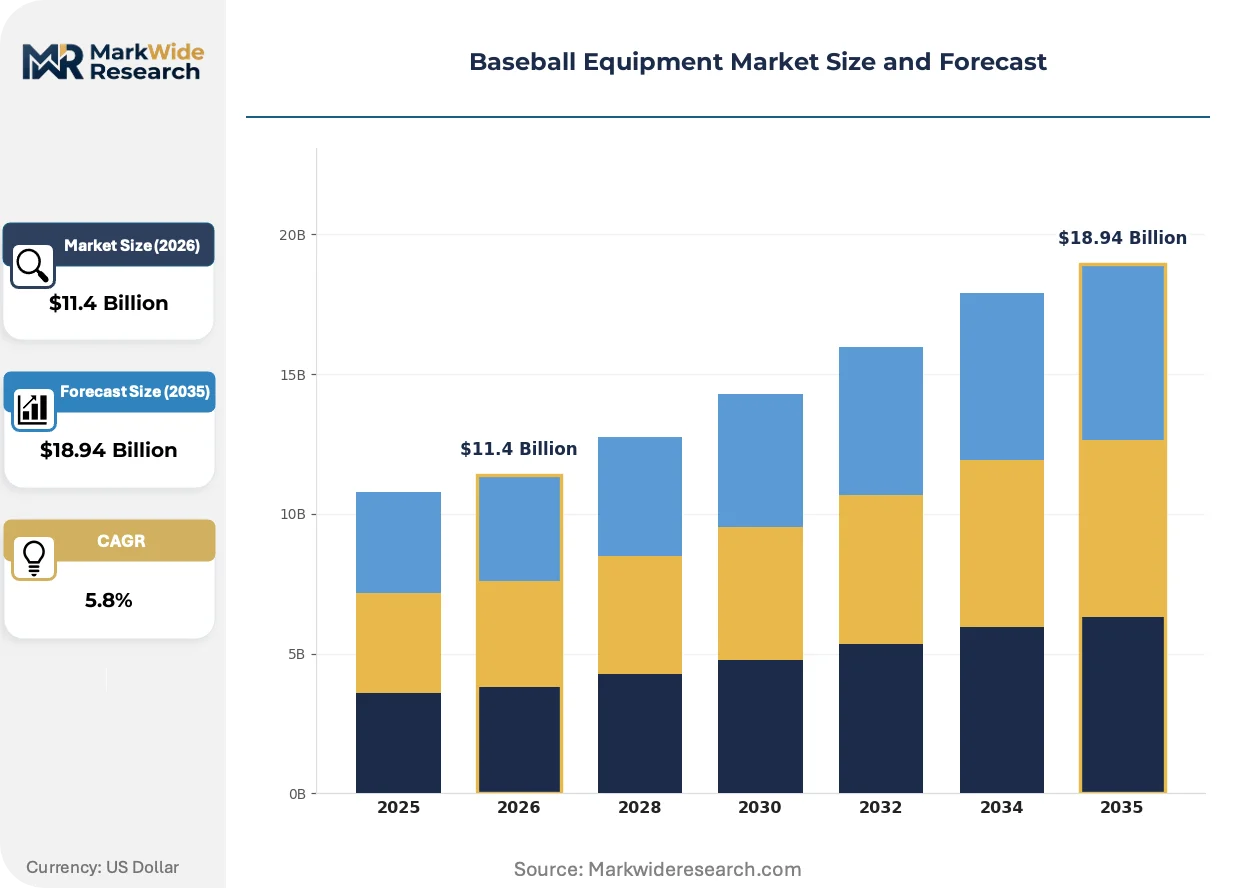
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bats, Gloves, Balls, Protective Gear End User: Professional Teams, Amateur Players, Schools, Recreational Leagues Material: Aluminum, Composite, Wood, Leather Distribution Channel: Online Retailers, Sporting Goods Stores, Specialty Shops, Direct Sales |
| Companies Covered | Mizuno Corp., Under Armour Inc., Nike Inc., Louisville Slugger, Franklin Sports Inc., Adidas AG, Amer Sports Corp., Easton Diamond Sports LLC, Rawlings Sporting Goods Co. Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baseball Equipment Market Strategic Shifts & Innovations
Material science and distribution architecture are the primary vectors of change, with composite formulations and channel control determining competitive outcomes more than brand heritage alone.
Multi-wall composite bat construction is consolidating performance advantages previously scattered across aluminum alloy grades. Travel ball programs and collegiate summer leagues are adopting these models at accelerated replacement intervals. The technology is consolidating market share around three dominant suppliers who control proprietary resin formulations and layup patents.
ASTM International updated its F2397 helmet impact standard in 2023, mandating expanded coverage zones and face guard attachment protocols. Manufacturers must retool mold designs and absorb recertification costs before the 2025 youth league season. Chest protector suppliers serving the catcher segment face the steepest compliance timeline, with several mid-tier brands exiting rather than absorbing redesign expenses.
Club and academy buyers are consolidating purchasing through specialized distributors who bundle uniforms, equipment, and facility services. This procurement consolidation is displacing the fragmented coach-directed ordering that historically drove retail foot traffic. The shift is most visible in Florida and Arizona, where year-round training facility density supports dedicated baseball-only supply contracts.
Baseball Equipment Market Segmentation
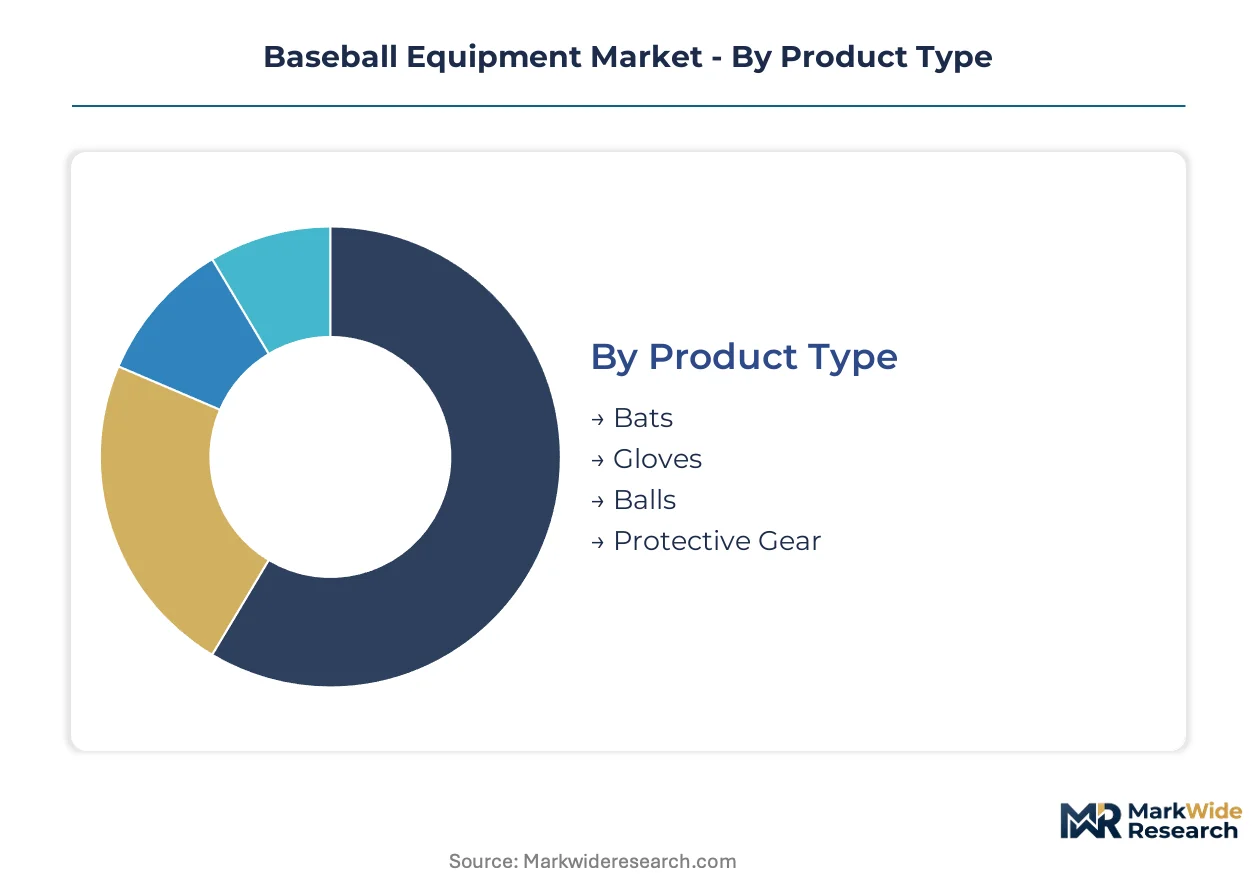
Equipment replacement cycles and regulatory compliance mandates are fragmenting demand across distinct performance tiers. Manufacturers calibrate production allocation by matching material specifications to the certification requirements governing each user segment.
Product Type:
USA Baseball stamp requirements and BBCOR certification rules are compressing replacement intervals and forcing inventory turnover across all four equipment categories.
- Bats:Aluminum and composite constructions dominate volume, with multi-wall carbon fiber layering improving sweet spot consistency. High school athletic associations in Texas and California are mandating enhanced specifications, accelerating procurement from travel ball programs and collegiate summer leagues.
- Protective Gear:Helmets and face guards incorporate expanded coverage zones under ASTM F2397 protocols. Concussion protocol expansion across suburban Midwestern districts elevates replacement frequency beyond traditional seasonal cycles.
- Gloves:Full-grain steerhide construction remains the professional standard, with break-in characteristics determining grade differentiation.
- Balls:Cork-centered wound yarn specifications vary by league tier, from youth league reduced-impact models to professional-grade raised seam designs.
Volume placements concentrate in Bats; the faster expansion belongs to Protective Gear.
End User:
Procurement authority and budget scale create four distinct purchasing behaviors, from centralized professional sourcing to fragmented recreational ordering.
- Professional Teams:Equipment managers negotiate direct manufacturer relationships for custom specifications. MLB clubhouses in Florida and Arizona anchor preseason procurement volumes through dedicated supply contracts.
- Amateur Players:Individual buyers prioritize performance-to-price ratios, with travel ball parents driving premium composite bat adoption. This segment gains share fastest as academy and club program density increases year-round training participation.
- Schools:District-level purchasing consolidates across multiple sports, compressing baseball-specific line item budgets.
- Recreational Leagues:Volunteer-coordinated ordering favors entry-level price points and mass retail accessibility.
Professional Teams anchor absolute dollar volume; Amateur Players show the steepest expansion trajectory.
Material:
Performance standards and tariff exposure are reshaping material selection priorities across the manufacturing base.
- Composite:Proprietary resin formulations and carbon fiber layup patents consolidate supply around three dominant suppliers. The technology is displacing aluminum in travel ball and collegiate summer league channels.
- Aluminum:BBCOR performance ceilings cap innovation potential, compressing premium pricing power in collegiate specifications.
- Wood:Heritage craftsmanship anchors commemorative and professional practice segments, with Louisville Slugger's ash and maple sourcing sustaining niche demand.
- Leather:Midwestern American tanneries concentrate professional-grade glove leather supply, creating bottleneck risk during peak preseason windows.
Composite captures the fastest volume growth; Aluminum retains the largest installed base.
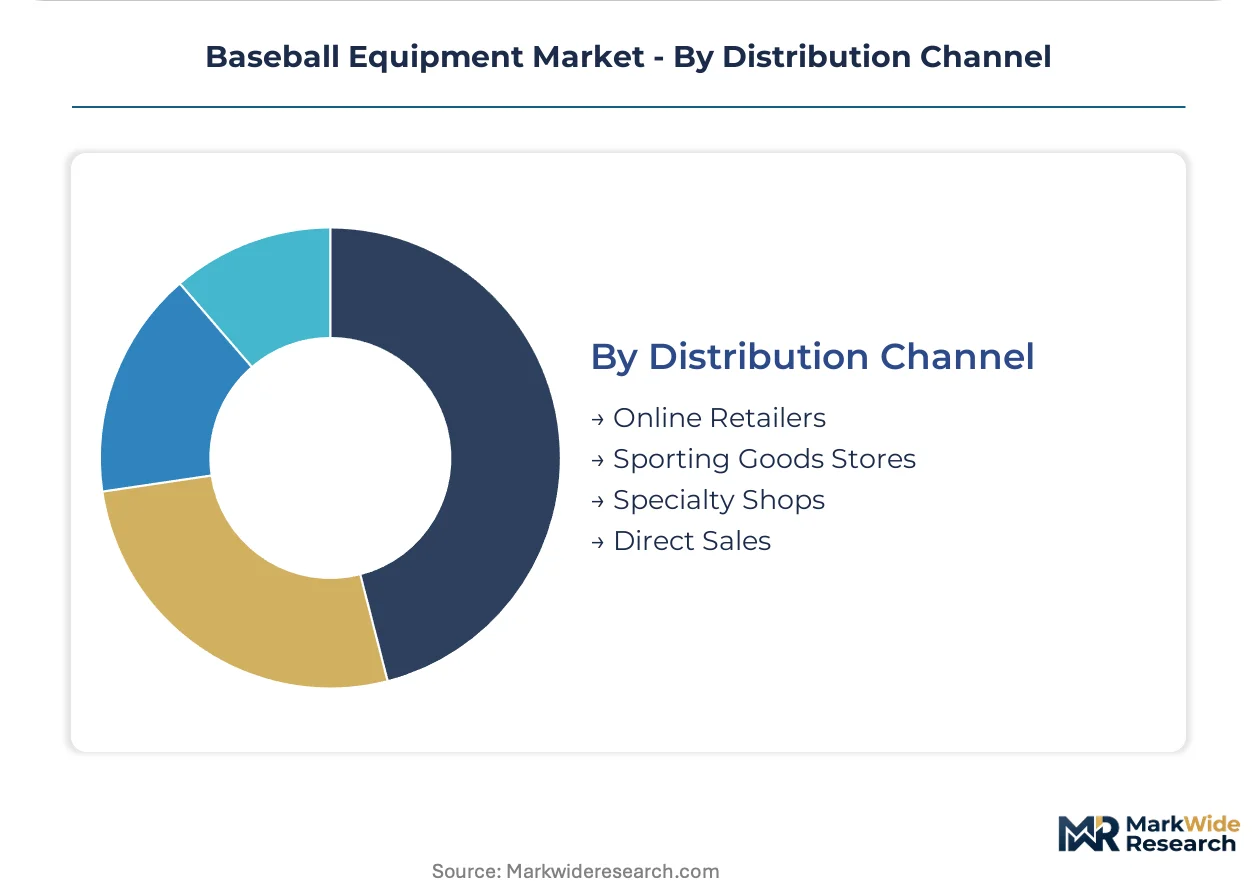
Distribution Channel:
Channel migration patterns are reallocating margin capture from traditional retail to direct and digital platforms.
- Online Retailers:Custom bat configuration platforms capture margin previously ceded to sporting goods retailers. Marucci Sports and Warstic demonstrate viable direct-to-consumer models with academy and travel ball penetration.
- Sporting Goods Stores:Historical foot traffic dominance erodes as club and academy buyers consolidate purchasing through specialized distributors.
- Specialty Shops:Fitting expertise and local league relationships sustain relevance in glove and protective gear categories.
- Direct Sales:USMCA tariff advantages and labor cost differentials draw Mexico-based manufacturing toward captive distribution networks.
Online Retailers expand most quickly; Sporting Goods Stores defend the largest transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangzhou anchors composite bat manufacturing through its Pearl River Delta industrial corridor, where carbon fiber layup facilities cluster near polymer resin suppliers. Mexico's Bajío region draws glove assembly migration via USMCA tariff advantages and labor cost differentials.
United States
Youth league participation drives equipment procurement across Texas and California, where high school athletic associations mandate enhanced helmet specifications. The Consumer Product Safety Commission enforces youth baseball bat performance standards that shape manufacturer design priorities. Louisville, Kentucky sustains heritage wood bat craftsmanship while Arizona and Florida host MLB preseason training facilities that anchor professional-grade supply contracts.
China
Taiwanese OEM partnerships concentrate finished bat and glove production in coastal manufacturing zones for export to North American markets. GB standards and MIIT oversight govern domestic product quality frameworks. Dongguan and Shenzhen industrial parks house carbon fiber preprocessing facilities that feed composite material supply chains.
Mexico
USMCA tariff advantages draw glove stitching and assembly operations away from Chinese facilities into Nuevo León and Jalisco production zones. Labor cost differentials support margin recovery for brands facing duty uncertainty on Asian sourcing. The Bajío region emerges as a secondary cluster for protective gear component manufacturing.
Japan
METI industrial policy supports precision manufacturing in Osaka-based glove leather tanning operations that supply professional-grade equipment. Domestic demand concentrates in Kansai and Kanto regions where youth baseball maintains cultural priority. JIS standards certification requirements filter market access for imported protective gear.
Taiwan
Finished bat and glove exports face elevated duty uncertainty that pressures margin structures for dependent brands. The island's OEM fabricators serve as critical intermediaries between Chinese material suppliers and North American brand owners. Kaohsiung industrial corridors concentrate composite preprocessing capacity.
Baseball Equipment Market Key Industry Players
Capital-heavy producers compete with asset-light designers across a tiered structure where heritage brands anchor premium positioning while mass-market specialists control retail channel access. Three strategic archetypes dominate: wood-craft heritage houses leveraging century-old brand equity, precision manufacturers emphasizing Japanese or European tanning traditions, and mass-market distributors optimizing sporting goods store penetration. Consolidation pressure intensifies through direct-to-consumer platform buildout and Mexico manufacturing migration.
Within the heritage-craft tier, Louisville Slugger exemplifies wood-bat authenticity anchoring high-performance segments, while Mizuno Corp. represents Japanese manufacturing precision in glove leather tanning. Franklin Sports Inc. occupies the mass-market protective gear position through retail channel density. These three archetypes illustrate how brand positioning stratifies across premium craftsmanship, technical specialization, and volume accessibility.
| Leading Market Players |
|---|
| Mizuno Corp. |
| Under Armour Inc. |
| Nike Inc. |
| Louisville Slugger |
| Franklin Sports Inc. |
| Adidas AG |
| Amer Sports Corp. |
| Easton Diamond Sports LLC |
| Rawlings Sporting Goods Co. Inc. |
| Others |
Cost & Logistics Intelligence
Composite bat manufacturing transitions from aluminum extrusion to carbon fiber layup, simultaneously elevating raw material costs and concentrating production around three resin-formulation patent holders. This technology shift compresses margins for second-tier brands while amplifying pricing power for vertically integrated producers controlling proprietary layup techniques.
Pricing Analysis
Performance-based pricing anchored to BBCOR and USA Baseball certification tiers stratifies the market across premium composite, standard aluminum, and economy wood bat segments. Price differentiation hinges on certification grade and volume scale, with travel ball programs commanding bulk discounts unavailable to individual recreational buyers. Pricing pressure stems from tariff exposure on Taiwanese OEM sourcing, compressing margins for brands without Mexico manufacturing alternatives. Recreational league coordinators exhibit highest price sensitivity, while professional equipment managers prioritize performance consistency over unit cost.
Supply Chain Analysis
USMCA domestic-content provisions are accelerating glove assembly migration from Chinese facilities to Nuevo León and Jalisco production zones. Geographic supply concentration centers on China, Taiwan, and Mexico for finished goods, with Midwestern American tanneries anchoring professional-grade leather feedstock. Raw material dependencies include carbon fiber preprocessing from Dongguan, polymer resin formulations from Kaohsiung, and full-grain steerhide from domestic tanneries. Tariff exposure on Taiwanese imports constitutes the primary structural risk. Distribution runs through direct-to-consumer platforms, specialized academy distributors, and eroding sporting goods retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around certification-capable producers, with ASTM F2397 compliance timelines and USA Baseball standard updates forcing mid-tier protective gear brands toward exit.
For Market Incumbents: Anticipate certification timeline compression by securing laboratory testing partnerships ahead of standard updates. Backward integration into Mexico glove assembly insulates margin structures from Taiwanese tariff volatility. Channel control through academy distributor exclusivity defends position against direct-to-consumer entrants.
For New Entrants and Emerging Players: Begin with sensor-enabled training hardware bundled with bat purchases, targeting the academy and travel ball white space in Florida and Arizona. Custom configuration platforms offer the most penetrable entry angle, with performance analytics software providing recurring revenue attachment to equipment sales.
For Investors and Strategic Acquirers: Exit pathways concentrate in heritage-brand acquisition by sporting goods conglomerates seeking authentic craft positioning. Long-term viability favors producers with captive resin formulation patents and USMCA-qualifying manufacturing footprints. The signal to watch is USA Baseball standard update frequency accelerating replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Buildout | Marucci Sports and Warstic demonstrate custom bat configuration capturing margin from retailers. |
| Mexico Manufacturing Migration | USMCA tariff advantages draw glove stitching from Chinese facilities into Nuevo León production zones. |
| Sensor-Enabled Training Integration | Swing analytics hardware convergence creates bundled equipment-software offerings for academy segments. |
| Certification Pre-Investment | ASTM F2397 helmet standard compliance secures market access ahead of 2025 youth league season. |
| Resin Formulation Patent Acquisition | Proprietary carbon fiber layup patents consolidate supply around dominant composite bat producers. |
Research Approach
Trade databases, athletic association procurement records, and CPSC regulatory filings formed the secondary backbone for this analysis. Primary interviews with equipment managers at MLB spring training facilities, youth league program directors, sporting goods retail buyers, and composite material procurement leads at Taiwanese OEMs validated demand assumptions. Bottom-up unit shipment estimates across bats, gloves, protective gear, and balls were triangulated against top-down manufacturer revenue disclosures.
Historical trendline analysis established baseline growth patterns across the projection horizon, with segmentation modeling incorporating product type, end user tier, material specification, and distribution channel. CAGRs were derived from regression analysis against youth participation rates, replacement cycle intervals, and regulatory compliance mandates. Forecast inputs included USA Baseball standard adoption curves, concussion protocol expansion trajectories, and channel migration velocity from retail to direct platforms.
Tariff rate volatility, ASTM certification timeline delays, and multi-sport athlete retention erosion are the dominant revision risks to modeled outputs. Forecasts reflect assumptions regarding regulatory stability and material cost trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Cleat Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Rally Sport Riding Gear Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Dirt Bike Market
Sports Equipment
Global Horse Riding Equipment Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Global Badminton Equipment and Facilities Market
Sports Equipment
Concussion Helmets Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Global Basketball Shoes Market
Sports Equipment
Cricket Equipment Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Sports Devices Market