
 Starting Blocks Market | 2026-2036
Starting Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Starting Blocks Market Analytics
Italian synthetic track manufacturers is recalibrating global supply chains for competition-grade athletics equipment. MONDO leverages its vertical integration in vulcanized rubber surfaces to dominate Olympic-specification starting block procurement. MSR anchors its position through specialized aluminum alloy casting operations serving European championship venues. Stackhouse Athletic Equipment competes on domestic manufacturing scale within North American scholastic track programs.
Starting blocks are mechanical foothold devices engineered with adjustable pedal angles, high-friction base plates, and spring-loaded release mechanisms to optimize sprint launch biomechanics; aluminum and rubber composite construction delivers the strength-to-weight ratio and ground adhesion required for elite competition. The premium product tier captures margin pools through World Athletics certification requirements that exclude uncertified equipment from sanctioned events. Aluminum material segments sustain pricing power due to CNC machining complexity and durability specifications, while portable configurations expand addressable demand among training facilities with multi-surface usage requirements.
World Athletics technical rules, ISO 9001 quality management standards, and national sports federation procurement codes collectively govern product certification and market access for competition-grade equipment. The European Union's REACH chemical safety framework restricts certain rubber vulcanization additives, prompting material reformulation across supply chains. Stakeholders must monitor evolving biomechanical research on pedal angle optimization and anticipate regulatory harmonization between World Athletics specifications and emerging national standards in Asian markets.
Market Dynamics
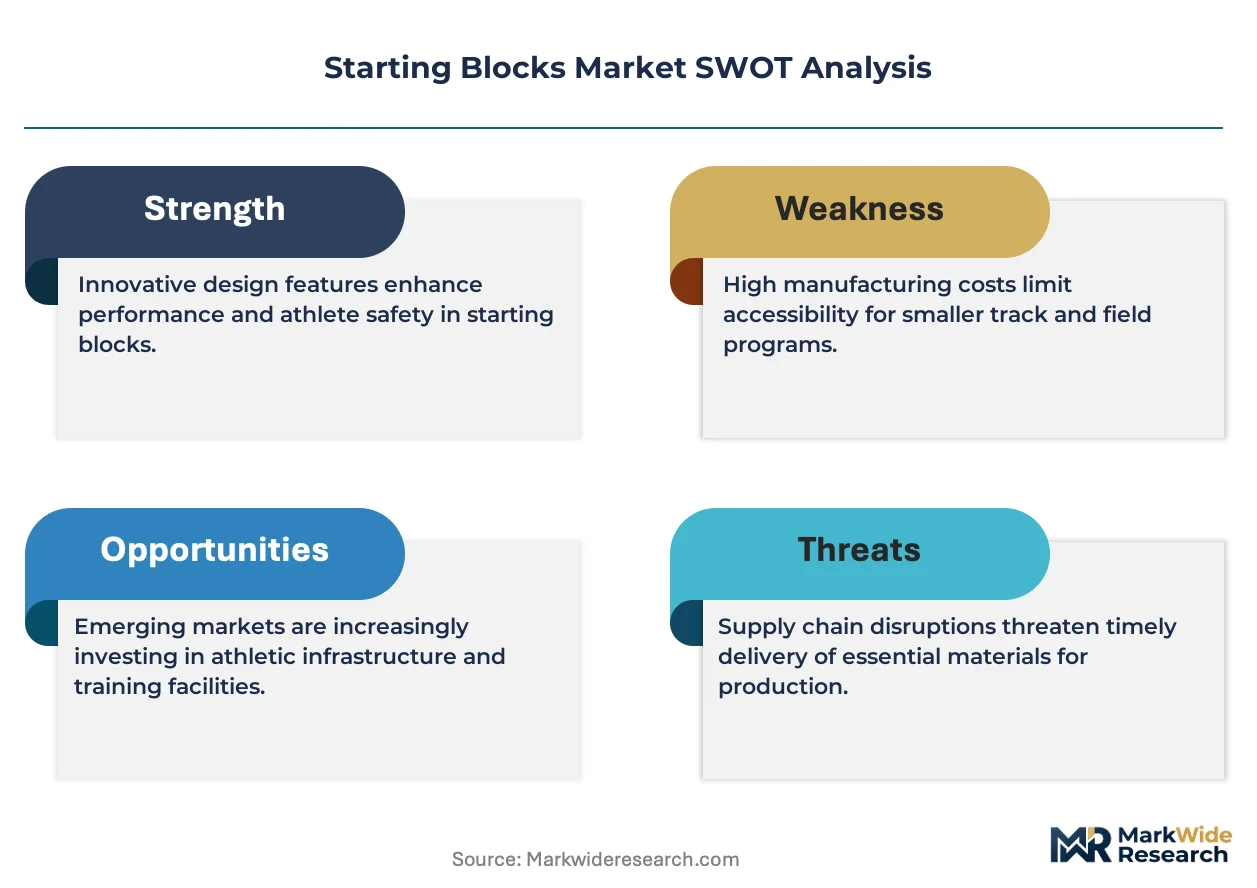
World Athletics certification tightening is compressing vendor margins while concentrating procurement authority among national federation technical committees that specify Olympic-grade equipment. This regulatory intensification forces manufacturers to absorb compliance costs or exit sanctioned competition segments entirely.
Growth Catalysts
- Biomechanical research advancement:Pedal angle optimization studies from university sports science departments are validating adjustable block designs for training facilities seeking measurable performance gains.
- REACH material reformulation:The European Union's chemical safety framework is accelerating rubber composite innovation that transfers to competition-grade starting block construction.
- China infrastructure investment:Provincial sports bureaus are expanding elite track construction under national athletic development mandates, creating certified equipment demand clusters in Shanghai and Guangdong.
Market Restraints
- Aluminum alloy price volatility:CNC-machined pedal components face input cost pressure from aerospace and automotive sector competition for 6061-T6 and 7075-T6 billet stock.
- Italian supply concentration:Vulcanized rubber base plate production clusters in northern Italy create geographic single-point vulnerability for World Athletics-certified manufacturers.
- Portable configuration durability limits:Lightweight designs sacrifice structural longevity, constraining product lifecycle economics for high-frequency training environments.
Strategic Opportunities
- Indian scholastic expansion:State-level school athletics programs under Khelo India initiative lack certified equipment penetration, creating first-mover positioning for compliance-ready suppliers.
- Sensor integration convergence:Force plate technology and wireless timing systems are enabling smart starting blocks with real-time biomechanical feedback for elite training centers.
- German environmental procurement codes:Federal sustainability mandates for public sports infrastructure are favoring low-carbon aluminum sourcing and recyclable rubber formulations.
Industry Challenges
- World Athletics certification timeline compression:Equipment approval cycles now span 18-24 months for design modifications, freezing product development roadmaps and straining R&D amortization.
- Legacy track surface incompatibility:Existing polyurethane installations from pre-2010 construction waves lack standardized anchor point spacing, complicating block retrofit deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starting Blocks Market |
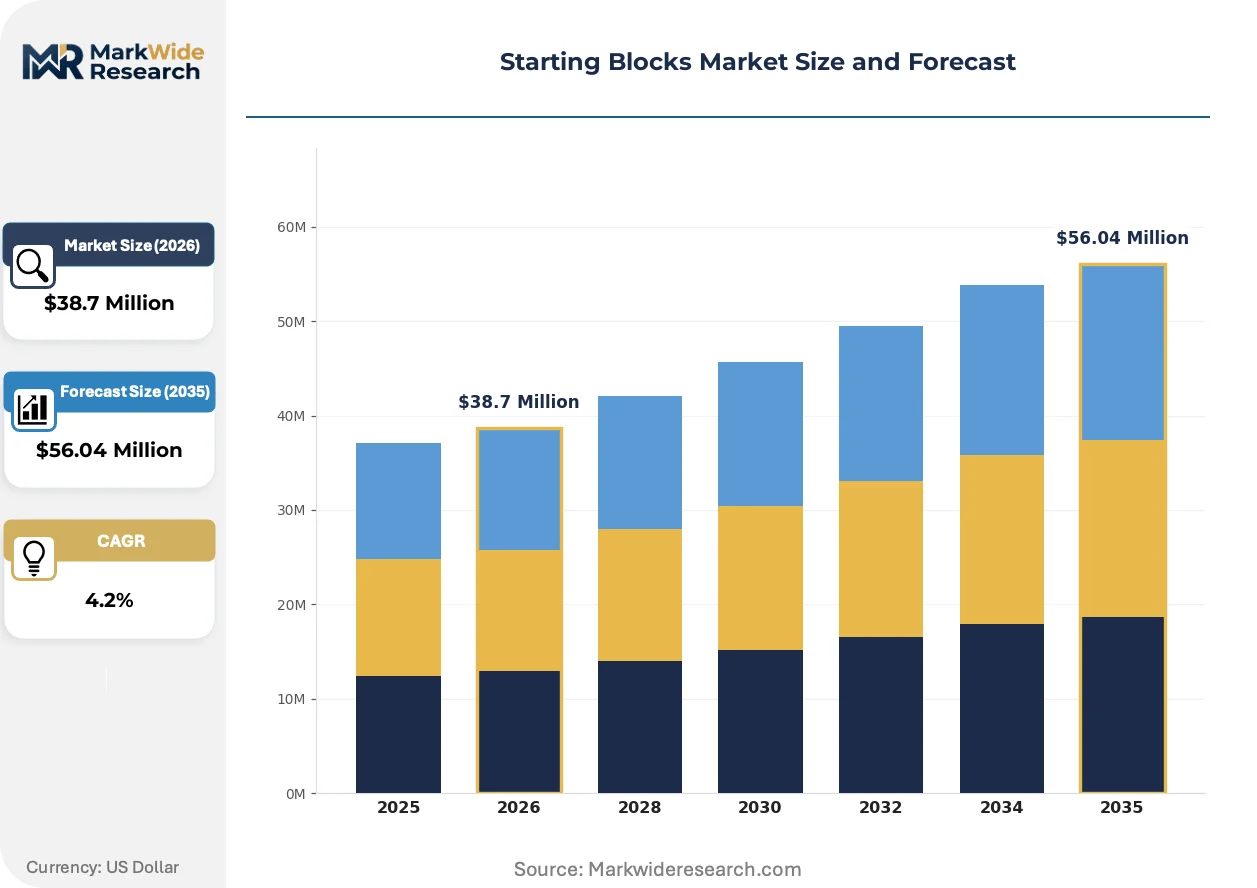
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Use, Premium, Portable, Adjustable Material: Rubber, Aluminum, Plastic, Steel End User: Track Athletes, Coaches, Training Facilities, Schools Feature: Foldable, Shock Absorbing, Customizable, Lightweight |
| Companies Covered | MONDO, MSR, HART Sport, Stackhouse Athletic Equipment, Champion Sports, BSN Scholastic, Universal Services, DIMASPORT, Khalsa Gymnastic Works, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starting Blocks Market Evolving Landscape
Competitive positioning is fragmenting across three vectors: sensor-enabled performance analytics, sustainable material substitution, and procurement centralization through federation-level framework agreements. These forces are compressing traditional equipment margins while opening premium service attach-rate pools.
Carbon fiber reinforced polymer pedal construction is unifying strength-to-weight performance previously split between aluminum structural frames and rubber contact surfaces. NCAA Division I programs and European national training centers are adopting these hybrid designs at accelerating replacement cycles. The technology is unifying previously separate equipment categories into integrated sprint-launch systems that bundle blocks, timing gates, and force measurement.
REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons in rubber vulcanization are forcing compound reformulation across EU-based manufacturers. Industrial consequence includes 12-18 month material qualification periods that freeze supplier switching. German and French federation procurement specifications now embed these chemical compliance requirements as mandatory bid prerequisites.
Framework contracting is consolidating purchasing authority from individual venues to national sports confederations with centralized technical specifications. Traditional distributor networks serving independent athletic clubs are losing volume to direct federation procurement portals. This concentration is most visible in United States collegiate athletics through NCAA equipment standardization initiatives and in China's provincial sports bureau central purchasing platforms.
Starting Blocks Market Segmentation
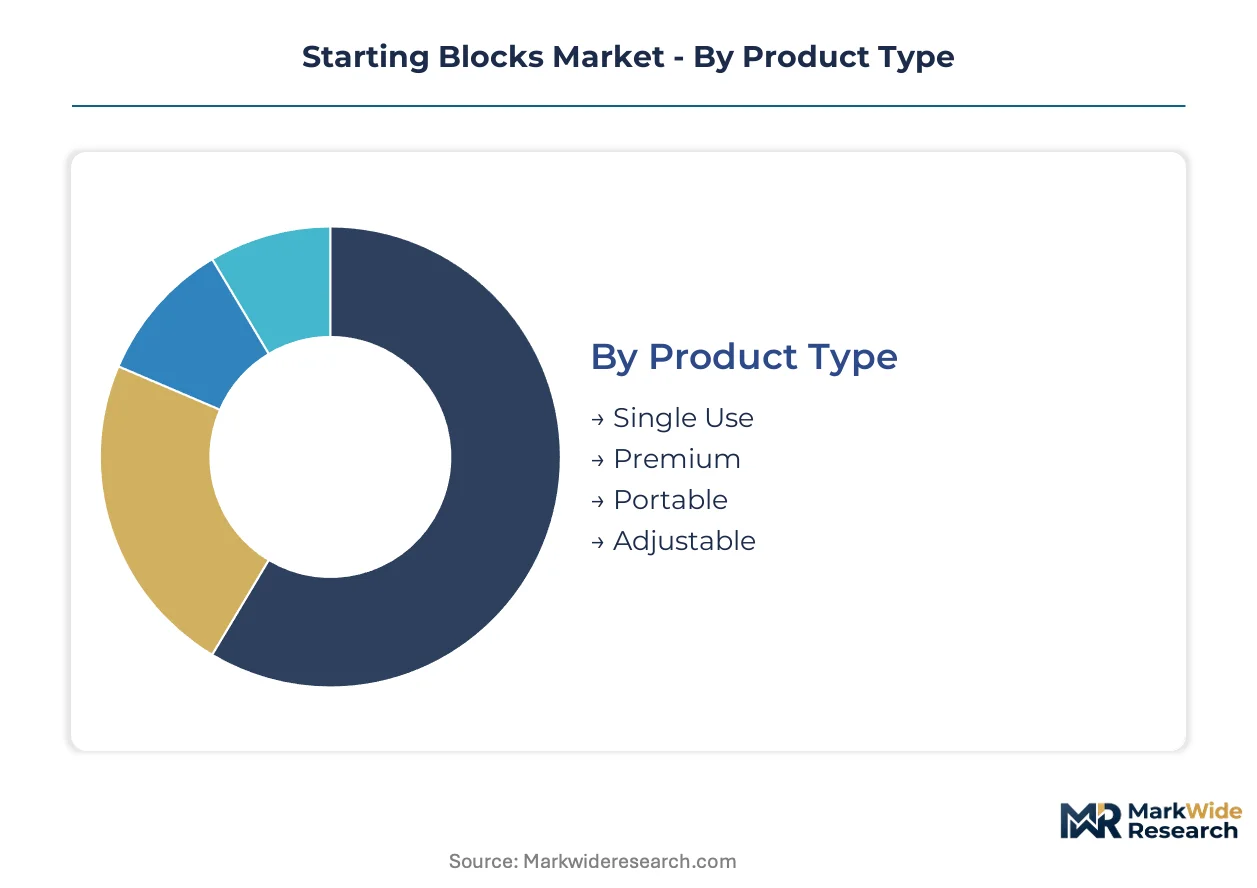
Starting blocks manufacturers face divergent certification burdens across product tiers, with World Athletics approval requirements filtering addressable demand and shaping R&D allocation. Segmentation reveals where compliance costs concentrate and which material-product combinations unlock premium pricing.
Product Type:
World Athletics certification mandates apply differentially across product tiers, with competition-grade equipment requiring 18-24 month approval cycles while training-grade products face lighter technical scrutiny.
- Adjustable:Pedal angle mechanisms with CNC-machined aluminum components dominate elite competition procurement. NCAA Division I programs and Chinese provincial training centers are expanding orders for biomechanically optimized configurations that support force plate integration.
- Premium:Competition-specification blocks with vulcanized rubber base plates and spring-loaded release systems command certification-dependent pricing. German and French federation framework agreements now specify REACH-compliant rubber formulations as mandatory bid prerequisites.
- Portable:Lightweight designs sacrifice structural longevity for multi-surface deployment flexibility. Training facilities in the United States with shared-use track infrastructure represent the primary demand cluster.
- Single Use:Entry-level aluminum constructions serve scholastic programs with limited replacement budgets. Indian state-level school athletics initiatives under Khelo India are expanding first-time equipment procurement.
Leading the category by volume: Adjustable. Growing fastest: Portable.
Material:
Input cost structures and regulatory compliance timelines vary sharply across material categories, with aluminum facing aerospace sector billet competition while rubber compounds navigate REACH reformulation mandates.
- Aluminum:6061-T6 and 7075-T6 alloys deliver the strength-to-weight ratios required for CNC-machined pedal components. Price volatility from automotive and aerospace demand competition is compressing margins for mid-tier manufacturers.
- Rubber:Vulcanized base plate production concentrates in northern Italy, creating geographic supply vulnerability. ECHA REACH Annex XVII restrictions on polycyclic aromatic hydrocarbons are forcing 12-18 month material qualification cycles.
- Steel:Heavier constructions persist in budget-conscious scholastic procurement. Indian and Chinese domestic manufacturers maintain cost positioning through localized foundry operations.
- Plastic:Polymer composites serve portable and foldable configurations where weight reduction outweighs durability requirements. Recyclable formulations are gaining traction under German federal sustainability procurement codes.
Aluminum holds the largest volume share. Carbon fiber reinforced polymer hybrids are climbing the fastest as NCAA and European national training centers accelerate replacement cycles.
End User:
Procurement authority concentration varies dramatically across user types, with federation-level framework agreements displacing independent venue purchasing for elite segments while scholastic markets remain fragmented.
- Training Facilities:Multi-surface usage requirements drive demand for portable and adjustable configurations. Force plate integration and wireless timing system compatibility are emerging as technical specifications for premium procurement.
- Track Athletes:Individual elite competitors and their coaching teams specify World Athletics-certified equipment for competition preparation. Personalized pedal angle optimization based on biomechanical research is shifting preference toward adjustable models.
- Schools:Budget-constrained procurement favors single-use aluminum constructions. Indian Khelo India initiative expansion and US scholastic program standardization are creating volume demand clusters.
- Coaches:Independent coaching operations represent fragmented demand with limited certification requirements. Secondary market equipment turnover is higher in this segment due to budget sensitivity.
Training facilities command the highest revenue per unit. Schools are expanding most quickly as national athletic development mandates proliferate across Asia-Pacific markets.
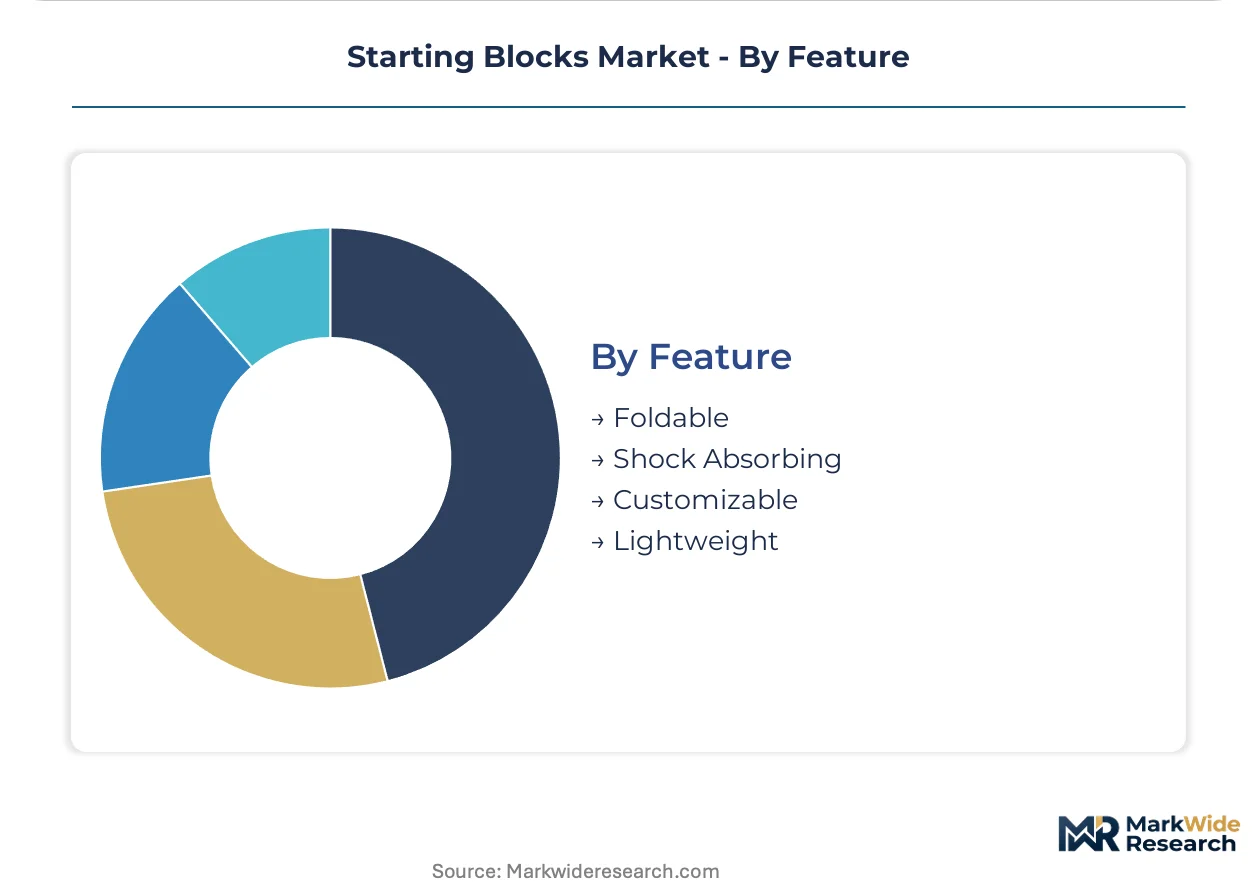
Feature:
Technical feature differentiation is converging with sensor integration and sustainability mandates, reshaping traditional equipment categories into bundled performance systems.
- Shock Absorbing:Vulcanized rubber composite constructions reduce joint stress during sprint launch. World Athletics technical specifications now incorporate impact attenuation metrics for certification eligibility.
- Customizable:Modular pedal and base plate configurations support athlete-specific biomechanical optimization. German environmental procurement codes are favoring designs with replaceable components to extend product lifecycle.
- Lightweight:Carbon fiber reinforced polymer and advanced aluminum alloys enable sub-5-kilogram competition specifications. Trade-offs in structural durability constrain deployment to low-frequency competition use.
- Foldable:Collapsible frames address storage constraints in multi-purpose training facilities. Chinese provincial sports bureau construction projects are specifying space-efficient equipment for urban venue footprints.
Shock absorbing features dominate competition-grade procurement. Customizable configurations are gaining share fastest as biomechanical research validates adjustable designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian vulcanized rubber production in northern Italy anchors competition-grade base plate supply chains for certified starting block manufacturers worldwide.
United States
NCAA Division I programs and scholastic track infrastructure drive adjustable block procurement with force plate integration requirements. Federal sustainability procurement guidelines under EPA recommendations favor low-carbon aluminum sourcing for public university athletic departments. California and Texas training facility clusters concentrate demand for portable multi-surface configurations.
Germany
Federal environmental procurement codes mandate REACH-compliant rubber formulations and recyclable components for public sports infrastructure investment. KBA-adjacent chemical safety standards influence material qualification timelines for base plate suppliers. Bavarian and North Rhine-Westphalian championship venues anchor European certification demand.
China
Provincial sports bureaus in Shanghai and Guangdong expand elite track construction under national athletic development mandates. SAMR standardization initiatives align domestic equipment certification with World Athletics technical specifications. Pearl River Delta manufacturing clusters supply aluminum pedal components for regional and export markets.
India
State-level school athletics programs under Khelo India initiative generate first-time certified equipment demand with limited vendor penetration. BIS quality standards for sports equipment are tightening import requirements for competition-grade blocks. Maharashtra and Karnataka urban training centers concentrate premium adjustable block procurement.
Starting Blocks Market Competitive Landscape
Global majors compete with regional champions across certification authority and material specialization. The vendor base stratifies between Olympic-specification suppliers with World Athletics approval and domestic fabricators serving training and scholastic segments. Three archetypes dominate: vertically integrated rubber-aluminum specialists, CNC-machining-focused component suppliers, and scale-driven scholastic equipment distributors. Competitive moves concentrate on federation framework contracting and REACH-compliant material reformulation partnerships.
Among Italian specialists, MONDO exemplifies the vertically integrated archetype through captive vulcanized rubber surface production. MSR occupies a position within European championship venue supply chains through specialized aluminum operations. Stackhouse Athletic Equipment represents North American domestic manufacturing scale serving scholastic procurement networks.
| Leading Market Players |
|---|
| MONDO |
| MSR |
| HART Sport |
| Stackhouse Athletic Equipment |
| Champion Sports |
| BSN Scholastic |
| Universal Services |
| DIMASPORT |
| Khalsa Gymnastic Works |
| Others |
Value Network & Pricing Analysis
London Metal Exchange aluminum alloy price indices cascade through starting block manufacturing into three distinct procurement tiers, with 6061-T6 and 7075-T6 billet volatility compressing margins for mid-tier CNC machining houses while federation-certified suppliers pass input costs through framework contract escalators.
Pricing Analysis
Service bundling separates competition-grade procurement from training-tier transactions, with World Athletics certification maintenance and pedal angle calibration support included in premium federation contracts while scholastic buyers face unbundled equipment-only pricing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales coverage depth. Cost compression in the mid-tier intensifies because aluminum billet competition from aerospace and automotive sectors is squeezing CNC machining houses. Schools and independent coaching operations exhibit highest price sensitivity, whereas national federation technical committees prioritize certification compliance over unit cost.
Supply Chain Analysis
Refurbishment flows for competition-grade starting blocks create secondary market circulation, with force plate integration upgrades extending product lifecycles in elite training centers. Vulcanized rubber base plate production concentrates in northern Italy, aluminum pedal component machining clusters in China's Pearl River Delta, and steel foundry operations localize in India and domestic Chinese facilities. Raw material dependencies rest on Italian rubber compound formulations, high-grade aluminum billet from aerospace suppliers, and REACH-compliant chemical additives. Single-source vulnerability in northern Italian rubber production threatens certified equipment supply continuity. Distribution runs through federation procurement portals displacing traditional venue-level distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
World Athletics certification timeline compression is consolidating vendor ranks, forcing capital-constrained manufacturers to exit sanctioned competition segments as compliance costs amortize across extended product development cycles.
For Market Incumbents: Extend certification maintenance capabilities into adjacent timing and force measurement equipment categories to capture bundled procurement authority from national federation technical committees. Deepen backward integration into REACH-compliant rubber compound formulation to insulate margin structures from ECHA regulatory revision cycles. Aluminum alloy price hedging programs and captive machining capacity in Guangdong province defend against aerospace sector billet competition. For New Entrants and Emerging Players: Direct-to-coach digital platforms bypass federation procurement concentration, enabling biomechanical customization services for independent training facilities and scholastic programs outside framework contract coverage. Indian state-level Khelo India equipment procurement represents the most penetrable geography, with first-mover positioning available for BIS-compliant suppliers before vendor consolidation hardens. Sensor integration partnerships with university sports science departments provide differentiated entry angles. For Investors and Strategic Acquirers: Distressed-cycle entries favor CNC-machining-focused component suppliers in Germany and Italy facing aluminum input cost pressure but holding World Athletics certification assets. Long-term viability over the coming decade hinges on federation framework contract renewal rates and sensor-enabled product transition execution. Monitor German federal environmental procurement code revisions for early signals of recyclable rubber formulation mandate acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA Annex XVII compliance unlocks German and French federation framework contract eligibility. |
| Sensor Integration Partnership | Force plate and wireless timing bundling captures NCAA Division I program upgrade cycles. |
| Provincial Sports Bureau Direct Contracting | Shanghai and Guangdong construction mandates bypass traditional distributor markups. |
| Carbon Fiber Pedal Hybrid Development | Strength-to-weight optimization accelerates replacement cycles at European national training centers. |
| Refurbishment Service Network Buildout | Secondary market equipment lifecycle extension counters portable configuration durability limits. |
Research Methodology
Federation procurement databases, World Athletics technical specification filings, and ECHA REACH regulatory archives formed the secondary backbone, supplemented by primary interviews with national federation equipment managers, CNC machining house operations directors, university sports science department heads, and athletic facility procurement officers. Bottom-up demand modeling triangulated against top-down aluminum alloy consumption and vulcanized rubber trade flow analysis.
Historical trendline analysis of certification approval cycles, replacement frequency patterns across NCAA and European national training centers, and provincial sports bureau construction pipeline tracking anchored the analytical framework. Segmentation dimensions encompassed product tier, material composition, end-user procurement authority concentration, and regional regulatory compliance cluster. CAGRs were derived from equipment unit demand elasticity relative to track infrastructure investment flows and federation budget allocation patterns.
The model holds under stable World Athletics technical specification continuity and aluminum alloy supply elasticity; deviation in ECHA chemical restriction expansion timelines or Chinese provincial construction mandate acceleration would shift volume trajectories. Practitioners should monitor German federal sustainability procurement code revisions and Indian BIS standard harmonization progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Ladderball Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Balance Bike Market
Sports Equipment
Figure Skating Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Sports Equipment Market
Sports Equipment
UAE Horse Riding Equipment Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Golf Shoes Market
Sports Equipment
Baseball Equipment Market
Sports Equipment
Global Cycling Power Meters Market
Sports Equipment
Cross Training Shoes Market
Sports Equipment
Bowling Lane Panels Market