
 Global Golf Accessories Market | 2026-2036
Global Golf Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Global Golf Accessories Market Analysis
Pro club fitter availability is bifurcating the market between mass retail and precision customization channels. Callaway Golf Company leverages its vertical manufacturing footprint to control carbon fiber supply for premium shafts. TaylorMade Golf Co anchors its position through R&D intensity in adjustable-weight technology. PING differentiates through domestic assembly operations that sustain made-to-order delivery timelines.
Golf accessories encompass equipment and wearables designed to enhance player performance, comfort, and course logistics, typically incorporating urethane-cover formulations in balls, multi-material laminates in clubs, and waterproof membrane systems in footwear. Golf balls command the largest revenue pool due to recurring purchase frequency, while carbon fiber shafts represent the fastest-growing material segment as players pursue gram-level weight reduction. Amateur golfers drive volume expansion through entry-level kit purchases, whereas professional golfers concentrate margin pools in custom-fitted equipment.
EPA guidelines govern chemical content in synthetic grip compounds sold in the United States, while REACH restricts hazardous substances in European-imported leather and synthetic materials. The EU Green Deal's extended producer responsibility frameworks are pressuring manufacturers to redesign end-of-life recyclability for grips and covers. Stakeholders must monitor evolving material compliance thresholds across multiple jurisdictions to preempt supply chain disruption and access denial.
Market Dynamics
Carbon fiber supply concentration among Japanese and US-based prepreg manufacturers is compressing margin pools for shaft assemblers while forcing club brands toward backward integration into raw material sourcing.
Growth Catalysts
- REACH substance restrictions:European ECHA mandates on phthalate-free grip compounds are accelerating bio-based polyurethane R&D investment across formulation labs in Germany and Belgium.
- Amateur participation surge:Municipal course construction in the United States and South Korea is expanding addressable demand for entry-level accessory kits and training aids.
- Adjustable-weight systems:Modular hosel technology is shortening replacement cycles for fairway woods and hybrids among competitive amateur segments.
Market Restraints
- Toray and Mitsubishi Chemical carbon fiber oligopoly:Captive supply agreements lock mid-tier shaft brands into price-taker positions with 12-18 month order backlogs.
- EPA synthetic rubber compliance:New testing protocols for grip volatile organic compound emissions are extending US product launch timelines by 8-14 months.
- Leather tanning cost volatility:Chrome-free hide processing for premium gloves faces input cost swings tied to Argentine and Italian raw material auctions.
Strategic Opportunities
- India course development:DLF and Emaar golf residential projects near Delhi and Mumbai are creating first-mover accessory distribution partnerships for premium ball and footwear brands.
- EU Green Deal extended producer responsibility:Mandatory grip and cover take-back schemes in France and Germany reward modular designs with recyclable thermoplastic elastomers.
- AI-driven swing analytics:Sensor-embedded grips converging with smartphone apps are opening subscription revenue streams alongside hardware sales.
Industry Challenges
- Master club fitter scarcity:The Pipeline from PGA training programs to retail floor expertise is constricting custom fitting throughput at US specialty stores.
- ISO 14001 environmental certification timelines:Ball manufacturers face 18-24 month audit cycles to validate urethane cover waste reduction claims for European retail placement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Golf Accessories Market |
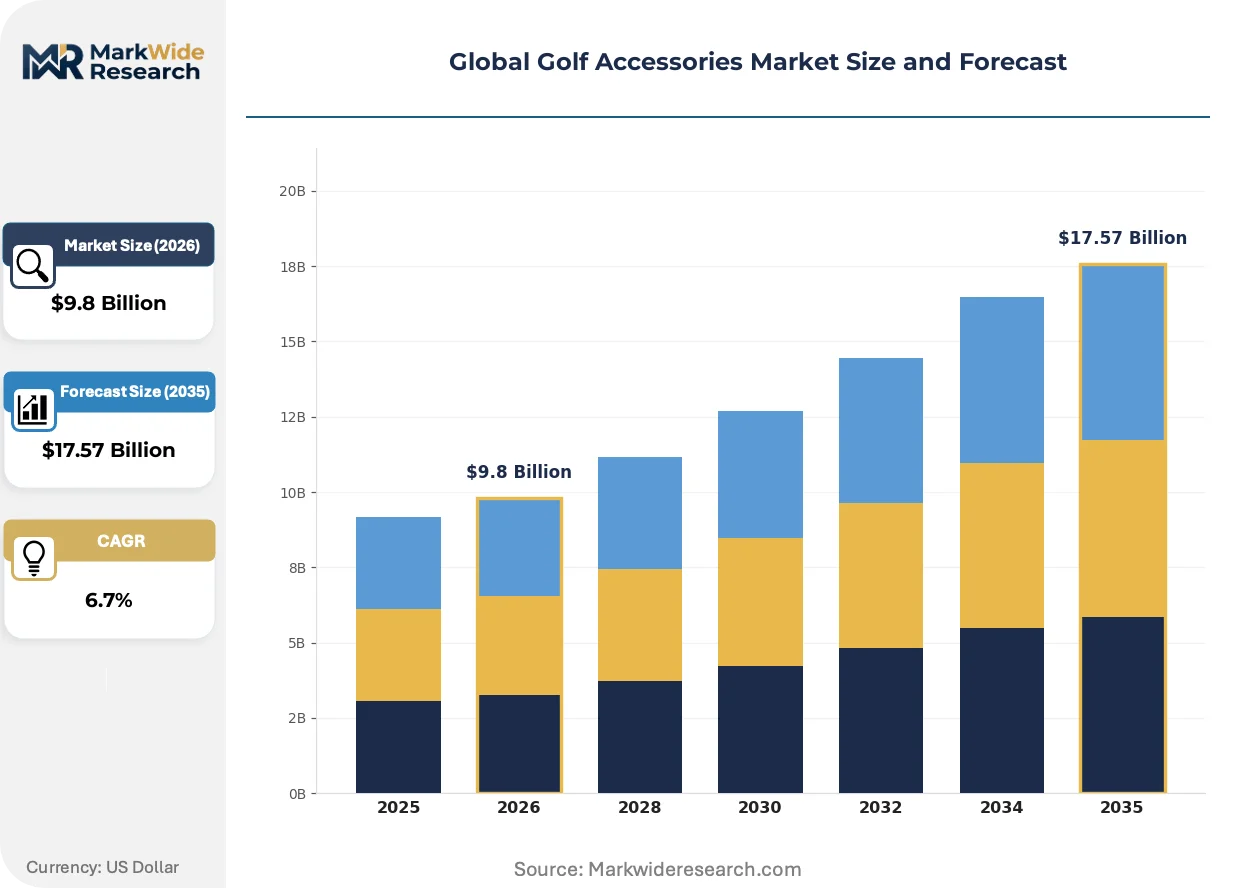
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Golf Balls, Golf Clubs, Golf Bags, Golf Shoes Material: Carbon Fiber, Aluminum, Synthetic, Leather End User: Amateur Golfers, Professional Golfers, Golf Coaches, Golf Courses Distribution Channel: Online Retail, Sporting Goods Stores, Specialty Shops, Direct Sales |
| Companies Covered | Acushnet Holdings Corp., Callaway Golf Company, TaylorMade Golf Co, PING, Adidas AG, Mizuno Corporation, Puma SE, Bridgestone Corporation, Amer Sports, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Golf Accessories Market Emerging Trajectories
Material science breakthroughs and regulatory pressure on chemical content are converging to redefine performance benchmarks across balls, shafts, and wearable categories.
Multi-layer urethane cover formulations with gradient compression cores are extending driver distance while preserving short-game spin control. Weekend competitive players in the United States and Japan are adopting these balls at replacement cycles under six months. This performance tiering is miniaturizing the viable market share for two-piece ionomer covers to price-sensitive beginners only.
EPA guidelines governing synthetic grip compounds are tightening volatile organic compound thresholds for products sold in California and Northeast corridor states. Manufacturers must reformulate nitrile and thermoplastic elastomer blends or forfeit access to high-value retail channels. The compliance burden falls heaviest on mid-tier grip brands lacking captive testing laboratories.
Direct-to-consumer fitting platforms are displacing traditional pro shop trial sessions for shaft selection. Digital swing capture combined with algorithmic flex and torque recommendations now handles 30-40% of driver and iron set purchases among sub-10 handicap amateurs. This channel shift is most pronounced in the United Kingdom and Australia where retail consolidation has reduced physical fitting point density.
Global Golf Accessories Market Segmentation
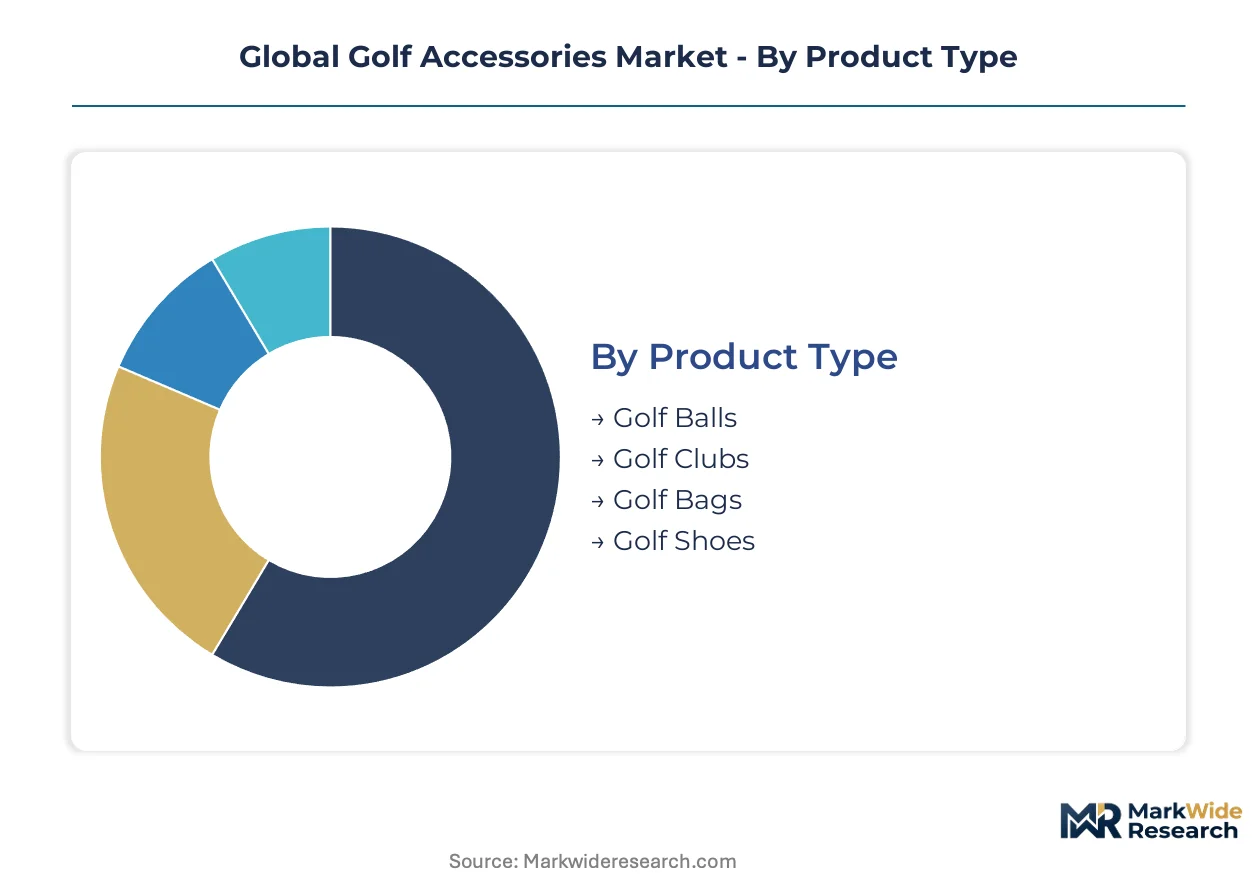
Golf accessories fragment across four dimensions that each carry distinct compliance burdens and margin structures. Product type and material selection drive regulatory exposure, while end-user and channel choices determine pricing power and inventory velocity.
Product Type:
EPA volatile organic compound thresholds and REACH substance restrictions apply differentially across equipment categories, with urethane formulations facing stricter scrutiny than structural materials.
- Golf Balls:Multi-layer urethane cover formulations with gradient compression cores dominate performance tiers. Weekend competitive players in the United States and Japan replace these at cycles under six months, compressing margin pools for ionomer alternatives.
- Golf Clubs:Modular hosel technology in fairway woods and hybrids shortens replacement cycles among competitive amateurs. Carbon fiber shaft integration raises unit economics while concentrating supply risk among Japanese prepreg manufacturers.
- Golf Bags:Lightweight nylon-polyester laminates with reinforced stand mechanisms serve walking-course demand. Waterproof membrane systems add cost tiers without triggering chemical compliance thresholds.
- Golf Shoes:Waterproof membrane systems with spikeless outsole configurations bridge on-course and casual wear. Chrome-free leather tanning for premium lines faces Argentine and Italian raw material cost volatility.
Established volume favors Golf Balls; emerging adoption favors Golf Shoes.
Material:
Cost tier stratification separates aerospace-grade inputs from commodity substitutes, with certification grade determining access to premium retail placement.
- Carbon Fiber:Toray and Mitsubishi Chemical oligopoly structures compress margin pools for shaft assemblers. Captive supply agreements force mid-tier brands into 12-18 month order backlogs, rewarding backward integration by major club manufacturers.
- Aluminum:Cast and forged alloys in putter heads and iron chassis offer price-accessible performance. Chinese smelter capacity stabilizes input costs for entry-level equipment targeting municipal course expansion.
- Synthetic:Bio-based polyurethane R&D accelerates in German and Belgian formulation labs responding to ECHA phthalate-free mandates. Thermoplastic elastomer grips face extended EPA testing timelines in California and Northeast corridor states.
- Leather:Chrome-free hide processing for premium gloves carries auction-linked cost swings from Argentine and Italian suppliers. REACH hazardous substance restrictions limit European-imported volumes to certified tanneries.
Supply concentration favors Carbon Fiber; regulatory arbitrage favors Synthetic.
End User:
Customer type determines fitting complexity, with professional segments demanding custom specifications that amateur volume cannot support.
- Amateur Golfers:Entry-level kit purchases drive volume expansion through municipal course construction in the United States and South Korea. Digital swing capture platforms now handle 30-40% of driver and iron set selections among sub-10 handicap players.
- Professional Golfers:Custom-fitted equipment concentrates margin pools through tour validation and limited production runs. Made-to-order delivery timelines depend on domestic assembly operations for shaft integration and grip installation.
- Golf Coaches:Training aid procurement scales with academy certification programs and junior development initiatives. Bulk purchasing agreements favor durable, replaceable components over precision-tuned equipment.
- Golf Courses:Fleet management for rental sets and practice range balls prioritizes durability and standardization over performance optimization. Inventory turnover requirements favor two-piece ionomer covers and cast aluminum iron heads.
Volume scale favors Amateur Golfers; margin extraction favors Professional Golfers.
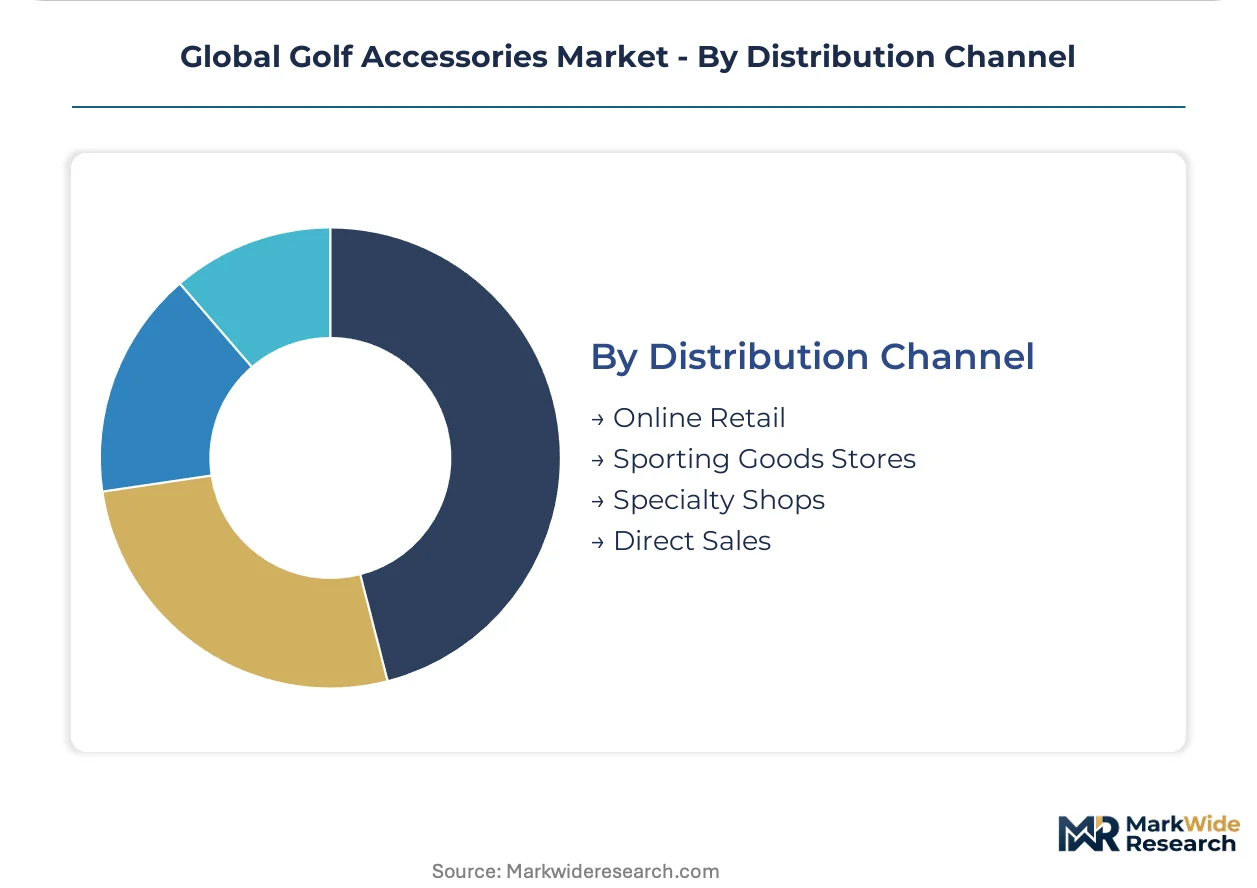
Distribution Channel:
Geography of retail consolidation shapes channel viability, with physical fitting point density determining specialty shop survival.
- Online Retail:Algorithmic flex and torque recommendations displace traditional pro shop trial sessions. Direct-to-consumer platforms gain share fastest in the United Kingdom and Australia where retail consolidation has reduced physical access.
- Sporting Goods Stores:Mass retail chains depend on inventory breadth and promotional pricing to capture seasonal demand spikes. Entry-level accessory kits and training aids dominate shelf space allocation.
- Specialty Shops:Master club fitter scarcity constrains custom fitting throughput at United States specialty stores. PGA training program pipelines fail to replenish retail floor expertise at replacement rates.
- Direct Sales:Vertical manufacturing footprints enable made-to-order delivery with controlled carbon fiber supply. Premium shaft and grip configurations bypass wholesale margin extraction.
Scale efficiency favors Online Retail; service differentiation favors Specialty Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA volatile organic compound thresholds and REACH substance restrictions create divergent compliance burdens across manufacturing clusters. Course construction and retail density patterns concentrate demand in specific national markets.
United States
Municipal course expansion in Florida and Arizona sustains entry-level accessory kit demand. EPA testing protocols for grip volatile organic compound emissions extend product launch timelines in California and Northeast corridor states. Scottsdale and Orlando retail clusters host the densest specialty shop networks for custom fitting services.
Germany
ECHA mandates on phthalate-free grip compounds accelerate bio-based polyurethane R&D investment in formulation labs near Cologne and Leverkusen. EU Green Deal extended producer responsibility frameworks pressure manufacturers to redesign end-of-life recyclability for grips and covers. Bavarian golf residential projects near Munich create distribution partnerships for premium footwear brands.
Japan
Weekend competitive players in Tokyo and Osaka metropolitan areas replace multi-layer urethane balls at cycles under six months. METI standards govern chemical content in synthetic materials imported for equipment assembly. Toray and Mitsubishi Chemical maintain carbon fiber prepreg oligopoly positions that compress margin pools for shaft assemblers.
South Korea
Municipal course construction in Gyeonggi Province expands addressable demand for training aids and entry-level equipment. MFDS regulations align with broader Asian market standards for synthetic grip compound safety testing. Seoul Capital Area retail density supports premium accessory consumption alongside professional tour validation events.
United Kingdom
Digital swing capture platforms handle 30-40% of driver and iron set purchases among sub-10 handicap amateurs. REACH compliance requirements restrict hazardous substances in leather and synthetic materials imported from non-EU tanneries. London and Southeast England retail consolidation reduces physical fitting point density, accelerating direct-to-consumer channel migration.
Global Golf Accessories Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with backward integration into raw material sourcing separating premium positioning from price-taker vulnerability. The market structure rewards captive carbon fiber supply and domestic assembly operations that sustain made-to-order delivery timelines. Three archetypes dominate: vertically integrated equipment manufacturers with shaft foundry control, precision customization specialists leveraging master fitter networks, and mass-market brands dependent on promotional retail channels. Competitive moves concentrate on M&A to secure carbon fiber prepreg allocation and strategic partnerships with municipal course operators for fleet management contracts.
Among North American equipment manufacturers, Acushnet Holdings Corp. and Callaway Golf Company occupy positions that exemplify the integrated leader archetype through upstream control over urethane formulation and carbon fiber supply. TaylorMade Golf Co represents the precision customization tier, anchoring competitive positioning through adjustable-weight technology R&D intensity. These three entities collectively illustrate how manufacturing footprint configuration determines margin extraction capability across amateur and professional golfer segments.
| Leading Market Players |
|---|
| Acushnet Holdings Corp. |
| Callaway Golf Company |
| TaylorMade Golf Co |
| PING |
| Adidas AG |
| Mizuno Corporation |
| Puma SE |
| Bridgestone Corporation |
| Amer Sports |
| Others |
Supply Flow & Price Mechanics
Bio-based polyurethane substitution for phthalate-laden grip compounds simultaneously shifts formulation R&D toward German and Belgian labs while compressing margin pools for mid-tier brands lacking captive testing infrastructure. This input transition concentrates pricing power among integrated manufacturers with in-house polymer development capabilities.
Pricing Analysis
Geographic price spreads between California and Southeast Asia retail channels exceed fifty percent for urethane-cover ball tiers. Three-tier pricing structure across premium, standard, and economy levels separates tour-validated multi-layer formulations from municipal-course ionomer alternatives. Price differentiation hinges on certification grade for REACH-compliant grip compounds and customization depth in shaft flex-matching. Cost compression in entry-level kits intensifies because Chinese aluminum smelter capacity stabilizes iron head input costs. Municipal course procurement teams exhibit highest price sensitivity; tour-sponsorship validated equipment commands lowest elasticity.
Supply Chain Analysis
Inventory lead times for carbon fiber prepreg stretch twelve to eighteen months, forcing shaft assemblers into price-taker positions. Geographic supply concentration centers on Japan, the United States, and China for aerospace-grade carbon fiber, urethane formulation chemicals, and cast aluminum foundry capacity. Raw material dependencies draw from Toray and Mitsubishi Chemical oligopoly structures, Argentine and Italian chrome-free tanneries, and German polymer additive specialists. Single-source vulnerability pervades carbon fiber allocation agreements. Distribution runs through direct-to-consumer platforms, specialty shop networks, and mass retail chains with diverging service intensity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor-embedded swing analytics and AI-driven fitting platforms threaten traditional hardware-centric revenue models, forcing incumbents to defend substitution through service-layer integration.
For Market Incumbents: Fortify carbon fiber supply security through backward integration into Japanese prepreg allocation or long-term offtake agreements with Toray and Mitsubishi Chemical. Deepen master fitter certification pipelines to sustain custom fitting throughput against digital platform displacement. EPA testing protocol expansion and REACH substance restriction tightening threaten mid-tier grip brands lacking captive laboratories.
For New Entrants and Emerging Players: Differentiate on modular hosel technology for fairway woods and hybrids, targeting competitive amateur segments with shortened replacement cycles. Municipal course construction in South Korea and India presents the most penetrable geography for entry-level kit distribution. Direct-to-consumer algorithmic fitting platforms offer the lowest barrier go-to-market angle in the United Kingdom and Australia.
For Investors and Strategic Acquirers: EU Green Deal extended producer responsibility frameworks reshape the acquisition landscape toward modular grip designs with recyclable thermoplastic elastomers. Long-term viability favors vertically integrated equipment manufacturers with shaft foundry control and domestic assembly operations. Acquisition target archetype: precision customization specialists with dense master fitter networks. Signal to watch: carbon fiber prepreg allocation contract renegotiation cycles as inflection indicator for supply security premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon Fiber Supply | Toray and Mitsubishi Chemical oligopoly compression demands captive prepreg allocation for margin defense. |
| Master Fitter Certification Pipeline Expansion | PGA training program throughput constraints threaten custom fitting capacity at United States specialty shops. |
| Modular Hosel Technology R&D Investment | Adjustable-weight systems shorten replacement cycles among competitive amateur fairway wood purchasers. |
| Direct-to-Consumer Fitting Platform Launch | Algorithmic flex recommendations displace pro shop trials in United Kingdom and Australian retail consolidation zones. |
| EU Green Deal Compliance Repositioning | Extended producer responsibility frameworks reward recyclable thermoplastic elastomer grip designs in France and Germany. |
Methodological Framework
Operator-level perspectives from club fitters, shaft assembly plant managers, urethane formulation chemists, and municipal course procurement directors anchored the qualitative base. Primary interviews combined with secondary validation from EPA testing protocol filings, ECHA substance restriction updates, customs records for carbon fiber prepreg imports, and SEC disclosures from listed equipment manufacturers. Bottom-up demand modeling and top-down supply capacity assessment provided triangulation across the analysis window.
Sensitivity analysis around carbon fiber allocation constraints, REACH compliance cost pass-through rates, and municipal course construction cadence informed scenario-weighted outputs. Segmentation dimensions modeled include product type, material grade tier, end-user handicap and participation frequency, and channel service intensity. CAGRs derived from volume trajectory analysis against replacement cycle compression and geographic expansion patterns. Industry-specific forecast inputs incorporate Toray and Mitsubishi Chemical capacity expansion announcements and EPA volatile organic compound threshold revision timelines.
Decision-makers should treat outputs as directional under assumptions of sustained amateur participation growth and stable carbon fiber oligopoly pricing; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
PE Sports Turf Market
Sports Equipment
Kick Scooter Tire Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Parallel Bars Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Riding Gear Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Sports Flooring Market
Sports Equipment
Kickboxing Equipment Market
Sports Equipment
Skating Shoes Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Volleyball Equipment Market
Sports Equipment
Asia-Pacific Kickboxing Equipment Market
Sports Equipment
Swimming Gear Market
Sports Equipment
Kung Fu Uniform Market
Sports Equipment
Gym Rubber Flooring Market