
 Sports Fishing Equipment Market | 2026-2036
Sports Fishing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Fishing Equipment Market Intelligence
Market Context with Strategic Players
Carbon-fiber blank manufacturing and in-house resin compounding is redrawing competitive boundaries between integrated manufacturers and assembly-only brands. Shimano Inc. leverages its Osaka-based composites lab to control rod taper profiles from prepreg to finish, sustaining margin capture that Pure Fishing, Inc. navigates through multi-brand distribution across mass retail and specialty channels. Daiwa Seiko Corporation anchors its position with magnetic braking systems in baitcasting reels, competing on casting precision rather than price.
Technical Definition and Structural Segments
Sports fishing equipment comprises purpose-built implements—graphite or fiberglass rods with action ratings from slow to extra-fast, machined aluminum or carbon-fiber reels with drag systems rated to specific line-test breaking strengths, and monofilament, fluorocarbon, or braided lines measured by diameter-to-strength ratios—designed to present artificial or natural baits and secure fish through hookset and retrieval. The primary commercial purpose is enabling recreational and sport anglers to target specific species across varying depths, currents, and cover densities with calibrated precision. Rods and reels together occupy the largest value share as replacement cycles shorten with graphite blank technology advancing sensitivity-to-weight ratios. Smart technology integration in reels—digital line counters, GPS-enabled casting logs, and Bluetooth-connected drag alerts—represents the fastest-expanding margin pool as amateur anglers adopt connected tackle. Lures remain structurally fragmented across hundreds of niche artisans and mass producers, concentrating volume in hard-body crankbaits and soft-plastic swimbaits while margin accrues to proprietary color-pattern licensing.
Regulatory Frame and Forward-Looking Close
The EPA regulates lead content in fishing sinkers and jigs under the Toxic Substances Control Act, while the EU REACH framework restricts perfluorinated compounds in line coatings and reel greases, compelling reformulation across export-oriented suppliers. Japan's METI oversees JIS standards for carbon-fiber rod durability testing, creating certification barriers for offshore entrants seeking distribution through domestic retailers. Stakeholders must monitor how state-level lead bans in Maine, New Hampshire, and Vermont propagate to larger jurisdictions, and whether biodegradable line materials achieve performance parity sufficient to displace conventional polymers in professional tournament settings.
Market Dynamics
Carbon-fiber prepreg sourcing concentration in Japan and Taiwan is compressing margin structures for rod assemblers lacking captive composite capabilities, while tournament angler demand for sensitivity-to-weight ratios accelerates blank replacement cycles.
Growth Catalysts
- REACH restrictions on fluorinated compounds:The EU's chemical framework is compelling manufacturers to reformulate line coatings and reel lubricants, opening first-mover advantages for bio-based suppliers with certified alternatives.
- Recreational boating infrastructure:Coastal marina expansion across Florida, Texas, and North Carolina is expanding tackle procurement budgets for charter operators and leisure fleets.
- Graphite sensitivity advancement:High-modulus carbon blanks with enhanced vibration transmission are shortening replacement cycles among competitive anglers seeking species-specific action profiles.
Market Restraints
- Toray carbon-fiber concentration:Japanese and Taiwanese suppliers control 70%+ of aerospace-grade prepreg output, exposing rod manufacturers to input cost volatility and allocation rationing during demand surges.
- Lead substitution technical gap:EPA and state-level bans on sinker materials have not yet produced tungsten or bismuth alternatives at cost-performance parity for depth-critical jigging applications.
- Reel magnetic braking complexity:Precision casting systems require skilled calibration that mass-market anglers struggle to optimize, limiting adoption outside enthusiast segments.
Strategic Opportunities
- Smart reel convergence:Bluetooth-enabled drag alerts and GPS casting logs are creating premium price tiers as amateur anglers adopt connected tackle for pattern documentation.
- Biodegradable line materials:Performance parity achievements in tournament settings could displace conventional polymers, with early certification from Japan's METI creating distribution access.
- Direct-to-consumer channels:Specialty rod builders are bypassing retail markup through custom-configurator platforms, capturing margin from anglers seeking species-specific taper profiles.
Industry Challenges
- Composite technician scarcity:Rod blank manufacturing requires skilled layup specialists that coastal manufacturing clusters struggle to retain against aerospace sector competition.
- JIS certification timelines:Japan's durability testing standards create 12-18 month approval windows for offshore entrants seeking domestic retailer distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Fishing Equipment Market |
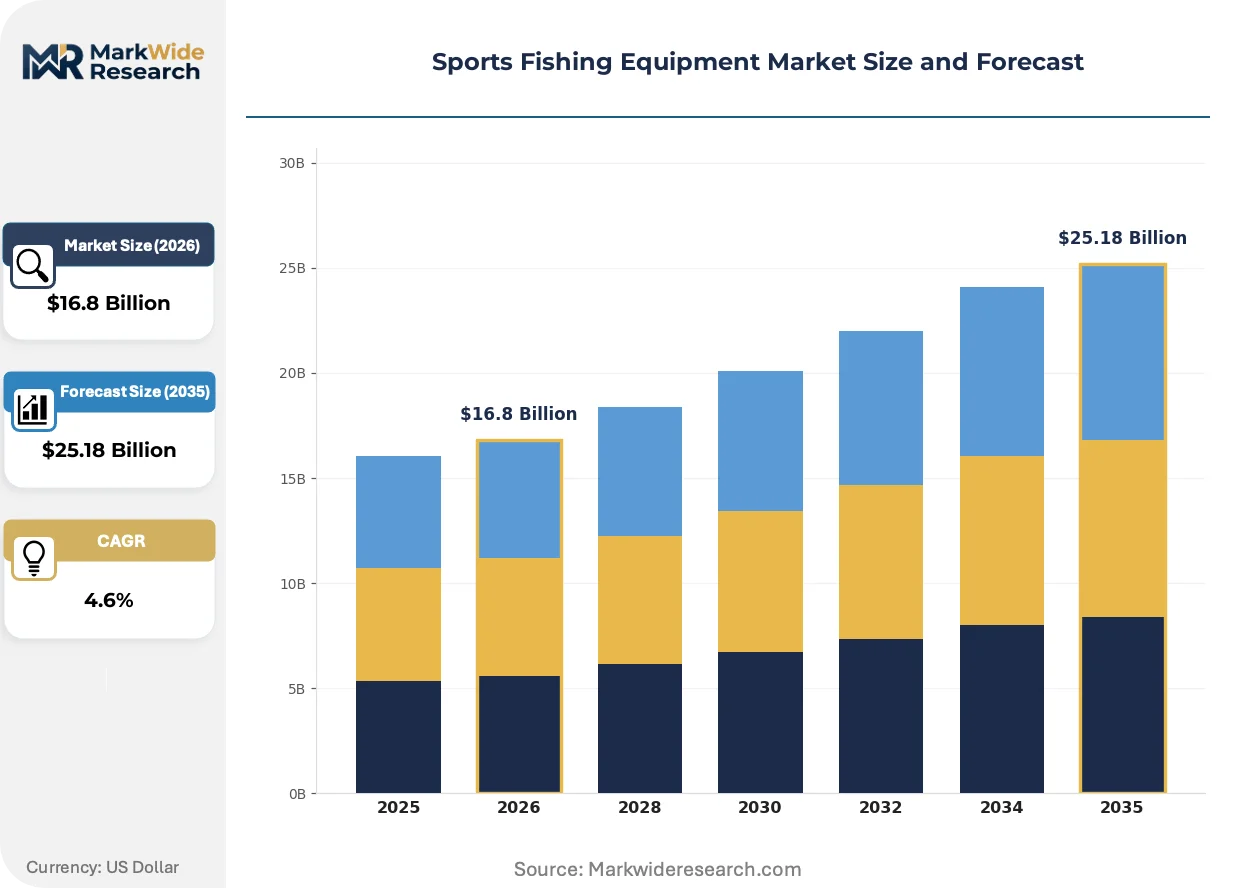
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $25.18 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rods, Reels, Lines, Lures Application: Freshwater, Saltwater, Fly Fishing, Ice Fishing End User: Amateur Anglers, Professional Fishermen, Tour Operators, Retailers Technology: Electric, Smart, Conventional, Baitcasting |
| Companies Covered | Globeride Inc., O. Mustad & Son A.S., Shimano Inc., Daiwa Seiko Corporation, Newell Brands Inc., Pure Fishing, Inc., Okuma Fishing Tackle Corporation, Gamakatsu, Rapala VMC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Fishing Equipment Market Strategic Shifts & Innovations
Material science advances and connected hardware integration are redrawing product boundaries between precision instruments and consumer electronics, while regulatory chemical frameworks force formulation discontinuities across legacy product lines.
Smart reel technology is fragmenting the traditional mechanical-reel market into connected and non-connected segments. Digital line counters and Bluetooth drag alerts are attracting amateur anglers who value pattern documentation over casting precision alone. This convergence with consumer electronics is compressing product lifecycles as software updates and sensor obsolescence displace decades-long mechanical durability as the primary value anchor.
The EU F-Gas Regulation on fluorinated greenhouse gases is forcing lubricant and line-coating reformulations across export-oriented suppliers. Manufacturers serving European distribution channels must eliminate perfluorinated compounds from reel greases and line treatments or face market exclusion. Japanese suppliers with early bio-based certification through METI are capturing shelf space as European brands navigate multi-year reformulation timelines.
Tournament angler procurement is consolidating around species-specific rod action ratings rather than all-purpose configurations. Competitive bass anglers in the Great Lakes states and Florida are building quivers of fast-action graphite blanks matched to lure weights and cover densities. This specialization is fragmenting retail inventory requirements and compressing replacement cycles as sensitivity benchmarks advance seasonally.
Sports Fishing Equipment Market Segmentation
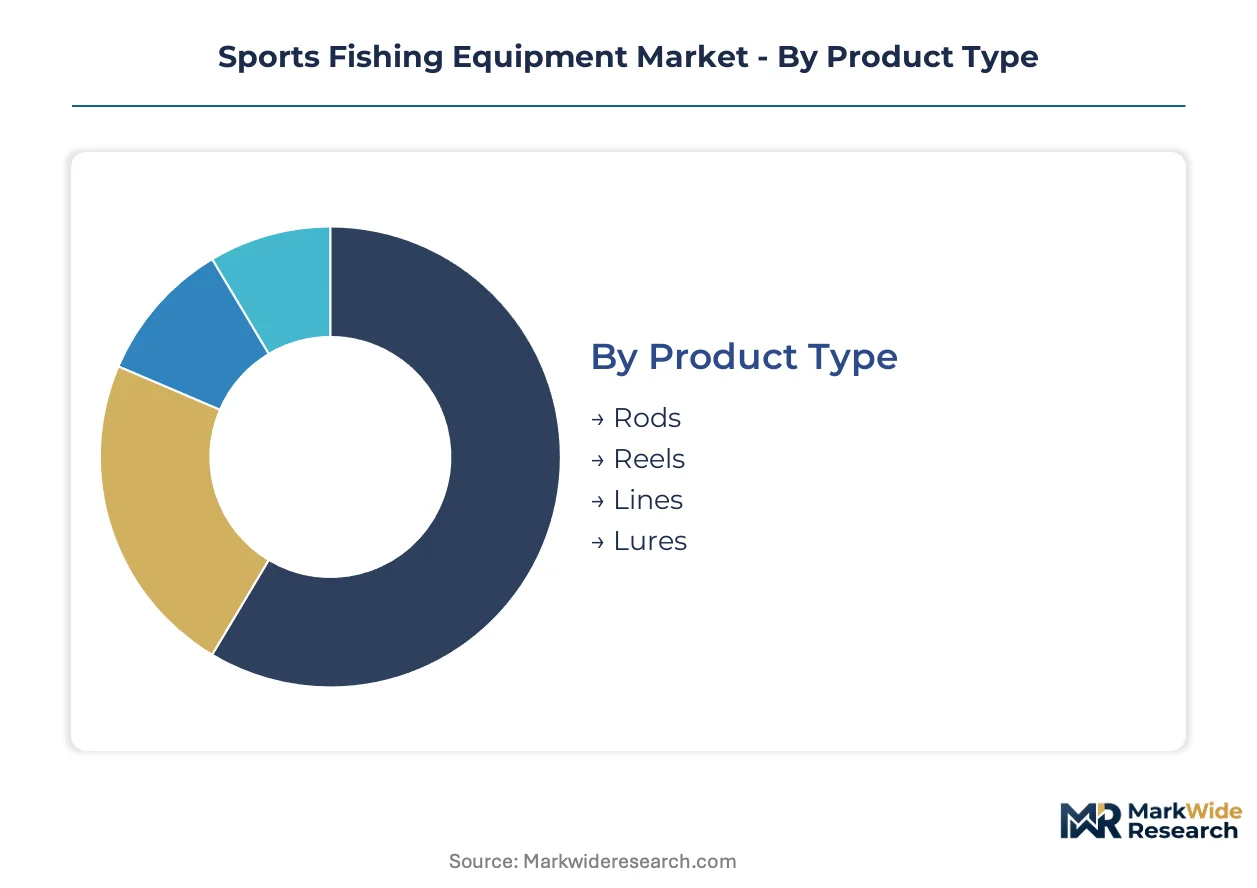
Segmentation in sports fishing equipment reveals how procurement patterns diverge between domestic recreational consumption and export-oriented tournament supply chains. Understanding these splits helps manufacturers align production capacity with regional regulatory requirements and angler sophistication levels.
Product Type:
Domestic assembly dominates rods and reels for North American mass retail, while European and Asian export channels concentrate specialized line and lure formulations subject to REACH chemical restrictions.
- Rods:High-modulus graphite blanks with taper profiles calibrated to lure weights and cover densities command premium positioning. Demand clusters in Florida bass tournaments and Great Lakes walleye derbies where sensitivity-to-weight ratios drive replacement cycles.
- Reels:Machined aluminum and carbon-fiber bodies with magnetic braking systems require skilled calibration that limits mass-market penetration. Magnetic braking complexity concentrates adoption among enthusiast segments in Texas coastal markets and competitive circuits.
- Lines:Monofilament, fluorocarbon, and braided constructions face EU F-Gas Regulation reformulation pressures on coatings.
- Lures:Hard-body crankbaits and soft-plastic swimbaits fragment across hundreds of niche artisans and mass producers.
Rods hold the largest share; momentum sits with reels as smart technology integration accelerates.
Application:
Cost stratification separates premium tournament-grade equipment from rental fleet procurement, with freshwater and saltwater applications diverging on corrosion resistance specifications and replacement frequency.
- Freshwater:Bass and walleye targeting across the Great Lakes states and inland reservoirs drives graphite blank sensitivity demands. Tournament anglers build species-specific quivers that compress replacement cycles as action ratings fragment.
- Saltwater:Corrosion-resistant reel sealing and titanium componentry address Gulf Coast and Atlantic charter operator requirements. Marina infrastructure expansion across Florida and North Carolina expands tackle procurement budgets for leisure fleets.
- Fly Fishing:Precision casting systems concentrate in Rocky Mountain and Northeast trout corridors with specialized retail distribution.
- Ice Fishing:Short-action blanks and compact reels serve seasonal Great Lakes and upper Midwest demand with concentrated winter procurement windows.
Freshwater captures the greatest volume; saltwater climbs fastest on coastal tourism investment.
End User:
Customer sophistication tiers separate custom-configurator direct sales from mass retail, with professional and tour operator procurement subject to durability certification requirements that amateur channels bypass.
- Amateur Anglers:Connected tackle adoption is highest among this segment as Bluetooth-enabled drag alerts and GPS casting logs attract pattern documentation demand. Smart reel convergence creates premium price tiers outside traditional enthusiast demographics.
- Professional Fishermen:Tournament competitors require JIS-certified durability testing and species-specific action profiles that fragment inventory requirements. METI certification creates 12-18 month approval windows for equipment validation.
- Tour Operators:Charter fleets across Florida and Texas prioritize corrosion resistance and fleet standardization over sensitivity optimization.
- Retailers:Specialty shops and mass channels diverge on margin structure and brand mix, with multi-brand distributors navigating different service requirements.
Amateur anglers constitute the broadest base; professional fishermen drive margin expansion through certification premiums.
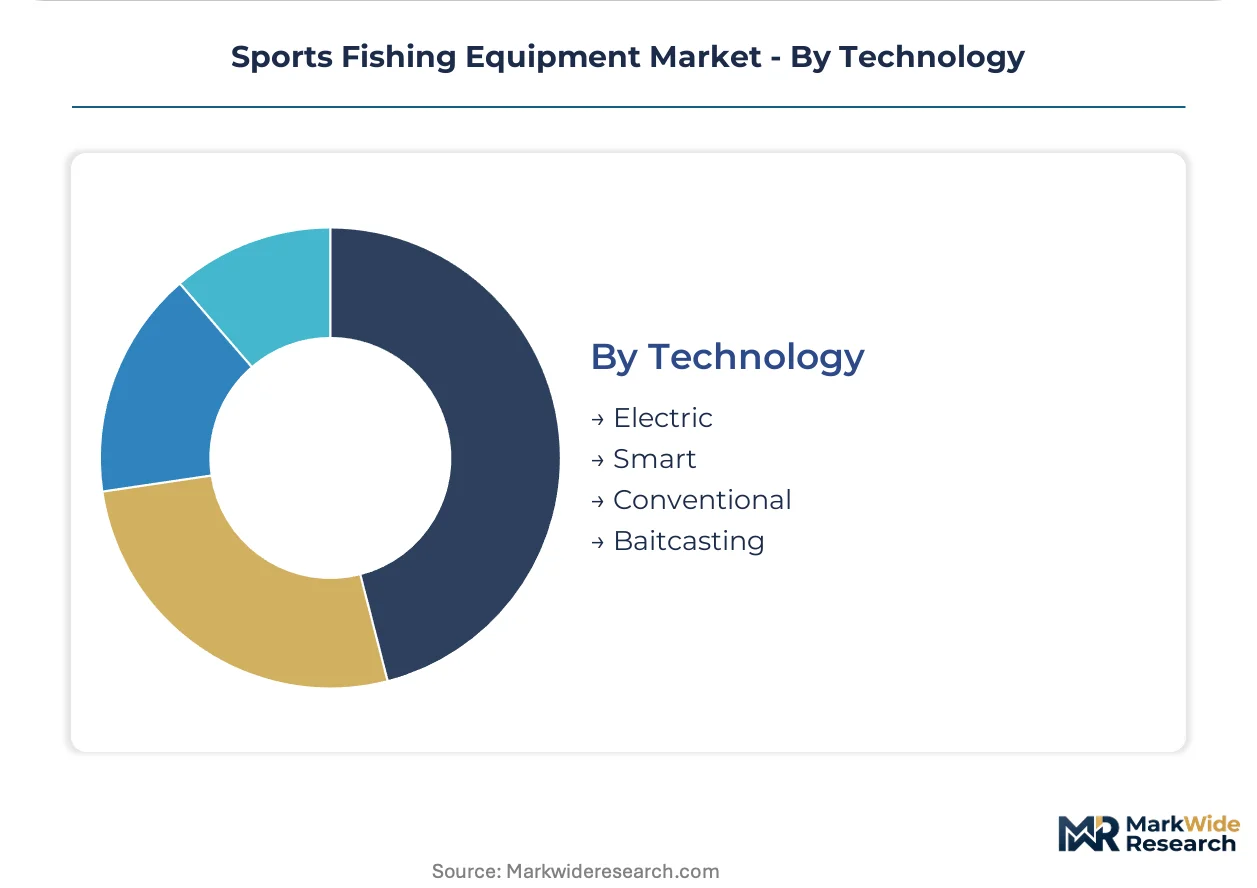
Technology:
Supply concentration in Japanese and Taiwanese carbon-fiber prepreg shapes which technology tiers achieve cost-performance viability for export versus domestic assembly.
- Smart:Digital line counters, GPS-enabled casting logs, and Bluetooth-connected drag alerts are compressing product lifecycles as software obsolescence displaces mechanical durability as the primary value anchor. Sensor integration demands consumer electronics supply chain partnerships that mechanical specialists struggle to access.
- Electric:Motorized retrieval systems address accessibility and deep-water jigging applications with battery chemistry constraints.
- Conventional:Mechanical drag systems retain longevity advantages in saltwater corrosion environments where electronic sealing remains problematic.
- Baitcasting:Magnetic braking precision requires skilled calibration that limits adoption outside enthusiast segments despite casting accuracy benefits.
Conventional technology retains volume leadership; smart systems gain share fastest on amateur connectivity demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anglers in the United States demonstrate the lowest price elasticity for premium carbon-fiber blanks and smart reels, while European buyers face steeper trade-offs between performance tiers due to REACH compliance costs. Asian markets split between Japan's certification-driven premium procurement and China's volume-tier mass production.
United States
Florida, Texas, and Great Lakes states anchor domestic demand through tournament circuits and coastal charter expansion. The EPA regulates lead content in sinkers and jigs under the Toxic Substances Control Act, pushing tungsten substitution in depth-critical applications. Rod assembly clusters concentrate in Arkansas and South Carolina where multi-brand distributors serve mass retail and specialty channels.
Japan
Kanto and Kansai regions house integrated manufacturers with captive carbon-fiber prepreg capabilities and Osaka-based composites laboratories. METI oversees JIS standards for rod durability testing, creating 12-18 month certification windows that protect domestic incumbents. Nagoya-area machining specialists supply precision reel components to both domestic brands and export assemblers.
Germany
Bavaria and North Rhine-Westphalia concentrate specialty retailers serving Central European fly-fishing and predator-angling enthusiasts. The EU F-Gas Regulation on fluorinated greenhouse gases forces lubricant and line-coating reformulations across export-oriented suppliers. Stuttgart-area engineering firms consult on magnetic braking system calibration for premium reel manufacturers.
China
Pearl River Delta and Yangtze River Delta regions dominate graphite blank mass production and OEM assembly for export markets. The country's national environmental regulator enforces dual carbon goals that pressure factory energy intensity and resin compounding emissions. Weihai in Shandong Province hosts rod manufacturing clusters supplying private-label brands to North American and European distributors.
Australia
New South Wales and Queensland coastal corridors drive saltwater tackle demand through reef charter operations and game-fishing tourism. The Therapeutic Goods Administration does not regulate fishing equipment, leaving state-level fisheries management to govern gear restrictions. Sydney and Melbourne specialty retailers import Japanese and American premium brands while distributing domestic lure artisans to Asian export channels.
Sports Fishing Equipment Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive carbon-fiber capabilities separating margin-capturing manufacturers from assembly-dependent brands. The market structures around three archetypes: vertically integrated Japanese manufacturers controlling prepreg-to-finish rod production, multi-brand distributors spanning mass retail and specialty channels, and precision-reel specialists competing on magnetic braking calibration rather than price. Dominant competitive moves include backward integration into carbon-fiber sourcing and direct-to-consumer configurator platforms that bypass retail markup.
Within the integrated manufacturing tier, Shimano Inc. and Daiwa Seiko Corporation exemplify archetypes of captive composite control and precision casting systems respectively. Pure Fishing, Inc. occupies a position representing multi-brand distribution scale across North American mass retail. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning: Osaka-based integrated manufacturers, Tokyo-area reel specialists, and American multi-brand holding companies each sit within distinct competitive tiers.
| Leading Market Players |
|---|
| Globeride Inc. |
| O. Mustad & Son A.S. |
| Shimano Inc. |
| Daiwa Seiko Corporation |
| Newell Brands Inc. |
| Pure Fishing, Inc. |
| Okuma Fishing Tackle Corporation |
| Gamakatsu |
| Rapala VMC Corporation |
| Others |
Cost & Logistics Intelligence
EU REACH certification gates both supplier qualification and price differentiation simultaneously, compelling manufacturers to absorb reformulation costs for fluorinated compound alternatives or surrender European shelf space to Japanese competitors with METI-validated bio-based coatings. This regulatory bifurcation concentrates margin capture among prepreg-integrated rod builders while assembly-dependent brands face compression from input volatility and compliance premiums.
Pricing Analysis
After-sales revenue from replacement blank segments, drag system servicing, and software-enabled reel updates drives lifetime value capture. Three-tier pricing structure across premium tournament-grade, standard enthusiast, and economy mass-retail levels segments buyers by certification requirements and sensitivity specifications. Pricing pressure stems from Toray carbon-fiber allocation rationing during demand surges, compressing margins for rod assemblers lacking captive composite capabilities. Amateur anglers demonstrate highest price sensitivity through mass retail channels, while tournament competitors accept premium positioning for JIS-certified durability and species-specific action profiles.
Supply Chain Analysis
Toray Industries' aerospace-grade prepreg output in Japan and Taiwan underwrites rod blank manufacturing viability for integrated manufacturers while exposing assembly-only brands to single-source vulnerability. High-modulus carbon fiber, machined aluminum reel bodies, and magnetic braking system components draw from specialized machining clusters in Nagoya and Osaka. Tariff exposure on Chinese-assembled private-label rods entering North American distribution channels threatens cost structures for multi-brand distributors. Distribution runs through Arkansas and South Carolina assembly clusters serving mass retail, alongside direct-to-consumer configurator platforms bypassing traditional markup.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart reel convergence with consumer electronics represents a high-growth disruption, with Bluetooth-enabled drag alerts and GPS casting logs fragmenting traditional mechanical-reel market boundaries and compressing product lifecycles through software obsolescence cycles.
For Market Incumbents: Fortify captive carbon-fiber prepreg capabilities against aerospace sector competition for composite technician talent, while accelerating METI bio-based certification timelines to capture European market share during REACH reformulation windows. Prioritize backward integration into resin compounding to defend margin structures against Toray allocation rationing. For New Entrants and Emerging Players: Anchor in direct-to-consumer custom-configurator platforms for species-specific rod taper profiles, targeting amateur anglers seeking tournament-grade sensitivity without specialty retail markup penetration. Exploit biodegradable line material white space by pursuing early METI certification for distribution access through Japanese retail channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart reel manufacturing as sensor integration demands consumer electronics supply chain partnerships that mechanical specialists cannot access. Target integrated manufacturers with captive composite laboratories and software development capabilities, monitoring tournament angler adoption rates of connected tackle as inflection indicator for premium tier viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbon-Fiber Prepreg | Captive composite capabilities insulate margin capture from Toray allocation volatility and aerospace competition. |
| Smart Reel Technology Platform Launch | Bluetooth drag alerts and GPS casting logs attract amateur pattern documentation demand outside enthusiast demographics. |
| Bio-Based Coating Certification Pursuit | METI validation accelerates European market access during REACH multi-year reformulation timelines. |
| Direct-to-Consumer Configurator Expansion | Species-specific taper customization captures margin from anglers bypassing specialty retail markup structures. |
| Biodegradable Line Material Development | Tournament performance parity achievements could displace conventional polymers with early-mover certification advantages. |
Research Approach
Operator-level perspectives from rod manufacturing plant managers, tournament angler procurement coordinators, specialty retail buyers, and marina charter fleet operators anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through customs trade records, SEC filings of publicly held equipment manufacturers, Japan's METI certification databases, and EU REACH substance restriction updates. Bottom-up demand modeling across freshwater, saltwater, fly fishing, and ice fishing applications triangulated with top-down carbon-fiber prepreg consumption estimates.
Sensitivity analysis tested forecast outputs against variable tournament participation rates, REACH enforcement stringency scenarios, and smart reel adoption curves across amateur versus professional angler segments. Segmentation dimensions modeled included product type, application environment, end-user sophistication tier, and technology integration level, with CAGRs derived from historical replacement cycle compression and coastal infrastructure investment patterns. Carbon-fiber modulus advancement timelines and regulatory chemical reformulation schedules served as industry-specific forecast inputs.
Material uncertainties — state-level lead ban propagation beyond Maine, New Hampshire, and Vermont, biodegradable polymer performance parity achievements in professional tournament settings, and aerospace sector composite technician poaching intensity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding marina infrastructure expansion trajectories and smart technology convergence adoption curves. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement timelines and Japanese JIS certification backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Sports Flooring Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Bowling Lane Panels Market
Sports Equipment
United States Archery Equipment Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Europe Archery Equipment Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Rubber Dumbbells Market
Sports Equipment
China Sports Optic Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Germany Horse Riding Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Ergonomic Strap Systems Market