
 North America Kickboxing Equipment Market | 2026-2036
North America Kickboxing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
North America Kickboxing Equipment Market Analytics
Synthetic microfiber is shifting product economics across the North America kickboxing equipment landscape, displacing traditional cowhide leather in mid-tier gloves and pads without sacrificing tensile strength. Everlast Worldwide leverages vertical integration across its Mexico manufacturing network to control raw material costs on synthetic lines. Hayabusa Fightwear differentiates through proprietary Deltra-EG inner-core foam formulations that exceed standard impact-distribution benchmarks. Title Boxing anchors wholesale distribution through exclusive contracts with major gym chains in the United States and Canada.
Kickboxing equipment encompasses striking implements, protective apparatus, and training accessories engineered to absorb repetitive high-impact forces while maintaining anatomical mobility through multi-density foam laminates and reinforced stitching protocols. Gloves dominate value generation due to mandatory replacement cycles tied to hygiene and padding degradation, while protective gear commands premium positioning as concussion-awareness elevates headguard and shin-guard specifications among amateur practitioners. Synthetic materials represent the fastest-expanding material category as vinyl and polyurethane blends reduce unit costs for entry-level fitness enthusiasts, whereas leather sustains its hold on professional athlete segments where durability and hand-feel determine purchasing decisions. Online retail channels are capturing share from specialty stores as direct-to-consumer brands deploy augmented-reality fitting tools to reduce return rates on gloves sized by weight class.
The Consumer Product Safety Commission enforces impact-threshold testing for protective headgear sold in the United States, while Health Canada mandates flammability labeling on foam-based training equipment under the Canada Consumer Product Safety Act. ASTM International publishes voluntary consensus standards for martial-arts protective equipment that many insurers require for facility liability coverage, effectively gating market access for uncertified suppliers. Stakeholders must monitor state-level legislative proposals in California and New York that would mandate recycled-content minimums in synthetic sports equipment, as compliance timelines could reshape sourcing strategies and supplier qualification protocols across the value chain.
Market Dynamics
Synthetic microfiber adoption is compressing leather's dominance across mid-tier kickboxing equipment, forcing manufacturers to reconfigure supply chains around polyurethane blending facilities while the Consumer Product Safety Commission tightens impact-absorption testing protocols for protective headgear sold in the United States.
Growth Catalysts
- Boutique Combat-Sports Studios:Dedicated kickboxing gym chains in California and Texas are accelerating equipment refresh cycles through membership growth and multi-location expansion strategies.
- Impact-Absorption Standards:The Consumer Product Safety Commission's updated testing protocols for protective gear are compelling manufacturers to reformulate padding compounds, creating upgrade demand across existing installed bases.
- Synthetic Material Economics:Vinyl and polyurethane blends are reducing unit production costs for entry-level fitness enthusiasts without sacrificing tensile strength benchmarks established under ASTM International consensus standards.
Market Restraints
- Petrochemical Input Volatility:Polyurethane foam and synthetic leather production depends on ethylene and propylene derivatives, exposing manufacturers to crude oil price swings that compress margin stability on mid-tier product lines.
- Concentrated Retail Gatekeeping:Exclusive wholesale contracts between major gym chains and incumbent distributors create barriers for emerging brands seeking shelf placement in high-volume training facilities across the United States and Canada.
- Leather Durability Premium:Professional athlete segments maintain purchasing preference for cowhide construction based on hand-feel and longevity performance, limiting total addressable market expansion for synthetic alternatives.
Strategic Opportunities
- Augmented-Reality Fitting Tools:Direct-to-consumer brands deploying AR sizing applications are capturing online retail share from specialty stores by reducing return rates on gloves sized by weight class.
- Recycled-Content Mandates:Legislative proposals in California and New York would establish minimum recycled-content thresholds in synthetic sports equipment, creating first-mover advantage for suppliers with certified circular material streams.
- Concussion-Awareness Tailwind:Elevated headguard and shin-guard specifications among amateur practitioners are shifting protective gear toward premium positioning with higher average selling prices.
Industry Challenges
- Multi-Density Foam Lamination Expertise:Manufacturers face scarcity of technical talent capable of engineering layered padding systems that balance impact distribution with anatomical mobility requirements.
- ASTM Certification Timelines:Voluntary consensus standard compliance for martial-arts protective equipment creates extended product development cycles before insurers recognize liability coverage eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Kickboxing Equipment Market |
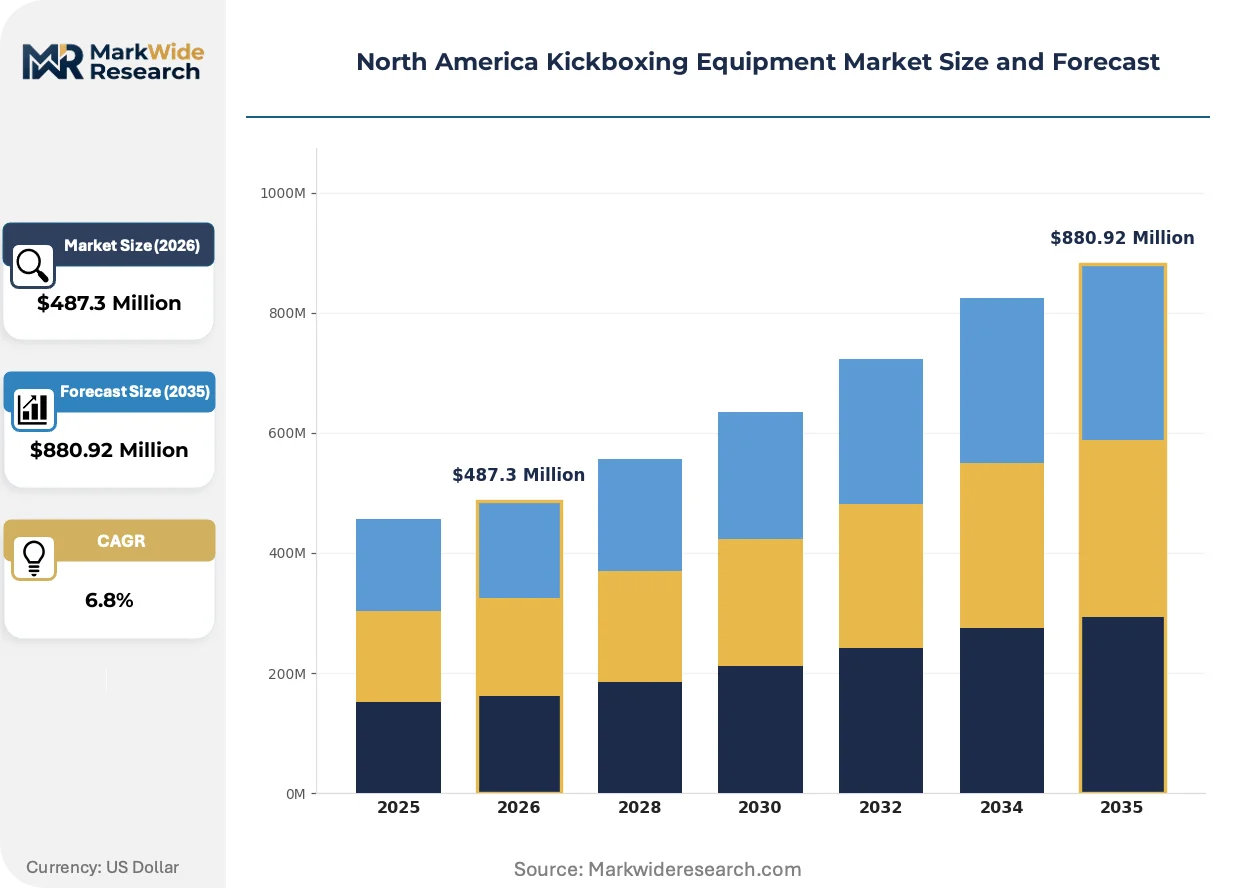
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gloves, Pads, Punch Bags, Protective Gear Material: Leather, Synthetic, Foam, Vinyl End User: Fitness Enthusiasts, Professional Athletes, Gyms, Schools Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesalers |
| Companies Covered | Everlast Worldwide, Adidas, Hayabusa Fightwear, Venum, Title Boxing, RDX Sports, Century Martial Arts, Twins Special, Ringside Boxing, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Kickboxing Equipment Market Evolving Landscape
Material science breakthroughs and regulatory compression are simultaneously reshaping product architecture and go-to-market economics across North American kickboxing equipment, with digital distribution tools and sustainability mandates emerging as decisive competitive differentiators.
Smart sensor integration into training gloves and heavy bags is electrifying performance analytics for competitive athletes and boutique studio operators. Amateur practitioners in Texas and California are adopting Bluetooth-enabled strike-force measurement systems at accelerating rates. This connectivity layer is compressing the traditional boundary between equipment manufacturers and software-enabled coaching platforms.
The Consumer Product Safety Commission's enforcement of impact-threshold testing for protective headgear sold in the United States is mandating third-party laboratory certification before market entry. Manufacturers are reformulating Deltra-EG and similar proprietary foam cores to exceed baseline distribution benchmarks. Amateur segments bear the highest compliance cost burden as premium protective gear prices adjust to absorb testing and documentation overhead.
Boutique studio procurement officers are consolidating vendor relationships around full-equipment-package suppliers capable of delivering gloves, pads, headgear, and heavy bags under unified brand aesthetics. Specialty retailers in Canada and the United States are losing floor traffic to direct-to-consumer channels offering augmented-reality fitting and subscription-based replacement programs. California's gym chain expansion corridors exhibit the most pronounced channel shift toward integrated equipment-and-digital-content bundles.
North America Kickboxing Equipment Market Segmentation
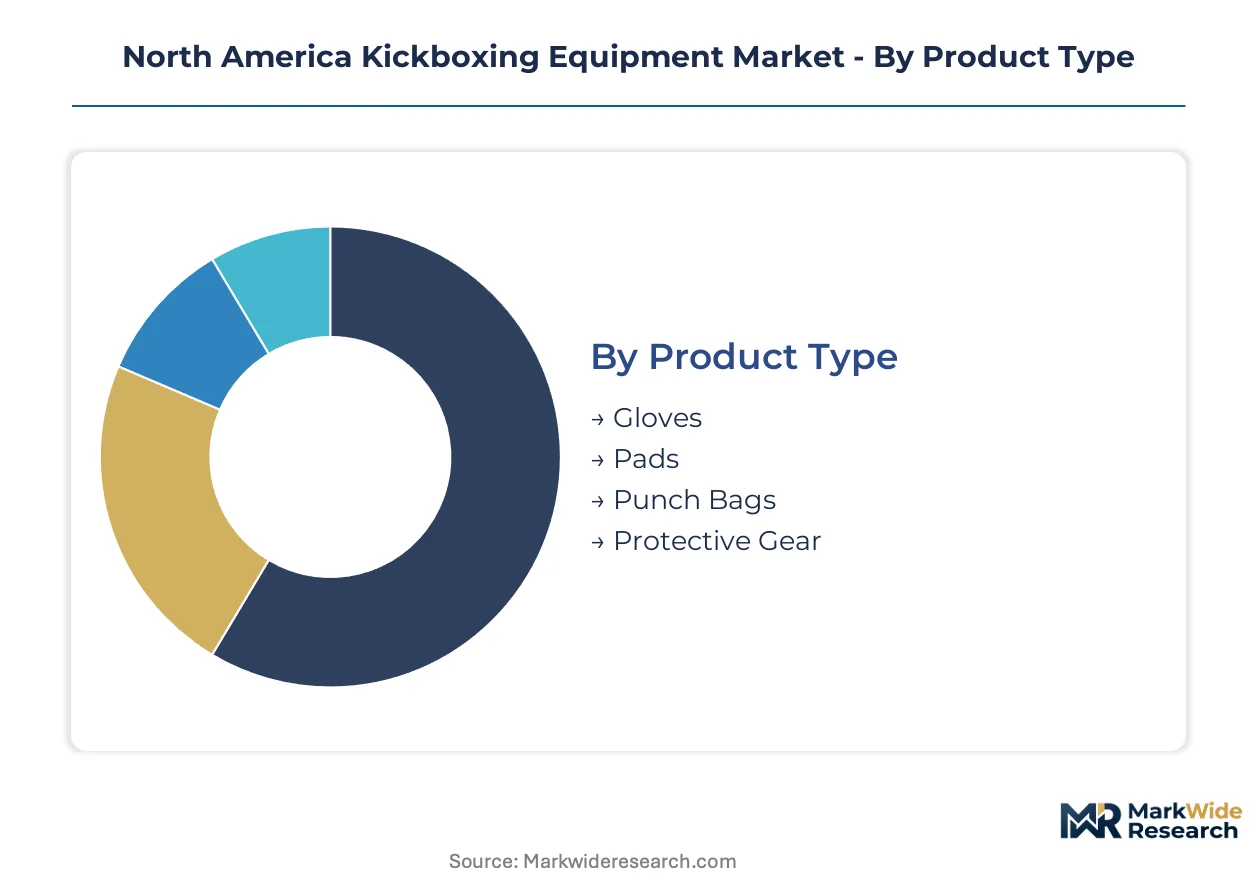
Equipment segmentation in North American kickboxing reveals divergent performance requirements across fitness and competitive use cases. Material composition and distribution channel choices directly determine margin profiles and replacement cycle frequency for manufacturers serving this market.
Product Type:
Standalone striking implements dominate replacement-driven revenue streams, while embedded protective systems anchor premium positioning through safety certification requirements.
- Gloves:Multi-density foam laminates with reinforced wrist closures absorb repetitive impact forces while maintaining anatomical mobility. California and Texas gym chains drive bulk procurement through exclusive vendor contracts tied to membership growth. Mandatory hygiene-driven replacement cycles sustain recurring revenue for manufacturers with established wholesale relationships.
- Protective Gear:Headguards and shin-guards engineered to CPSC impact-threshold specifications command premium pricing as concussion awareness elevates amateur practitioner safety standards. Reformulated padding compounds incorporating Deltra-EG-style foam cores exceed baseline distribution benchmarks required for insurer liability coverage eligibility.
- Pads:Strike-absorbing surfaces for coaching drills utilize layered synthetic or leather construction depending on training intensity tier.
- Punch Bags:Heavy and freestanding bag systems anchor studio infrastructure investments with extended depreciation schedules.
Gloves lead volumes today; Protective Gear is gaining share fastest.
Material:
Cost tier stratification separates professional-grade durability requirements from mass-market accessibility targets.
- Synthetic:Polyurethane and microfiber blends reduce unit production costs without sacrificing tensile strength benchmarks under ASTM International consensus standards. Entry-level fitness enthusiasts in boutique California studios accept synthetic construction where hand-feel trade-offs remain acceptable.
- Leather:Cowhide construction sustains professional athlete preference based on longevity performance and tactile feedback characteristics. Texas competitive circuits and professional training camps maintain leather-dominant procurement patterns despite synthetic encroachment in adjacent segments.
- Foam:Multi-density core materials determine impact distribution performance across protective gear categories.
- Vinyl:Budget-tier surfaces serve introductory practitioner segments with compressed margin profiles.
Synthetic materials climb the fastest; Leather retains professional segment anchoring.
End User:
Customer type determines equipment specification intensity and replacement frequency patterns across the value chain.
- Fitness Enthusiasts:Boutique studio members in California and Texas accelerate equipment refresh cycles through membership growth and multi-location expansion strategies. Synthetic material acceptance runs highest among this segment where unit cost sensitivity exceeds durability premium willingness.
- Professional Athletes:Competitive practitioners demand leather construction and proprietary foam formulations with documented impact-distribution superiority. CPSC compliance certification and ASTM International recognition gate supplier access to this specification-intensive segment.
- Gyms:Commercial training facilities consolidate vendor relationships around full-equipment-package suppliers capable of unified brand aesthetic delivery.
- Schools:Educational institutional procurement emphasizes bulk pricing and standardized safety certification documentation.
Fitness Enthusiasts anchor volume concentration; Professional Athletes sustain margin premiums.
Distribution Channel:
Channel configuration determines customer acquisition economics and return rate exposure for sizing-dependent products.
- Online Retail:Direct-to-consumer deployment of augmented-reality fitting tools reduces return rates on gloves sized by weight class. Specialty retailers in Canada and the United States lose floor traffic to digital channels offering subscription-based replacement programs.
- Specialty Stores:Physical fitting services sustain relevance for professional athlete segments requiring tactile evaluation before purchase commitment.
- Supermarkets:Mass-market retail placement captures introductory practitioner impulse purchases with compressed specification requirements.
- Wholesalers:Exclusive contracts between major gym chains and incumbent distributors create barrier structures limiting emerging brand shelf access in high-volume training facilities.
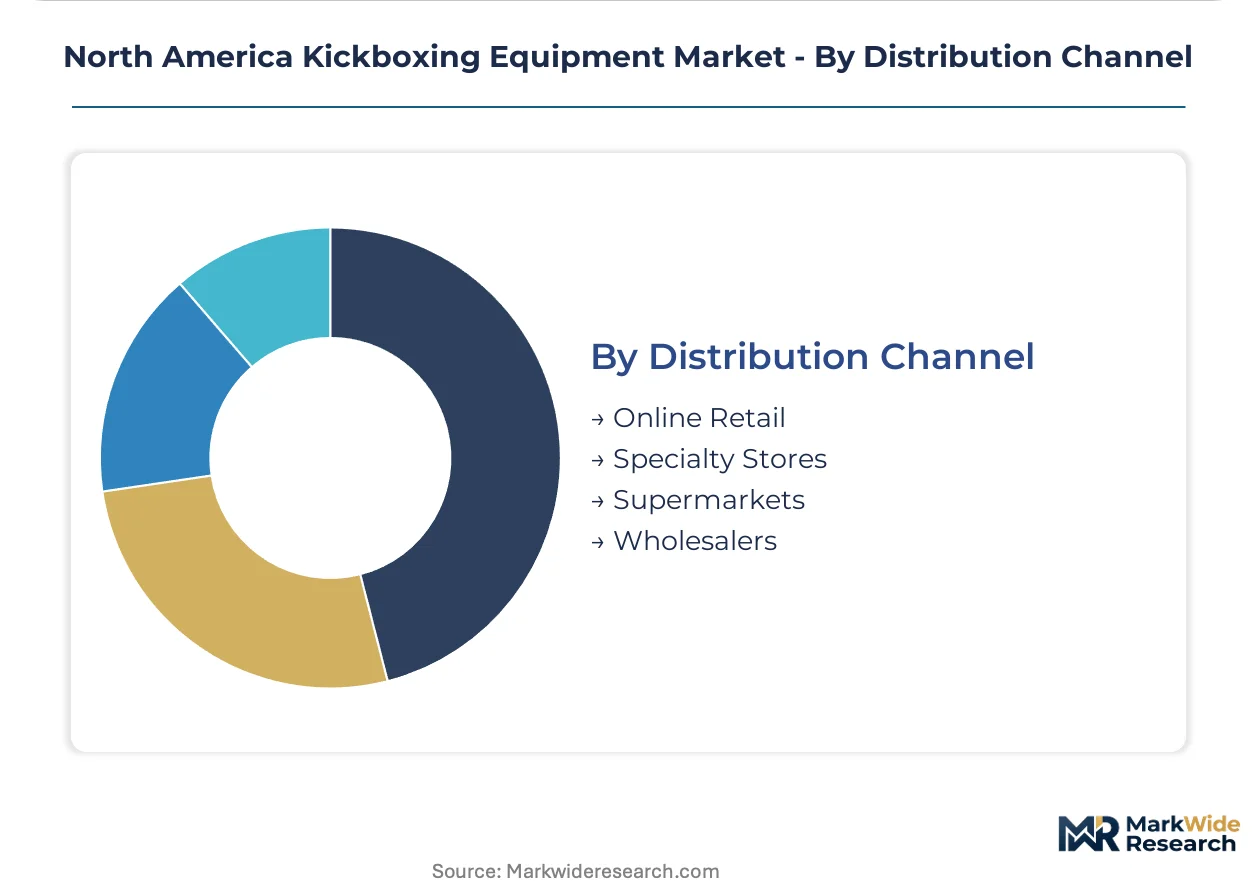
Online Retail expands most quickly; Wholesalers retain institutional contract anchoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's boutique kickboxing studio corridor concentrates equipment procurement power through multi-location gym chains driving refresh cycles across the western United States.
United States
Fitness enthusiasts in California and Texas boutique studios accelerate equipment replacement through membership growth and chain expansion. The Consumer Product Safety Commission enforces updated impact-absorption testing protocols for protective headgear, compelling manufacturers to reformulate padding compounds. Los Angeles and Dallas-Fort Worth anchor the fastest-growing procurement clusters where dedicated kickboxing gym chains consolidate vendor relationships.
Canada
Amateur practitioners in Toronto and Vancouver elevate headguard and shin-guard specifications as concussion awareness spreads through fitness communities. Health Canada mandates flammability labeling on foam-based training equipment under the Canada Consumer Product Safety Act. Montreal's combat-sports retail network sustains specialty store relevance through tactile fitting services for professional athlete segments.
Mexico
Manufacturing operations in northern border states supply synthetic microfiber and polyurethane blending capacity serving North American mid-tier product lines. Mexican environmental regulators monitor industrial emissions from foam lamination facilities under SEMARNAT protocols. Tijuana and Monterrey industrial parks host captive production for brands seeking vertical control over raw material costs.
North America Kickboxing Equipment Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure supply chains around polyurethane blending facilities to capture synthetic material economics. The vendor base stratifies across three tiers: heritage boxing brands with wholesale gym contracts, direct-to-consumer specialists deploying augmented-reality tools, and Asian manufacturing specialists serving private-label programs. Consolidation pressure concentrates among mid-tier synthetic lines where margin compression from petrochemical volatility favors scale. Geographic expansion into Texas and California studio corridors represents the primary vector for share capture.
Within the heritage equipment tier, Everlast Worldwide and Title Boxing exemplify wholesale-anchored positioning through exclusive gym chain relationships. Hayabusa Fightwear occupies the premium protective gear segment where proprietary foam formulations exceed baseline impact-distribution benchmarks. These three entities represent divergent strategic archetypes: vertical manufacturing control, distribution lock-in, and materials science differentiation.
| Leading Market Players |
|---|
| Everlast Worldwide |
| Adidas |
| Hayabusa Fightwear |
| Venum |
| Title Boxing |
| RDX Sports |
| Century Martial Arts |
| Twins Special |
| Ringside Boxing |
| Others |
Value Network & Pricing Analysis
California's proposed recycled-content minimums for synthetic sports equipment gate qualified supply access and premium-tier pricing power, compelling manufacturers to certify circular material streams before competing for boutique studio contracts in the western United States.
Pricing Analysis
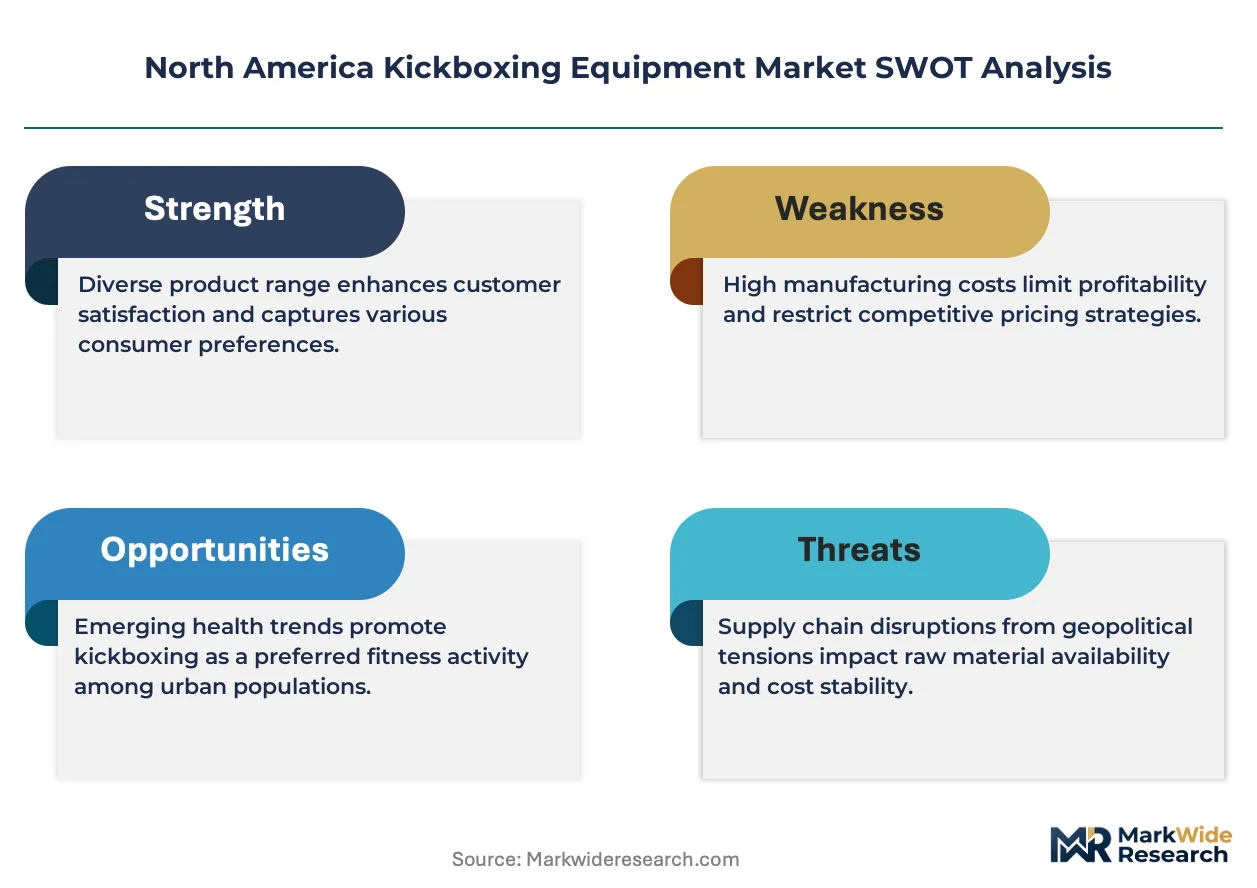
Petrochemical input pass-through from ethylene and propylene derivatives compresses margin stability on mid-tier synthetic lines, forcing manufacturers to absorb crude oil volatility or surrender share. Three-tier pricing structure across premium, standard, and economy levels separates CPSC-certified protective gear from ASTM-baseline equipment and uncertified entry-level imports. Cost compression in synthetic gloves is intensifying because polyurethane blending capacity concentrates in northern Mexico industrial parks. Fitness enthusiasts in California boutique studios exhibit highest price sensitivity, while professional athletes in Texas competitive circuits accept leather premiums for longevity performance.
Supply Chain Analysis
Polyurethane foam and synthetic microfiber supply rests on petrochemical processing capacity in Mexico, Taiwan, and South Korea, with Mexican border states anchoring captive production for brands seeking upstream control over raw material costs. Ethylene derivatives, propylene feedstocks, and multi-density foam lamination equipment constitute critical input dependencies. Single-source vulnerability runs through concentrated Deltra-EG-style proprietary foam formulation suppliers serving premium protective gear tiers. Distribution runs through exclusive wholesale contracts between incumbent distributors and major gym chains across the United States and Canada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America kickboxing equipment market functions as a stable compounder, with boutique combat-sports studio expansion driving predictable equipment refresh cycles through membership growth and multi-location strategies.
For Market Incumbents: Cement exclusive vendor relationships with California and Texas gym chains through full-equipment-package contracts spanning gloves, pads, headgear, and heavy bags under unified brand aesthetics. Invest in CPSC pre-certification for reformulated padding compounds to capture upgrade demand from existing installed bases. Direct-to-consumer specialists deploying augmented-reality fitting tools threaten wholesale-anchored positioning; defend channel control through subscription-based replacement programs.
For New Entrants and Emerging Players: Boutique studio procurement officers represent the most penetrable buyer archetype, as these operators consolidate vendor relationships around suppliers capable of delivering integrated equipment-and-digital-content bundles. White-space opportunity concentrates in AR-enabled direct-to-consumer channels where specialty retailers are losing floor traffic. Target amateur practitioners in Texas and California through Bluetooth-enabled strike-force measurement systems that compress the boundary between hardware and software-enabled coaching platforms.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier synthetic equipment specialists because margin compression from petrochemical volatility favors scale and California's recycled-content mandates will disqualify uncertified suppliers. Long-term viability extends through the projection horizon for manufacturers with verified circular material streams and CPSC-certified protective gear portfolios. Monitor state-level legislative timelines in California and New York as inflection indicators for sourcing strategy disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled-Content Certification | California's proposed mandates will disqualify uncertified synthetic suppliers from boutique studio contracts. |
| Proprietary Foam Formulation | Deltra-EG-style cores exceeding CPSC impact-thresholds command premium positioning in protective gear. |
| Augmented-Reality Fitting Deployment | AR sizing applications reduce return rates on weight-class gloves in direct-to-consumer channels. |
| Vertical Manufacturing Control | Mexico-based polyurethane blending facilities insulate margin stability from petrochemical input volatility. |
| Exclusive Gym Chain Contracts | Title Boxing-style wholesale lock-in creates barrier structures limiting emerging brand shelf access. |
Research Methodology
Direct dialogue with boutique studio owners, equipment procurement officers at gym chains, foam lamination engineers, protective gear certification specialists, and synthetic material suppliers grounded the qualitative foundation. Secondary validation drew from CPSC enforcement records, Health Canada product safety advisories, ASTM International consensus standard publications, and trade data on polyurethane and leather imports. Bottom-up and top-down triangulation cross-referenced manufacturer production capacities against end-user replacement cycle frequencies.
Bottom-up modeling built forecasts from individual segment growth trajectories across product type, material composition, end-user category, and distribution channel dimensions. Top-down validation anchored aggregate market expansion to macroeconomic indicators for combat-sports participation and fitness studio membership growth across the projection horizon. CAGRs emerged from iterative reconciliation between segment-level demand drivers and regional procurement cluster expansion patterns in California and Texas.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to state-level recycled-content mandate implementation timelines and petrochemical price volatility. Forecasts reflect assumptions about CPSC enforcement consistency and boutique studio chain expansion durability. Material deviation in California legislative passage or crude oil derivative pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Global Spikeball Equipment Market
Sports Equipment
Global Rock Climbing Equipment Market
Sports Equipment
Speed Hurdle Market
Sports Equipment
Winter Sports Equipment Market
Sports Equipment
Athletic Mask Market
Sports Equipment
Bicycle Drivetrain Cassette Market
Sports Equipment
Europe Stand-Up Paddleboard Market
Sports Equipment
Sports and Athletic Insoles Market
Sports Equipment
Golf Equipment Market
Sports Equipment
Boxing Gloves Market
Sports Equipment
Global Skateboard Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Badminton Equipment and Products Market
Sports Equipment
Sports Equipment Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
BMX Bikes Market